
 Shaper & Shaping Machine Market | 2026-2036
Shaper & Shaping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Shaper & Shaping Machine Market Insights
REACH compliance is recalibrating material specifications for European-built shaping equipment, forcing suppliers to eliminate restricted substances in hydraulic fluids and surface coatings. SCM Group leverages captive foundry capacity to control casting quality for its heavy-duty horizontal shapers. Weinig sustains dominance in woodworking-specialized shapers through precision spindle technology developed at its German headquarters. Bosch competes across electric drive architectures, integrating servo motors that reduce energy draw versus conventional mechanical systems.
A shaper and shaping machine is a reciprocating machine tool that drives a single-point cutting tool in a linear stroke to plane flat, angular, or contoured surfaces, with typical ram stroke lengths ranging from 200 mm to 900 mm and cutting speeds adjustable between 5 and 60 meters per minute. Its primary industrial purpose is roughing and finishing of internal and external profiles in tool rooms, die shops, and low-to-medium volume production lines where milling economics prove unfavorable. CNC shaping machines command premium positioning due to programmable stroke optimization and reduced setup times for complex contours. Metal shaping applications anchor volume demand from automotive transmission component and aerospace structural fitting producers. Mechanical technology segments retain cost advantages in emerging-market tool rooms, though electric architectures are displacing pneumatic systems in precision-oriented installations.
EMA's machinery safety directives and the EU Green Deal's embodied carbon requirements shape product design rules for equipment sold across Europe. China's MIIT enforces GB standards on machine tool energy efficiency that filter through supply chains to component vendors. OSHA lockout/tagout regulations in the United States mandate guarding retrofits that extend equipment replacement cycles. Stakeholders must weigh whether to prioritize electric platform development or defend mechanical system margins as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Electric servo architectures are displacing mechanical drive systems across precision-oriented installations, driven by China's GB energy efficiency standards and tightening embodied carbon rules in European markets. This technological transition concentrates investment cycles in industrial clusters where regulatory thresholds and export demand intersect.
Growth Catalysts
- Automotive transmission manufacturing:OEMs pursuing tighter tolerances for gear housings and synchronizer hubs are expanding roughing and finishing capacity in dedicated tool rooms. Metal shaping applications anchor this demand pull.
- REACH compliance recalibration:ECHA-mandated elimination of restricted substances in hydraulic fluids and surface coatings is accelerating equipment replacement cycles among European die shops and maintenance facilities.
- Aerospace structural fitting production:Low-to-medium volume runs of titanium and aluminum airframe components favor shaper economics over milling centers for complex internal profiles.
Market Restraints
- Casting supply concentration:Heavy-duty horizontal shapers depend on captive or regional foundry capacity for bed and column castings, with quality control bottlenecks in emerging-market supply chains.
- CNC premium compression:Programmable stroke optimization and reduced setup times command price premiums that exclude cost-sensitive tool rooms in price-driven procurement environments.
- Milling substitution threat:Five-axis machining centers with adaptive toolpaths encroach on traditional shaper applications in higher-volume production lines.
Strategic Opportunities
- Woodworking spindle specialization:Precision spindle technology developed for furniture and joinery applications opens adjacent revenue streams beyond metalworking core markets.
- Electric platform retrofit kits:Servo motor conversion packages for installed mechanical bases address sustainability mandates without full equipment replacement.
- Baden-Württemberg precision engineering exports:Germany's industrial cluster sustains tooling investment cycles that favor premium equipment specifications for re-export markets.
Industry Challenges
- Setup technician skill compression:Complex contour programming for CNC shapers requires specialized training that outpaces vocational pipeline output in multiple manufacturing regions.
- OSHA lockout/tagout retrofit complexity:Guarding modifications to extend equipment replacement cycles demand engineering resources that strain maintenance department capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaper & Shaping Machine Market |
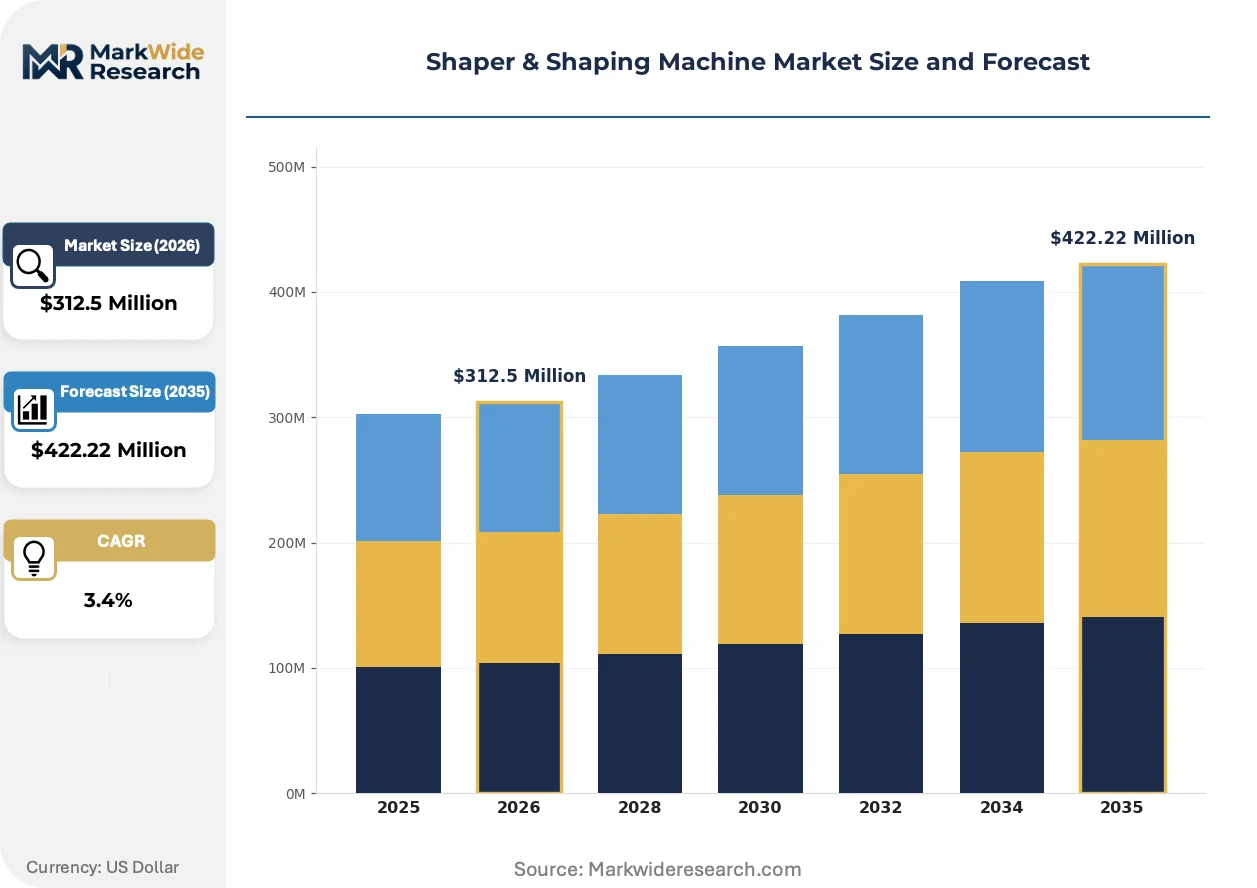
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $422.22 Million |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Shapers, Vertical Shapers, CNC Shaping Machines, Specialty Shapers Technology: Mechanical, Hydraulic, Pneumatic, Electric End User: Manufacturing, Automotive, Aerospace, Construction Application: Metal Shaping, Woodworking, Tool Making, Mold Production |
| Companies Covered | SCM Group, Weinig, Baileigh Industrial, Delta, Ryobi, Porter Cable, Bosch, Woodmaster, DMG MORI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaper & Shaping Machine Market Trends and Innovations
Reciprocating machine tool architecture is undergoing selective digitization as regulatory pressure and energy accounting reshape buyer specifications. Three developmental vectors dominate current product evolution.
Servo-electric ram drive systems are integrating closed-loop position feedback and regenerative braking to cut energy draw versus conventional mechanical clutches and brakes. Automotive component manufacturers in export-oriented supply chains are adopting these architectures fastest. The technology is integrating programmable stroke optimization that compresses setup times for batch-of-one production runs.
China's MIIT enforces GB standards on machine tool energy efficiency that filter through supply chains to component vendors. Domestic manufacturers must certify equipment against these thresholds to access state procurement channels and preferential financing. Electric architectures are displacing pneumatic systems fastest in precision-oriented installations serving aerospace and medical device supply chains.
Buyers are unbundling after-sales service contracts from equipment purchases, selecting third-party maintenance providers or developing in-house capability. This procurement pattern disrupts traditional OEM service revenue models. The shift is most visible in Germany's industrial cluster, where precision engineering firms prioritize uptime guarantees over manufacturer-branded service agreements.
Shaper & Shaping Machine Market Segmentation
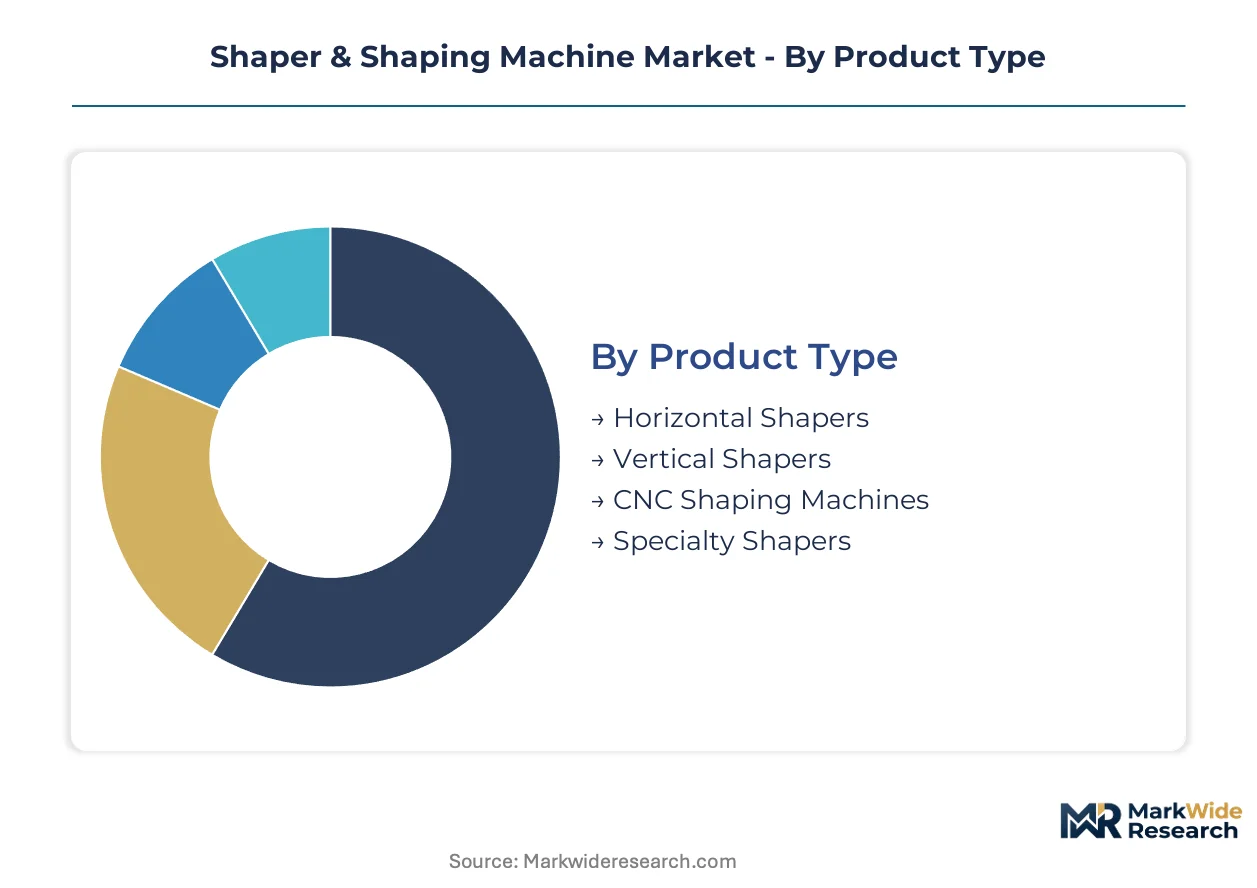
Segmentation in the Shaper & Shaping Machine Market reveals how equipment specifications align with distinct operational environments. Buyers select architectures based on integration depth with existing production lines, energy accounting requirements, and regulatory thresholds in their operating geographies.
Product Type:
Standalone horizontal and vertical shapers dominate tool room installations, while CNC and specialty variants embed into automated production cells.
- Horizontal Shapers:Reciprocating ram drives cutting tools across horizontally oriented worktables, with stroke lengths from 200 mm to 900 mm. Foundry-dependent bed castings concentrate production in Germany's Baden-Württemberg cluster, where precision engineering exports sustain tooling investment cycles despite REACH compliance recalibration costs.
- CNC Shaping Machines:Programmable stroke optimization and closed-loop position feedback enable batch-of-one production for complex contours. Automotive transmission manufacturers in export-oriented supply chains adopt these fastest, though premium pricing excludes cost-sensitive tool rooms in emerging markets.
- Vertical Shapers:Ram stroke operates perpendicular to the worktable, suited for internal keyway cutting and spline machining in dedicated die shops.
- Specialty Shapers:Configured for gear tooth generation, rack cutting, or curved surface generation in aerospace structural fitting production.
Horizontal shapers lead volumes today; CNC shaping machines are gaining share fastest.
Technology:
Cost tiers separate legacy mechanical systems from emerging electric architectures that command sustainability premiums.
- Electric:Servo motor drives with regenerative braking cut energy draw versus mechanical clutches. China's MIIT enforces GB standards that filter through supply chains to component vendors, accelerating displacement of pneumatic systems in precision-oriented installations.
- Mechanical:Crank and slotted link mechanisms deliver cost advantages in emerging-market tool rooms where capital constraints dominate procurement decisions.
- Hydraulic:High-force ram actuation for heavy-duty roughing operations, though REACH-mandated fluid restrictions are accelerating replacement cycles in European die shops.
- Pneumatic:Compressed air drives retain niche positioning in woodworking applications where spark hazards prohibit electric alternatives.
Mechanical systems anchor installed base volumes; electric architectures are expanding most quickly.
End User:
Application maturity varies by sector, with automotive and aerospace demanding precision tolerances that reshape equipment specifications.
- Automotive:OEMs pursue tighter tolerances for gear housings and synchronizer hubs, expanding roughing and finishing capacity in dedicated tool rooms. Metal shaping applications anchor this demand concentration.
- Aerospace:Low-to-medium volume runs of titanium and aluminum airframe components favor shaper economics over milling centers for complex internal profiles.
- Manufacturing:General job shops and maintenance facilities balance equipment versatility against capital recovery timelines.
- Construction:Heavy equipment component repair and structural steel preparation drive periodic demand spikes.
Automotive leads volume demand today; aerospace is climbing the fastest.
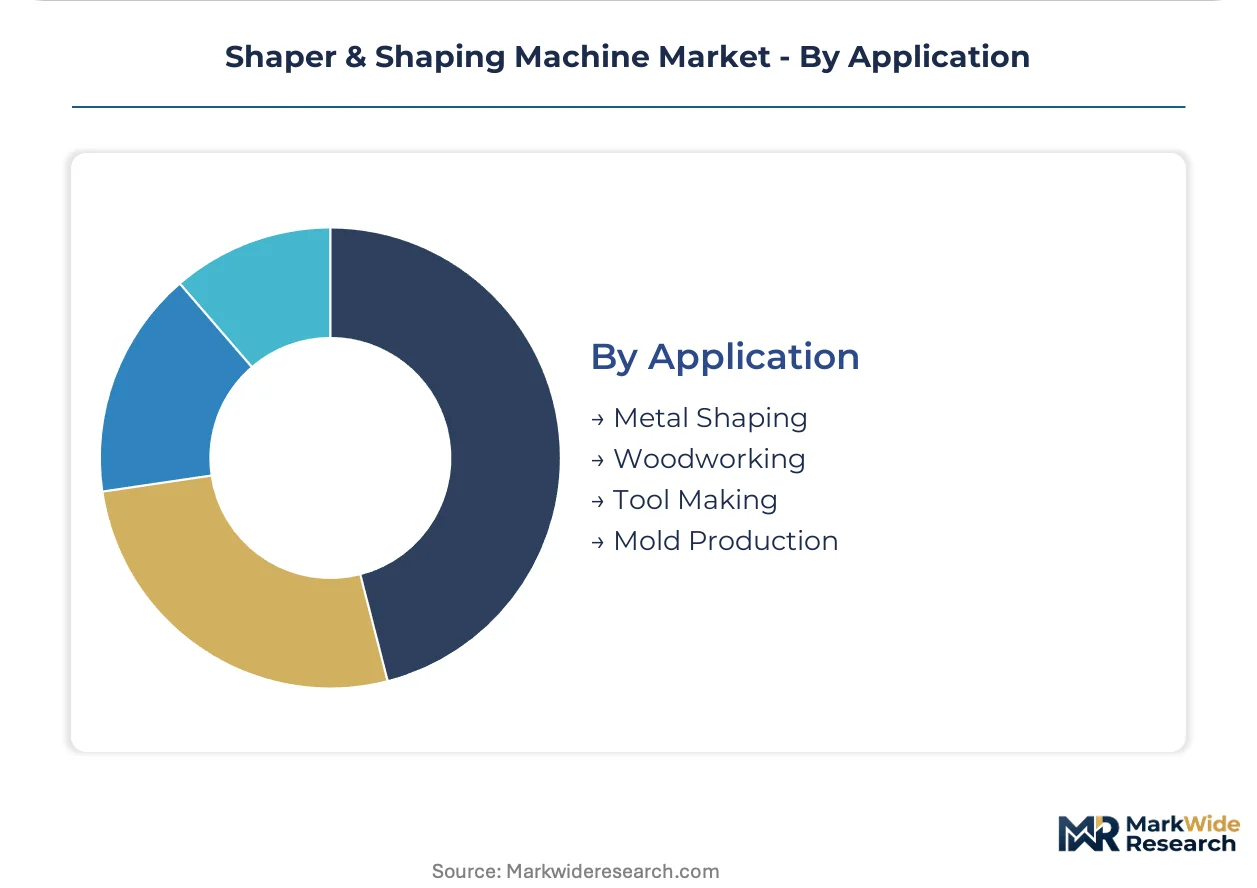
Application:
Customer type differentiation separates high-mix tool room work from dedicated production line installations.
- Metal Shaping:Single-point cutting tools plane flat, angular, or contoured surfaces in steel, aluminum, and titanium. Baden-Württemberg's industrial cluster sustains premium equipment specifications for re-export markets serving this core application.
- Woodworking:Precision spindle technology developed for furniture and joinery applications opens adjacent revenue streams, with guarding retrofits mandated by OSHA lockout/tagout regulations extending equipment replacement cycles in US facilities.
- Tool Making:Die shops and mold production facilities require specialized contour programming that outpaces vocational pipeline output in multiple manufacturing regions.
- Mold Production:Complex cavity roughing and finishing for plastic injection and die casting tooling.
Metal shaping leads volumes today; woodworking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial shaping machinery originated in European machine tool traditions during the nineteenth century, with German engineering standards subsequently diffusing through export markets. Contemporary demand clusters in manufacturing centers where precision tolerances intersect with regulatory pressure on energy efficiency.
Germany
Baden-Württemberg's precision engineering cluster sustains premium equipment specifications for automotive transmission component producers. EMA machinery safety directives and EU Green Deal embodied carbon requirements filter through design rules for equipment sold across Europe. Stuttgart-based tooling investment cycles favor servo-electric architectures over mechanical systems.
China
State procurement channels drive domestic manufacturer certification against MIIT-enforced GB energy efficiency standards. Yangtze River Delta machine tool producers supply automotive OEMs pursuing tighter tolerances for gear housings. Shanghai and Jiangsu province industrial parks concentrate electric servo technology adoption fastest.
United States
OSHA lockout/tagout regulations mandate guarding retrofits that extend equipment replacement cycles in maintenance facilities. Midwest tool rooms and die shops anchor mechanical system demand where capital constraints dominate procurement. Michigan and Ohio automotive supplier networks favor roughing capacity for transmission components.
Japan
METI industrial policy supports precision spindle technology development for aerospace structural fitting applications. Nagoya and Osaka manufacturing belts concentrate low-to-medium volume titanium and aluminum airframe component production. JIS standards alignment enables re-export positioning across Asia-Pacific supply chains.
India
Bureau of Indian Standards certification requirements shape import specifications for metal shaping equipment in tool rooms. Maharashtra and Gujarat industrial corridors expand roughing and finishing capacity for domestic automotive component manufacturing. PLI scheme incentives for advanced manufacturing indirectly support precision machinery investment.
Shaper & Shaping Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and captive foundry capacity. The vendor base spans integrated machinery conglomerates, woodworking-specialized fabricators, and regional metalworking equipment suppliers. Three archetypes dominate: diversified industrial tool manufacturers with captive casting operations, precision spindle specialists serving furniture and joinery applications, and electric drive component suppliers integrating servo architectures. Competitive moves concentrate on electric platform development versus mechanical system margin defense, plus aftermarket service contract unbundling.
Among European-anchored industrial machinery groups, SCM Group and Weinig occupy distinct positioning archetypes. SCM Group represents the captive foundry-integrated model controlling casting quality for heavy-duty horizontal equipment. Weinig exemplifies woodworking-specialized precision through spindle technology development. Bosch anchors the electric drive architecture vector, integrating servo motors that reduce energy draw. These three illustrate how technology specialization and vertical integration depth separate margin tiers.
| Leading Market Players |
|---|
| SCM Group |
| Weinig |
| Baileigh Industrial |
| Delta |
| Ryobi |
| Porter Cable |
| Bosch |
| Woodmaster |
| DMG MORI |
| Others |
Pricing and Supply Chain Analysis
Cast iron bed castings from Baden-Württemberg foundries flow through three distinct pricing tiers as they reach automotive tool rooms, aerospace die shops, and emerging-market maintenance facilities. China's MIIT-enforced GB energy efficiency standards compress margins on mechanical systems while electric servo architectures capture sustainability premiums upstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CNC shaping machines with programmable stroke optimization from conventional horizontal units and refurbished mechanical systems. Price differentiation hinges on certification grade against EU machinery safety directives and after-sales service bundling. Pricing pressure stems from REACH-mandated hydraulic fluid substitutions that accelerate replacement cycles in European die shops. Cost-sensitive tool rooms in emerging markets exhibit highest price sensitivity, while aerospace structural fitting producers prioritize precision tolerances over capital expenditure.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Nagoya orchestrate hub-and-spoke patterns for precision spindle components and servo motor assemblies. Manufacturing concentrates in Germany, China, and Japan, with foundry-dependent bed castings anchoring production in captive facilities. Supply chains draw from gray iron foundries, hardened steel guide ways, and rare-earth servo motor magnets. Single-source vulnerability persists in precision spindle bearings sourced from Japanese specialists. Distribution runs through OEM-direct channels for premium CNC systems and third-party distributors for mechanical tool room equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's GB energy efficiency standards and EU Green Deal embodied carbon requirements force simultaneous technology transitions across multiple jurisdictions.
For Market Incumbents: Extend captive foundry integration into electric platform casting specifications to defend margin position against servo motor suppliers entering downstream assembly. Consolidate service contract unbundling by offering uptime guarantees that third-party maintenance providers cannot match. Milling substitution threats from five-axis machining centers demand accelerated CNC stroke optimization development. For New Entrants and Emerging Players: REACH compliance recalibration in Europe opens a window for electric retrofit kit specialists to bypass capital-intensive foundry investments. Target woodworking spindle applications where precision tolerances lag metalworking sophistication and OSHA guarding retrofits extend replacement cycles. Pursue direct sales to Baden-Württemberg precision engineering exporters seeking re-export market certification. For Investors and Strategic Acquirers: Consolidation pressure builds where captive foundry capacity intersects with electric architecture development costs that strain mid-tier balance sheets. Long-term viability favors vertically integrated specialists controlling casting quality through servo motor integration rather than pure-play assemblers. Watch for MIIT certification delays that strand mechanical inventory in Chinese state procurement channels as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Retrofit Development | Servo motor conversion packages address China's GB standards without full equipment replacement. |
| Captive Foundry Capacity Expansion | SCM Group's casting quality control for heavy-duty horizontal shapers defends premium positioning. |
| Precision Spindle Technology Licensing | Weinig's woodworking expertise transfers to aerospace structural fitting contour applications. |
| Aftermarket Service Contract Unbundling | Third-party maintenance disruption in Germany's industrial cluster forces uptime guarantee innovation. |
| REACH-Compliant Hydraulic System Redesign | ECHA-mandated fluid elimination accelerates equipment replacement cycles across European die shops. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market gathered through structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation draws from MIIT certification databases, EU machinery safety directive filings, OSHA enforcement records, and customs trade data for machine tool imports. Bottom-up equipment shipment tracking triangulates against top-down industrial capacity utilization estimates.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window, with segmentation modeling across product type, technology architecture, end-use sector, and application. CAGRs derive from regression analysis against automotive transmission production forecasts, aerospace airframe build rates, and woodworking industry capital expenditure surveys. Energy efficiency regulatory threshold timing and vocational training pipeline output feed scenario-weighted projections.
Revisions become necessary when MIIT enforcement intensity shifts, REACH substance restriction lists expand, or milling center economics cross below shaper threshold costs for complex internal profiles. Forecasts reflect documented assumptions on regulatory implementation schedules and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
CNC Polishing Machines Market