
 Benelux Metal Fabrication Equipment Market | 2026-2036
Benelux Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Benelux Metal Fabrication Equipment Market Outlook
A shift from single-source to multi-source equipment procurement is rebalancing capital deployment across Benelux metalworking facilities. TRUMPF leverages its integrated software-hardware ecosystem to dominate high-power laser cutting installations in Dutch shipyards. Amada sustains competitive pressure through dense service networks and rapid spare parts availability across Belgian automotive suppliers. Yamazaki Mazak Corporation specializes in five-axis CNC machining centers that serve precision aerospace subcontractors near Brussels and Rotterdam.
Benelux metal fabrication equipment encompasses machinery for cutting, bending, welding, and forming metallic workpieces, typically handling steel plate thicknesses from 0.5 mm to 50 mm and operating at laser power ratings up to 20 kW for industrial throughput. Its primary purpose is transforming raw sheet and plate stock into dimensionally precise components for assembled products. Laser Cutters command the largest installed base among equipment types, though Additive Manufacturing within the technology dimension is expanding fastest as Dutch medical device and Belgian tooling producers validate metal 3D printing for end-use parts. CNC Machining retains the deepest margin pool due to aftermarket tooling, software subscriptions, and retrofit services that extend machine economic life beyond fifteen years.
The EU Green Deal's carbon border adjustment mechanism and REACH chemical compliance requirements are elevating demand for energy-efficient electric press brakes and fiber laser systems that eliminate hydraulic oil and reduce power consumption per processed ton. CE marking under the EU Machinery Directive governs market access, while Belgium's regional environmental agencies and the Dutch Rijksdienst voor Ondernemend Nederland enforce supplemental emissions and workplace safety standards. Stakeholders must monitor how forthcoming EU AI Act provisions classify autonomous quality inspection and predictive maintenance modules integrated into fabrication equipment.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is compressing payback periods for energy-efficient fiber laser and electric press brake investments across Belgian and Dutch fabrication facilities. Automotive OEMs in the Eindhoven-Antwerp corridor are reconfiguring capital allocation toward in-house EV component production, shortening supplier tiers and reshaping equipment procurement volumes.
Growth Catalysts
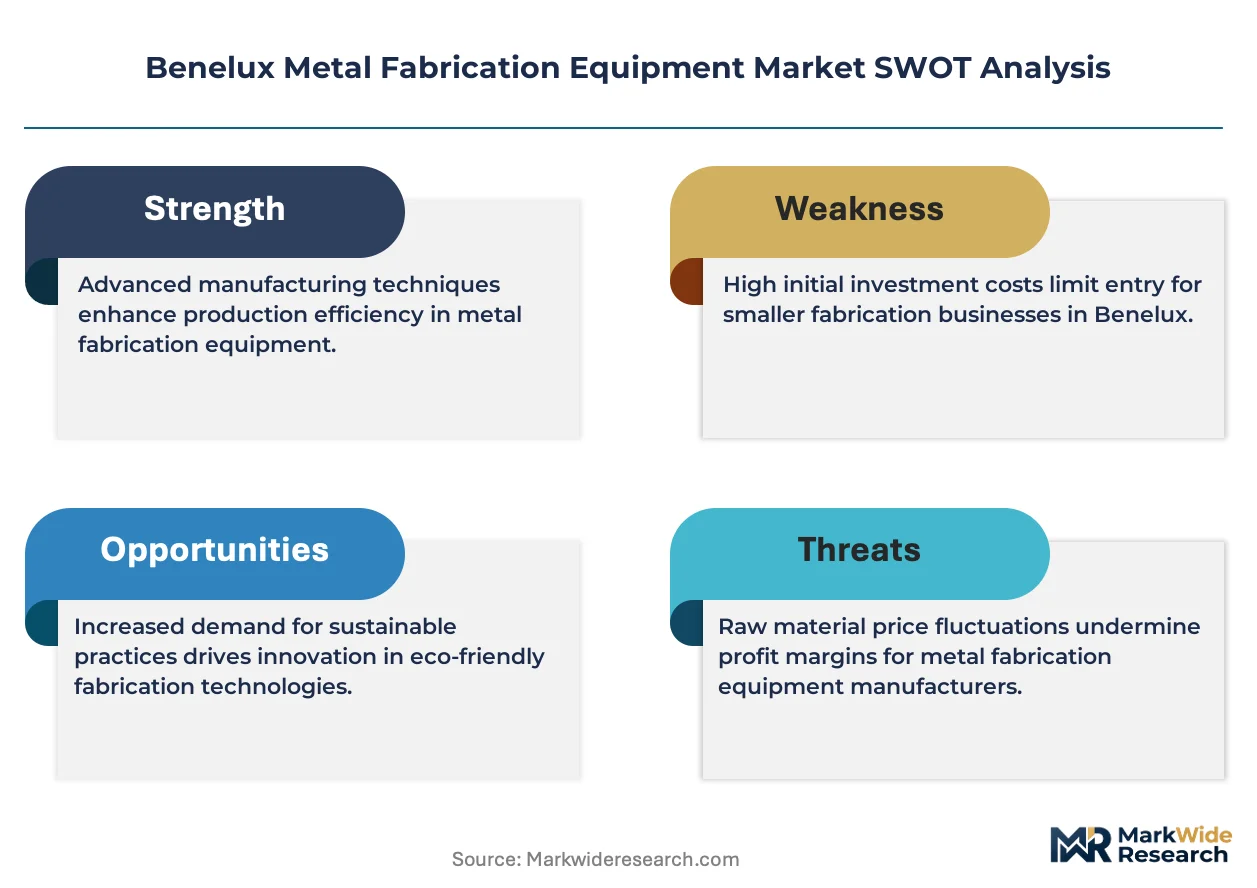
- EU Green Deal carbon border adjustments:Belgian and Dutch fabricators face escalating carbon costs on imported steel, accelerating replacement of hydraulic press brakes with all-electric servo-electric models that eliminate oil consumption and cut energy per ton processed.
- EV battery enclosure fabrication:Netherlands-based automotive OEMs are expanding laser welding and CNC machining capacity for aluminum battery trays, pulling high-power fiber laser systems into Dutch industrial parks.
- Semiconductor equipment supply chain:Precision metal housings and vacuum chambers for lithography systems cluster around Leuven and Eindhoven, sustaining demand for five-axis CNC machining centers with micron-level repeatability.
Market Restraints
- Steel price volatility:Input cost swings for hot-rolled coil and specialty alloys compress fabrication margins, delaying equipment upgrade cycles at mid-tier Belgian job shops serving construction and agricultural machinery.
- High-voltage laser source concentration:Fiber laser resonator and cutting head supply concentrates among German and Japanese specialists, exposing Dutch shipyards and Belgian automotive suppliers to lead time risk and currency fluctuation.
- Skilled CNC programmer scarcity:Technical vocational pipelines in Belgium's Flemish Region and the Netherlands fail to match retirement rates, constraining utilization rates at installed machining centers regardless of equipment capability.
Strategic Opportunities
- Walloon Region industrial renewal:Belgium's southern province maintains underpenetrated laser cutting density versus Flanders, presenting first-mover positioning for equipment vendors targeting Liege-area aerospace subcontractors.
- Metal additive manufacturing validation:Dutch medical implant producers and Belgian tooling houses are qualifying selective laser melting for end-use production, opening equipment sales beyond prototyping into production-scale powder bed systems.
- EU AI Act predictive maintenance modules:Autonomous quality inspection and machine learning-driven downtime prevention integrated into press brakes and laser systems will face classification requirements, creating compliance service revenue streams for vendors with embedded software ecosystems.
Industry Challenges
- CE marking timeline compression:The EU Machinery Directive's conformity assessment procedures for software-integrated fabrication equipment extend delivery schedules, frustrating just-in-time capital deployment at Dutch automotive tier-one suppliers.
- Legacy hydraulic system interoperability:Belgian job shops with amortized hydraulic press brake fleets face integration friction when retrofitting automated material handling and nesting software, delaying full workflow digitization.
- REACH chemical compliance for cutting fluids:Substitution of mineral oil-based coolants with bio-alternatives for machining operations requires process requalification, consuming engineering bandwidth at precision subcontractors near Brussels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benelux Metal Fabrication Equipment Market |
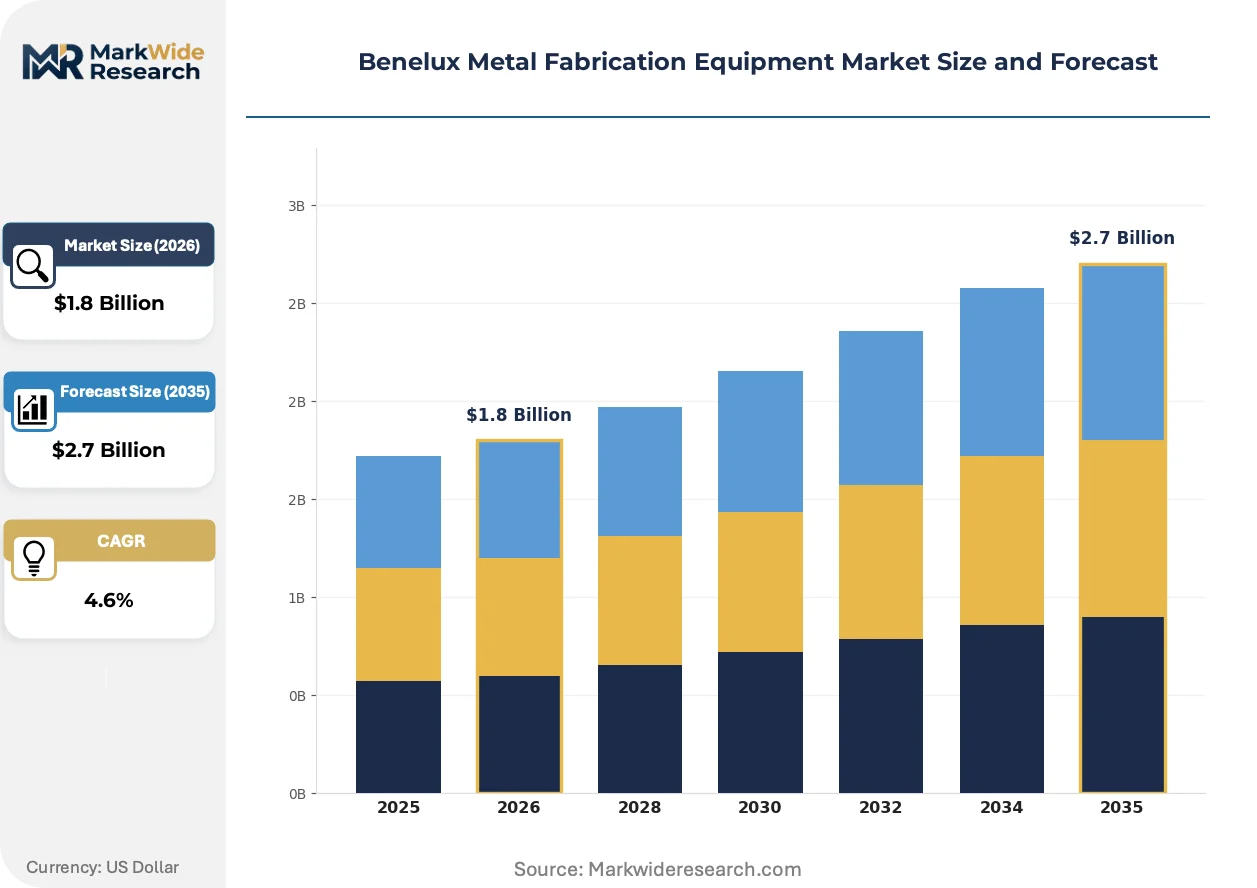
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Laser Cutters, Press Brakes, Welding Machines, Plasma Cutters End User Sector: Aerospace, Automotive, Construction, Electronics Technology: Sheet Metal Processing, CNC Machining, Additive Manufacturing, Industrial Robotics Application Area: Prototype Development, Production Line, Custom Fabrication, Maintenance Repair |
| Companies Covered | DMG Mori Aktiengesellschaft, Amada, TRUMPF, Bystronic Laser AG, Dalian Machine Tool Group Corporation, Okuma Corporation, Sandvik AB, Yamazaki Mazak Corporation, Prima Industrie, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benelux Metal Fabrication Equipment Market Strategic Shifts
Fabrication technology in Benelux is pivoting from standalone equipment sales toward integrated production cells where software orchestrates material flow, cutting parameters, and quality verification. This convergence compresses the traditional boundary between machine tool and factory automation.
Artificial intelligence-driven nesting and cut-path optimization is converging with real-time kerf monitoring in high-power fiber laser systems. Dutch shipyards serving offshore wind installation vessels are deploying these systems to maximize plate yield from high-strength steel. The technology is compressing quoting-to-delivery cycles at Antwerp-area metal service centers, enabling same-day turnaround on complex cutting jobs that previously required overnight programming.
REACH chemical restrictions and the EU Green Deal's embodied carbon accounting are elevating dry cutting and minimum-quantity lubrication in CNC machining. Belgian precision subcontractors serving semiconductor equipment OEMs are requalifying processes to eliminate flood coolant, reducing chemical disposal costs and simplifying compliance documentation. The Flemish Region's environmental agencies are accelerating permit approvals for facilities demonstrating closed-loop coolant systems or dry machining adoption.
Service contract unbundling is fragmenting the traditional equipment sale model across Dutch and Belgian fabrication facilities. Buyers are separating hardware acquisition from software subscriptions, maintenance, and training, treating each as distinct procurement decisions. This pattern concentrates in the Eindhoven-Antwerp corridor where automotive and aerospace tier-one suppliers maintain dedicated reliability engineering teams capable of self-performing preventive maintenance on laser and press brake systems.
Benelux Metal Fabrication Equipment Market Segmentation
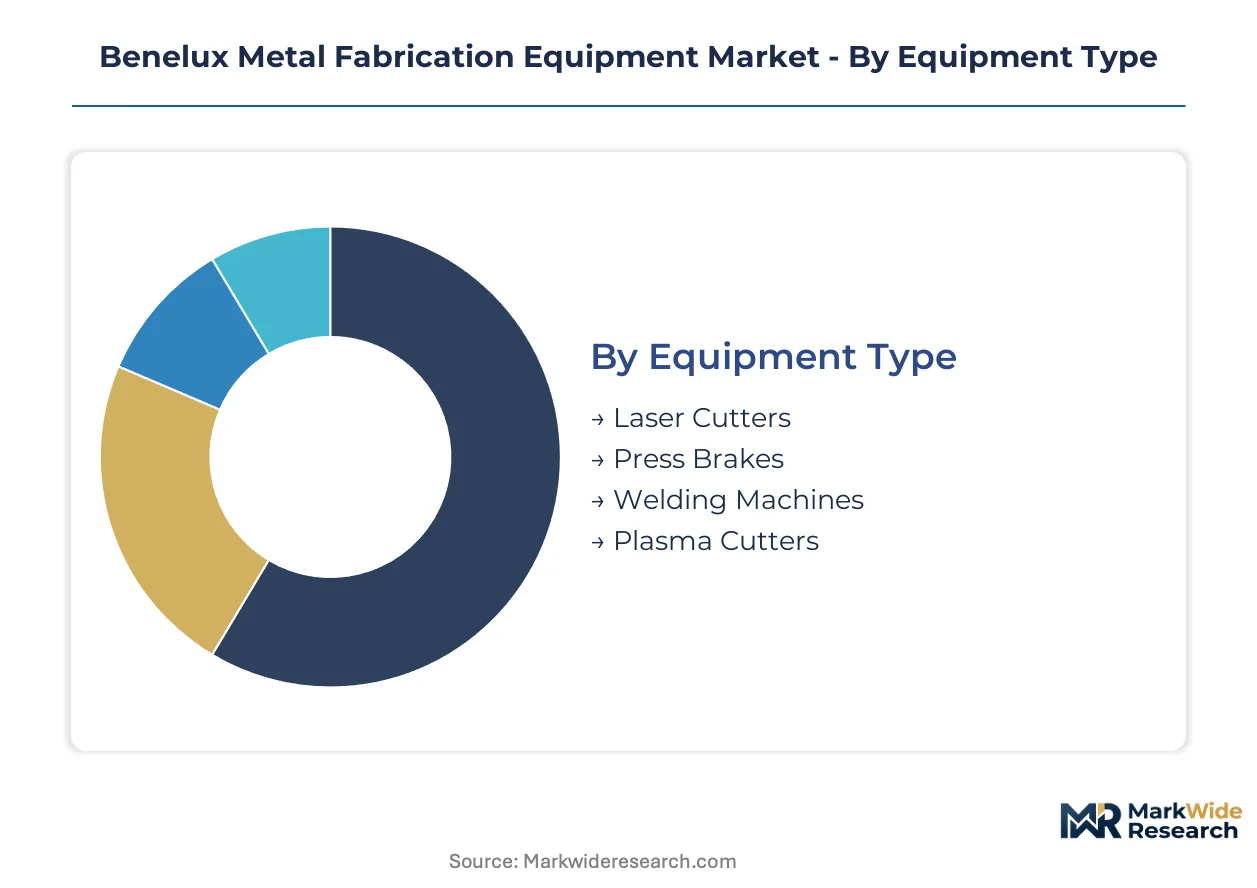
Equipment buyers in Belgium and the Netherlands segment procurement decisions by integration complexity—standalone machines versus embedded production cells—shaping vendor pricing power and aftermarket revenue pools. Understanding these divides clarifies why laser cutting commands capital allocation while additive manufacturing penetrates only validated process niches.
Equipment Type:
Standalone machines dominate job-shop floors, yet integrated cells with automated material handling capture the premium placement tier in automotive and aerospace facilities.
- Laser Cutters:Fiber laser systems with power ratings up to 20 kW process steel plate from 0.5 mm to 50 mm thickness. Dutch shipyards and Antwerp-area metal service centers concentrate demand for high-power configurations serving offshore wind and same-day cutting turnaround.
- Press Brakes:Electric servo-electric models displace hydraulic units across Belgian automotive suppliers seeking to eliminate oil consumption and cut energy per ton processed under EU Green Deal carbon border pressures.
- Welding Machines:Automated arc and laser welding systems serve EV battery enclosure fabrication in Eindhoven-area industrial parks.
- Plasma Cutters:Oxygen-fuel and high-definition plasma systems retain cost advantage for thick plate roughing at construction-focused job shops.
Volume placements concentrate in Laser Cutters; the faster expansion belongs to electric Press Brakes.
End User Sector:
Capital intensity and certification requirements separate aerospace and automotive tier-one suppliers from price-sensitive construction and electronics fabricators.
- Automotive:OEMs in the Eindhoven-Antwerp corridor reconfigure supply chains toward in-house EV component production, pulling fiber laser welding and CNC machining capacity into Dutch industrial parks.
- Aerospace:Precision subcontractors near Brussels and Rotterdam sustain demand for five-axis CNC machining centers with micron-level repeatability for structural and engine components.
- Construction:Belgian job shops serving agricultural machinery and structural steel face compressed margins from input cost volatility, delaying equipment upgrade cycles.
- Electronics:Semiconductor equipment housing fabricators cluster around Leuven and Eindhoven, requiring vacuum-tight weld quality and surface finish specifications.
Capital deployment tilts toward Automotive; Aerospace claims the deepest margin pool per machine-hour.
Technology:
Process maturity and software integration depth differentiate established subtractive methods from emerging additive and robotic platforms.
- CNC Machining:Five-axis centers with pallet automation generate aftermarket revenue through tooling, software subscriptions, and retrofit services extending economic life beyond fifteen years. Belgian precision subcontractors serving semiconductor OEMs drive dry machining adoption to simplify REACH compliance.
- Sheet Metal Processing:Nesting software and real-time kerf monitoring compress quoting-to-delivery cycles at metal service centers, with AI-driven optimization penetrating Dutch shipyards first.
- Additive Manufacturing:Selective laser melting systems qualify for end-use production at Dutch medical implant producers and Belgian tooling houses, expanding beyond prototyping into production-scale powder bed configurations.
- Industrial Robotics:Automated material handling and quality inspection modules face forthcoming EU AI Act classification requirements for predictive maintenance integration.
Installed base dominance rests with CNC Machining; Additive Manufacturing climbs the fastest as production validation accelerates.
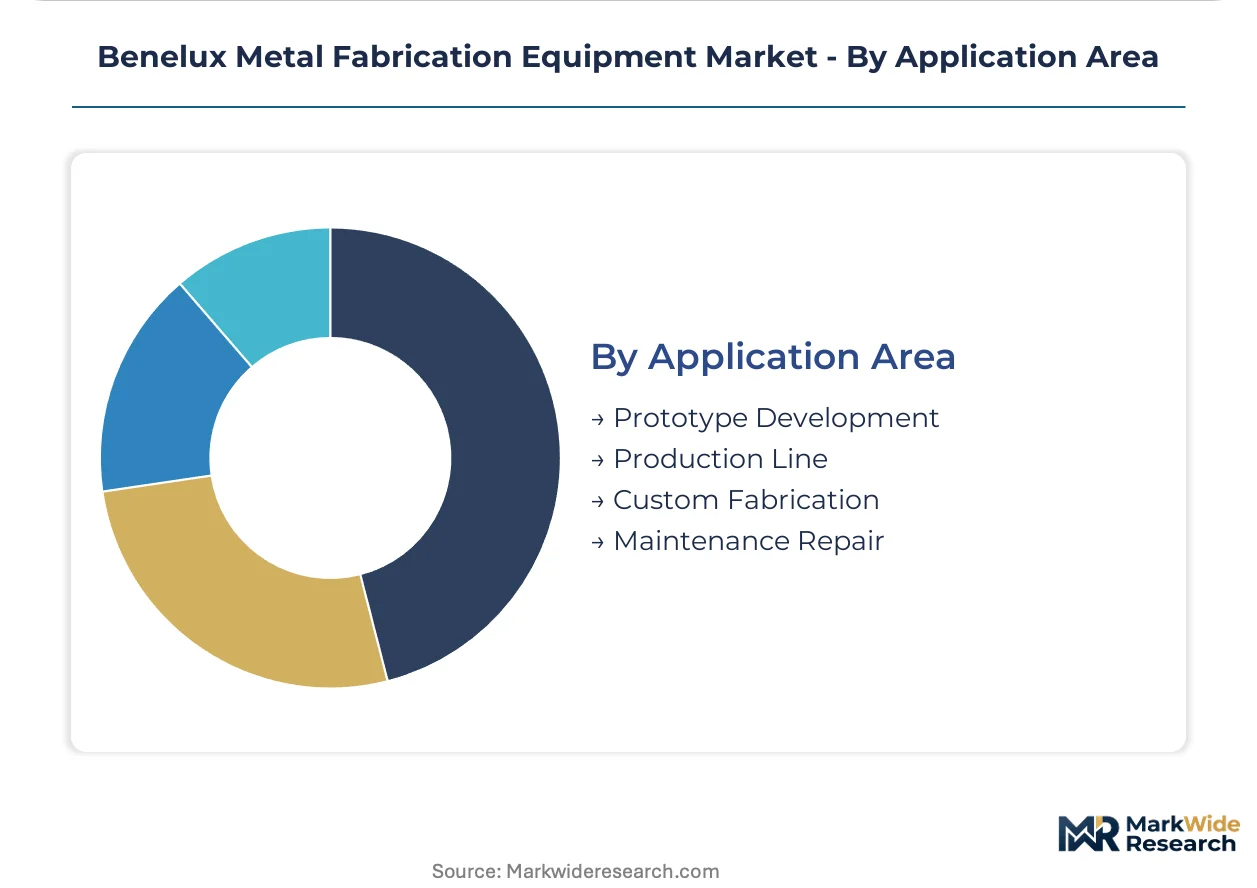
Application Area:
Volume predictability and engineering bandwidth requirements separate repetitive production line work from engineering-intensive prototype and custom fabrication.
- Production Line:High-volume repetitive cutting and forming operations in automotive battery tray fabrication favor automated cells with minimal changeover.
- Custom Fabrication:Job shops across Flanders and the Netherlands optimize for lot-size-one flexibility, prioritizing rapid programming over raw throughput.
- Prototype Development:Aerospace and medical device validation cycles demand micron-level precision and process documentation, concentrating at Leuven-area subcontractors.
- Maintenance Repair:Field service welding and portable machining operations serve offshore wind installation vessels and port infrastructure.
Equipment utilization peaks in Production Line; Custom Fabrication absorbs the widest machine capability range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel coil from the Port of Rotterdam anchors Benelux metal fabrication, with high-grade alloy imports feeding precision machining clusters across the Netherlands and Belgium. The Eindhoven-Antwerp industrial corridor concentrates demand for EV battery enclosures and semiconductor equipment housings.
Netherlands
Eindhoven-area automotive OEMs and Rotterdam shipyards drive laser cutting and CNC machining procurement. The Dutch Rijksdienst voor Ondernemend Nederland enforces emissions standards that accelerate electric press brake adoption. Philips supplier networks around Eindhoven sustain demand for micron-precision five-axis centers serving lithography equipment fabricators.
Belgium
Flemish automotive tier-one suppliers and Walloon aerospace subcontractors split equipment demand across servo-electric press brakes and precision machining centers. Belgium's regional environmental agencies administer REACH compliance inspections that push fabricators toward dry cutting processes. Leuven's semiconductor equipment housing cluster requires vacuum-tight weld quality that pulls automated laser welding systems into Flemish industrial parks.
Germany
Rhineland fabricators supply steel components across the open Benelux border, with laser cutting capacity concentrated around Düsseldorf and Cologne serving Dutch construction machinery OEMs. Germany's KBA enforces machinery safety standards that harmonize with EU Machinery Directive CE marking requirements. Aachen-area job shops specialize in thick-plate processing for Belgian agricultural equipment manufacturers.
France
Northern French metal service centers in Lille and Valenciennes compete for Benelux cutting contracts, particularly high-strength steel for Dutch offshore wind installation vessels. ANSM workplace safety inspections align with Belgian and Dutch enforcement patterns under shared EU frameworks. The Lille metropolitan area hosts French fabricators qualifying for Belgian aerospace supply chains through AS9100 certification.
Luxembourg
Steel trading and financial services dominate Luxembourg's limited fabrication footprint, with specialized job shops serving cross-border automotive logistics. The country's environmental administration applies EU Green Deal carbon accounting to imported steel inventories. Luxembourg-based steel traders coordinate just-in-time alloy deliveries to Antwerp-area metal service centers.
Benelux Metal Fabrication Equipment Market Competitive Environment
Global majors compete with regional champions across software-hardware integration and aftermarket service density. The Benelux market structures around three tiers: integrated ecosystem vendors commanding premium placement in automated cells, service-intensive specialists defending share through rapid spare parts availability, and scale-driven Asian manufacturers penetrating price-sensitive job shop segments. Consolidation pressures concentrate among mid-tier European fabricators seeking geographic coverage, while technology licensing agreements proliferate around AI-driven nesting and predictive maintenance modules.
Among German-anchored precision equipment vendors, DMG Mori Aktiengesellschaft and TRUMPF exemplify the integrated ecosystem archetype, bundling hardware with proprietary software and long-term service contracts. Japanese specialists Yamazaki Mazak Corporation occupy positions defined by five-axis machining center reliability and dense technical support networks. Amada represents the service-intensive specialist model, with rapid spare parts logistics sustaining competitive pressure across Belgian automotive supplier relationships. These three patterns—ecosystem integration, precision reliability, and service density—capture the competitive vectors shaping capital allocation decisions in Eindhoven-Antwerp corridor facilities.
| Leading Market Players |
|---|
| DMG Mori Aktiengesellschaft |
| Amada |
| TRUMPF |
| Bystronic Laser AG |
| Dalian Machine Tool Group Corporation |
| Okuma Corporation |
| Sandvik AB |
| Yamazaki Mazak Corporation |
| Prima Industrie |
| Others |
Value Chain & Pricing Dynamics
Hot-rolled coil price volatility at the Port of Rotterdam cascades through Belgian and Dutch fabrication tiers, compressing margins at construction-focused job shops while supporting premium pricing for aerospace-certified subcontractors with locked alloy supply contracts.
Pricing Analysis
Warranty and service bundling now separates premium from standard procurement tiers across the Eindhoven-Antwerp corridor. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, software integration depth, and spare parts availability commitment. Pricing pressure stems from steel input cost swings, forcing mid-tier Belgian job shops toward unbundled hardware-only purchases. Construction machinery fabricators exhibit highest price sensitivity; semiconductor equipment suppliers accept premium positioning for vacuum-tight weld certification.
Supply Chain Analysis
Skilled CNC programmer scarcity in Germany's Ruhr industrial belt and Japan's Nagoya manufacturing zone constrains resonator and cutting head output. Fiber laser source supply concentrates in Germany and Japan, with Dutch shipyards drawing from these geographies for high-power systems. Single-source vulnerability for 20 kW resonators exposes Belgian automotive suppliers to lead time risk. Distribution runs through Antwerp-area metal service centers and Rotterdam port logistics hubs serving cross-border OEM networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Benelux metal fabrication equipment operates as a supply-constrained market where fiber laser resonator bottlenecks prop pricing power for vendors with captive German or Japanese source relationships.
For Market Incumbents: Anchor service contract density in Flemish automotive tier-one accounts to defend against Asian manufacturers penetrating price-sensitive job shop segments. Expand spare parts warehousing near Rotterdam port to compress lead times below unbundled competitors. Prioritize CE marking pre-certification for AI-driven predictive maintenance modules ahead of EU AI Act enforcement timelines. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Belgium and the Netherlands open a window for electric press brake specialists targeting hydraulic fleet replacement cycles. Target Walloon Region aerospace subcontractors with five-axis machining center lease-to-own structures absent incumbent service networks. Lead with dry machining process qualification support to simplify REACH compliance for precision subcontractors near Brussels. For Investors and Strategic Acquirers: The window for entry favors software-integrated ecosystem vendors with embedded AI nesting and predictive maintenance capabilities. Long-term viability rests on capturing automotive EV battery enclosure fabrication contracts before platform standardization locks in supplier relationships. Watch for EU AI Act classification rulings on autonomous quality inspection as inflection signal for compliance service revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Resonator Supply | Captive sourcing from German or Japanese specialists insulates against lead time volatility for Dutch shipyard contracts. |
| EU AI Act Compliance Pre-Certification | Early CE marking for predictive maintenance modules captures automotive tier-one upgrade cycles ahead of regulatory deadlines. |
| Walloon Region Sales Network Expansion | First-mover positioning in Liege-area aerospace subcontractors exploits underpenetrated laser cutting density versus Flanders. |
| Metal Additive Manufacturing Production Validation | Qualifying selective laser melting for end-use medical implants opens equipment sales beyond prototyping at Dutch producers. |
| Dry Machining Process Requalification Services | REACH-compliant coolant elimination packages capture Belgian precision subcontractors facing Flemish environmental agency inspections. |
Study Parameters
Independent corroboration across plant engineers at Belgian automotive tier-one suppliers, procurement leads at Dutch shipyards, aftermarket service heads at German equipment vendors, and Flemish environmental agency inspectors underwrites the qualitative findings. Secondary validation drew from EU Machinery Directive CE marking databases, REACH compliance filings with ECHA, customs records for laser resonator imports through Rotterdam, and SEC 10-K disclosures of listed precision equipment manufacturers. Bottom-up equipment placement tallies triangulate against top-down market size estimates from trade association shipment reports.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift effects and pricing trajectory. Segmentation dimensions modeled include equipment type, end user sector, technology maturity tier, and application area complexity. CAGRs derive from installed base replacement cycles, capacity expansion announcements, and regulatory compliance-driven upgrade timelines. Industry-specific forecast inputs incorporate EU Green Deal carbon border adjustment implementation pace and EV battery enclosure fabrication capacity buildout in Eindhoven-area industrial parks.
The model assumes a particular technology adoption path; alternative pathways for fiber laser power scaling or electric press brake servo architecture would alter the outlook. Forecasts reflect assumptions regarding semiconductor equipment housing demand sustainability and REACH chemical restriction enforcement intensity. Material deviation in steel price volatility, resonator supply lead times, or EU AI Act classification rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market