
 Rotary Breaker Market | 2026-2036
Rotary Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Breaker Market Analytics
Electrification of mining equipment is reshaping rotary breaker design priorities, with manufacturers integrating variable frequency drives and energy recovery systems into traditional mechanical platforms. Caterpillar Inc. leverages its global dealer network to sustain aftermarket parts revenue across coal-producing regions. Komatsu Ltd. anchors its position through in-house production of breaker drums and replaceable wear components. McLanahan Corporation differentiates via specialized double roll configurations for high-moisture coal applications.
A rotary breaker is a cylindrical tumbling mechanism that uses lifting shelves to raise raw material and drop it against perforated screen plates, separating friable coal from harder rock and refuse based on differential breakage rates; drum diameters typically range from 24 to 96 inches with throughput capacities from 100 to over 2,000 tons per hour. Coal cleaning applications dominate installed base volumes due to regulatory pressure on sulfur content and ash reduction at preparation plants. Mining operations represent the most concentrated end user segment, with procurement patterns favoring direct sales channels for large capital equipment and distributor networks for consumable parts. Double roll breakers command premium positioning where operators require precise size control for downstream washing circuits.
EPA coal combustion residuals rules and MSHA dust exposure limits shape equipment specifications, with manufacturers engineering enclosed breaker housings and integrated dust suppression to satisfy compliance thresholds. ISO 21873 mobile crusher safety standards and IEC motor efficiency classifications further constrain design choices for international shipments. Stakeholders must monitor electrification cost curves against diesel retrofit economics as energy transition policies reshape mine site power infrastructure decisions.
Market Dynamics
Electrification mandates and EPA emissions enforcement are compressing the operational economics of diesel-powered rotary breakers, forcing capital allocation toward grid-connected or battery-electric crushing systems at coal preparation facilities.
Growth Catalysts
- EPA Coal Combustion Residuals Rules:Operators in Appalachian basins must upgrade to enclosed breaker housings with integrated dust suppression, triggering replacement cycles at aging preparation plants.
- Variable Frequency Drive Integration:Mining engineers specify VFD-equipped breakers to cut energy consumption during partial-load operations at Powder River Basin surface mines.
- High-Moisture Coal Processing:Double roll configurations capture demand from Illinois Basin operators handling wet feedstock that jams conventional single-drum designs.
Market Restraints
- Steel Input Volatility:Breaker drum fabrication depends on abrasion-resistant alloy plate pricing, exposing manufacturers to scrap metal commodity swings.
- Supply Concentration in Foundry Capacity:Domestic casting capacity for 96-inch breaker drums concentrates in Pennsylvania and Ohio, creating single-source vulnerability for large-diameter orders.
- Substitution by Sizers:Mineral sizers from MMD and FLSmidth capture size-reduction applications requiring precise product control, eroding rotary breaker share in metallurgical coal circuits.
Strategic Opportunities
- India Thermal Coal Expansion:CEA mandates for coal beneficiation at power plants create first-time demand for imported breaker systems in Jharkhand and Odisha.
- Copper Byproduct Recovery:Chilean porphyry operations deploy rotary breakers for ore pre-concentration, opening non-coal revenue streams for drum manufacturers.
- IRA Clean Energy Tax Credits:Mine electrification grants under the Inflation Reduction Act subsidize grid-connection infrastructure for electric breaker installations.
Industry Challenges
- Automation Engineering Shortage:PLC programming for VFD-integrated breakers outpaces available talent in West Virginia and Kentucky mining communities.
- MSHA Compliance Timelines:Dust exposure limit revisions force 18-month certification cycles for modified breaker enclosures, delaying field deployment.
- Legacy Mechanical Integration:Electric drive retrofits must interface with 1970s-era support structures at Appalachian preparation plants, complicating installation scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Breaker Market |
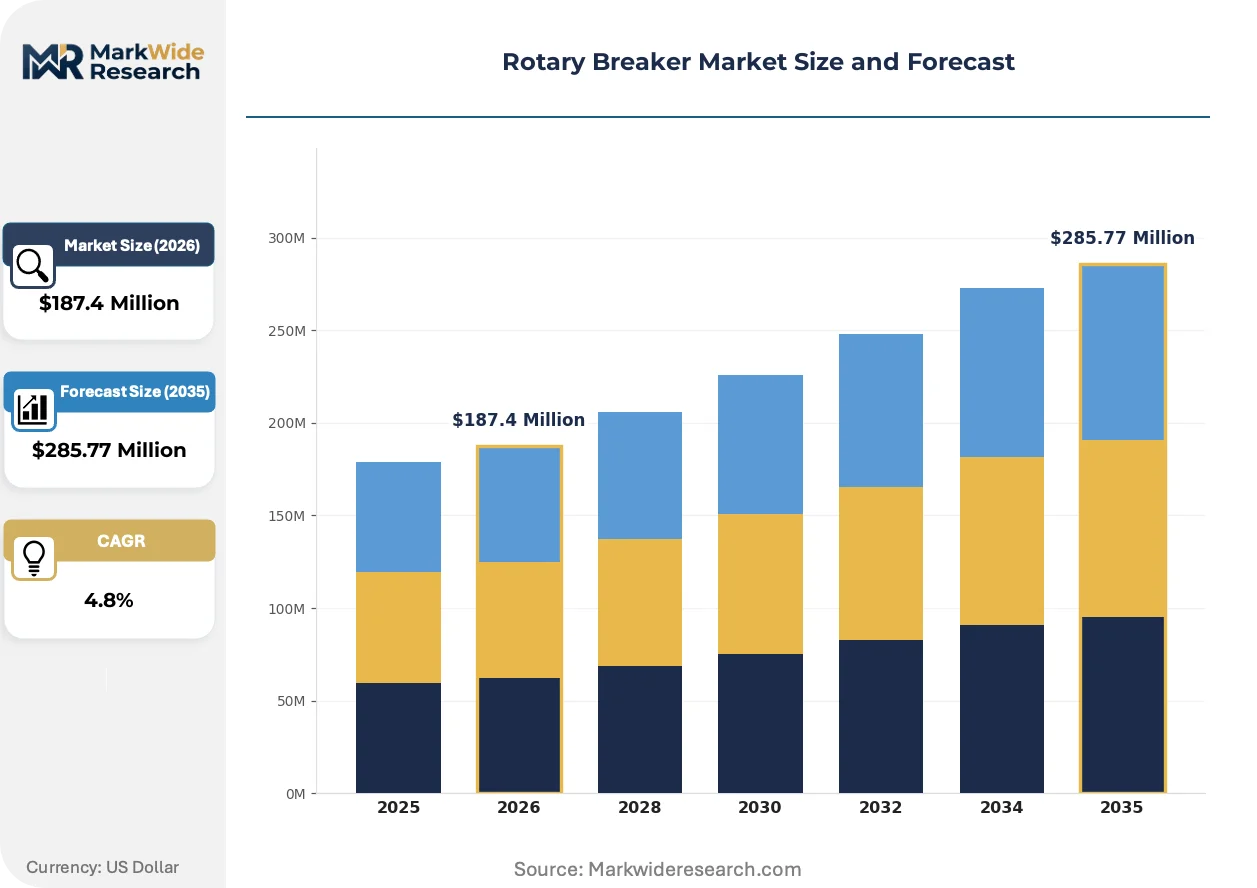
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Roll Breakers, Double Roll Breakers, Multi Roll Breakers, Jaw Crushers Application: Coal Cleaning, Mineral Processing, Construction Aggregates, Waste Handling End User: Mining Operations, Construction Companies, Recycling Firms, Energy Producers Distribution Channel: Direct Sales, Distributors, Online Platforms, Industrial Auctions |
| Companies Covered | Atlas Copco, Caterpillar Inc., McLanahan Corporation, Hitachi Construction Machinery, Doosan Corporation, Sandvik AB, Komatsu Ltd., Furukawa Rock Drill, Epiroc AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Breaker Market Evolving Landscape
Rotary breaker engineering is pivoting from mechanical reliability toward energy efficiency and emissions compliance, with three concurrent developments reshaping procurement criteria at coal operators.
Direct-drive permanent magnet motors are collapsing the maintenance burden associated with gearbox-coupled breaker drums. Surface mines in Wyoming specify these systems to eliminate lubrication intervals and reduce downtime during 2,000 ton-per-hour campaigns. The technology is collapsing total cost of ownership calculations that previously favored refurbished mechanical units.
EPA enforcement of coal combustion residuals rules is tightening specifications for fugitive dust containment at preparation plants. Operators must install negative-pressure breaker housings with baghouse connections to satisfy compliance thresholds. Underground longwall operations in Alabama and Colorado face the steepest retrofit requirements due to proximity to residential receptors.
Service unbundling is fragmenting the traditional bundled sales model for breaker systems. Large coal operators now procure drums, drives, and control systems through separate RFPs, forcing manufacturers to defend component margins rather than capture full-system value. This pattern concentrates among Powder River Basin producers with in-house engineering staffs capable of system integration.
Rotary Breaker Market Segmentation
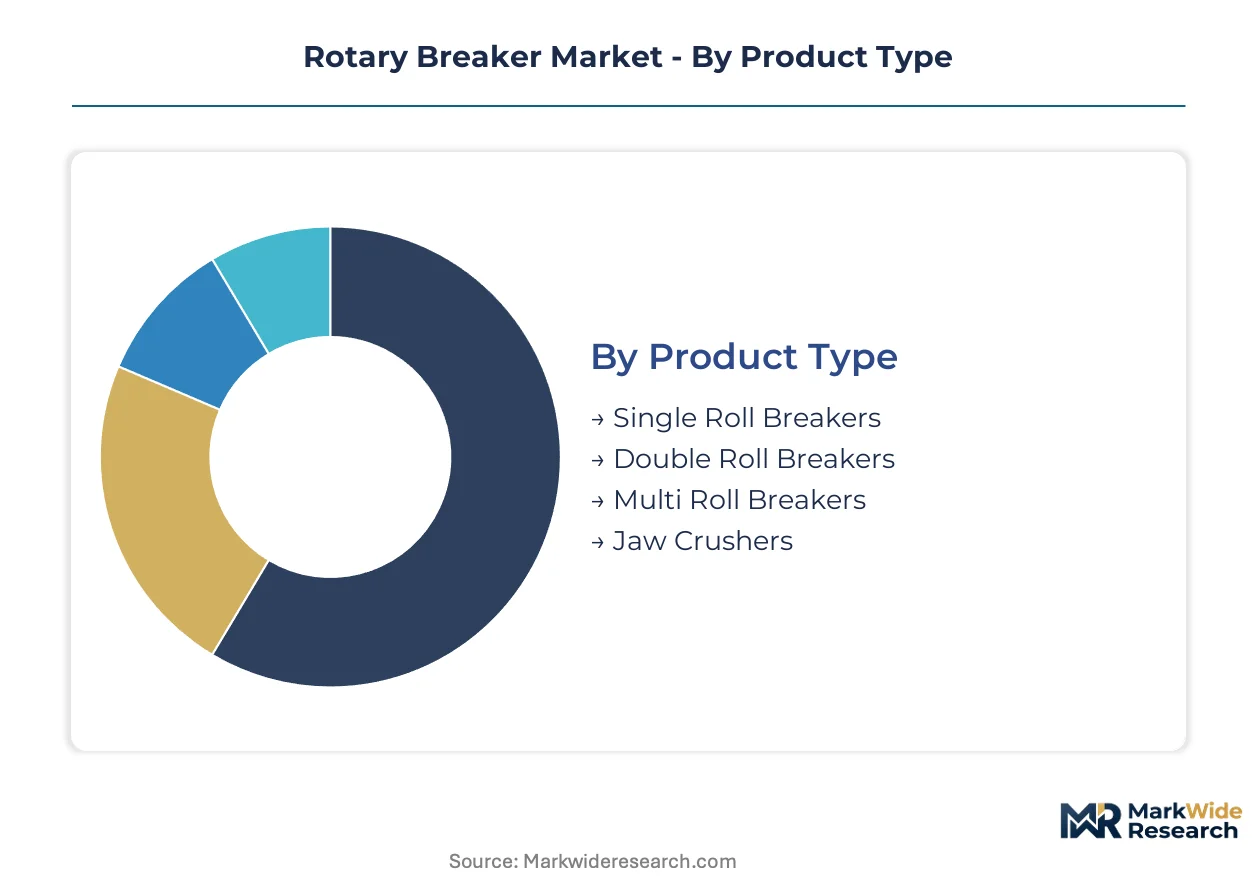
Rotary breaker procurement patterns diverge sharply across product configurations and end-use environments, with coal cleaning specifications driving premium engineering requirements while mineral processing applications tolerate broader sizing tolerances. Equipment buyers segment their vendor evaluation criteria by throughput demands, moisture content challenges, and integration complexity with existing preparation plant infrastructure.
Product Type:
Use-case spectrum spans from single-drum simplicity for dry coal streams to multi-roll precision for complex mineral feeds requiring staged size reduction.
- Single Roll Breakers:Cylindrical drums with perforated screen plates rotate at fixed speeds to separate friable coal from harder refuse through differential breakage. Appalachian surface mines in West Virginia and Kentucky specify these units for raw feed streams with consistent moisture profiles below 15 percent.
- Double Roll Breakers:Counter-rotating drums with intermeshing teeth deliver precise size control for high-moisture Illinois Basin coal that jams conventional single-drum designs. Operators at preparation plants in Indiana and Illinois prioritize these configurations to maintain throughput during wet seasons without screen blinding.
- Multi Roll Breakers:Staged crushing zones handle metallurgical coal requiring multiple size fractions for coking blends.
- Jaw Crushers:Compression-based primary reduction for construction aggregate pre-processing at quarry operations.
The dominant share belongs to Single Roll Breakers, while Double Roll Breakers is closing the gap fastest.
Application:
Volume concentration tracks regulatory enforcement intensity, with emissions compliance investments concentrating procurement in coal cleaning while construction aggregates follow infrastructure spending cycles.
- Coal Cleaning:Separation of sulfur-bearing rock and ash-forming minerals from run-of-mine coal at preparation plants. EPA coal combustion residuals rules force enclosure upgrades at Appalachian facilities, triggering replacement demand for dust-suppressed breaker housings in Pennsylvania and Ohio.
- Mineral Processing:Copper porphyry operations in Chile deploy rotary breakers for ore pre-concentration, removing waste rock before energy-intensive grinding circuits.
- Construction Aggregates:Limestone and granite quarries employ breakers for primary sizing before secondary cone crushing.
- Waste Handling:Construction and demolition debris recycling facilities size mixed C&D streams for landfill diversion credits.
Coal Cleaning commands the largest installed base, though Mineral Processing is expanding most quickly outside traditional coal geographies.
End User:
Customer sophistication determines procurement channel selection, with integrated mining houses favoring direct manufacturer relationships while independent operators rely on distributor networks for parts availability.
- Mining Operations:Coal producers in the Powder River Basin negotiate multi-unit fleet purchases with performance guarantees on throughput and availability. These buyers specify variable frequency drive integration and energy recovery systems to reduce operating costs during partial-load campaigns.
- Construction Companies:Aggregate producers prioritize initial capital cost over lifecycle efficiency, favoring refurbished mechanical units for short-project durations.
- Recycling Firms:C&D processors demand rapid screen changeout capabilities for mixed waste streams with unpredictable feed composition.
- Energy Producers:Power plant coal handling departments procure breakers for fuel preparation systems, with CEA-mandated beneficiation requirements driving first-time demand at Indian thermal stations.
Mining Operations retains the dominant procurement volume, while Energy Producers is climbing the fastest on the back of international coal quality regulations.
Distribution Channel:
Channel selection reflects equipment complexity and buyer technical capability, with engineered systems requiring factory-direct commissioning while standardized units flow through regional inventory.
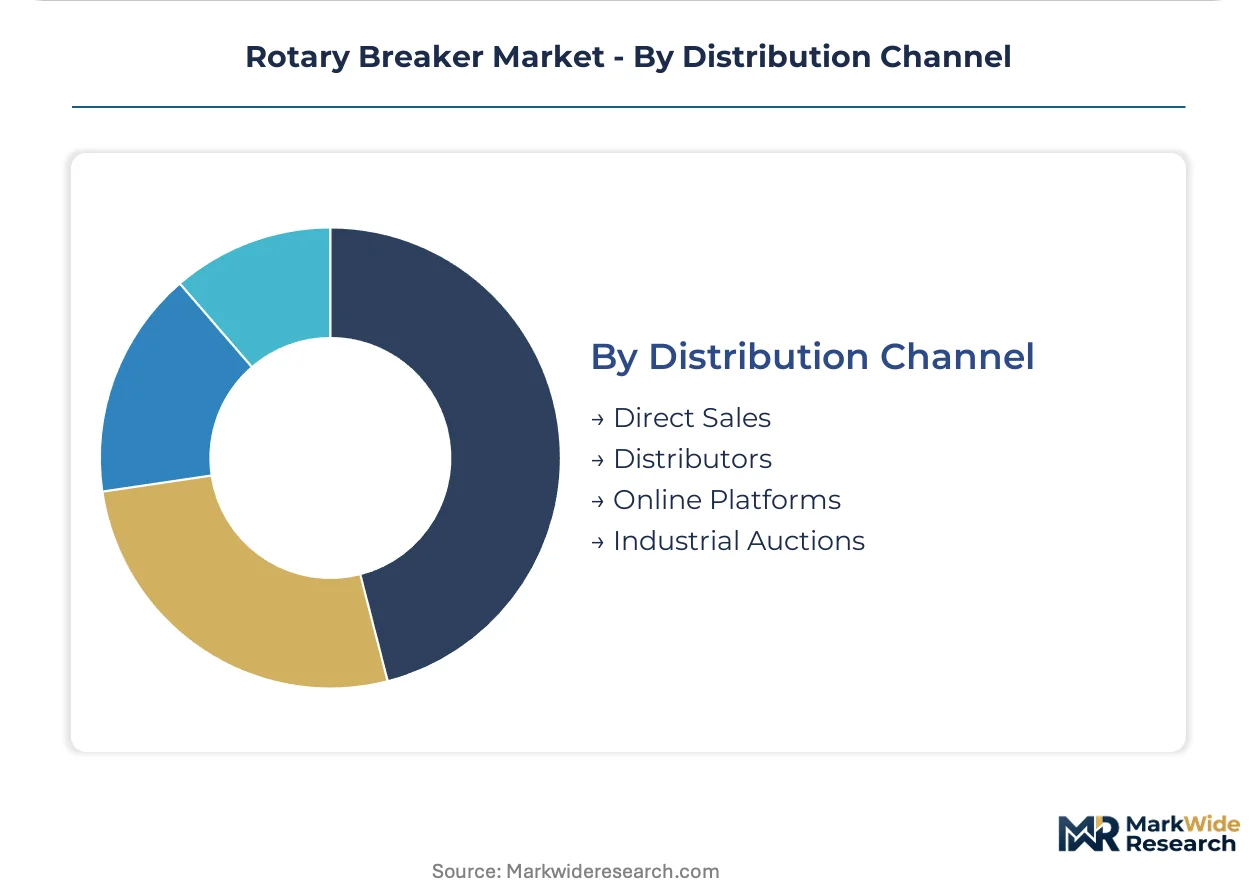
- Direct Sales:Manufacturer engineering teams design integrated breaker systems with custom drum diameters, drive configurations, and dust containment specifications. Large coal operators in Wyoming and Montana specify direct channels for 96-inch diameter units requiring specialized transport logistics.
- Distributors:Regional equipment dealers stock wear components and smaller breaker models for immediate availability. Caterpillar's dealer network dominates aftermarket parts revenue across coal-producing counties.
- Online Platforms:Surplus equipment marketplaces facilitate secondary market transactions for idled preparation plant assets.
- Industrial Auctions:Bankruptcy and mine closure sales redistribute mechanical breakers to smaller operators seeking depreciated capital equipment.
Direct Sales captures the premium system value, while Distributors is gaining share fastest through aftermarket parts consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rotary breaker trade flows reflect coal mining intensity and import substitution policies across major producing jurisdictions. Equipment exports concentrate from established manufacturing bases toward emerging beneficiation markets.
United States
Appalachian surface mines in West Virginia and Kentucky drive replacement demand for enclosed breaker housings. EPA coal combustion residuals enforcement mandates dust-suppressed systems at preparation plants. The Powder River Basin in Wyoming anchors high-throughput procurement for 96-inch diameter units with variable frequency drive integration.
Australia
Queensland metallurgical coal operations deploy rotary breakers for coking blend preparation before export to Asian steel mills. The country's national mining regulator enforces strict dust exposure limits at open-cut sites. The Bowen Basin coal cluster near Mackay concentrates fleet upgrade activity for autonomous-compatible crushing circuits.
India
CEA mandates for coal beneficiation at thermal power stations create first-time demand for imported breaker systems. Central Electricity Authority regulations require ash reduction to 34 percent for domestic coal burned at utilities. Jharkhand and Odisha host the steepest installation curves where mine-mouth power plants lack preparation infrastructure.
Chile
Copper porphyry operations in the Atacama Desert deploy rotary breakers for ore pre-concentration before energy-intensive grinding. The national mining regulator encloses crushing circuits to protect surrounding communities from particulate emissions. The Chuquicamata and Escondida superclusters drive non-coal revenue diversification for drum manufacturers.
Germany
Lignite mining in the Rhineland and Lusatia regions sustains residual demand for high-capacity breakers at RWE and LEAG operations. EU Green Deal phase-out timelines compress replacement cycles toward end-of-life equipment. The Hambach and Garzweiler surface mines represent the final European concentration of rotary breaker procurement for brown coal applications.
Rotary Breaker Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified mining equipment conglomerates and specialized crushing system fabricators. Strategic archetypes include full-line construction-mining hybrids with captive foundry capacity, dedicated mineral processing specialists with application engineering depth, and regional fabrication houses serving aftermarket parts demand. Competitive dynamics center on vertical integration into wear component manufacturing and electrification engineering partnerships for mine site power infrastructure.
Among diversified heavy equipment manufacturers, Caterpillar Inc. and Komatsu Ltd. occupy positions anchored by global distribution networks and in-house breaker drum production. McLanahan Corporation exemplifies the specialized engineering tier with focused expertise in double roll configurations for high-moisture coal applications. Sandvik AB and Epiroc AB represent the European technology-driven segment with integrated automation capabilities for remote operation.
| Leading Market Players |
|---|
| Atlas Copco |
| Caterpillar Inc. |
| McLanahan Corporation |
| Hitachi Construction Machinery |
| Doosan Corporation |
| Sandvik AB |
| Komatsu Ltd. |
| Furukawa Rock Drill |
| Epiroc AB |
| Others |
Value Network & Pricing Analysis
Domestic foundry capacity for 96-inch breaker drums concentrates in Pennsylvania and Ohio, anchoring margin capture at the casting tier while fabricators downstream compete on assembly efficiency and aftermarket service bundling. This upstream bottleneck shapes how pricing power distributes between drum manufacturers and system integrators across coal-producing regions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span multi-year fleet purchases with performance guarantees on throughput and availability. Price differentiation rests on abrasion-resistant alloy grade certification and variable frequency drive integration level, with premium tiers commanding wider margins for dust-suppressed enclosures compliant with EPA coal combustion residuals rules. Cost compression in standard mechanical configurations is intensifying because refurbished unit competition from mine closure auctions floods secondary markets. Independent operators in Appalachia exhibit the highest price sensitivity, while Powder River Basin integrated mining houses prioritize lifecycle efficiency over initial capital outlay.
Supply Chain Analysis
Extended payment terms from 90 to 180 days have become standard for large-diameter breaker drum orders, with supply-chain finance facilities increasingly bridging working capital gaps for foundries in Pennsylvania and Ohio. Raw material feeds draw from domestic scrap metal markets, Canadian alloy plate imports, and Australian manganese ore for wear-resistant castings. Single-source vulnerability concentrates at the 96-inch drum casting tier where domestic capacity cannot surge to meet spike demand. Distribution runs through manufacturer-direct channels for engineered systems and Caterpillar's dealer network for aftermarket wear components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EPA enforcement of coal combustion residuals rules triggers replacement demand at aging Appalachian preparation plants, creating a tailwind for enclosed breaker housing upgrades that outpaces underlying coal production growth.
For Market Incumbents: Harden foundry capacity control through captive supply agreements with Pennsylvania and Ohio casting houses to defend against mineral sizer substitution from MMD and FLSmidth in metallurgical coal circuits. Extend electrification engineering partnerships to secure grid-connection infrastructure contracts as IRA clean energy tax credits reshape mine site power decisions. For New Entrants and Emerging Players: Copper porphyry pre-concentration applications in Chile represent the most penetrable entry point for drum manufacturers seeking non-coal revenue diversification. India's CEA-mandated coal beneficiation at Jharkhand and Odisha power plants offers first-time import demand for mid-size breaker systems. Pursue joint venture structures with local EPC contractors to navigate customs logistics and commissioning requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabrication houses holding aftermarket parts contracts across Appalachian coal counties. Long-term viability hinges on electrification transition execution over a five-to-ten year window as diesel retrofit economics deteriorate. Monitor MSHA dust exposure limit revision timelines as an inflection signal for enclosed housing retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive supply of 96-inch breaker drums eliminates single-source vulnerability for large-diameter orders. |
| Electrification Engineering Partnership | Grid-connection infrastructure contracts leverage IRA tax credits for electric breaker installations at Wyoming surface mines. |
| Aftermarket Service Unbundling | Separate RFP procurement for drums, drives, and controls captures component margin defense against integrated mining house engineering staffs. |
| Copper Porphyry Diversification | Ore pre-concentration deployments at Chilean superclusters open non-coal revenue streams for drum manufacturers. |
| India Market Entry Joint Venture | Local EPC partnerships navigate CEA beneficiation mandates at Jharkhand and Odisha mine-mouth power plants. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at Powder River Basin surface mines, plant engineers at Appalachian preparation facilities, OEM procurement teams at diversified mining equipment manufacturers, and aftermarket service heads at regional fabrication houses, then refined through secondary validation against MSHA enforcement records, EPA coal combustion residuals compliance filings, SEC 10-K disclosures from heavy equipment conglomerates, and customs trade data for alloy plate imports. Bottom-up equipment unit economics triangulated against top-down coal preparation plant capital expenditure patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product configuration type, application environment, end-user sophistication tier, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield beneficiation capacity additions. Industry-specific forecast inputs incorporated electrification cost curve trajectories and scrap metal commodity volatility indices.
Macroeconomic conditions sit as an overlay; deviation in steel input pricing and mine site power infrastructure investment rates would shift the trajectory. Forecasts reflect documented assumptions on EPA enforcement intensity and MSHA certification timeline adherence. Regulatory suspension of coal combustion residuals rules or acceleration of lignite phase-out timelines under EU Green Deal frameworks would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Europe Port Equipment Market