
 Sound Reinforcement Market | 2026-2036
Sound Reinforcement Market Size, Share, and Industry Trends Forecast 2026-2036
Sound Reinforcement Market Outlook
Corporate events is repositioning as the fastest-growing end-use vertical as enterprises expand hybrid meeting infrastructure and immersive presentation spaces. Harman International leverages its integrated ecosystem of amplifiers, loudspeakers, and control software to dominate installed corporate audio. Yamaha Corporation anchors professional audio through its digital mixing console portfolio and extensive service network for live venues. Shure Incorporated differentiates through wireless microphone technology leadership and frequency coordination expertise for spectrum-constrained environments.
Sound reinforcement encompasses the complete signal chain of electro-acoustic systems designed to amplify, process, and distribute audio in live or installed environments, typically spanning frequency responses from 20 Hz to 20 kHz and sound pressure levels exceeding 130 dB for large-format applications. The primary purpose is to deliver intelligible, high-fidelity audio coverage to audiences across variable acoustic spaces. Speakers command the largest product category by installed value, driven by line array deployments in touring and fixed installations. Digital technology is displacing analog architectures as Dante networking, DSP-based loudspeaker management, and software-defined mixing reduce cabling complexity and enable remote diagnostics. Microphones retain concentrated margin pools in premium wireless segments where RF stability and encryption capabilities separate professional from consumer tiers.
The FCC regulates wireless microphone frequency allocations and transmission power in the United States, while the EU's Radio Equipment Directive and RED compliance framework govern spectrum harmonization across member states. These regulations compel manufacturers to redesign RF architectures and certify products for regional frequency plans, directly influencing R&D allocation and product line segmentation. Stakeholders must monitor emerging spectrum auctions and energy efficiency mandates that could obsolete existing hardware inventories or create compliance-driven replacement cycles.
Market Dynamics
Networked audio architectures are compressing installation timelines and reconfiguring value capture across the signal chain. Dante protocol adoption in touring and installed sound is absorbing margin from traditional copper infrastructure while shifting technical differentiation toward software-defined control layers.
Growth Catalysts
- Live venue infrastructure renewal:Concert halls in Germany and the United Kingdom are replacing aging analog systems with steerable line arrays and networked amplification to meet rising SPL and coverage requirements for immersive formats.
- FCC spectrum reallocation:The FCC's 600 MHz band clearance is compelling broadcast and live production facilities to migrate toward digital wireless microphone systems with AES-256 encryption and automated frequency coordination.
- Immersive audio formats:Object-based spatial audio standards for cinema and live performance are driving loudspeaker count expansion and DSP channel density in premium installations.
Market Restraints
- Rare earth magnet supply concentration:Neodymium pricing volatility and processing concentration in China creates input cost instability for high-output transducer manufacturers.
- RF spectrum scarcity:Wireless microphone operators face shrinking available UHF spectrum as mobile broadband auctions encroach on traditional professional audio frequency blocks.
- Long replacement cycles:Installed sound systems in houses of worship and municipal venues often exceed fifteen-year service life, compressing refresh revenue for equipment vendors.
Strategic Opportunities
- India live event infrastructure:Untapped demand for touring-grade systems exists in Mumbai and Bangalore as international artist bookings accelerate and domestic promoter capacity expands.
- Software subscription models:DSP platform vendors can capture recurring revenue through loudspeaker management and room tuning applications delivered via cloud-connected hardware.
- EU Green Deal alignment:Energy efficiency mandates for commercial buildings create specification advantages for Class-D amplification and passive cooling designs in permanent installations.
Industry Challenges
- RF coordination expertise gap:Venue technicians lack training in spectrum analyzer operation and intermodulation calculation for dense wireless microphone deployments.
- Legacy analog integration:Hybrid installations require protocol bridging between Dante networks and existing copper snake systems, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sound Reinforcement Market |
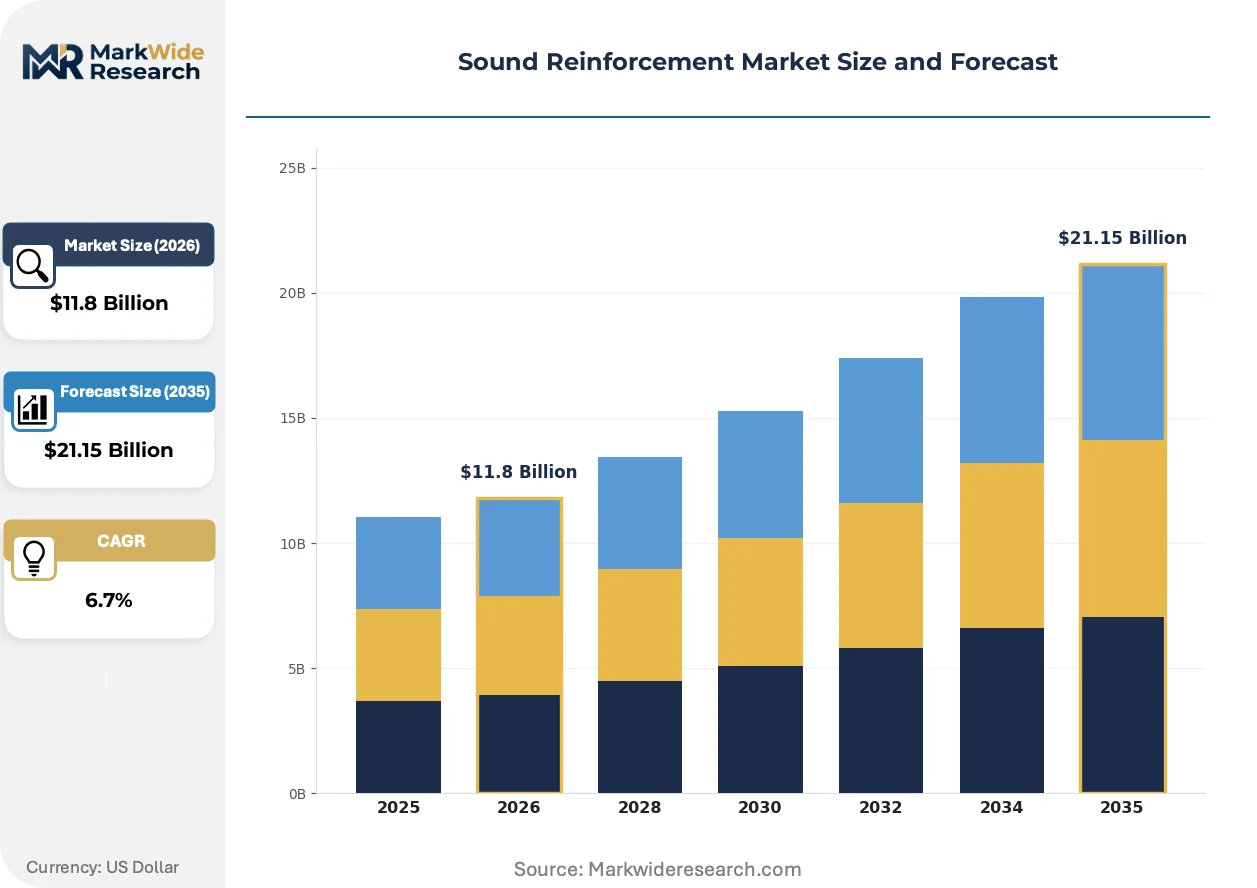
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Amplifiers, Speakers, Mixers End User: Concerts, Theaters, Corporate Events, Houses of Worship Technology: Active, Passive, Digital, Analog Application: Public Address, Live Sound, Recording, Broadcasting |
| Companies Covered | Bose Corporation, Harman International, Yamaha Corporation, Shure Incorporated, Sennheiser Electronic, Audio-Technica, Sony Corporation, JBL Professional, Electro-Voice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sound Reinforcement Market Strategic Shifts
Audio-over-IP protocols are dissolving the boundary between signal transport and control, enabling centralized management of distributed loudspeaker networks. This convergence is compressing the distinction between live sound and installed AV while opening new service revenue models.
Beam-steering loudspeaker technology is absorbing market share from mechanically aimed line arrays in acoustic-critical venues. Houses of worship and corporate atria in the United States are adopting column arrays with DSP-controlled vertical pattern adjustment to address reflective surfaces without physical repositioning. The technology is absorbing commissioning budget from traditional rigging and tuning labor.
The EU Radio Equipment Directive's harmonized frequency access rules are fragmenting product certification requirements across member states. Manufacturers must validate wireless microphone transmitters against multiple national frequency plans, extending time-to-market for new RF platforms. Germany's BNetzA implementation is particularly stringent, creating a de facto regulatory laboratory for European spectrum compliance.
Enterprise AV departments are consolidating purchasing authority previously dispersed across facilities and IT groups. Fortune 500 headquarters in the United States now specify unified communication platforms where sound reinforcement integrates with video conferencing and building management systems. This concentration is compressing vendor count and favoring suppliers with certified interoperability across Microsoft Teams and Zoom Rooms ecosystems.
Sound Reinforcement Market Segmentation
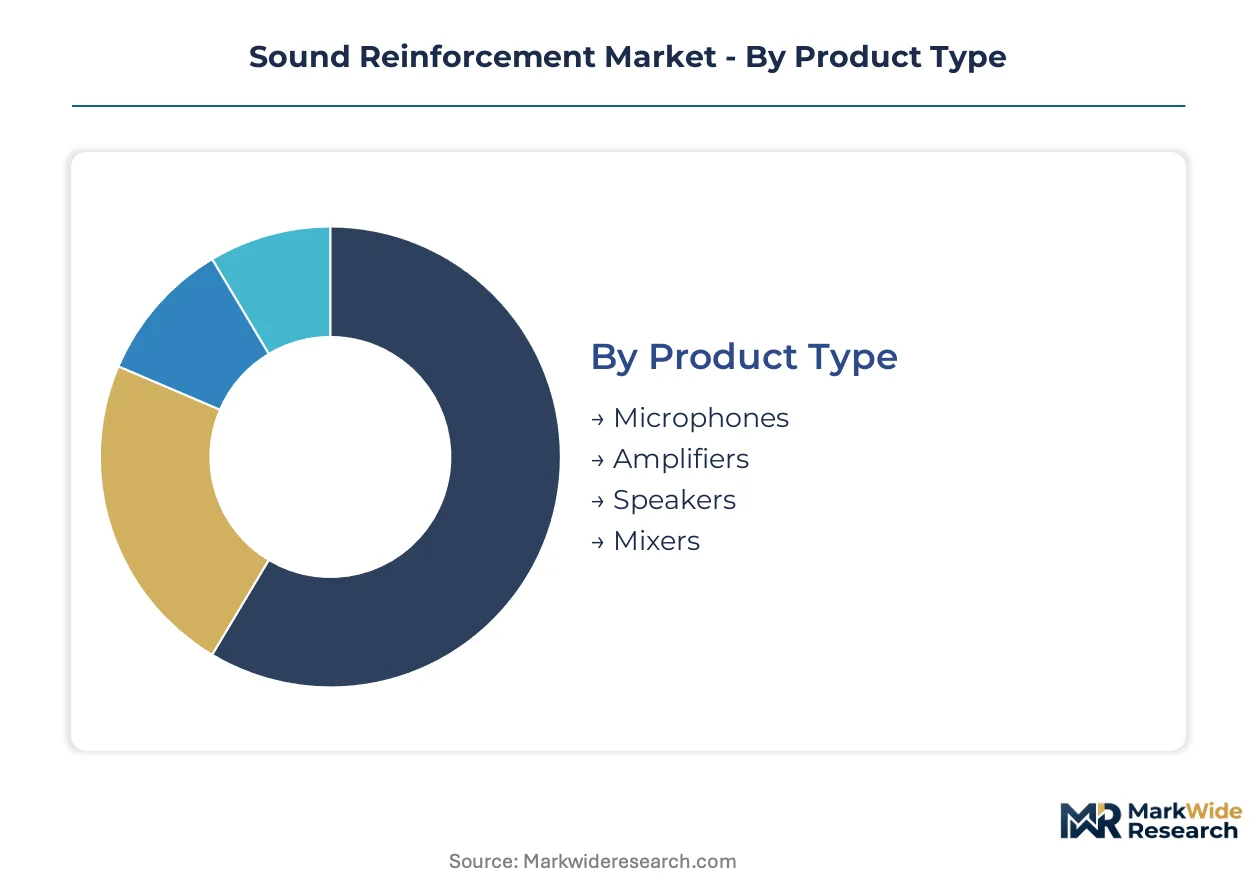
Sound reinforcement procurement diverges sharply across use cases, with installed corporate systems prioritizing network interoperability while touring productions emphasize thermal efficiency and rapid deployment. Segmentation reveals how technology choices cascade through specification requirements, maintenance protocols, and replacement cadences.
Product Type:
Supply concentration in transducer manufacturing and DSP chip fabrication concentrates margin capture among integrated amplifier-loudspeaker vendors.
- Speakers:Line array and point-source enclosures dominate installed value, with neodymium motor structures and onboard Class-D amplification reducing transport weight for touring applications. Demand concentrates in Germany's Messe Frankfurt and London's West End venues as immersive audio formats expand loudspeaker count requirements.
- Microphones:Wireless handheld and lavalier systems absorb premium pricing through AES-256 encryption and automated frequency coordination capabilities. FCC spectrum reallocation in the United States is accelerating digital wireless migration as analog UHF bands clear.
- Amplifiers:Networked amplification with Dante audio-over-IP integration enables centralized monitoring and reduced cabling infrastructure.
- Mixers:Digital consoles with motorized faders and multi-touch surfaces displace analog architectures in mid-market installations.
Today's leader: Speakers. Tomorrow's challenger: Microphones.
End User:
Corporate event budgets now exceed house of worship refresh cycles, reconfiguring vendor sales force deployment toward enterprise AV departments.
- Corporate Events:Hybrid meeting infrastructure and immersive presentation spaces drive specification of beam-steering column arrays and software-defined DSP platforms. Fortune 500 headquarters in the United States consolidate purchasing authority across facilities and IT groups, favoring certified interoperability with Microsoft Teams and Zoom Rooms ecosystems.
- Concerts:Touring productions demand ruggedized line arrays with rapid rigging systems and networked amplification for daily load-in/load-out schedules. International artist bookings in Mumbai and Bangalore are expanding demand for touring-grade systems.
- Theaters:Acoustic-critical venues adopt steerable loudspeaker technology to address reflective surfaces without physical repositioning.
- Houses of Worship:Extended replacement cycles exceeding fifteen years compress refresh revenue, though beam-steering column arrays gain adoption for speech intelligibility in reverberant spaces.
Corporate Events expands most quickly. Concerts retains the largest installed base.
Technology:
Cost tier stratification separates premium digital networking solutions from legacy analog maintenance markets.
- Digital:Dante protocol adoption, DSP-based loudspeaker management, and software-defined mixing reduce cabling complexity and enable remote diagnostics. EU Green Deal energy efficiency mandates create specification advantages for networked Class-D amplification.
- Active:Self-powered loudspeakers with onboard amplification and DSP simplify system commissioning while reducing amplifier rack footprint.
- Analog:Copper snake infrastructure persists in budget-constrained municipal venues and legacy installations requiring protocol bridging.
- Passive:External amplification configurations retain presence in large-format touring systems requiring centralized thermal management.
Digital commands premium pricing. Active gains share fastest.
Application:
Volume concentration in live sound touring contrasts with margin stability in broadcast infrastructure.
- Live Sound:Concert halls in Germany and the United Kingdom replace aging analog systems with steerable line arrays and networked amplification to meet rising SPL and coverage requirements.
- Broadcasting:FCC 600 MHz band clearance compels production facilities toward digital wireless microphone systems with automated frequency coordination.
- Public Address:Transportation hubs and stadium concourses specify weather-resistant column arrays for speech intelligibility.
- Recording:Studio environments prioritize low-noise microphone preamplification and acoustic isolation over networked connectivity.
Live Sound dominates transaction volume. Broadcasting sustains margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting manufacturing footprints as compliance costs for wireless spectrum certification diverge across jurisdictions. Manufacturers now optimize production location against the cost-of-compliance gap for FCC, EU Radio Equipment Directive, and national frequency coordination requirements.
United States
Live entertainment infrastructure renewal and corporate AV consolidation drive procurement of networked audio systems. The FCC's 600 MHz band clearance compels facilities toward digital wireless migration with AES-256 encryption. Nashville's music venue cluster and Las Vegas integrated resorts anchor premium system deployments.
Germany
Messe Frankfurt and major concert halls including Berlin Philharmonie and Elbphilharmonie Hamburg sustain premium loudspeaker upgrade cycles. BNetzA's stringent Radio Equipment Directive implementation creates a de facto regulatory laboratory for European spectrum compliance. Munich and Hamburg concentrate touring-grade system procurement for international productions.
United Kingdom
West End theaters and London's O2 Arena complex demand steerable line arrays for immersive audio formats. Ofcom's spectrum management frameworks govern wireless microphone frequency coordination alongside EU RED alignment post-Brexit. London's corporate headquarters sector consolidates purchasing authority for hybrid meeting infrastructure.
India
International artist bookings in Mumbai and Bangalore accelerate demand for touring-grade systems as domestic promoter capacity expands. TRAI's spectrum allocation frameworks for wireless audio devices remain under development, creating regulatory uncertainty. Mumbai's film production infrastructure and Bangalore's tech campus atria drive column array adoption for speech intelligibility.
Japan
Broadcast infrastructure and live venue refurbishment sustain demand for digital mixing consoles and wireless microphone systems. METI's radio equipment certification requirements and JIS standards govern product market entry. Tokyo's concert hall district and Osaka's commercial broadcast facilities anchor premium equipment procurement.
Sound Reinforcement Market Competitive Environment
Portfolio diversification dominates the current landscape as vendors extend from hardware into software-defined control layers and recurring service revenue. The market exhibits tiered concentration: integrated conglomerates capture installed corporate value, specialized wireless manufacturers defend premium RF segments, and regional fabricators compete on cost-engineered touring packages. Three archetypes prevail: ecosystem-integrated suppliers, RF technology specialists, and scale-driven transducer manufacturers. M&A activity and strategic technology licensing represent the dominant competitive vectors.
Among ecosystem-integrated suppliers, Harman International and Yamaha Corporation occupy positions spanning amplifiers, loudspeakers, and control software. Shure Incorporated exemplifies the RF technology specialist archetype, anchoring wireless microphone segments where frequency coordination expertise separates professional from consumer tiers. These three companies represent distinct strategic postures: integrated platform breadth, professional audio heritage, and wireless transmission leadership.
| Leading Market Players |
|---|
| Bose Corporation |
| Harman International |
| Yamaha Corporation |
| Shure Incorporated |
| Sennheiser Electronic |
| Audio-Technica |
| Sony Corporation |
| JBL Professional |
| Electro-Voice |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between AES-256 encrypted digital wireless systems and legacy analog microphones manifests in both pricing stratification and supply chain sourcing patterns. Premium RF platforms command three-tier pricing across enterprise, broadcast, and touring tiers while drawing from concentrated neodymium magnet suppliers in China and specialized DSP fabricators in Taiwan and Japan.
Pricing Analysis
Distributor margins absorb 25-35 points on professional audio hardware before system integrators apply project-based markups for commissioning and calibration services. Pricing stratifies across premium, standard, and economy tiers based on RF channel density and Dante networking integration, with FCC-compliant digital wireless systems carrying certification premiums over analog equivalents. Cost compression in entry-level powered loudspeakers is intensifying because Chinese OEMs are scaling Class-D amplification modules. House of worship and municipal venue buyers exhibit highest price sensitivity, while broadcast and touring rental houses prioritize RF reliability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for critical RF components compel manufacturers to qualify both Taiwanese and Japanese DSP suppliers alongside domestic alternatives. Neodymium motor structures draw from Chinese rare earth processing, while precision capacitors and Class-D amplifier modules source from South Korea and Malaysia. Single-source vulnerability concentrates in specialized UHF oscillator crystals where German and Swiss suppliers dominate. Distribution runs through regional AV integrators and touring rental houses, with direct OEM relationships governing large-format line array deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory-driven replacement cycles, with FCC spectrum reallocation and EU Radio Equipment Directive harmonization forcing hardware obsolescence across installed bases.
For Market Incumbents: Anchor defensive positioning through backward integration into DSP chip design and captive RF oscillator supply. Deepen channel control by certifying service networks for automated frequency coordination software. Counter emerging white-label Chinese entrants by bundling encryption-licensed wireless systems with multi-year spectrum management subscriptions. For New Entrants and Emerging Players: Launch via direct-to-rental-house distribution to bypass entrenched integrator relationships. Target India's nascent touring infrastructure in Mumbai and Bangalore where international promoter demand outpaces qualified local supply. Penetrate through software-defined DSP platforms priced below incumbent hardware-locked ecosystems. For Investors and Strategic Acquirers: Consolidation pressure builds where wireless microphone specialists lack amplifier-loudspeaker integration to compete for corporate AV consolidation contracts. Long-term viability favors vendors with recurring software revenue attaching to installed hardware bases. Watch for inflection when TRAI finalizes India's wireless audio spectrum framework, triggering compliance-driven procurement.| Strategic Initiative | Industry Significance |
|---|---|
| RF Platform Certification Investment | Accelerates market access under BNetzA's stringent RED implementation in Germany. |
| Dante Networking Integration | Captures specification authority as enterprise AV consolidates around Audio-over-IP standards. |
| Software Subscription Migration | Converts one-time hardware revenue into recurring loudspeaker management and room tuning services. |
| India Distribution Partnership | Positions for touring-grade demand surge as Mumbai and Bangalore promoter capacity expands. |
| Neodymium Supply Diversification | Reduces input cost volatility from Chinese rare earth processing concentration. |
Study Parameters
Direct dialogue with touring rental house operations managers, corporate AV procurement directors, RF coordination technicians, and house of worship technical directors grounds qualitative assessment in operational reality. Secondary validation draws from FCC equipment authorization databases, EU RED compliance filings, customs records for neodymium magnet imports, and SEC disclosures from listed audio equipment vendors. Bottom-up demand modeling triangulates against top-down market sizing across the projection horizon.
Top-down macroeconomic drivers anchor the analytical framework while bottom-up channel checks verify pricing and procurement patterns across product categories. Segmentation models capture technology tiers, end-use verticals, application contexts, and regional regulatory clusters throughout the forecast period. CAGRs derive from installed base replacement cadences, spectrum reallocation timelines, and immersive audio format adoption curves. Forecast inputs include wireless microphone channel count expansion rates and line array deployment data from Messe Frankfurt and London's O2 Arena.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or extended TRAI deliberation in India. Deviation in neodymium pricing volatility or 600 MHz clearance litigation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Electroshock Weapons Market
Others
Global Smart Kitchen Market
Others
Level Measuring Instrument Market
Others
Powder Coating Equipment Market
Others
Lightweight Compact Wheel Loader Market
Others
Digital Education Projector Market
Others
Android STB and TV Market
Others
Ultrasonic Flow Meter Market
Others
Latin America Automotive HVAC Market
Others
Solar Panel Testers Market
Others
Foldable Smartphone Market
Others
Europe Flow Battery Market
Others
Kuwait Retail Market
Others
Boston Round Bottle Market
Others
Video-As-A-Service (Vaas) Market
Others
Allogeneic T Cell Therapies Market