
 North America 3D Printing Construction Market | 2026-2036
North America 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3D Printing Construction Market Analytics
Concrete is decoupling from traditional formwork economics in North American construction. ICON Technology Inc. leverages proprietary Lavacrete formulations to dominate large-scale residential printing in Texas. Mighty Buildings anchors its position through factory-based panel production with near-zero waste streams. COBOD International extends European hardware designs into US commercial projects through distributor partnerships.
North America 3D printing construction encompasses automated deposition of cementitious, polymeric, or metallic materials through gantry, robotic arm, or crane-mounted systems to produce structural and non-structural building elements with layer heights typically ranging from 10 to 50 millimeters. Material extrusion systems lead installed capacity across the region due to lower capital thresholds and compatibility with conventional ready-mix supply chains. Residential builders represent the deepest margin pool among end users, while infrastructure applications show the steepest growth trajectory as departments of transportation pilot bridge components and culvert sections.
The US Department of Housing and Urban Development, the International Code Council, and OSHA collectively shape product standards, worker safety protocols, and market access pathways for additive construction methods. The National Institute of Standards and Technology coordinates material characterization protocols that influence insurer willingness to underwrite printed structures. Stakeholders must monitor code adoption velocity across municipal jurisdictions to time capacity investments against enforceable demand.
Market Dynamics
The International Code Council's 2024 approval of Appendix AW for 3D-printed concrete walls is compressing permitting timelines across US municipal jurisdictions, triggering capital deployment into previously code-uncertain markets.
Growth Catalysts
- HUD Code Alignment:The US Department of Housing and Urban Development's building code harmonization for additive manufacturing reduces regulatory friction for federally funded affordable housing projects.
- Material Extrusion Compatibility:Cementitious printing systems integrate with existing ready-mix concrete supply chains, lowering adoption barriers for residential builders.
- Southwestern Housing Demand:Texas and California municipalities face acute affordable housing shortages, directing public procurement toward rapid-deployment printed wall systems.
Market Restraints
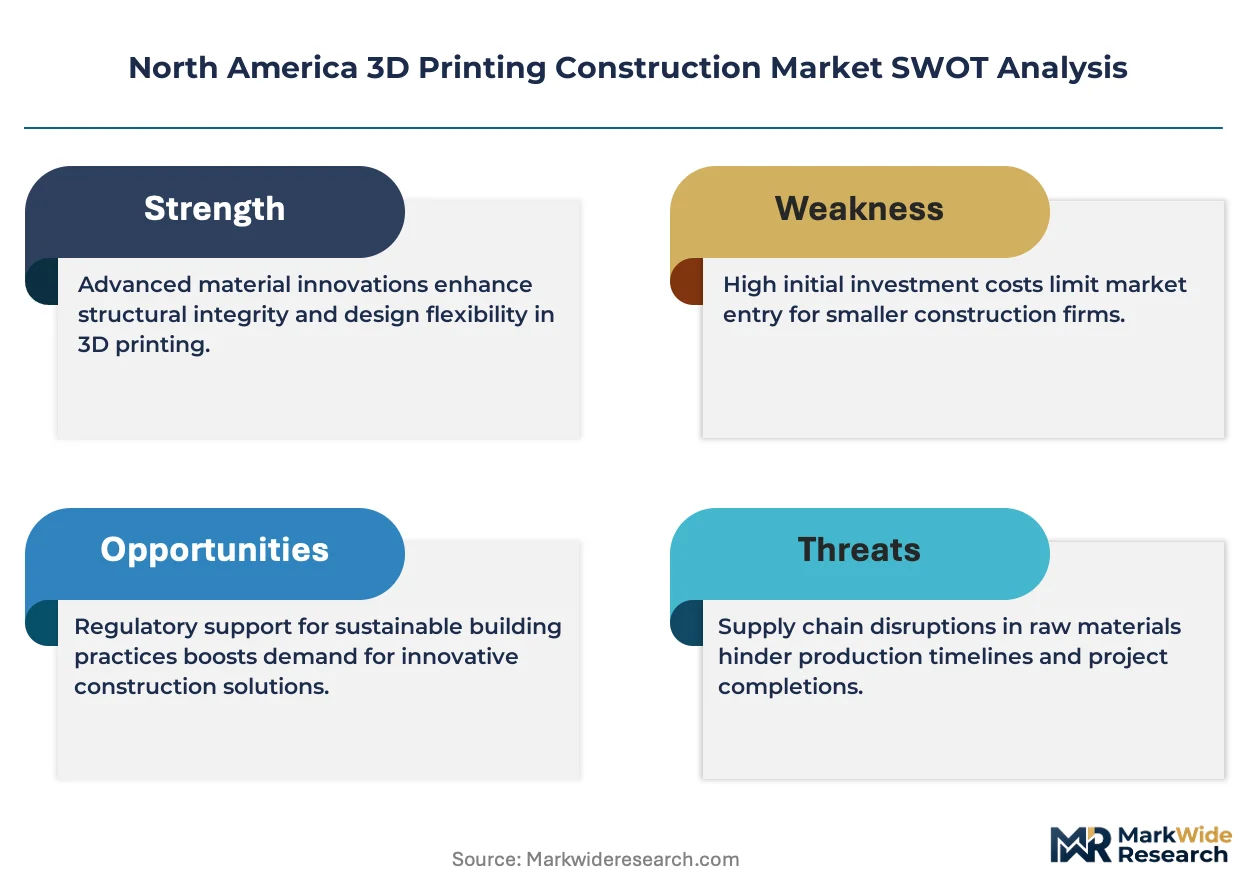
- Portland Cement Price Volatility:Input cost swings for the primary binder in Lavacrete formulations compress margin predictability for project developers.
- Hardware Supply Concentration:European-origin gantry and robotic arm systems create import dependency and lead-time exposure for US-based contractors.
- Rebar Integration Limitations:Current deposition geometries restrict conventional steel reinforcement placement, constraining structural applications to low-rise residential.
Strategic Opportunities
- Department of Transportation Pilots:Infrastructure applications including bridge components and culvert sections represent unpenetrated demand pools with standardized specifications.
- Factory-Based Panel Production:Controlled-environment manufacturing decouples output from weather and site logistics, opening northern US markets with shorter construction seasons.
- OSHA Additive Manufacturing Protocols:Evolving worker safety frameworks for robotic construction sites will create first-mover certification advantages for training-capitalized firms.
Industry Challenges
- Structural Engineer Certification Gap:Licensed professionals with additive construction competency remain scarce, extending project design timelines.
- Multi-Material Deposition Complexity:Integrating insulation, conduits, and finish layers within single print sequences demands workflow reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3D Printing Construction Market |
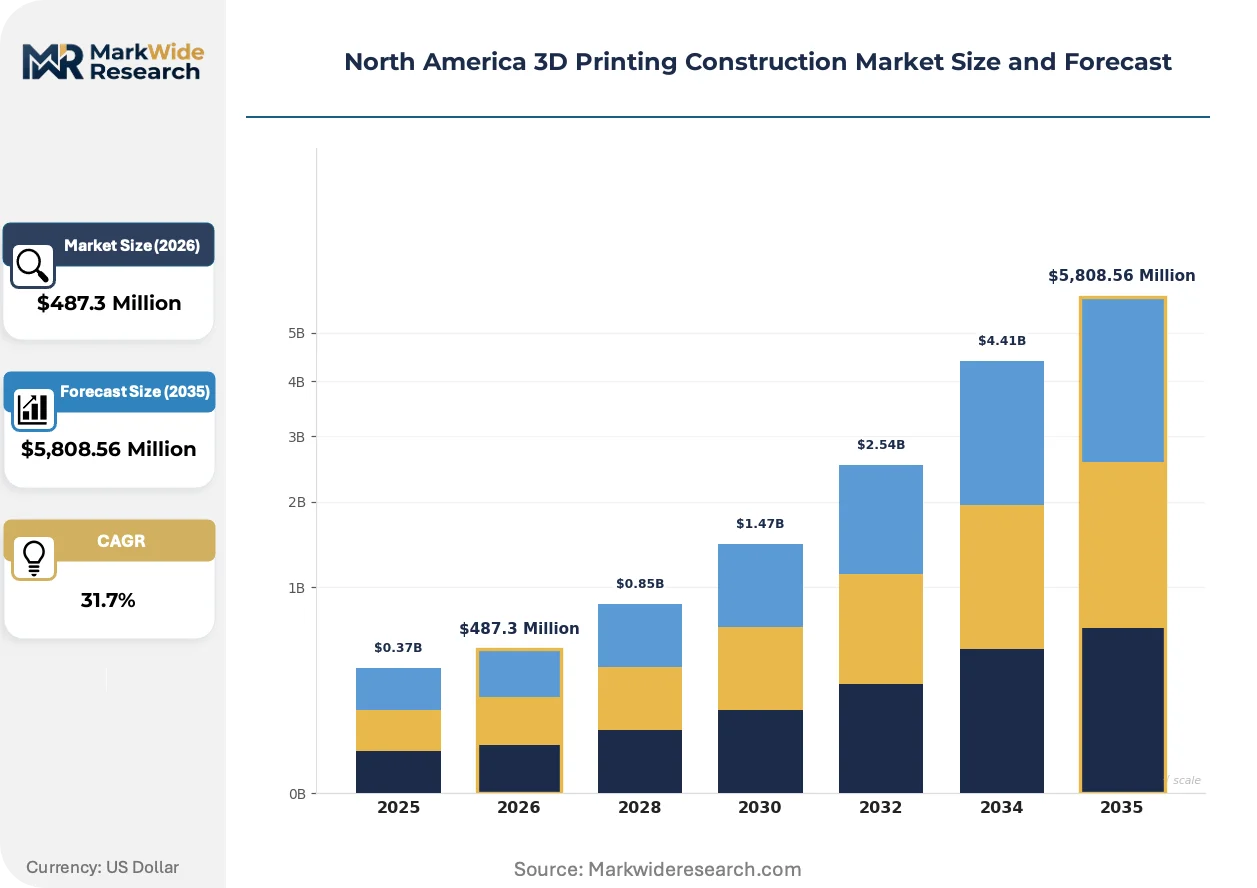
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $5,808.56 Million |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Binder Jetting, Material Extrusion, Powder Bed Fusion, Vat Polymerization Material Type: Concrete, Plastic, Metal, Composite End User: Residential Builders, Commercial Developers, Government Projects, Industrial Entities Application: Building Construction, Infrastructure Development, Renovation Projects, Prototype Creation |
| Companies Covered | ICON Technology Inc., Apis Cor, COBOD International, Mighty Buildings, Skanska AB, Contour Crafting Corporation, Branch Technology, Sika AG, CyBe Construction, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3D Printing Construction Market Evolving Landscape
Layered deposition systems are compressing traditional formwork economics while regulatory clarity unlocks institutional capital deployment. Three developments dominate competitive positioning.
Multi-axis robotic arm configurations are decentralizing construction execution from centralized batch plants to distributed job sites. Residential developers in Arizona and New Mexico deploy mobile systems for on-demand wall production, eliminating formwork rental cycles and reducing skilled labor dependency. This topology is compressing project timelines from months to weeks for single-family enclosures.
The International Code Council's Appendix AW adoption is standardizing structural validation protocols across US jurisdictions. Municipal building departments in Texas reference unified load-testing requirements, reducing project-specific engineering reviews. Commercial developers in Dallas-Fort Worth leverage this clarity to secure construction financing previously withheld from unproven methods.
Design-build contractors are consolidating procurement authority over material selection and deposition parameters. Traditional general contractors cede specification control to integrated firms with captive printing capability, compressing subcontractor tiers. This concentration is most visible in California's Central Valley, where agricultural-to-residential land conversion projects favor single-source envelope delivery.
North America 3D Printing Construction Market Segmentation
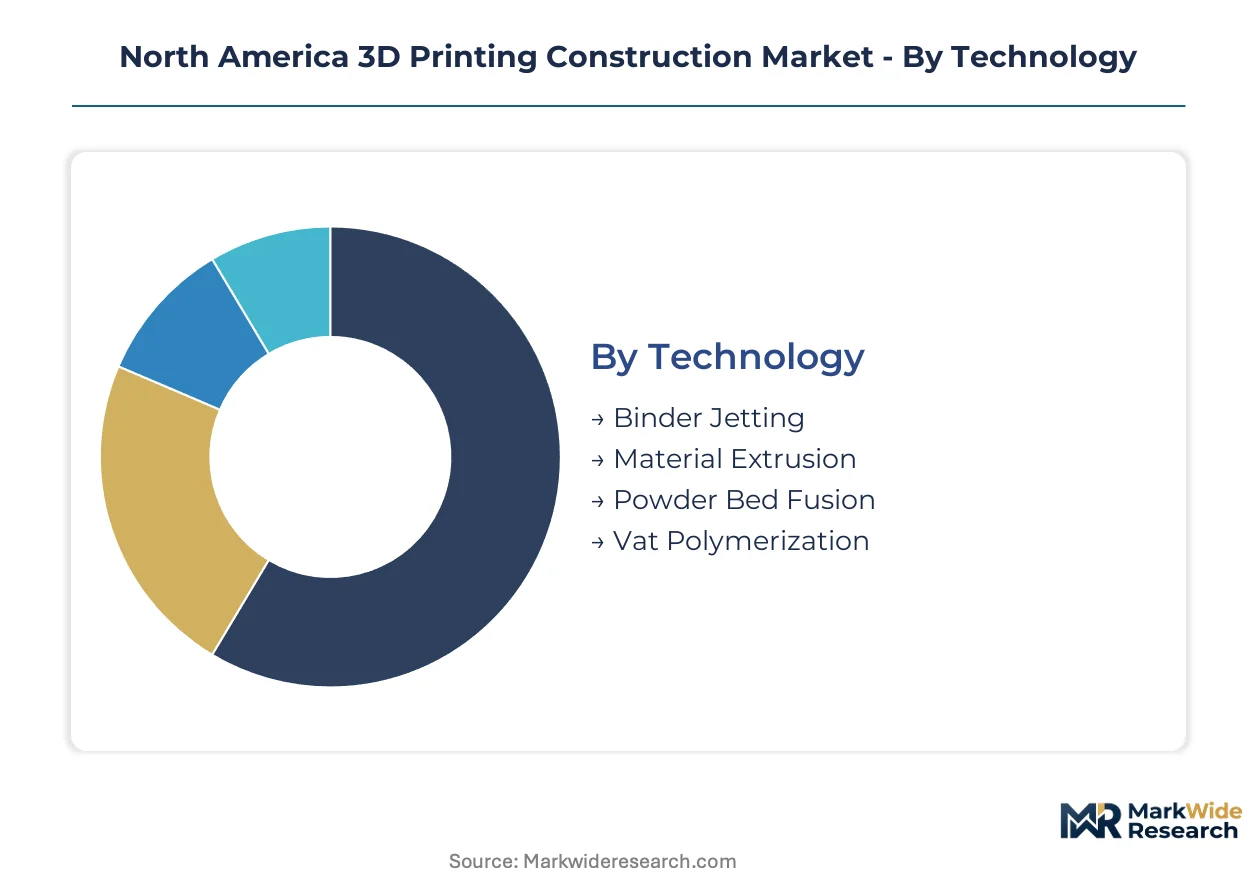
Technology-material pairings determine capital intensity and regulatory pathway for additive construction across North America. End-user procurement authority and application specifications further stratify vendor targeting and margin capture in this emerging build methodology.
Technology:
Standardization dominates high-throughput extrusion systems while binder jetting retains project-specific calibration requirements.
- Material Extrusion:Cementitious deposition through gantry or robotic arm systems dominates installed base due to compatibility with conventional ready-mix supply chains. Demand concentrates among Texas and California residential builders seeking rapid wall assembly without formwork logistics.
- Binder Jetting:Powder-based binding enables complex geometries and metallic component production but requires dedicated feedstock handling infrastructure. Commercial developers in industrial zones pilot this topology for structural connectors and facade elements where geometric complexity justifies higher unit costs.
- Powder Bed Fusion:Laser or electron beam sintering of metallic powders produces high-strength structural components with minimal post-processing. Aerospace-adjacent industrial entities in southwestern manufacturing corridors drive specification authority for this capital-intensive modality.
- Vat Polymerization:Photopolymer curing generates precise architectural models and non-structural interior elements with surface finishes unattainable through deposition methods. Prototype creation workflows in design-build firms anchor demand for this precision-oriented technology.
Leading the category by volume: Material Extrusion. Expanding most quickly: Binder Jetting.
Material Type:
Cost per cubic meter and structural certification status stratify material selection across project types.
- Concrete:Proprietary cementitious formulations with tailored rheology for layer adhesion and green-strength development constitute the primary deposition feedstock. Government-funded affordable housing projects across the southwestern United States specify concrete-based printed wall systems for speed-to-occupancy metrics.
- Plastic:Recycled polymer blends and fiber-reinforced thermoplastics enable non-structural envelope components and interior partition systems. Factory-based panel producers in controlled-environment facilities favor plastic deposition for waste minimization and dimensional precision.
- Metal:Structural steel and aluminum alloys processed through powder-based systems deliver load-bearing connections and architectural features. Industrial entities with in-house additive manufacturing capacity specify metal components for equipment housing and process infrastructure.
- Composite:Hybrid material systems combining cementitious matrices with polymer or fiber reinforcement address thermal performance and crack-resistance requirements. Renovation projects targeting envelope upgrades utilize composite deposition for retrofit compatibility with existing structural frames.
Highest volume concentration: Concrete. Steepest adoption curve: Composite.
End User:
Procurement scale and risk tolerance separate institutional buyers from speculative developers in additive construction adoption.
- Residential Builders:Single-family and small-scale multifamily developers leverage printed wall systems to compress construction schedules and reduce skilled labor dependency. Texas and California municipalities with acute housing shortages direct public procurement toward these rapid-deployment methods.
- Commercial Developers:Office and retail project sponsors require structural engineering certification and insurer acceptance before specifying additive methods. Dallas-Fort Worth design-build contractors consolidate procurement authority over material selection and deposition parameters in this segment.
- Government Projects:Federal and state agencies fund affordable housing and public facility construction with standardized specifications and extended performance warranties. HUD code harmonization for additive manufacturing reduces regulatory friction for this risk-averse buyer category.
- Industrial Entities:Manufacturing and logistics firms deploy additive construction for process buildings, equipment enclosures, and rapid facility expansion. Department of Transportation pilot programs for bridge components and culvert sections originate from this end user's infrastructure focus.
Deepest margin pool: Residential Builders. Fastest procurement velocity: Government Projects.
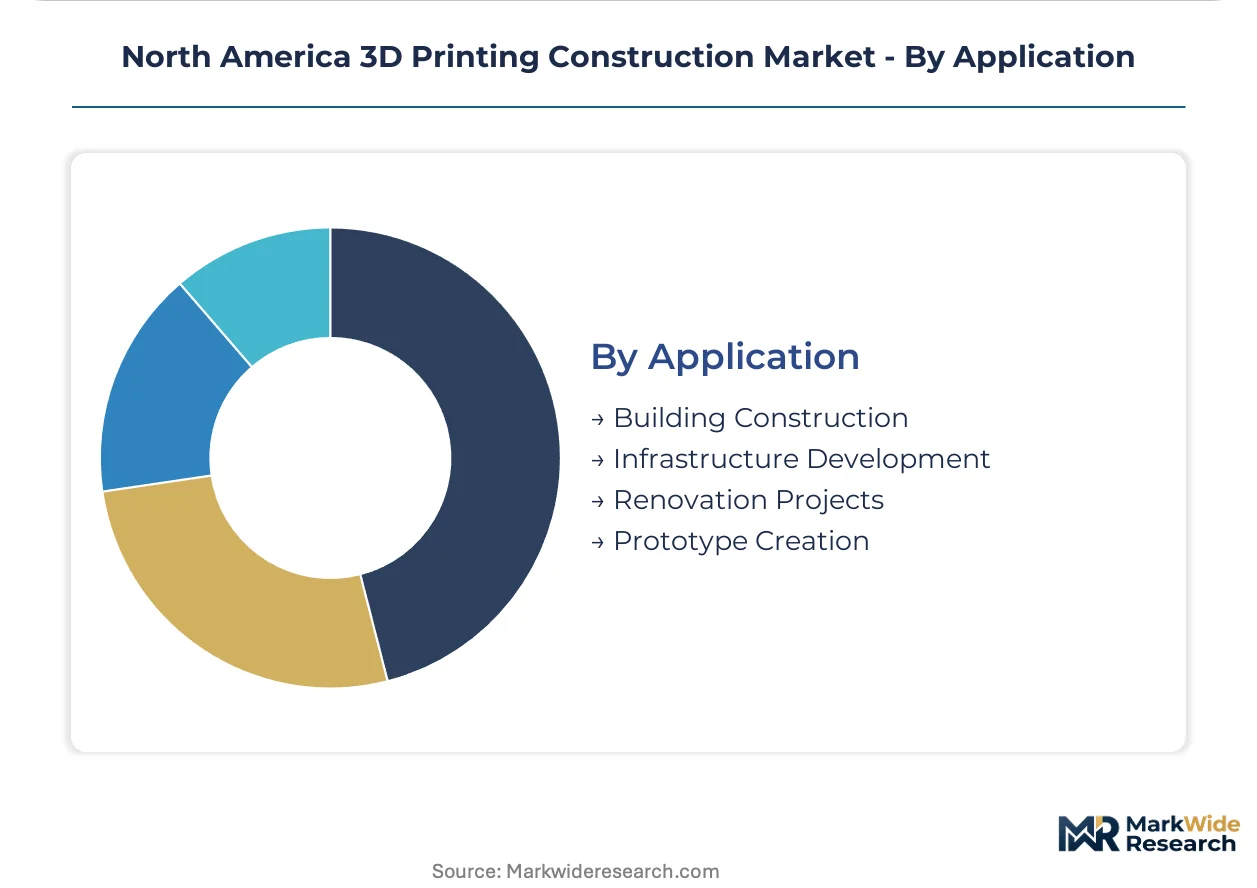
Application:
Structural versus non-structural use cases determine code compliance burden and revenue recognition timing.
- Building Construction:Structural walls, floor plates, and roof elements produced through on-site or near-site deposition constitute the core revenue application. International Code Council Appendix AW adoption standardizes structural validation protocols across US jurisdictions for this segment.
- Infrastructure Development:Bridge components, culvert sections, and transportation-related structures represent unpenetrated demand pools with standardized agency specifications. State departments of transportation pilot additive methods for accelerated project delivery in rural corridor improvements.
- Renovation Projects:Envelope retrofits, facade replacements, and structural reinforcements utilize additive deposition for geometric customization and minimal disruption to occupied facilities. Northern US markets with shorter construction seasons favor factory-based panel production for this application.
- Prototype Creation:Architectural scale models, design validation structures, and temporary installations enable risk reduction before full-scale construction commitment. Design-build contractors in California's Central Valley leverage prototype workflows for agricultural-to-residential land conversion projects.
Dominant revenue share: Building Construction. Gaining share fastest: Infrastructure Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for printed wall systems concentrates in southwestern US states with acute housing shortages and permissive building codes. Texas and California municipalities direct public procurement toward rapid-deployment concrete construction. Federal code harmonization accelerates permitting clarity across state lines.
United States
Texas and California residential builders scale concrete-based printed wall systems for speed-to-occupancy metrics. The US Department of Housing and Urban Development's building code harmonization for additive manufacturing reduces regulatory friction for federally funded affordable housing projects. Dallas-Fort Worth design-build contractors consolidate procurement authority over material selection and deposition parameters in this cluster.
Canada
Factory-based panel production gains traction in Ontario and Quebec to decouple output from weather-constrained construction seasons. Health Canada coordinates material characterization protocols that influence provincial building code adoption for printed structures. Toronto-area developers pilot controlled-environment manufacturing for envelope components targeting renovation applications.
Mexico
Northern border states attract cross-border equipment deployment from US contractors seeking lower labor cost structures for gantry system operation. The country's national housing authority evaluates international code frameworks for potential adoption in federally subsidized residential programs. Nuevo León industrial zones host pilot projects for equipment housing and process infrastructure using imported deposition systems.
North America 3D Printing Construction Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware suppliers align with regional contractors to secure distribution channels. The vendor base clusters around three archetypes: proprietary material developers with captive printing systems, European hardware manufacturers licensing through local distributors, and factory-based panel producers with controlled-environment capabilities. Technology licensing agreements and capacity expansion into southwestern US markets represent the primary competitive vectors reshaping positioning.
Within the proprietary material tier, ICON Technology Inc. and Mighty Buildings occupy distinct positions—one anchoring on-site residential deposition, the other exemplifying factory-based panel production with waste-minimization workflows. COBOD International represents the European hardware-licensing archetype, extending gantry system distribution through regional contractor partnerships. These three entities collectively illustrate the strategic divergence between site-based execution and controlled-environment manufacturing models competing for residential builder procurement authority.
| Leading Market Players |
|---|
| ICON Technology Inc. |
| Apis Cor |
| COBOD International |
| Mighty Buildings |
| Skanska AB |
| Contour Crafting Corporation |
| Branch Technology |
| Sika AG |
| CyBe Construction |
| Others |
Value Network & Pricing Analysis
Captive material formulation anchors supply positioning and pricing power for North American additive construction vendors. ICON Technology Inc.'s proprietary Lavacrete development and Mighty Buildings' factory-controlled polymer blends demonstrate how upstream integration into feedstock design compresses cost variability while commanding premium positioning against commodity-ready-mix competitors.
Pricing Analysis
Volume concentration in government-funded affordable housing projects compresses margins, while factory-based panel production captures premium pricing through waste-minimization guarantees. Price differentiation rests on certification tier—International Code Council Appendix AW compliance versus project-specific engineering validation—and geographic delivery cost to southwestern US job sites. Cost compression in cementitious feedstock tiers intensifies because Portland cement price volatility transmits directly through Lavacrete formulations. Residential builders in Texas and California exhibit highest price sensitivity, whereas commercial developers in Dallas-Fort Worth prioritize speed-to-occupancy over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for gantry and robotic arm hardware mandate multi-supplier qualification across European-origin manufacturers and emerging US distributors. Geographic supply concentration centers on Denmark for COBOD International gantry systems, Texas for ICON's captive Lavacrete production, and California for Mighty Buildings' factory panel output. Raw material dependencies include Portland cement, proprietary polymer admixtures, and steel reinforcement bar. Single-source vulnerability in European hardware imports creates lead-time exposure for US contractors. Distribution runs through design-build contractor consolidation in Texas and California, with channel control shifting toward integrated firms with captive printing capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race. Players are pursuing captive control over material rheology and deposition parameters to compress subcontractor tiers and defend margin position.
For Market Incumbents: Cement distribution partnerships in Texas and California to lock ready-mix supply chains ahead of competitor capacity expansion. Secure International Code Council Appendix AW pre-certification for proprietary material formulations before municipal adoption spreads. The threat of European hardware licensors establishing direct US sales operations demands channel control investment. Backward integration into polymer admixture production represents the priority defensive lever. For New Entrants and Emerging Players: HUD code harmonization for additive manufacturing in the United States opens a window for specialized structural engineering certification services. Target the infrastructure development segment—bridge components and culvert sections—where Department of Transportation pilots lack established vendor relationships. Factory-based panel production for northern US markets with weather-constrained construction seasons offers penetrable white space. A go-to-market angle through design-build contractor partnerships bypasses traditional general contractor procurement barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by construction materials conglomerates seeking additive manufacturing capability. Long-term viability hinges on regulatory clarity velocity across municipal jurisdictions rather than technology differentiation alone. Acquisition target archetype: factory-based panel producers with Health Canada or OSHA additive manufacturing protocols already secured. The signal to watch is International Code Council adoption timelines in secondary US markets beyond Texas and California.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Material Formulation Development | Proprietary Lavacrete blends lock supply chains and compress competitor access to HUD-funded projects. |
| Factory-Based Panel Production Scale-Up | Controlled-environment manufacturing opens northern US markets with shorter construction seasons. |
| International Code Council Certification Investment | Appendix AW pre-qualification accelerates municipal permitting and construction financing access. |
| Department of Transportation Pilot Partnership | Bridge component and culvert specifications create unpenetrated demand pools with agency backing. |
| Design-Build Contractor Integration | Consolidating procurement authority over deposition parameters compresses subcontractor tiers. |
Research Methodology
International Code Council regulatory filings, HUD building code documentation, and SEC disclosures from publicly traded construction technology firms formed the secondary backbone. Primary interviews with additive construction project managers, structural engineers with Appendix AW certification, ready-mix concrete procurement leads, and municipal building department officials validated demand assumptions. Bottom-up project pipeline analysis across Texas, California, Arizona, and New Mexico triangulated against top-down materials consumption estimates from cement industry associations.
Historical trendline analysis of permitting velocity and code adoption timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology-material pairings, end-user procurement authority, and application structural requirements. CAGRs were derived from installed capacity buildout assumptions and material extrusion system deployment rates. Industry-specific forecast inputs incorporated Portland cement price volatility coefficients and International Code Council jurisdictional adoption curves.
The model assumes a particular technology adoption path; alternative pathways for multi-material deposition integrating insulation and conduit layers would alter the outlook. Forecasts reflect material extrusion dominance assumptions and HUD code harmonization velocity. Deviation in European hardware import tariffs or OSHA additive manufacturing protocol timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home Gateways Market
Others
Disposable Non Woven Sponge Market
Others
Bird Food Market
Others
Molecular Spectroscopy Market
Others
Middle East and Africa Surface Analysis Market
Others
DNA Data Storage Market
Others
Coconut Activated Carbon Market
Others
Mainframe Market
Others
Digital Signage Media Player Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Finished Leather Market
Others
Duty Free Retail Market
Others
Global Phablets and Superphones Market
Others
UK Automotive LED Lighting Market
Others
Wearable AI Market
Others
Solar Animal Repeller Market