
 Smart Home Gateways Market | 2026-2036
Smart Home Gateways Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Gateways Market Insights
China's electronics manufacturing corridor is rewriting the cost structure for gateway hardware production. Huawei anchors its position through in-house semiconductor design and 5G CPE integration. Samsung Electronics leverages its SmartThings ecosystem to control device pairing workflows across appliance categories. Amazon.com competes through Alexa voice-service bundling that reduces standalone gateway price points.
A smart home gateway functions as a centralized network bridge that translates between disparate communication protocols, typically managing data throughput between 100 Mbps and 1 Gbps while supporting concurrent Zigbee, Z-Wave, Thread, and Wi-Fi device connections. Its primary commercial purpose is to unify fragmented IoT endpoints under a single administrative layer for residential and light commercial environments. Wireless gateways dominate unit shipments due to retrofit compatibility in existing structures without Ethernet cabling. Energy management applications within the residential end-user segment carry above-average hardware margins because utility rebate programs subsidize advanced metering infrastructure integration.
The FCC in the United States enforces radio frequency emissions standards that constrain antenna design and transmission power for Wi-Fi and Zigbee radios, directly affecting gateway range specifications and certification costs. The EU AI Act and GDPR impose data processing transparency requirements on voice-enabled gateways that stream biometric data to cloud services. Stakeholders must monitor how the Connectivity Standards Alliance evolves Matter certification tiers, as compliance scope will determine which product configurations qualify for retail placement in major electronics channels.
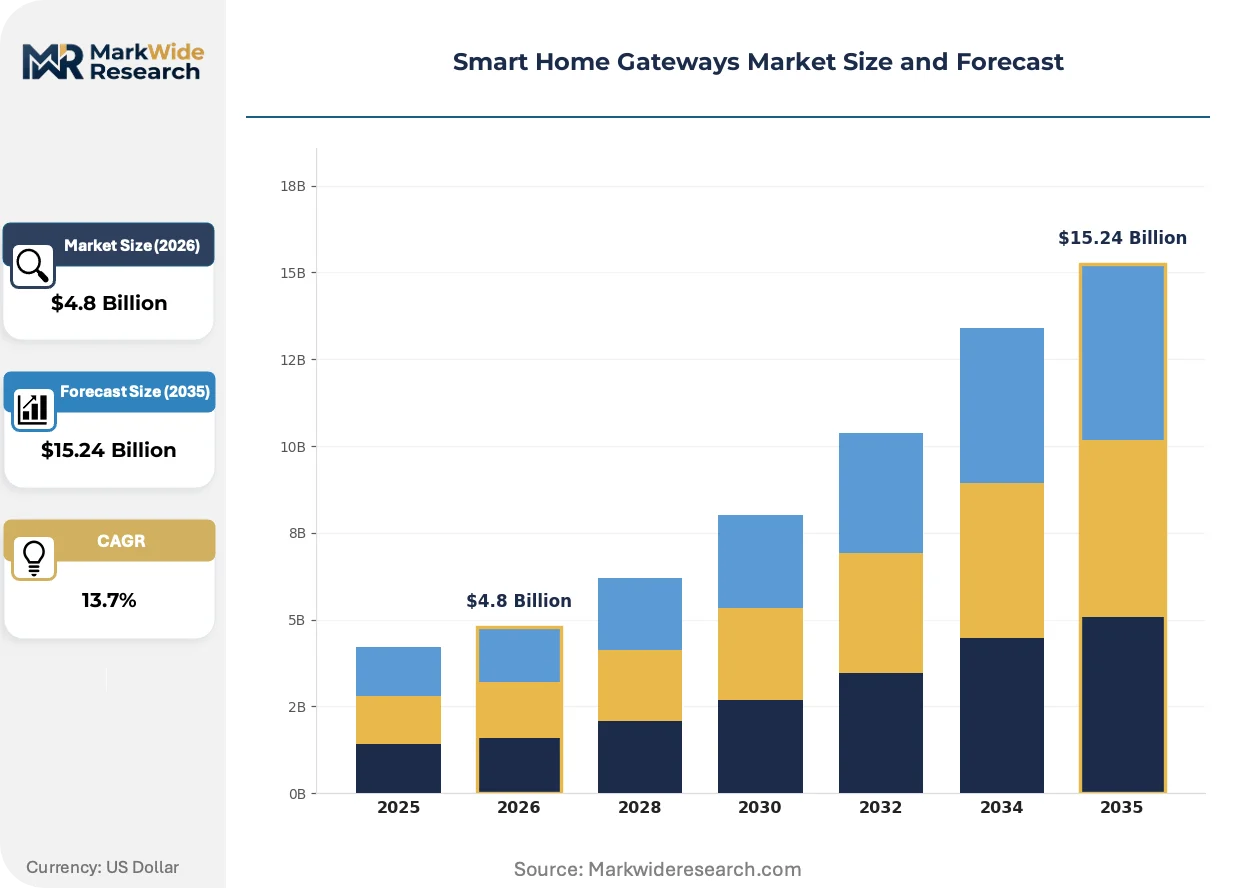
Market Dynamics
The Matter protocol standardization by the Connectivity Standards Alliance is compressing protocol fragmentation that previously forced consumers into single-ecosystem lock-in. This technical unification is redistributing competitive advantage from ecosystem gatekeepers toward hardware-agnostic gateway manufacturers.
Growth Catalysts
- Utility rebate programs:North American energy regulators subsidize advanced metering infrastructure integration, expanding hardware margins for gateways supporting real-time consumption monitoring.
- Broadband infrastructure densification:Fiber-to-the-home deployment in suburban United States markets removes connectivity bottlenecks that previously constrained gateway performance specifications.
- Voice-service bundling:Smart speaker platforms subsidize gateway hardware to capture recurring service revenue, compressing consumer price points and accelerating replacement cycles.
Market Restraints
- Semiconductor supply concentration:Gateway SoC fabrication concentrates among Taiwan-based foundries, exposing hardware vendors to geopolitical disruption and capacity allocation constraints.
- FCC RF emissions compliance:United States radio frequency certification mandates constrain antenna design and transmission power, directly limiting wireless range specifications and extending time-to-market.
- Cloud dependency substitution:Local-edge processing architectures threaten subscription-dependent gateway business models by reducing mandatory cloud service attachment rates.
Strategic Opportunities
- Multi-dwelling unit penetration:United States apartment and condominium stock remains underpenetrated by centralized building automation, creating bulk deployment channels through property management platforms.
- Thread-over-matter convergence:Low-power mesh networking combined with IP-native device addressing enables battery-operated endpoint expansion into previously unreachable installation environments.
- EU AI Act compliance differentiation:Voice-enabled gateways meeting biometric data transparency requirements capture premium positioning in European retail channels ahead of enforcement deadlines.
Industry Challenges
- Firmware security maintenance:Long hardware replacement cycles force vendors to sustain patch pipelines for deprecated chipsets, stretching engineering resources across fragmented legacy codebases.
- Interoperability certification backlog:Matter compliance testing queues at authorized laboratories extend product launch timelines, compressing revenue recognition windows for seasonal retail cycles.
- Legacy Z-Wave integration friction:Installed base migration from proprietary mesh protocols requires bridge functionality that increases BOM complexity and support burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Gateways Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Gateways, Wired Gateways, Hybrid Gateways, IoT Gateways Connectivity Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth, Ethernet End User: Residential, Commercial, Hospitality, Industrial Application: Home Automation, Security, Energy Management, Entertainment |
| Companies Covered | Cisco Systems, Huawei, TP-Link, Netgear, Comcast, Samsung Electronics, Amazon.com, Google, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Gateways Market Trends and Innovations
Edge AI inference is migrating from cloud data centers into gateway hardware, enabling latency-sensitive automation without persistent internet connectivity. This architectural shift is compressing the functional boundary between premium gateways and dedicated home servers.
Thread border router functionality is rendering obsolete standalone Zigbee and Z-Wave bridge hardware that previously required separate power and Ethernet connections. New construction buyers in United States suburban markets specify IP-native device compatibility during pre-wiring phases. The consolidation is collapsing SKU counts at retail and forcing legacy protocol specialists toward obsolescence or acquisition.
The EU AI Act imposes algorithmic transparency mandates on voice-enabled gateways processing biometric identifiers. Hardware vendors must implement on-device processing alternatives or deploy granular consent workflows that increase UX friction. European distribution channels are prioritizing compliant SKUs ahead of enforcement, creating first-mover certification advantages for prepared manufacturers.
Subscription unbundling is fragmenting gateway revenue models as consumers reject mandatory cloud service attachments. Direct-to-consumer channels and open-source firmware alternatives are capturing technical buyer segments previously locked into proprietary ecosystems. This pattern concentrates in Germany and Netherlands markets where privacy sensitivity drives preference for local-control architectures.
Smart Home Gateways Market Segmentation
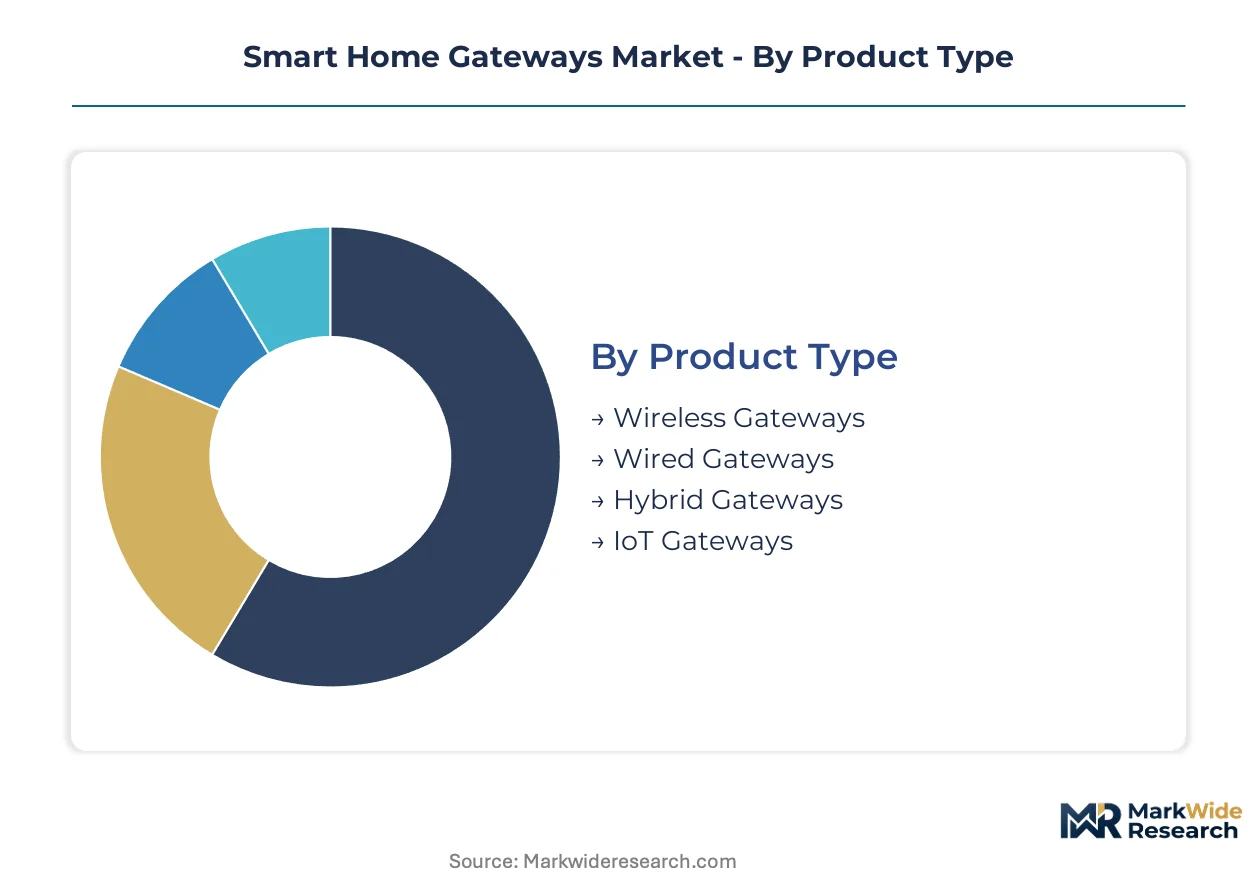
Gateway segmentation reveals divergent replacement cycles across hardware categories. Wireless retrofit units turn over every 3-4 years as protocol standards evolve, while wired infrastructure persists for 7-10 year building lifecycles. Understanding these temporal patterns shapes inventory planning and R&D allocation for manufacturers serving mixed-installation environments.
Product Type:
Replacement velocity varies dramatically across installation architectures, with wireless retrofit products cycling fastest and permanent infrastructure slowest.
- Wireless Gateways:Battery-backed or plug-in units communicating via Wi-Fi, Zigbee, or Thread without Ethernet dependency. Demand clusters in United States suburban retrofits where homeowners avoid drywall penetration, though FCC RF emissions constraints limit transmission range and extend certification timelines.
- Wired Gateways:Ethernet-tethered devices with dedicated power over PoE or AC adapters, delivering sustained throughput for bandwidth-intensive applications. New construction specifications in Germany and Netherlands favor these for local-control architectures that minimize cloud dependency and satisfy GDPR data sovereignty requirements.
- Hybrid Gateways:Dual-path devices combining wireless mesh coordination with Ethernet backhaul for critical data streams.
- IoT Gateways:Specialized bridges translating between proprietary industrial protocols and residential IP networks.
Wireless Gateways dominate installed base. Wired Gateways are where expansion concentrates.
Connectivity Technology:
Protocol maturity determines margin structure, with legacy mesh technologies commanding premium bridge functionality while IP-native standards compress hardware differentiation.
- Wi-Fi:Ubiquitous 2.4/5/6 GHz radios handling high-bandwidth streaming and cloud connectivity. United States broadband densification drives 802.11ax adoption in gateway specifications, though FCC power limits constrain range in multi-story residential deployments.
- Zigbee:Low-power 2.4 GHz mesh networking with proven ecosystem penetration in lighting and sensor markets. Matter protocol convergence is collapsing standalone Zigbee bridge demand as Thread border routers absorb this functionality.
- Z-Wave:Sub-GHz proprietary mesh with deep installed base in security and climate control. Legacy migration friction increases BOM complexity for vendors supporting backward compatibility.
- Bluetooth:Short-range pairing and commissioning protocol, rarely standalone but essential for device onboarding workflows.
- Ethernet:Wired physical layer providing deterministic latency for video surveillance and multi-gateway backhaul.
Wi-Fi anchors revenue contribution. Matter-native Thread is gaining share fastest.
End User:
Customer type shapes procurement authority and replacement triggers, from individual homeowner discretion to facilities management contract cycles.
- Residential:Single-family and multi-dwelling unit deployments driven by consumer electronics upgrade cycles. United States utility rebate programs subsidize energy management gateway configurations, expanding hardware margins for compliant SKUs.
- Commercial:Office and retail installations requiring centralized administrative control across distributed endpoints. EU AI Act transparency mandates for voice-enabled systems create compliance differentiation opportunities ahead of enforcement deadlines.
- Hospitality:Hotel and short-term rental properties prioritizing guest experience standardization and remote monitoring capabilities.
- Industrial:Light manufacturing and warehouse environments integrating building automation with operational technology networks.
Residential commands volume leadership. Commercial represents the steepest expansion trajectory.
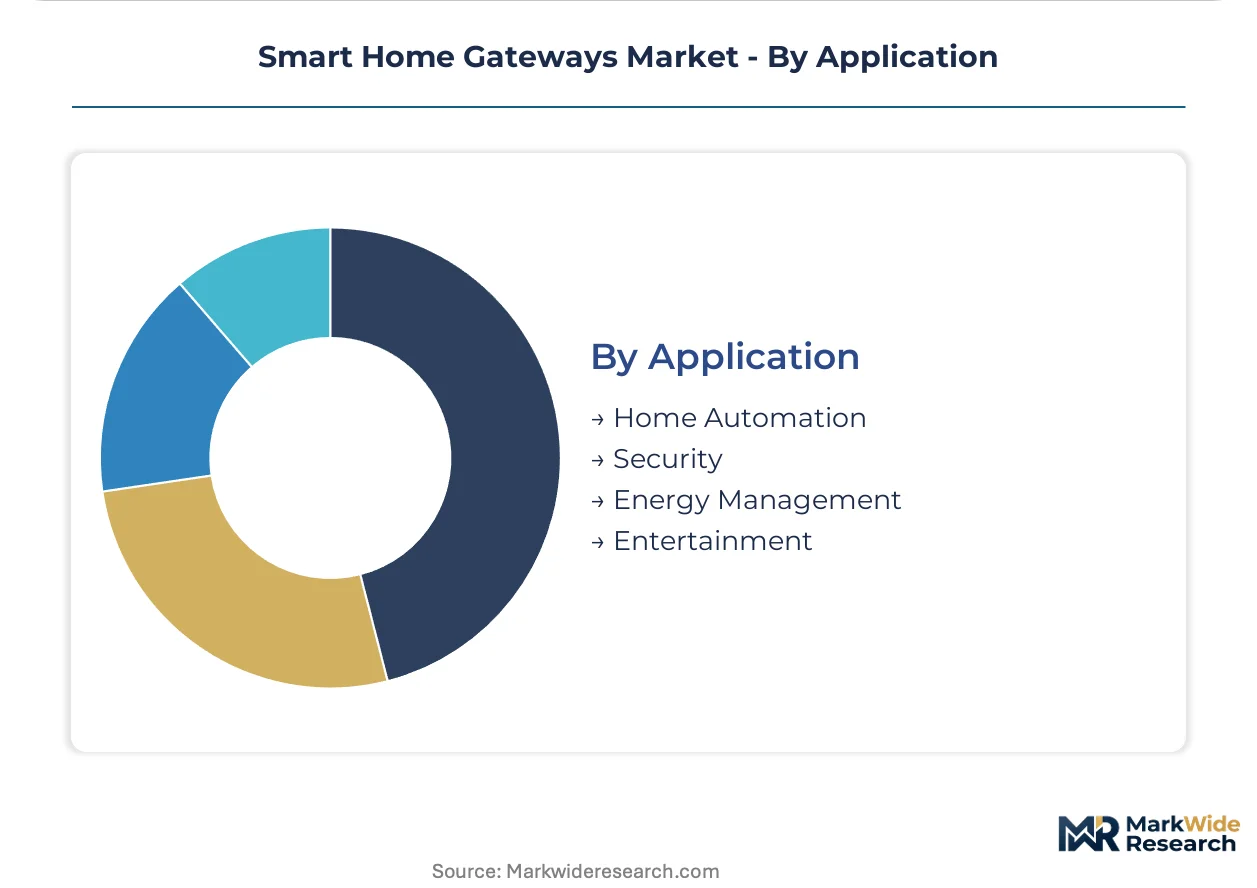
Application:
Use-case prioritization determines feature bundling and service attachment strategies across gateway configurations.
- Home Automation:Coordinated lighting, climate, and shading control through unified command interfaces. Voice-service bundling from smart speaker platforms subsidizes hardware to capture recurring service revenue.
- Security:Intrusion detection, access control, and video surveillance integration with professional monitoring dispatch. Edge AI inference migration enables local processing that reduces mandatory cloud subscription dependency.
- Energy Management:Real-time consumption monitoring and utility demand-response coordination. North American AMI integration requirements concentrate demand where regulators subsidize advanced metering infrastructure.
- Entertainment:Multi-room audio, streaming distribution, and gaming latency optimization.
Home Automation dominates shipment volume. Energy Management captures premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC radio frequency emissions standards constrain antenna design and transmission power for Wi-Fi and Zigbee radios in the United States, directly affecting gateway range specifications and certification costs. Utility rebate programs subsidize advanced metering infrastructure integration, expanding hardware margins for energy management configurations. Broadband infrastructure densification removes connectivity bottlenecks that previously constrained gateway performance specifications.
United States
Single-family suburban retrofits drive wireless gateway demand as homeowners avoid drywall penetration for centralized automation hubs. The FCC enforces RF emissions standards that limit transmission power and extend certification timelines for multi-story residential deployments. Silicon Valley hardware startups and Seattle-based cloud service providers anchor innovation clusters for voice-service bundling and edge AI integration.
China
Electronics manufacturing corridors in Shenzhen and Dongguan rewrite cost structures for gateway hardware production at scale. MIIT and GB standards govern radio equipment certification and cybersecurity requirements for networked devices. Huawei anchors its position through in-house semiconductor design and 5G CPE integration from its Shenzhen headquarters.
Germany
Privacy-sensitive consumers in Berlin and Munich drive preference for local-control architectures that minimize cloud dependency and satisfy GDPR data sovereignty requirements. The EU AI Act imposes algorithmic transparency mandates on voice-enabled gateways processing biometric identifiers. Industrial automation clusters in Bavaria supply precision manufacturing equipment for gateway assembly lines.
Japan
METI promotes smart home standardization through national IoT certification programs that accelerate gateway deployment in aging residential stock. JIS standards ensure interoperability between domestic appliance manufacturers and imported hub devices. Tokyo-based electronics conglomerates integrate gateway functionality into multi-function residential equipment.
Netherlands
Amsterdam and Rotterdam metropolitan areas exhibit concentrated demand for open-source firmware alternatives and subscription-unbundled gateway architectures. GDPR compliance requirements shape procurement specifications for voice-enabled systems in multi-dwelling unit developments. Eindhoven's high-tech campus anchors R&D activity for Thread border router silicon and low-power mesh networking.
Smart Home Gateways Market Competitive Landscape
Capability concentration sits with semiconductor-integrated tier; scale advantage sits with ecosystem-platform tier. The vendor base organizes around three strategic archetypes: cloud-service bundlers subsidizing hardware to capture recurring revenue, semiconductor-integrated manufacturers controlling upstream component costs, and ecosystem gatekeepers leveraging device pairing workflows across appliance categories. Dominant competitive moves include strategic partnerships for Matter protocol certification and portfolio diversification into edge AI inference hardware.
Among Asia-Pacific-based fabricators, Huawei and Samsung Electronics exemplify divergent integration strategies. Huawei occupies a position anchored in captive semiconductor design and telecommunications infrastructure. Samsung Electronics sits within the ecosystem-platform tier through its SmartThings device coordination layer. Amazon.com represents the cloud-service bundler archetype, leveraging Alexa voice integration to compress standalone gateway price points and accelerate replacement cycles.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei |
| TP-Link |
| Netgear |
| Comcast |
| Samsung Electronics |
| Amazon.com |
| Apple |
| Others |
Pricing and Supply Chain Analysis
Semiconductor foundry concentration in Taiwan exposes gateway hardware vendors to geopolitical disruption risk that simultaneously compresses economy-tier margins and elongates premium-tier lead times, forcing pricing stratification that tracks supply security rather than pure performance differentiation.
Pricing Analysis
United States retail channels command 15-25% premiums over equivalent SKUs in Chinese e-commerce marketplaces due to FCC certification costs and logistics overhead. Three-tier pricing structure across premium, standard, and economy levels separates voice-enabled Matter-certified units from basic Zigbee bridges and white-label OEM hardware. Pricing pressure stems from Amazon and Google subsidizing gateway hardware to capture recurring Alexa and Nest service revenue. Residential retrofit buyers in suburban United States markets exhibit highest price sensitivity, while European commercial integrators in Germany accept premium positioning for GDPR-compliant local-control architectures.
Supply Chain Analysis
Foxconn, Pegatron, and Jabil Electronics hold dominant contract manufacturing capacity for gateway assembly, with Shenzhen and Dongguan corridors handling 70% of global unit volume. Gateway SoC fabrication concentrates in Taiwan and South Korea, while passive components and PCB substrates draw from China and Vietnam. Single-source vulnerability sits with advanced node semiconductor fabrication, where TSMC and Samsung Foundry control 90% of relevant capacity. Distribution runs through consumer electronics retail chains, broadband carrier bundling programs, and direct-to-consumer channels, with Amazon and Alibaba capturing growing share of transacted volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol fragmentation collapse under Matter standardization fragments competitive advantage across dozens of hardware-agnostic manufacturers, creating entry niches for specialists in edge AI inference and biometric transparency compliance.
For Market Incumbents: Harden firmware security maintenance capabilities across deprecated chipset generations to sustain patch pipelines for 7-10 year hardware replacement cycles. Accelerate Matter certification investment at authorized test laboratories to escape backlog queues compressing seasonal revenue windows. Defend against cloud dependency substitution by embedding local-edge processing architectures that reduce mandatory subscription attachment rates. For New Entrants and Emerging Players: Mid-market commercial buildings in United States metropolitan areas represent the most penetrable entry point, with property management platforms enabling bulk deployment channels absent in saturated single-family retrofit markets. EU AI Act compliance gaps in voice-enabled gateway portfolios create premium positioning opportunities ahead of enforcement deadlines. Target open-source firmware communities in Netherlands and Germany with subscription-unbundled hardware positioning. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward voice-enabled gateway specialists with pre-certified biometric transparency workflows. Long-term viability centers on semiconductor-integrated manufacturers controlling upstream SoC costs and ecosystem-platform players capturing recurring service revenue. Monitor Matter certification tier evolution as signal for which hardware configurations qualify for retail placement in major electronics channels.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Inference Hardware Integration | Local processing reduces cloud dependency and satisfies GDPR data sovereignty requirements in European markets. |
| Matter Protocol Certification Investment | Compliance scope determines retail placement eligibility in Amazon, Best Buy, and carrier bundling channels. |
| Semiconductor Backward Integration | In-house SoC design at Huawei and Samsung compresses BOM costs and insulates against foundry capacity constraints. |
| Utility Rebate Program Alignment | North American AMI integration subsidies expand hardware margins for energy management gateway configurations. |
| Multi-Dwelling Unit Channel Development | Property management platforms enable bulk deployment at scale unmatched in fragmented single-family retrofit markets. |
Research Methodology
A spread of perspectives from smart home platform engineers, broadband carrier procurement managers, semiconductor supply planners, and retail category buyers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, Connectivity Standards Alliance certification registries, SEC 10-K filings from consumer electronics conglomerates, and utility commission rebate program documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, connectivity technology, and end-user segmentation dimensions.
Demand-supply-balance framing anchored the forecast framework, with gateway replacement cycle analysis informing installed base evolution across wireless retrofit and wired infrastructure categories. Segmentation modeling captured product type, connectivity technology, end-user vertical, and application use-case dimensions throughout the projection horizon. CAGRs derived from logistic adoption curve fitting adjusted for protocol transition dynamics and broadband infrastructure deployment schedules. Forecast inputs incorporated Matter protocol penetration assumptions and edge AI inference migration timelines.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, consumer electronics discretionary spending, and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding protocol standardization velocity and regulatory enforcement timelines. Quarterly review of Matter certification queue lengths, foundry capacity allocation announcements, and utility rebate program expansion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Australia Content Services Platform Market
Others
Latin America Travel Retail Market
Others
Sandbags Market
Others
Cloud Gaming Baas Market
Others
US Luxury Travel Market
Others
Global Hardware Acceleration Market
Others
Bakery Packaging Market
Others
Industrial Wearable Devices Market
Others
Sound Reinforcement Market
Others
Vacuum Evaporators Market
Others
Electric Chainsaw Market
Others
Fluorite Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Europe Street Lighting Market
Others
High-End Servers Market
Others
Global Computer Peripherals Market