
 Mini Pcs Market | 2026-2036
Mini Pcs Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Pcs Market Analysis
Enterprise procurement is collapsing toward SMEs and educational institutions as primary volume buyers. ASUS leverages its motherboard heritage to control component sourcing for compact builds. Intel sustains architecture leadership through NUC reference designs that anchor premium segments. MINISFORUM specializes in barebone configurations that occupy price-sensitive channels across Asia and Europe.
Mini PCs are self-contained computing devices built around integrated processors with thermal envelopes typically below 65 watts, designed for desktop replacement in space-constrained environments. These systems employ soldered memory and solid-state storage to achieve footprints under one liter while maintaining full Windows or Linux compatibility. NUC-format units lead in commercial deployments due to standardized mounting and enterprise manageability, while ARM Architecture variants represent the fastest-expanding technology tier as Qualcomm and Apple silicon demonstrate competitive performance per watt. Stick PCs remain a mature, low-margin category concentrated in digital signage and kiosk applications where compute requirements are minimal.
The EPA Energy Star program and EU Ecodesign Directive set mandatory standby power limits and efficiency benchmarks that determine market access for imported units. FCC Part 15 emissions compliance in the United States and CE marking under the Radio Equipment Directive in Europe add certification layers that favor established manufacturers with dedicated regulatory teams. Stakeholders must monitor how USB4 and Thunderbolt licensing costs reshape bill-of-materials structures as connectivity standards converge.
Market Dynamics
Enterprise IT refresh cycles are compressing replacement timelines for desktop infrastructure while EU Ecodesign Directive power thresholds are disqualifying legacy designs from import channels.
Growth Catalysts
- Industrial edge computing:Factory automation in Germany demands space-optimized compute nodes for real-time process control. German automotive suppliers are standardizing on NUC-format units for production line monitoring.
- REACH compliance:RoHS substance restrictions under European chemical frameworks are accelerating redesigns toward lead-free solder and halogen-free substrates that reduce thermal mass.
- Thunderbolt licensing:Intel's royalty-free USB4 integration is collapsing peripheral connectivity costs for compact workstation builds targeting creative professionals.
Market Restraints
- Memory supply concentration:DDR5 module sourcing clusters in Korean and Taiwanese foundries, exposing assemblers to allocation volatility during semiconductor cycle troughs.
- ARM software compatibility:Windows-on-ARM emulation overhead persists for legacy x86 business applications, limiting enterprise migration confidence.
- FCC Part 15 certification:Electromagnetic emissions testing for compact metal enclosures adds six-to-eight week lead times for new product introductions in the United States.
Strategic Opportunities
- Educational procurement:K-12 districts in the United States are consolidating device purchases toward standardized mini PC fleets with centralized management.
- Digital signage retrofit:HDMI 2.1 and AV-over-IP convergence is enabling 8K playback from sub-500ml chassis in retail and hospitality deployments.
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting assembly investments for price-optimized units targeting South Asian SME channels.
Industry Challenges
- Thermal engineering talent:Vapor chamber and heat-pipe design expertise concentrates in Taiwanese ODMs, constraining in-house thermal innovation at Western brands.
- Legacy port retention:Enterprise buyers demand RS-232 and VGA compatibility that conflicts with space-constrained modern I/O configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Pcs Market |
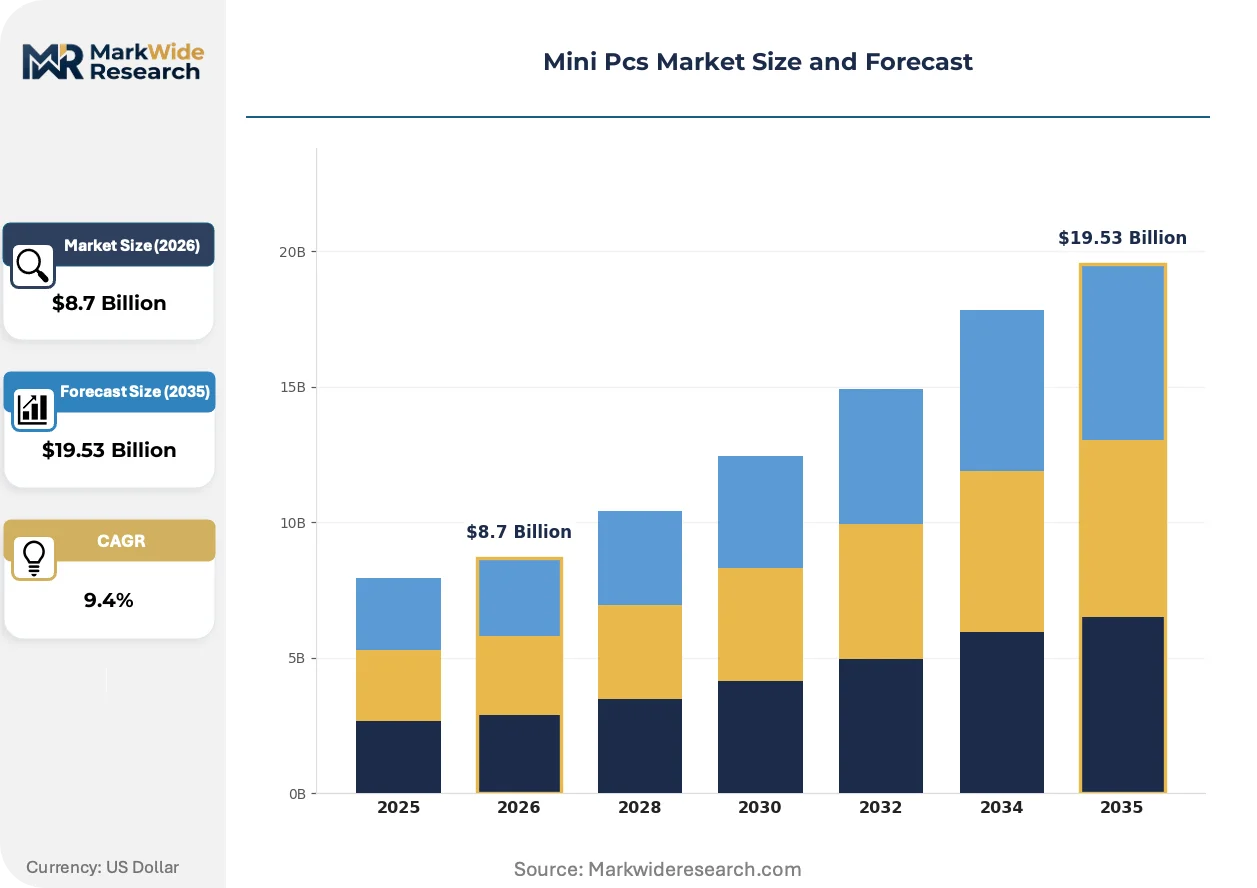
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barebone, NUC, Stick PCs, Compact PCs End User: Home Users, SMEs, Enterprises, Educational Institutions Technology: Intel Processors, AMD Processors, ARM Architecture, Cloud-Based Form Factor: Box PCs, Stick Form, Mini Tower, Embedded |
| Companies Covered | Apple, Intel, ASUS, HP, Dell, Lenovo, MINISFORUM, Beelink, Geekom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Pcs Market Emerging Trajectories
Active cooling architectures are giving way to fanless designs as thermal interface materials improve, while regulatory pressure on standby power is forcing fundamental circuit redesigns.
Chiplet-based processors are miniaturizing compute density without proportional thermal envelope expansion. Industrial automation buyers in Germany are adopting these packages for cabinet-mounted controllers. The shift is compressing motherboard real estate requirements and enabling sub-800ml chassis volumes.
EPA Energy Star Version 8.0 specifications are mandating sub-2-watt standby consumption for small-form-factor computers. Taiwanese ODMs are redesigning power delivery subsystems to maintain certification eligibility. Commercial channels in the United States are filtering procurement lists to Energy Star-qualified SKUs exclusively.
Volume purchasing through education cooperatives is displacing individual district RFP processes. Midwest United States buying consortia are aggregating demand across hundreds of schools. This consolidation is favoring standardized configurations over customized builds.
Mini Pcs Market Segmentation
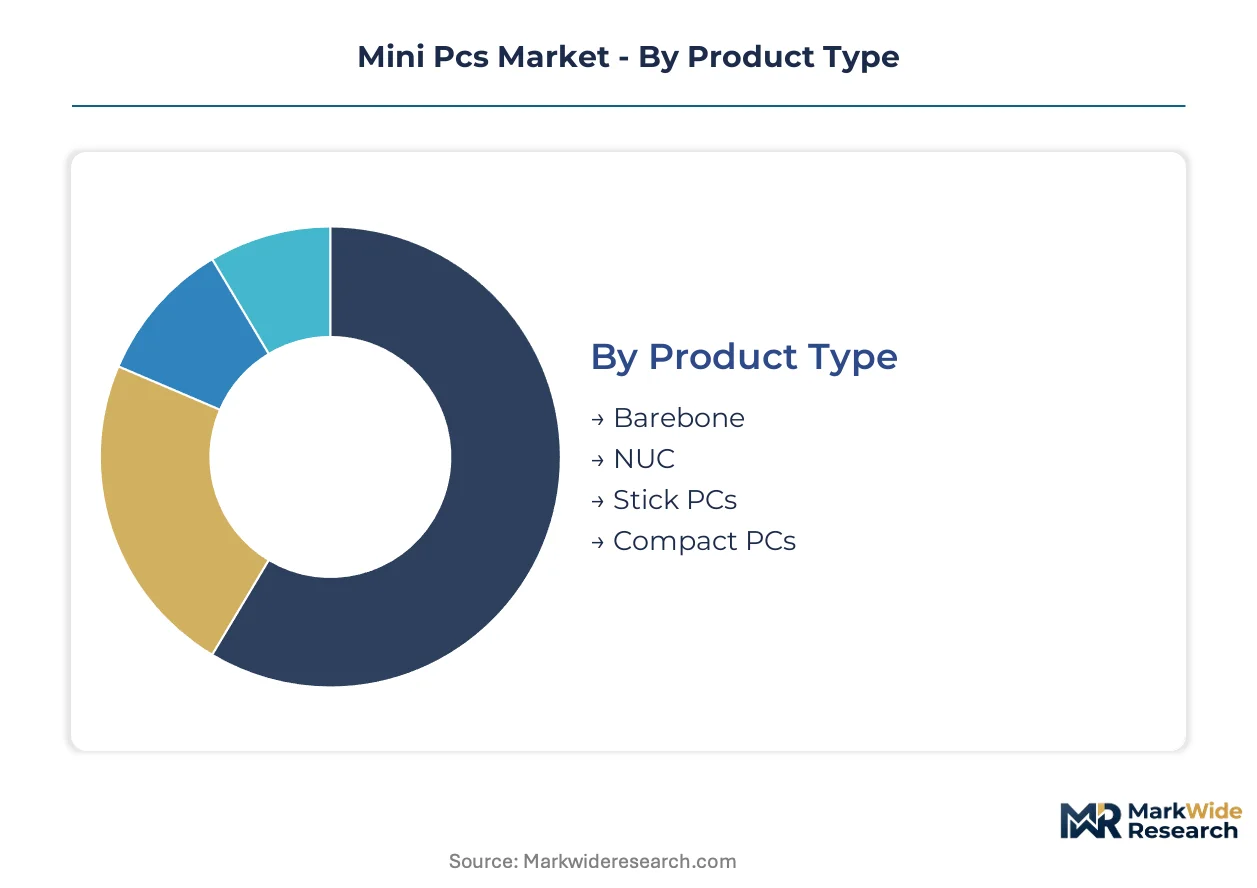
Mini PC procurement patterns diverge sharply across deployment contexts, with enterprise manageability requirements clashing against consumer price sensitivity. Component integration strategies and thermal engineering constraints reshape competitive positioning within each segment boundary.
Product Type:
NUC-format units face intensifying substitution pressure from compact PC alternatives as motherboard integration costs decline and ARM-based designs penetrate commercial channels.
- Barebone:Chassis and motherboard assemblies ship without processor, memory, or storage, allowing system integrators to customize configurations for regional price points. Demand clusters among European SMEs and Asian retail channels where local assembly reduces import duties. Component sourcing flexibility protects margin structures during semiconductor allocation volatility.
- NUC:Standardized small-form-factor reference designs with soldered processors and standardized mounting patterns dominate enterprise fleet deployments. German automotive suppliers and US federal agencies specify NUC units for their vPro manageability and remote administration capabilities. Intel's royalty-free USB4 integration is collapsing peripheral connectivity costs for this tier.
- Stick PCs:HDMI-integrated compute sticks serve digital signage and kiosk applications where space constraints are absolute. Media playback requirements in retail and hospitality sustain this mature category despite minimal margin contribution.
- Compact PCs:Sub-liter chassis with socketed components target creative professionals and developer workstations. Thunderbolt docking compatibility and discrete GPU options differentiate this tier from sealed NUC alternatives.
NUC retains volume leadership; Compact PCs hold the steepest expansion curve.
End User:
Procurement consolidation is reshaping volume distribution, with educational cooperatives and SME buying groups displacing individual enterprise contracts.
- Home Users:Media center and light productivity applications drive demand for silent, fanless designs with solid-state storage. European residential buyers prioritize Energy Star certification and sub-2-watt standby consumption under Ecodesign Directive thresholds.
- SMEs:Space-constrained offices and retail backrooms favor standardized fleet configurations with centralized management. German Mittelstand manufacturers deploy cabinet-mounted units for production line data collection.
- Enterprises:IT refresh cycles are compressing toward 3-4 year replacement timelines, with security-hardened vPro platforms dominating financial services and healthcare deployments. FCC Part 15 certification requirements filter procurement lists to established vendors with dedicated regulatory teams.
- Educational Institutions:K-12 districts across the US Midwest are aggregating demand through buying consortia covering hundreds of schools. Standardized mini PC fleets with ChromeOS or Windows Education editions displace customized builds.
Educational Institutions are expanding most quickly; Enterprises maintain revenue concentration.
Technology:
Architecture transitions are fragmenting software compatibility expectations, with emulation overhead creating deployment friction in legacy-dependent environments.
- Intel Processors:x86 architecture dominance persists in enterprise channels through vPro manageability and established application compatibility. NUC reference designs anchor premium pricing tiers.
- AMD Processors:Integrated Radeon graphics and competitive thermal envelopes attract creative workstation buyers. Taiwanese ODMs are expanding AMD-based barebone offerings for price-sensitive European channels.
- ARM Architecture:Qualcomm Snapdragon and Apple silicon platforms demonstrate superior performance-per-watt metrics, enabling fanless designs previously impossible with x86 thermal envelopes. Windows-on-ARM emulation limitations constrain enterprise migration confidence despite hardware advances.
- Cloud-Based:Thin-client configurations with browser-centric operating systems target call centers and task-worker environments. Indian SME channels show particular appetite for subscription-linked hardware models under PLI scheme assembly investments.
Intel Processors retain procurement preference; ARM Architecture climbs fastest on efficiency metrics.
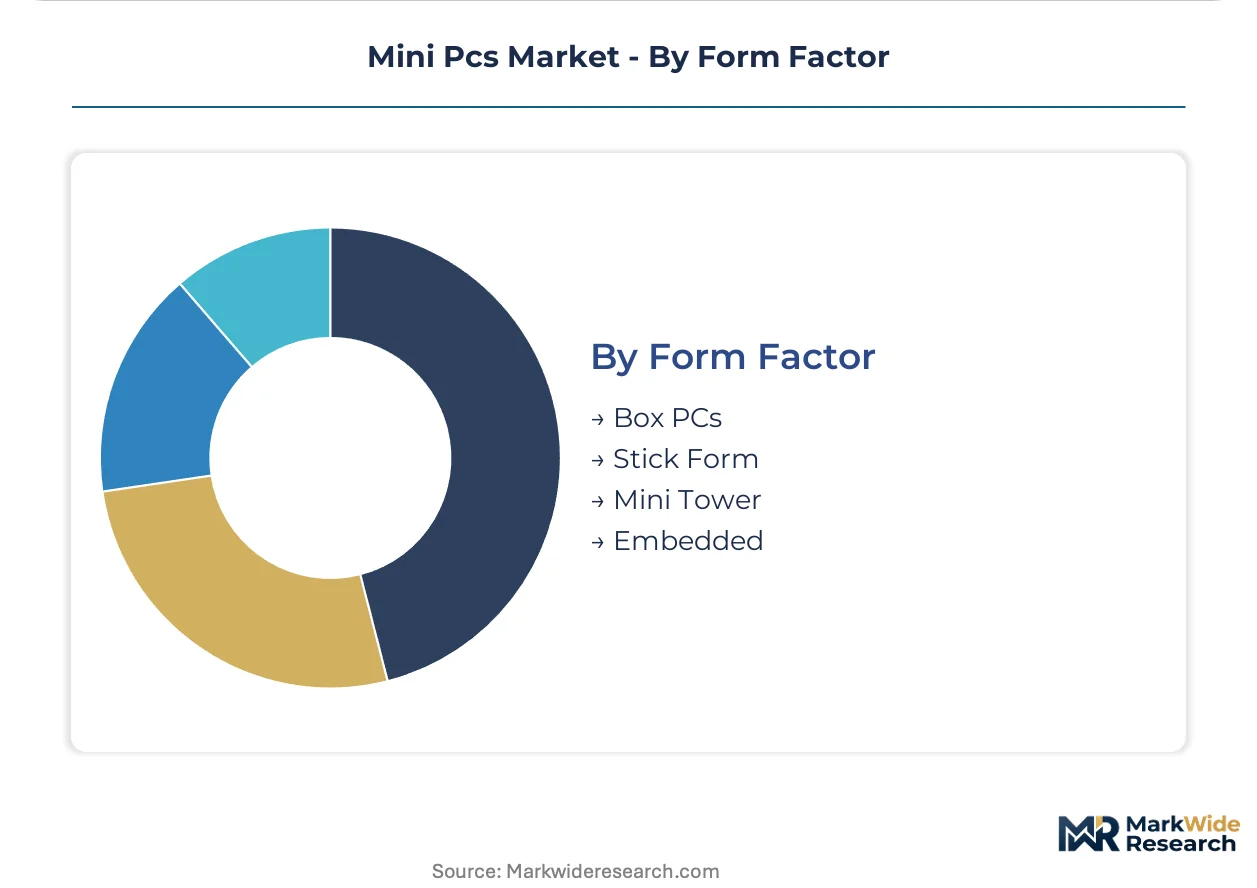
Form Factor:
Physical mounting constraints and legacy port requirements are forcing design compromises that favor established ODM thermal engineering capabilities.
- Box PCs:Rectangular chassis with standardized VESA mounting dominate commercial deployments. German industrial automation buyers specify these units for DIN rail and cabinet installations.
- Stick Form:Direct HDMI integration eliminates cable clutter for digital signage and hospitality applications. Heat dissipation limitations restrict sustained compute workloads.
- Mini Tower:Vertical orientation with expansion slots accommodates discrete GPUs and additional storage in sub-5-liter volumes. Creative professionals in North American markets favor this configuration for render workloads.
- Embedded:Fanless sealed designs with extended temperature ratings serve factory floor and outdoor deployments. REACH-compliant lead-free solder and halogen-free substrates are mandatory for EU market access.
Box PCs command shipment volumes; Embedded formats gain share on industrial edge computing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese ODMs export compact motherboard assemblies to Germany, the United States, and China, sustaining the primary trade corridor for mini PC hardware. Assembly concentration in Taoyuan and New Taipei City feeds industrial automation demand in Stuttgart and Munich, while US educational procurement channels absorb standardized NUC-format volumes.
United States
K-12 buying consortia across the Midwest aggregate demand from hundreds of districts, displacing individual RFP processes. The EPA Energy Star program mandates sub-2-watt standby consumption, filtering procurement lists to certified SKUs exclusively. Chicago-based cooperatives standardize on vPro-enabled fleets for centralized device management.
Germany
Automotive suppliers in Baden-Württemberg deploy cabinet-mounted units for production line monitoring and real-time process control. The EU Ecodesign Directive tightens power-efficiency thresholds, accelerating redesigns toward lead-free solder and halogen-free substrates. Stuttgart's Mittelstand manufacturers favor DIN rail-compatible Box PC formats for factory floor integration.
China
Domestic cloud computing expansion drives thin-client deployments in call centers and task-worker environments. MIIT standards govern electromagnetic compatibility certification for compact metal enclosures. Shenzhen hardware clusters supply barebone chassis to European SME channels, leveraging component sourcing flexibility during semiconductor allocation cycles.
India
The PLI scheme for electronics manufacturing attracts assembly investments targeting price-optimized units for South Asian SME markets. BIS certification requirements filter import channels to established vendors with dedicated regulatory compliance teams. Karnataka's Bengaluru tech corridor hosts integration facilities for subscription-linked hardware models.
Japan
Corporate IT refresh cycles compress replacement timelines for desktop infrastructure in Tokyo and Osaka metropolitan areas. METI efficiency guidelines align with international Energy Star specifications for standby power limits. Nagoya-based industrial automation buyers specify extended-temperature embedded formats for precision manufacturing environments.
Mini Pcs Market Vendor Landscape
Player mix skews toward component-integrated specialists with captive motherboard design capabilities. The vendor base clusters around three strategic tiers: silicon architects controlling reference designs, ODM-assemblers managing thermal engineering, and regional integrators customizing barebone configurations for local price points. Dominant competitive moves include Intel's royalty-free USB4 licensing collapse and Taiwanese ODM capacity expansion for fanless embedded formats.
Within the silicon-architect tier, Intel and Apple exemplify divergent strategies for premium positioning. Intel anchors enterprise channels through vPro manageability and standardized NUC reference designs. Apple occupies a parallel position with ARM-based silicon demonstrating superior performance-per-watt metrics for creative workstation segments. Among Asia-specialist assemblers, MINISFORUM represents the barebone-configuration archetype serving price-sensitive channels across European and Asian retail markets.
| Leading Market Players |
|---|
| Apple |
| Intel |
| ASUS |
| HP |
| Dell |
| Lenovo |
| MINISFORUM |
| Beelink |
| Geekom |
| Others |
Supply Flow & Price Mechanics
EPA Energy Star certification and EU Ecodesign Directive compliance simultaneously gate supply qualification and stratify price tiers across the Mini PCs Market. Vendors lacking certified power delivery subsystems face automatic disqualification from US federal and German industrial procurement channels, while certification attainment enables premium positioning against uncertified competitors.
Pricing Analysis
DDR4-to-DDR5 memory generation gaps anchor pricing stratification across premium, standard, and economy tiers. NUC-format units with soldered current-gen processors command premium positioning through vPro manageability and USB4 integration, while barebone configurations with user-installable prior-gen components occupy price-sensitive European SME channels. Certification-driven price differentiation separates Energy Star-qualified enterprise SKUs from uncertified consumer alternatives. Cost compression in ARM-based entry tiers intensifies as Qualcomm Snapdragon platforms achieve Windows compatibility parity, though emulation overhead limits enterprise penetration. Educational cooperatives exhibit highest price sensitivity through aggregated volume purchasing, whereas German automotive suppliers demonstrate lowest sensitivity due to DIN rail compatibility and extended temperature specifications.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication and DDR5 module production for compact motherboard assemblies. Taiwanese ODMs in Taoyuan and New Taipei City supply integrated chassis to German automotive suppliers and US educational channels, drawing from Korean memory foundries and domestic substrate manufacturers. Single-source vulnerability concentrates in vapor chamber thermal engineering expertise held by Taiwanese ODMs, constraining Western brands' in-house design capabilities. Distribution runs through direct enterprise fleet contracts, educational buying consortia, and Asian retail channels for barebone configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from ARM-based designs and cloud-thin client architectures eroding traditional x86 desktop replacement volumes. Defense requires consolidation around certification moats and thermal engineering capabilities that emerging competitors cannot rapidly replicate.
For Market Incumbents: Consolidate regulatory compliance capabilities by embedding dedicated FCC Part 15 and CE marking teams within product development cycles, shortening certification lead times against emerging competitors. Deepen captive motherboard design expertise through backward integration into Taiwanese ODM partnerships, securing allocation priority during semiconductor cycle troughs. Prioritize Energy Star Version 8.0 pre-certification for next-generation fanless embedded formats targeting German industrial automation demand.
For New Entrants and Emerging Players: BIS certification fast-tracks for Indian PLI scheme assembly investments unlock price-optimized SME channels with lower regulatory barriers than US or EU entry. White-space concentrates in subscription-linked thin-client hardware for Indian call center deployments and ARM-based fanless designs for European residential media center applications. Go-to-market leverage rests on direct e-commerce bypass of established distribution layers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant mini PC divisions lacking dedicated thermal engineering talent. Long-term viability hinges on ARM architecture transition completion and Windows-on-ARM software ecosystem maturation. Monitor Qualcomm Snapdragon enterprise adoption rates as inflection indicator for architecture shift timing.
| Strategic Initiative | Industry Significance |
|---|---|
| USB4 Integration Partnership | Intel's royalty-free licensing collapses peripheral connectivity costs for compact workstation builds. |
| Fanless Embedded Format Expansion | Taiwanese ODM capacity investments target German DIN rail automation specifications. |
| Educational Cooperative Certification | Midwest US buying consortia filter procurement to Energy Star-qualified vPro-enabled fleets. |
| ARM Architecture Platform Launch | Qualcomm Snapdragon designs demonstrate performance-per-watt metrics enabling new thermal envelopes. |
| India PLI Assembly Investment | Production-linked incentives attract price-optimized unit integration for South Asian SME channels. |
Methodological Framework
Cross-validation between primary interviews with ODM thermal engineers, enterprise IT procurement officers, and educational technology directors anchors the qualitative findings against secondary validation from SEC component supplier filings, EPA Energy Star certified product databases, and EU Ecodesign Directive implementation reports. Bottom-up triangulation aggregates unit shipment estimates by product format and processor architecture, while top-down verification cross-checks against regional electronics trade data. Primary fieldwork concentrated on Taiwanese motherboard design clusters, German automotive supplier deployments, and US Midwest educational buying consortia.
Sensitivity analysis across semiconductor allocation volatility scenarios and regulatory compliance timeline variations shapes the analytical framework. Segmentation dimensions span product type, end user category, processor technology, and physical form factor, with additional modeling of certification tier and thermal design power classes. CAGRs derive from regression analysis against historical refresh cycle compression patterns and enterprise edge computing adoption curves. Forecast inputs incorporate Intel NUC reference design roadmaps and ARM-based Windows compatibility evolution.
Underlying assumptions cover steady DDR5 supply normalization, stable EU Ecodesign Directive enforcement timelines, and continued Intel USB4 royalty-free licensing, with deviation risk concentrated in Taiwan semiconductor logistics disruptions and Qualcomm enterprise software ecosystem maturation delays. Recalibration cycles align with material shifts in processor architecture transitions and regulatory certification threshold updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Brazil Lime Market
Others
Drum Motor Market
Others
Video Conferencing Hardware Market
Others
Global Food Fiber Market
Others
Italy 3D Printing Construction Market
Others
Global Thermally Conductive Grease Market
Others
Allogeneic Human Chondrocyte Market
Others
Europe Astrology Market
Others
Canada Laser Hair Removal Market
Others
APAC Smart Home Market
Others
Folding Smartphone Market
Others
Grna Market
Others
Allogeneic T Cell Therapies Market
Others
Shear Testing Equipment Market
Others
Paraffin Physical Therapy Market
Others
Global Transparent Plastics Market