
 Sustainable Construction Market | 2026-2036
Sustainable Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Construction Market Analysis
Performance-based maintenance contracts for building envelopes is recalibrating what contractors and developers purchase as a bundled offering rather than discrete materials. Holcim leverages its geographic footprint across five continents to anchor low-carbon cement supply chains near major infrastructure corridors. Sika AG specializes in adhesive and sealing systems that extend structural lifespans, competing on durability metrics rather than first-cost pricing. Owens Corning dominates insulation manufacturing scale in North America, controlling distribution channels that reach regional homebuilders directly.
Sustainable construction encompasses the design, engineering, and assembly of built environments using materials and processes that minimize embodied carbon, energy consumption, and operational waste across a structure's full lifecycle. Primary industrial purpose centers on meeting stringent thermal performance targets while reducing greenhouse gas emissions from cement, steel, and aluminum production. Recycled steel and engineered bamboo dominate material type procurement for mid-rise commercial structures where strength-to-weight ratios determine feasibility. Green roofing and energy-efficient systems within the technology segment command premium positioning as municipalities embed vegetative cover and HVAC performance into building codes. Residential building type applications sustain volume leadership though institutional projects generate higher margins through longer contract durations and certification complexity.
The EU Green Deal and REACH frameworks in Europe mandate embodied carbon disclosure for construction products above specified thresholds, reshaping supplier qualification requirements for public tenders. EPA guidelines in the United States and China's GB standards for green building materials create parallel compliance pathways that fragment certification costs across export markets. BIS and GRIHA protocols in India establish domestic rating benchmarks that local developers must satisfy for commercial lending eligibility. Stakeholders must monitor divergence between regional carbon accounting methodologies and prepare dual-certification strategies where cross-border project pipelines justify the compliance overhead.
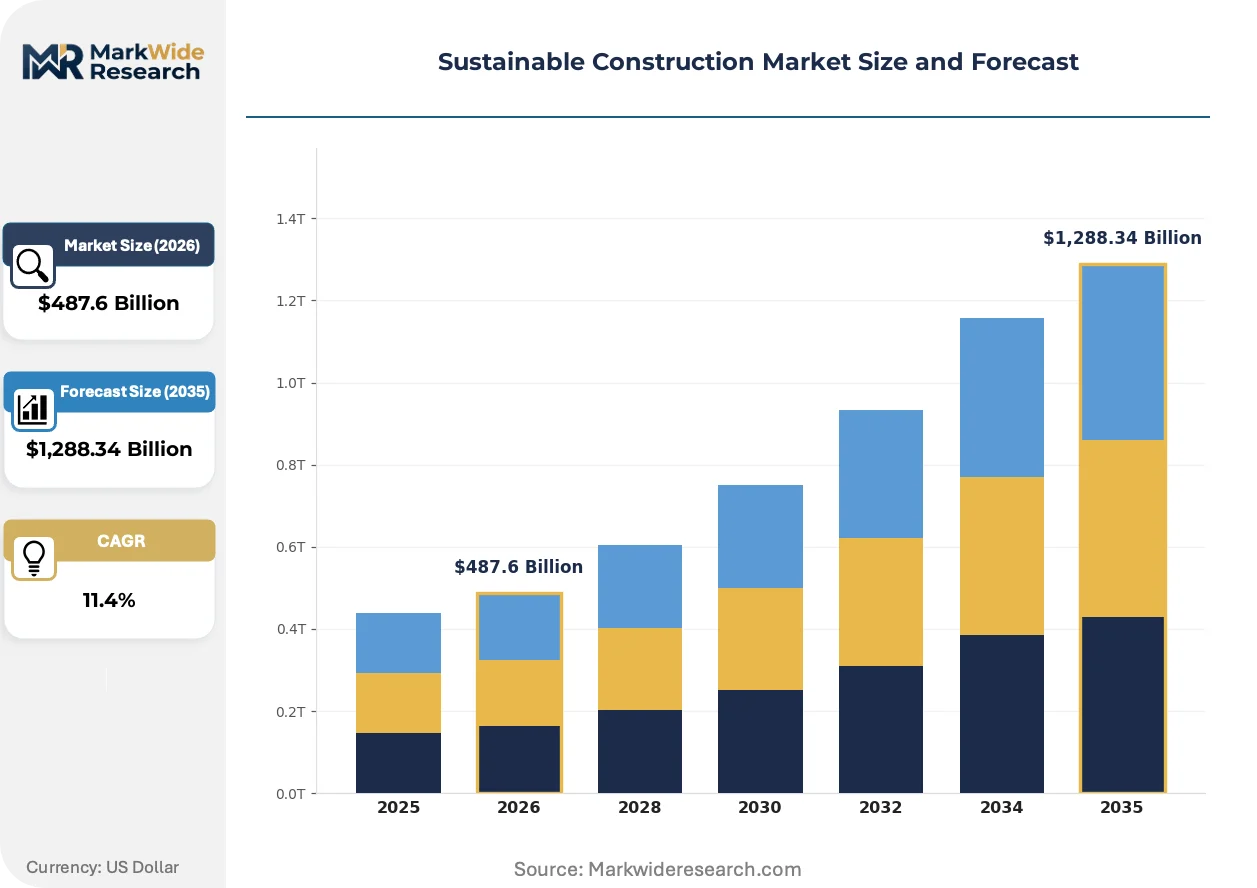
Market Dynamics
Performance-based procurement contracts for building envelopes are restructuring contractor purchasing patterns away from discrete materials toward bundled lifecycle solutions. This shift compresses supplier margins while favoring vertically integrated material-system providers capable of warranting thermal and structural outcomes across multi-decade horizons.
Growth Catalysts
- EU Green Deal retrofit mandates:Tightened energy performance standards across member states accelerate material substitution timelines for existing building stock. Public procurement rules in Germany, France, and the Netherlands now favor low-carbon concrete and engineered timber systems.
- Engineered bamboo structural systems:Superior strength-to-weight ratios enable mid-rise commercial construction with reduced foundation loads. Developers in seismic zones specify these systems for lateral force resistance.
- Green roofing technology:Municipal building codes embed vegetative cover requirements for stormwater management. Urban heat island mitigation drives specification in dense metropolitan cores.
Market Restraints
- Clinker substitution limits:Low-carbon cement formulations face technical ceilings on alternative binder content before compressive strength degradation occurs. ASTM C150 and EN 197-1 standards constrain formulation flexibility.
- Aluminum smelting concentration:Primary aluminum production clusters in regions with hydroelectric access, exposing supply chains to electricity cost volatility and carbon border adjustment exposure.
- Cross-laminated timber fire rating:Building code acceptance lags material capabilities in jurisdictions without prescriptive heavy timber provisions, delaying project approvals.
Strategic Opportunities
- India GRIHA certification pipeline:Commercial lending eligibility tied to domestic green building ratings creates certified material demand from domestic developers. BIS protocol alignment opens public sector procurement access.
- Building-integrated photovoltaics convergence:Façade-embedded solar generation merges envelope performance with on-site energy production. Curtain wall contractors expand service scope into electrical integration.
- Direct-to-regional-homebuilder distribution:Bypassing traditional lumber yard channels captures margin and specification control. Insulation manufacturers deploy captive fleet delivery for just-in-time job site coordination.
Industry Challenges
- Embodied carbon accounting skill gap:Lifecycle assessment expertise remains concentrated among specialized consultants. General contractors lack in-house capability to verify Environmental Product Declaration claims.
- Dual certification overhead:Divergence between regional carbon accounting methodologies forces suppliers to maintain parallel documentation systems for export market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Construction Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,288.34 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Recycled Steel, Bamboo, Rammed Earth, Hempcrete Building Type: Residential, Commercial, Industrial, Institutional Technology: Solar Panels, Green Roofing, Rainwater Harvesting, Energy-Efficient Systems End User: Contractors, Developers, Architects, Government Agencies |
| Companies Covered | Holcim, CRH plc, Saint-Gobain, Kingspan Group, BASF SE, Sika AG, Heidelberg Materials, Owens Corning, Skanska, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Construction Market Emerging Trajectories
Digital fabrication and material science advances are compressing design-to-assembly timelines while embedding performance verification directly into component manufacturing. These developments favor capital-intensive producers capable of integrating software-controlled production with certified material traceability.
Cross-laminated timber manufacturing is converging with robotic prefabrication to deliver panelized structural systems with millimeter tolerance. Mid-rise commercial developers in Scandinavia and the Pacific Northwest specify these systems for 30-50% schedule compression versus conventional steel framing. Factory-controlled moisture content and connection detailing enable weather-tight enclosure within compressed construction windows.
REACH framework embodied carbon disclosure thresholds are mandating Environmental Product Declarations for construction products above specified tonnage entering EU public tenders. Suppliers without verified lifecycle data face disqualification from infrastructure and institutional procurement pipelines. German and Dutch concrete producers accelerate clinker substitution investments to maintain qualification status under tightened thresholds.
Asset managers now bundle envelope performance warranties with property management contracts, transferring thermal and moisture risk from owner to contractor. Institutional investors in commercial office and multifamily residential portfolios drive this structure to secure green bond eligibility and secure rental premiums. This procurement evolution concentrates specification authority with national contractors capable of underwriting multi-decade performance outcomes.
Sustainable Construction Market Segmentation
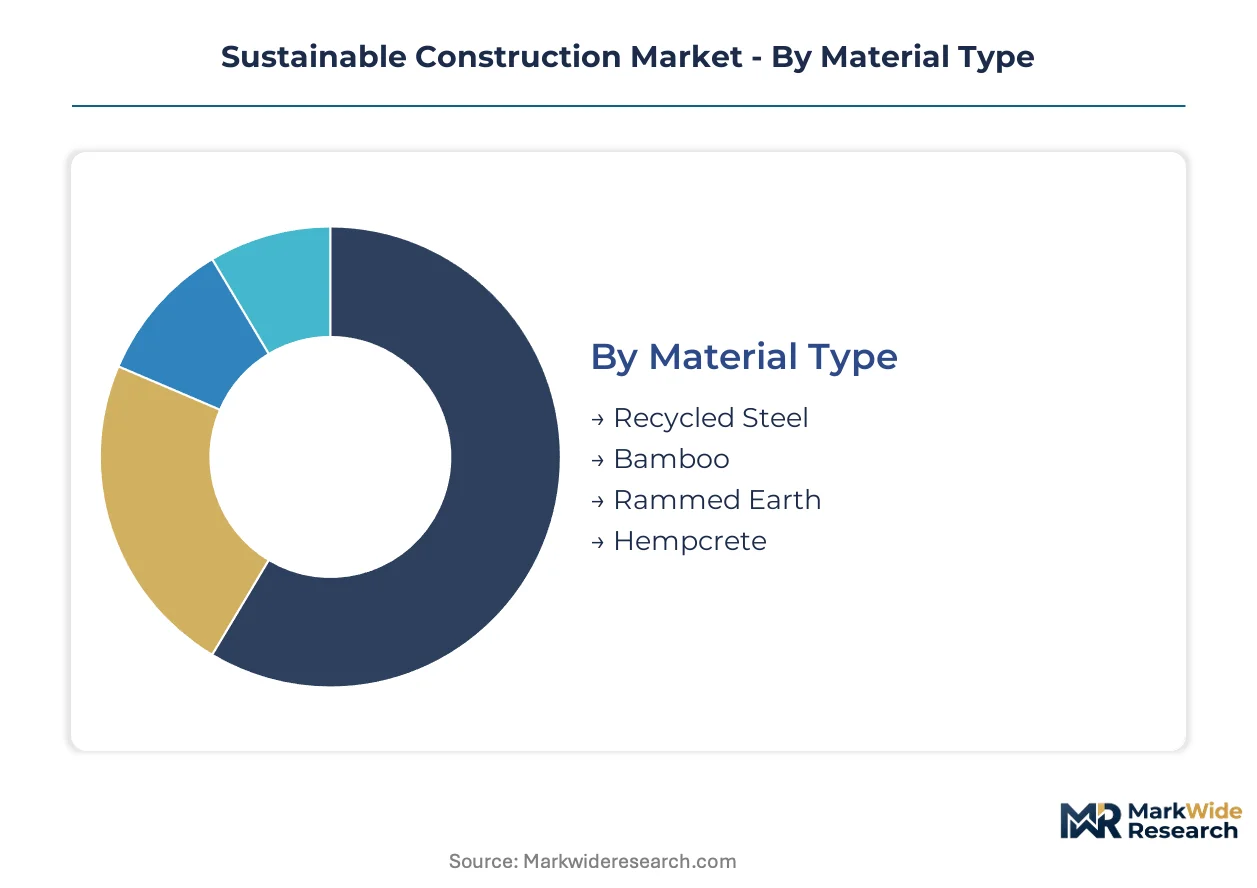
Segmentation in sustainable construction reveals how certification burdens, procurement authority, and technical performance requirements fragment demand across material specifications and building typologies. Understanding these divisions exposes where compliance costs concentrate and which stakeholder groups control specification decisions.
Material Type:
Certification requirements vary sharply across material categories, with some demanding extensive Environmental Product Declarations while others navigate lighter documentation paths.
- Recycled Steel:Structural rebar and framing members produced from electric arc furnace feedstock achieve high tensile strength with reduced embodied carbon. Demand concentrates in German and Dutch commercial retrofits where public procurement rules mandate scrap-content thresholds. ASTM A706 and EN 10025 compliance documentation adds administrative overhead for cross-border suppliers.
- Bamboo:Engineered structural systems leverage superior strength-to-weight ratios for mid-rise commercial applications. Seismic zones in Japan and Pacific Northwest jurisdictions specify these systems for lateral force resistance, though building code acceptance lags material capabilities in regions without prescriptive heavy timber provisions.
- Rammed Earth:Compressed soil mixtures deliver thermal mass for passive climate control in arid and Mediterranean climates.
- Hempcrete:Bio-aggregate lime composites provide hygrothermal regulation for low-rise residential envelopes in France and Belgium.
Recycled steel sits at the top of the volume ranking, with engineered bamboo climbing the fastest as code acceptance expands.
Building Type:
Margin structures diverge across building typologies, with longer contract durations and certification complexity rewarding patient capital in certain segments.
- Residential:Single-family and multifamily construction sustains absolute volume leadership through repetitive unit economics. Regional homebuilders in North America specify factory-produced panelized systems to compress construction windows and reduce on-site labor exposure.
- Commercial:Office and retail developments generate premium margins through performance-based procurement contracts that bundle envelope warranties with property management agreements. Institutional investors drive this structure to secure green bond eligibility.
- Industrial:Warehouse and logistics facilities prioritize speed-to-enclosure over thermal performance optimization.
- Institutional:Schools, hospitals, and government buildings face the most stringent embodied carbon disclosure requirements under EU Green Deal procurement rules.
Residential commands absolute shipment volumes, while institutional projects capture the steepest margin expansion trajectory.
Technology:
Technology adoption correlates with municipal code mandates rather than pure economic returns, embedding regulatory risk into investment planning.
- Solar Panels:Building-integrated photovoltaics merge façade performance with on-site generation, expanding curtain wall contractor scope into electrical integration. German and Dutch codes increasingly mandate renewable generation capacity for commercial structures above specified floor areas.
- Green Roofing:Vegetative cover systems manage stormwater and mitigate urban heat island effects. Copenhagen, Toronto, and Singapore embed coverage requirements in municipal building codes for structures above threshold footprints.
- Rainwater Harvesting:Collection and filtration systems address water scarcity in Australian and Middle Eastern jurisdictions.
- Energy-Efficient Systems:High-performance HVAC and lighting retrofits dominate EU renovation wave spending.
Energy-efficient systems anchor current deployment scale, with building-integrated photovoltaics gaining share fastest as electrical integration capabilities mature.
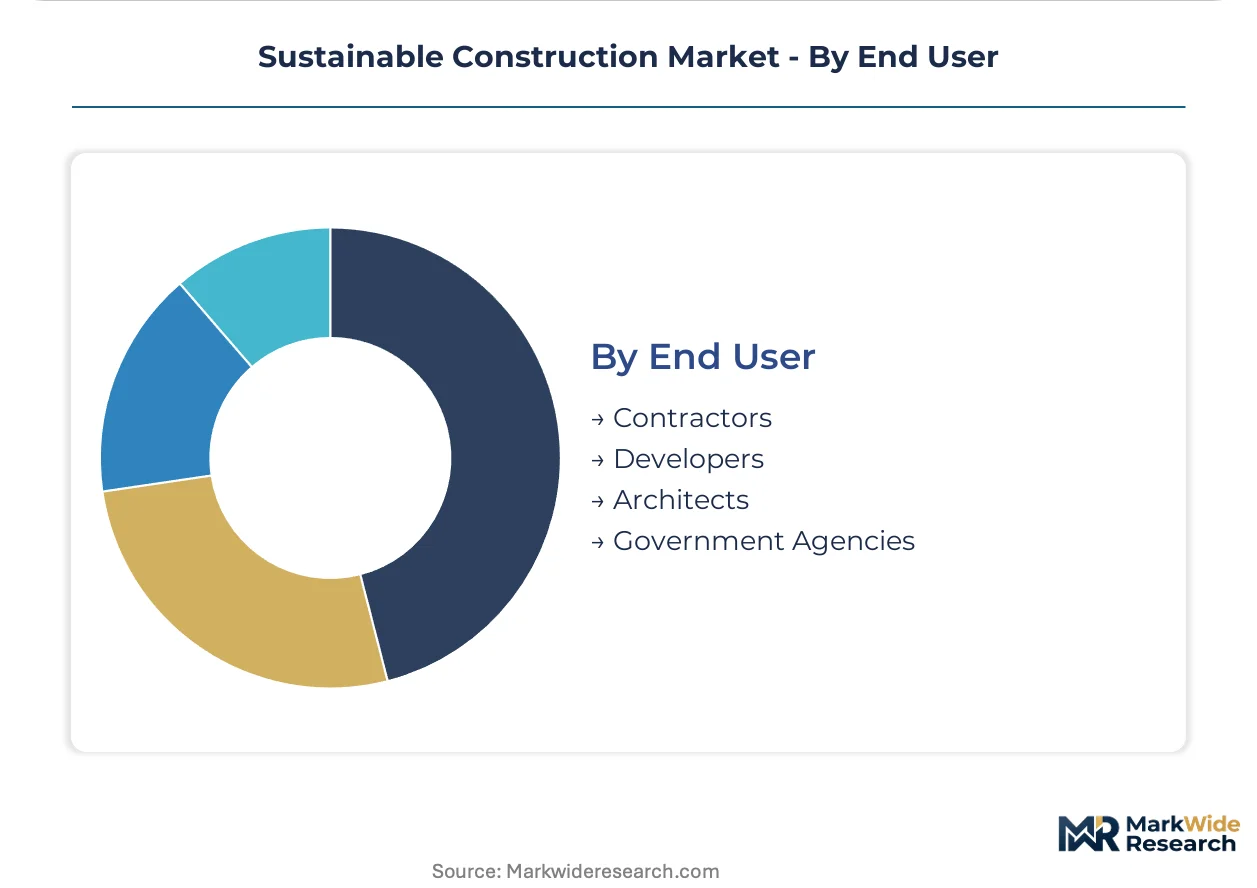
End User:
Procurement authority has shifted toward consolidated contractors capable of underwriting multi-decade performance outcomes, compressing supplier access routes.
- Contractors:National envelope specialists now control specification authority through performance-warranty offerings that transfer thermal and moisture risk from owners. These firms favor vertically integrated material-system providers over discrete component vendors.
- Developers:Commercial real estate developers anchor demand for certified green building materials as they respond to institutional investor ESG mandates and green bond eligibility requirements.
- Architects:Design professionals influence early-stage material selection but face constrained budgets in competitively tendered projects.
- Government Agencies:Public procurement rules in Germany, France, and the Netherlands create qualified supplier lists that exclude uncertified material producers from infrastructure pipelines.
Contractors control the largest share of specification decisions, with government agencies expanding their procurement leverage fastest through tightened public tender requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands deploy divergent retrofit financing mechanisms despite sharing EU Green Deal obligations, while India and the United States pursue parallel but uncoordinated embodied carbon disclosure frameworks.
Germany
Commercial real estate developers in Berlin and Munich accelerate procurement of low-carbon concrete and cross-laminated timber systems. The federal government's KfW building renovation programs mandate thermal performance thresholds that disqualify conventional material specifications. The Rhine-Ruhr industrial corridor concentrates engineered timber manufacturing capacity where factory-controlled prefabrication enables compressed construction schedules.
Netherlands
Public procurement rules in Amsterdam and Rotterdam favor suppliers with verified Environmental Product Declarations for infrastructure tenders. The national Omgevingswet environmental act embeds lifecycle carbon accounting into building permit approvals. The Eindhoven-Brainport region anchors digital fabrication clusters where robotic prefabrication merges with certified material traceability systems.
United States
Regional homebuilders in the Pacific Northwest specify factory-produced panelized systems to reduce on-site labor exposure. EPA guidelines for green building materials create compliance pathways that fragment certification costs across export markets. The Seattle metropolitan area dominates mass timber project approvals where prescriptive heavy timber building code provisions enable mid-rise commercial construction.
India
Domestic developers in Maharashtra and Gujarat pursue GRIHA certification to secure commercial lending eligibility from nationalized banks. The Bureau of Indian Standards protocol alignment opens public sector procurement access for certified material producers. The Delhi-NCR corridor concentrates green roofing technology deployment where municipal stormwater mandates drive vegetative cover specifications.
France
Institutional investors in Paris and Lyon bundle envelope performance warranties with property management contracts to secure green bond eligibility. The RE2020 environmental regulations mandate embodied carbon limits for new residential construction above specified floor areas. The Auvergne-Rhône-Alpes region anchors hempcrete production clusters where bio-aggregate lime composites serve low-rise residential thermal regulation requirements.
Sustainable Construction Market Vendor Landscape
Top-tier vendors anchor integrated material-system provision, while mid-scale specialists compete on regional certification expertise and discrete component manufacturing. The vendor base stratifies across three tiers: multinational building material conglomerates with captive low-carbon cement supply chains, national envelope specialists underwriting performance warranties, and regional fabricators serving discrete retrofit markets. Strategic archetypes include vertically integrated lifecycle solution providers, durability-focused adhesive and sealing system specialists, and scale-driven insulation manufacturers controlling direct distribution channels. Dominant competitive moves encompass backward integration into alternative binder feedstocks and geographic expansion through performance-based procurement contract anchoring.
Among Swiss-anchored material conglomerates, Holcim AG and Sika AG occupy distinct archetype positions within the competitive structure. Holcim exemplifies the integrated lifecycle solution provider through its five-continent geographic footprint anchoring low-carbon cement supply chains near major infrastructure corridors. Sika AG represents the durability-focused specialist archetype, competing on structural lifespan extension metrics rather than first-cost positioning. Owens Corning, identifiable by its corporate suffix structure, sits within the scale-driven insulation manufacturing tier where captive distribution channels reach regional homebuilders directly. These three entities demonstrate how divergent strategic positioning enables coexistence across procurement contract structures that favor bundled solutions over discrete material supply.
| Leading Market Players |
|---|
| Holcim |
| CRH plc |
| Saint-Gobain |
| Kingspan Group |
| BASF SE |
| Sika AG |
| Heidelberg Materials |
| Owens Corning |
| Skanska |
| Others |
Supply Flow & Price Mechanics
Clinker price volatility in China cascades through cement supply chains into three-tier pricing structures across premium, standard, and economy levels. Low-carbon cement producers in Germany and France absorb alternative binder cost premiums while regional homebuilders in North America face compressed margins on factory-produced panelized systems.
Pricing Analysis
Capacity additions in Scandinavia are reshaping price floors for cross-laminated timber systems as robotic prefabrication compresses unit economics. Project-based long-term offtake contracts dominate institutional procurement, with price differentiation hinging on Environmental Product Declaration tier and volume scale. Cost compression in standard-grade insulation runs through direct-to-homebuilder distribution channels. Regional homebuilders exhibit highest price sensitivity, while institutional investors underwriting green bond eligibility accept premium positioning for certified material bundles.
Supply Chain Analysis
Single-source vulnerability sits with Chinese primary aluminum smelting clusters exposed to electricity cost volatility and carbon border adjustment mechanisms. Engineered bamboo feedstock draws from Vietnam and Indonesia, while low-carbon cement production rests on German and Dutch clinker substitution investments. Tariff exposure threatens cross-border steel rebar flows. Distribution runs through national envelope specialists capable of warranting multi-decade thermal performance outcomes rather than discrete component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustainable construction market functions as a stable compounder anchored by EU Green Deal retrofit mandates that lock in multi-decade material substitution timelines across member states.
For Market Incumbents: Deepen backward integration into alternative binder feedstocks to defend against emerging low-carbon cement specialists. Anchor capacity additions in the Rhine-Ruhr corridor to capture German public procurement volume. Certification investment in BIS and GRIHA protocols secures Indian commercial lending eligibility pipelines against domestic challengers. For New Entrants and Emerging Players: Building-integrated photovoltaics convergence offers technology-first wedge positioning as curtain wall contractors expand electrical integration capabilities. Target underpenetrated hempcrete thermal regulation in French low-rise residential construction. Pursue direct-to-regional-homebuilder distribution bypassing traditional lumber yard channels. For Investors and Strategic Acquirers: Asymmetric upside sits with national envelope specialists underwriting performance warranties that transfer thermal and moisture risk from owners. Five-to-ten year viability favors vertically integrated material-system providers over discrete component manufacturers. Watch for REACH framework threshold tightening as inflection indicator for Environmental Product Declaration verification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Clinker Substitution Investment | German concrete producers maintain EU public tender qualification under tightened embodied carbon thresholds. |
| Robotic Prefabrication Scale-Up | Scandinavian engineered timber manufacturers compress panelized system delivery timelines for mid-rise developers. |
| Performance Warranty Bundling | National envelope specialists capture specification authority through multi-decade thermal outcome underwriting. |
| Direct Distribution Fleet Deployment | Insulation manufacturers bypass lumber yards to coordinate just-in-time job site delivery for regional homebuilders. |
| Dual Certification Documentation | Material suppliers maintain parallel lifecycle accounting systems for EU and Indian market access. |
Methodological Framework
Direct dialogue with commercial real estate developers, national envelope contractors, plant managers at cement producers, and procurement leads at institutional investors grounded qualitative findings. Secondary validation drew from EU Green Deal implementation reports, EPA green building material guidelines, BIS protocol documentation, and SEC filings of listed construction material conglomerates. Bottom-up shipment data triangulated against top-down construction spending forecasts.
Bottom-up modeling segmented demand across material type, building typology, technology adoption, and end-user procurement authority. The analysis window spans from base year through projection horizon. Modeled inputs included retrofit mandate implementation timelines, building code revision schedules, and green bond issuance trajectories. CAGRs derived from segment-level volume and value buildups cross-referenced against macro construction output indices.
The model holds under steady regulatory enforcement; deviation in EU Green Deal member state compliance intensity or carbon border adjustment implementation pace would shift material substitution timelines. Forecasts reflect documented assumptions on clinker substitution technical ceilings and cross-laminated timber code acceptance expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Solar Windows Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Green Cement Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Solar Frames Market
Green Building Materials
Green Coatings Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Silica Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Solar Glass Market