
 Mobile MRI Services Market | 2026-2036
Mobile MRI Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile MRI Services Market Intelligence
Single-source equipment procurement is shifting toward multi-vendor fleet strategies among mobile MRI operators. GE Healthcare leverages its installed base of 1.5T and 3T systems to anchor long-term service contracts with rural hospital networks. Siemens Healthineers competes through magnet technology leadership, while Philips Healthcare differentiates via patient-centric open-architecture designs that reduce claustrophobia-related scan cancellations.
Mobile MRI services deliver diagnostic imaging through tractor-trailer or van-mounted systems equipped with superconducting magnets operating at 1.5 to 3 Tesla, typically cooled by liquid helium and shielded against electromagnetic interference for use at non-fixed clinical sites. The primary purpose is to extend advanced neuroimaging, musculoskeletal, and body scanning capabilities to underserved facilities lacking capital budgets for permanent installations. Routine scanning occupies the largest revenue share within service type segmentation due to recurring contractual relationships with hospital systems. Open MRI technology leads patient throughput in pediatric and bariatric populations where closed-bore tolerance remains limited. Scheduled deployment models dominate over on-demand arrangements, as block-booking agreements with diagnostic centers generate predictable utilization rates and stronger margin pools.
The FDA enforces quality standards under 21 CFR 1020.32 for diagnostic x-ray and MRI equipment performance, while CMS reimbursement rules under the Physician Fee Schedule directly shape mobile service economics for Medicare-covered populations. State-level certificate-of-need regulations in approximately two-thirds of US jurisdictions constrain fleet expansion by requiring demonstrated community need before new imaging capacity approval. Stakeholders must monitor evolving site-neutral payment policies and helium supply chain constraints as determinants of fleet profitability and geographic coverage decisions.
Market Dynamics
Helium supply chain volatility is compressing fleet economics and forcing mobile MRI operators toward closed-loop cryogenic systems and alternative magnet cooling technologies.
Growth Catalysts
- 21st Century Cures Act:The FDA's diagnostic imaging quality mandates accelerate equipment replacement cycles among rural hospital networks seeking compliant mobile services.
- Hospital consolidation:Satellite facilities in the American Midwest now rely on scheduled mobile deployments rather than permanent radiology departments.
- Superconducting magnet advances:Higher field strength systems at 3 Tesla enable advanced neuroimaging protocols previously restricted to academic medical centers.
Market Restraints
- Helium scarcity:Global helium refining concentration in Qatar and the United States exposes fleet operators to price spikes and allocation rationing.
- Certificate-of-need laws:Two-thirds of US states require demonstrated community need before approving new imaging capacity, blocking fleet expansion.
- Fixed-asset substitution:Permanent 1.5T installations at mid-sized hospitals reduce reliance on mobile services for routine scanning volumes.
Strategic Opportunities
- Pediatric neuroimaging:Open-architecture magnets reduce claustrophobia-related cancellations in children's hospitals and autism specialty centers.
- Site-neutral payment policies:CMS reimbursement parity between hospital-based and freestanding imaging creates margin expansion for mobile operators serving Medicare populations.
- AI-assisted workflow integration:Automated scan prescription and reconstruction software compresses exam times and raises daily throughput per mobile unit.
Industry Challenges
- Specialized technician scarcity:MRI technologists with mobile deployment experience command premium wages and limited geographic mobility.
- Electromagnetic shielding logistics:Trailer-mounted Faraday cage integrity requires precision engineering for each non-clinical site placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile MRI Services Market |
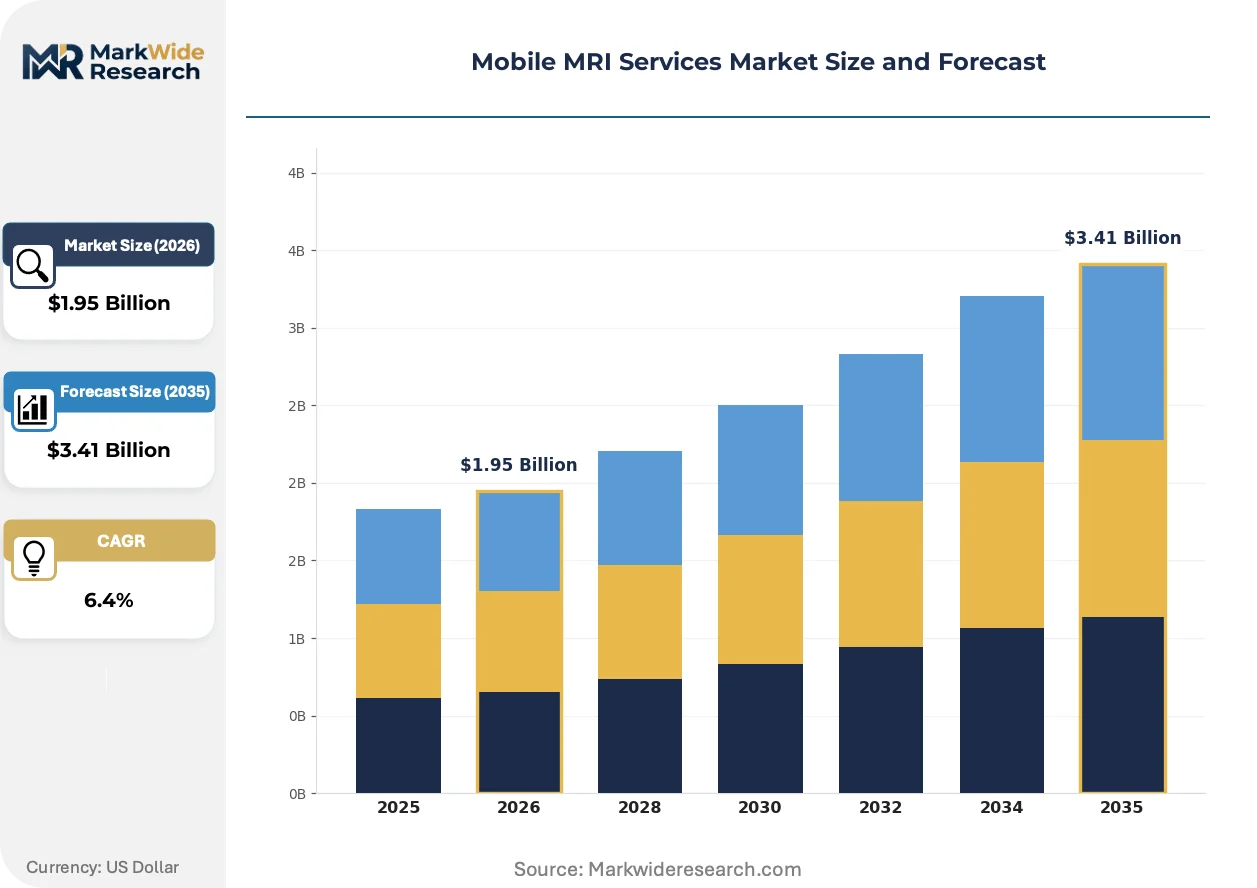
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Scanning, Routine Scanning, Sports Imaging, Research Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Home Healthcare Technology: Closed MRI, Open MRI, Extremity MRI, Hybrid MRI Deployment: On-Demand Services, Scheduled Services, Mobile Units, Temporary Installations |
| Companies Covered | DMS Health, Akumin Inc., Cobalt Health, RAYUS Radiology, Shared Medical Services, Front Range Mobile Imaging, Inc., GE Healthcare, Siemens Healthineers, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile MRI Services Market Strategic Shifts & Innovations
Mobile MRI service models are pivoting from equipment rental toward integrated diagnostic partnerships that bundle imaging, interpretation, and data management.
Helium-free superconducting magnets are electrifying fleet refresh strategies by eliminating cryogen dependency and reducing site preparation costs. Rural hospital networks in the American Midwest are adopting these systems at twice the rate of coastal markets. The technology is electrifying competitive positioning among service providers previously constrained by helium logistics and quench recovery downtime.
The FDA's 21 CFR 1020.32 performance standards now require enhanced quality assurance documentation for diagnostic MRI equipment. Mobile fleet operators must deploy automated monitoring systems to maintain compliance across dispersed deployment sites. Rural health systems lacking in-house biomedical engineering staff are outsourcing compliance management to specialized third-party service firms.
Block-booking agreements are displacing on-demand scheduling as the dominant contracting mechanism between mobile operators and diagnostic centers. Hospital systems seek predictable utilization rates and guaranteed capacity access over transactional per-scan pricing. This shift concentrates most visible in the American Midwest where consolidated health networks negotiate multi-year exclusive service arrangements.
Mobile MRI Services Market Segmentation
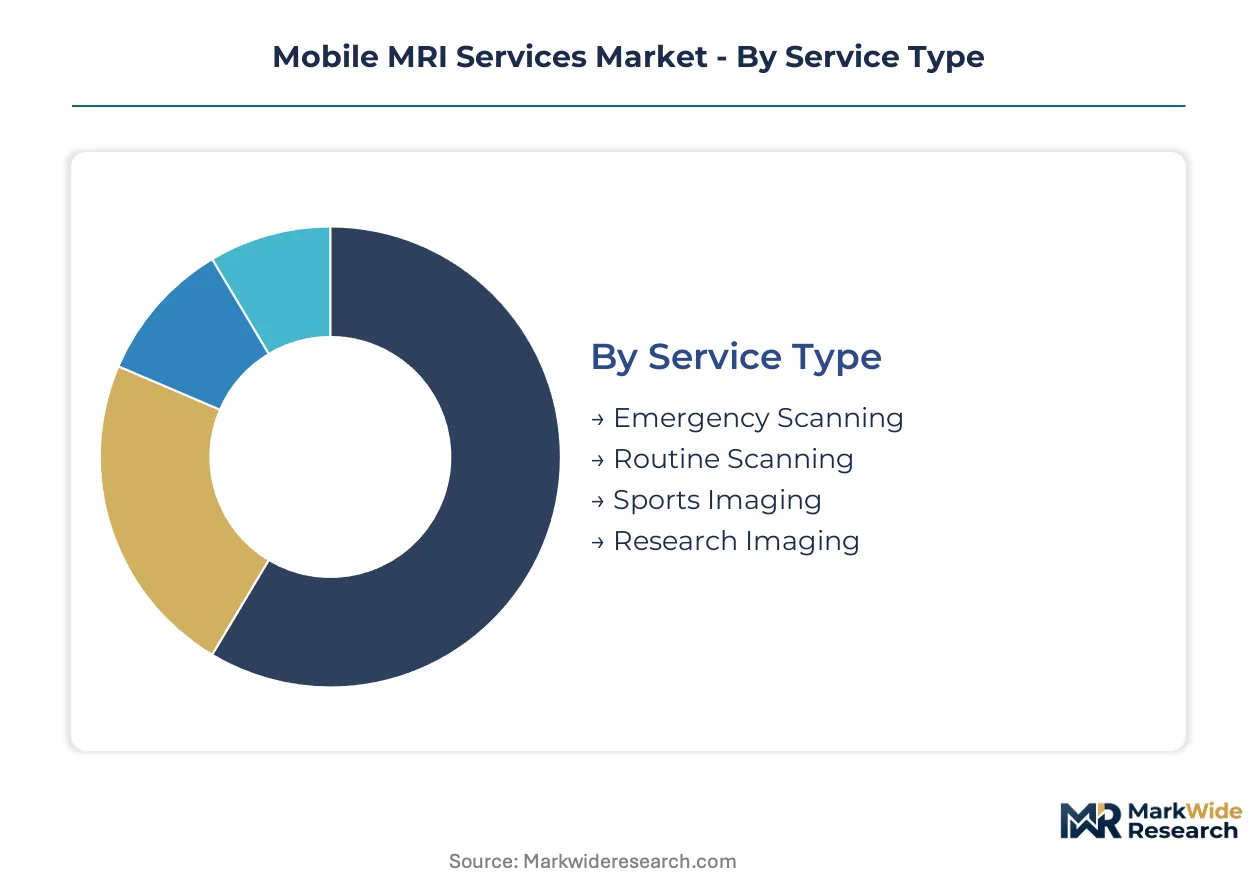
Mobile MRI operators structure service portfolios around utilization predictability and reimbursement economics. Segment selection determines fleet configuration, magnet technology procurement, and contracting terms with rural hospital networks.
Service Type:
Contract duration and scan volume predictability drive buyer selection across service categories.
- Routine Scanning:Recurring contractual relationships with hospital systems generate the largest revenue share. Block-booking agreements with diagnostic centers in the American Midwest produce predictable utilization rates and stronger margin pools for fleet operators.
- Emergency Scanning:Unscheduled neuroimaging for stroke protocols and trauma assessments commands premium per-scan pricing. Demand concentrates at Level III trauma centers in rural Wisconsin and Nebraska where permanent 3T capacity remains unavailable.
- Sports Imaging:Musculoskeletal protocols for athletic programs require specialized coil configurations and rapid turnaround. Collegiate athletic departments in Texas and Florida represent primary contracting parties.
- Research Imaging:Multi-site clinical trials demand standardized acquisition protocols and centralized data management. Academic medical centers in North Carolina and Ohio sponsor the majority of mobile research deployments.
Routine Scanning leads on scale; Emergency Scanning leads on momentum.
End User:
Capital availability and radiology staffing determine facility reliance on mobile services versus permanent installation.
- Hospitals:Rural critical access hospitals lacking fixed-asset budgets constitute the dominant demand source. Satellite facilities in consolidated Iowa and Illinois health systems rely on scheduled mobile deployments rather than permanent radiology departments.
- Diagnostic Centers:Independent imaging facilities leverage mobile units to extend service menus without facility expansion. Freestanding centers in Kansas and Missouri negotiate exclusive multi-year arrangements for guaranteed capacity access.
- Research Institutions:Academic medical centers deploy mobile systems for multi-site trial standardization. University hospitals in Michigan and Ohio sponsor the majority of research-oriented fleet contracts.
- Home Healthcare:Emerging segment serving bariatric and mobility-limited patients at residential sites. Palliative care networks in Arizona and New Mexico pilot bedside neuroimaging programs.
Hospitals command volume concentration; Home Healthcare climbs the fastest.
Technology:
Patient tolerance characteristics and field strength requirements dictate magnet selection for specific clinical populations.
- Open MRI:Patient-centric architecture reduces claustrophobia-related scan cancellations. Pediatric hospitals and autism specialty centers in Minnesota and Wisconsin adopt open systems at twice the rate of general acute care facilities.
- Closed MRI:Conventional superconducting systems at 1.5T and 3T deliver highest resolution neuroimaging. The FDA's 21 CFR 1020.32 quality mandates accelerate fleet upgrades to closed-bore systems with enhanced performance documentation.
- Extremity MRI:Dedicated limb scanners eliminate whole-body positioning for musculoskeletal assessments. Orthopedic specialty clinics in Colorado and Utah prioritize extremity-dedicated mobile units for joint and sports injury protocols.
- Hybrid MRI:Combined PET-MR or intraoperative imaging configurations serve advanced research and surgical planning. Academic medical centers in Ohio and North Carolina represent the primary contracting base.
Closed MRI dominates installed base; Open MRI gains share fastest.
Deployment:
Scheduling flexibility versus cost predictability shapes contracting preferences across facility types.
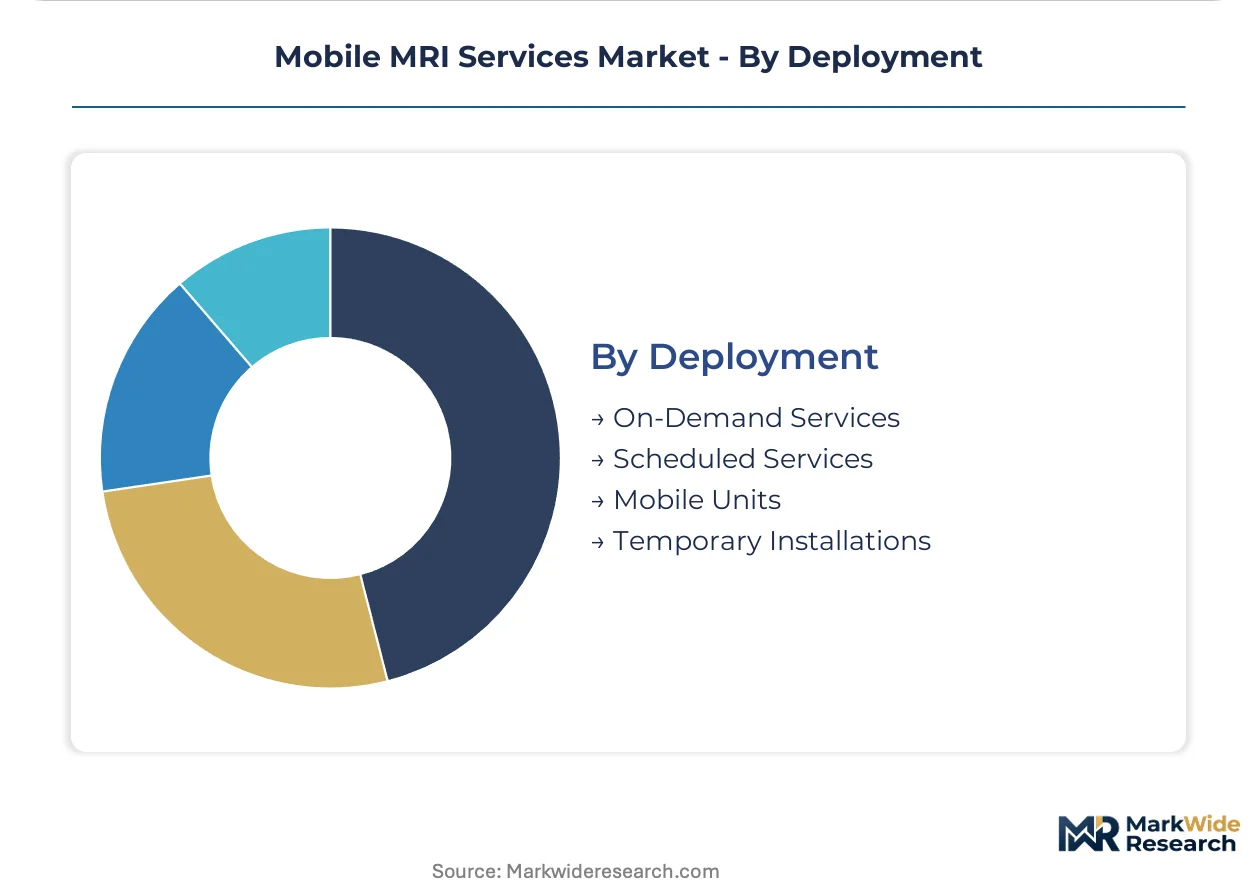
- Scheduled Services:Block-booking agreements generate predictable utilization and stronger margins. Consolidated health networks in the American Midwest negotiate multi-year exclusive service arrangements with guaranteed capacity access.
- Mobile Units:Tractor-trailer and van-mounted systems equipped with superconducting magnets enable site-to-site rotation. Rural hospital networks adopt helium-free mobile units to eliminate cryogen dependency and reduce quench recovery downtime.
- On-Demand Services:Per-scan transactional pricing serves episodic demand spikes. Emergency departments in Nebraska and Kansas retain on-demand contracts for weekend and overnight neuroimaging coverage.
- Temporary Installations:Fixed-site deployment during construction or equipment failure bridges permanent capacity gaps. Hospital systems in Indiana and Ohio deploy temporary installations during MRI suite renovations.
Scheduled Services anchor revenue stability; Mobile Units show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The American Midwest anchors mobile MRI deployment density, where hospital consolidation has eliminated permanent radiology departments at dozens of satellite facilities. Rural critical access hospitals across Iowa, Illinois, and Nebraska now contract scheduled mobile services rather than absorbing fixed-asset costs. Regulatory frameworks and reimbursement policies vary sharply across national boundaries, shaping where fleet operators can profitably expand.
United States
Rural hospital networks in Wisconsin and Minnesota drive contract volume for scheduled mobile deployments. The FDA enforces 21 CFR 1020.32 performance standards that accelerate equipment replacement cycles among fleet operators serving Medicare populations. Consolidated health systems in Iowa and Illinois negotiate multi-year exclusive arrangements with guaranteed capacity access.
Germany
University hospitals in Bavaria and North Rhine-Westphalia sponsor research-oriented mobile deployments for multi-site clinical trials. The country's national pharmaceutical regulator enforces MDR compliance timelines that compress fleet upgrade schedules for operators serving academic medical centers. Industrial clusters around Munich and Düsseldorf concentrate helium-free magnet adoption at twice the national average.
United Kingdom
NHS trusts in the Midlands and North England outsource advanced neuroimaging to mobile fleets during MRI suite renovations. The national health technology regulator mandates enhanced quality assurance documentation that increases compliance costs for dispersed deployment models. Hospital networks around Birmingham and Manchester pilot block-booking agreements with guaranteed weekend capacity.
Canada
Provincial health authorities in Ontario and Alberta contract mobile units to bridge permanent capacity gaps in remote communities. Health Canada enforces equipment performance standards that align with FDA 21 CFR 1020.32 provisions, simplifying compliance for US-based fleet operators. Diagnostic centers in Calgary and Edmonton adopt scheduled deployment models to manage predictable utilization rates.
Australia
Rural health districts in Queensland and Western Australia rely on mobile MRI for populations beyond permanent scanner reach. The Therapeutic Goods Administration requires conformity assessment procedures that extend procurement timelines for imported equipment. Fleet operators concentrate service contracts around Brisbane and Perth where hospital consolidation has reduced fixed-asset investment.
Mobile MRI Services Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue helium-free magnet technologies and AI-assisted workflow integration. The vendor base stratifies across three tiers: integrated equipment manufacturers with captive service divisions, independent mobile operators with multi-vendor fleets, and regional specialists concentrating single-state markets. Dominant competitive moves include exclusive contracting with consolidated health networks and backward integration into magnet maintenance capabilities.
Within the independent operator tier, DMS Health and Shared Medical Services exemplify multi-vendor fleet strategies that reduce single-source equipment risk. Among integrated manufacturers, GE Healthcare anchors long-term service contracts through its installed base of superconducting systems. Siemens Healthineers occupies a position emphasizing magnet technology leadership, while Philips Healthcare sits within the patient-centric design archetype targeting pediatric and bariatric populations.
| Leading Market Players |
|---|
| DMS Health |
| Akumin Inc. |
| Cobalt Health |
| RAYUS Radiology |
| Shared Medical Services |
| Front Range Mobile Imaging, Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up mobile operators anchor fleet economics through captive equipment financing and long-term service contracts with rural hospital networks. This ownership pattern concentrates pricing power among consolidated operators while helium supply volatility and FDA compliance costs reshape procurement priorities across the value chain.
Pricing Analysis
Input-cost pass-through from helium scarcity and magnet technology upgrades dominates mobile MRI pricing dynamics. Contract-based long-term offtake agreements with block-booking terms generate the largest revenue pools, while per-scan transactional pricing serves emergency and on-demand segments. Price differentiation separates premium 3T closed-bore systems with enhanced FDA 21 CFR 1020.32 documentation from standard 1.5T configurations and economy-tier open-architecture units for pediatric populations. Pricing pressure stems from site-neutral CMS reimbursement policies compressing margins for Medicare-covered populations. Rural critical access hospitals exhibit highest price sensitivity due to fixed-asset budget constraints, while academic medical centers demonstrate lowest sensitivity for research-oriented deployments.
Supply Chain Analysis
Certification gating through FDA 21 CFR 1020.32 and state-level certificate-of-need requirements constrains equipment sourcing and fleet expansion timelines. Superconducting magnet manufacturing concentrates in the United States, Germany, and the Netherlands, with helium refining anchored in Qatar and the United States. Raw material dependencies span liquid helium cryogen supply, niobium-titanium superconducting wire, and specialized electromagnetic shielding alloys. Single-source vulnerability in helium logistics exposes fleet operators to allocation rationing and price spikes from geopolitical disruptions. Distribution runs through integrated equipment manufacturers with captive service divisions, independent multi-vendor fleet operators, and regional single-state specialists serving consolidated health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile MRI services constitute a late-cycle quality story as rural hospital consolidation shifts procurement toward premium 3T systems with enhanced compliance documentation and AI-assisted workflow integration. Demand is migrating toward helium-free magnet technologies that eliminate cryogen dependency and reduce total cost of ownership.
For Market Incumbents: Hedge helium supply exposure through backward integration into closed-loop cryogenic systems and alternative magnet cooling technologies. Defend market position by securing exclusive multi-year block-booking agreements with consolidated Midwest health networks before emerging entrants deploy helium-free fleets. Prioritize certification investment in FDA 21 CFR 1020.32 automated monitoring systems to maintain compliance across dispersed deployment sites.
For New Entrants and Emerging Players: Capture white-space opportunity in home healthcare neuroimaging for bariatric and mobility-limited patients, where bedside deployment models remain underdeveloped. Target pediatric and autism specialty centers in Minnesota and Wisconsin with open-architecture magnets that reduce claustrophobia-related cancellations. Pursue go-to-market partnerships with palliative care networks in Arizona and New Mexico piloting residential imaging programs.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent multi-vendor fleet operators with established rural hospital network relationships and underutilized capacity. Long-term viability over the coming decade hinges on successful transition to helium-free magnet technologies and AI-assisted workflow integration. Monitor CMS site-neutral payment policy implementation as the primary inflection signal for margin expansion or compression across Medicare-serving operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Adoption | Eliminates cryogen dependency and reduces quench recovery downtime for rural deployments. |
| AI-Assisted Workflow Integration | Automated scan prescription compresses exam times and raises daily throughput per mobile unit. |
| Block-Booking Agreement Expansion | Multi-year exclusive arrangements with consolidated Midwest networks generate predictable utilization. |
| FDA Compliance Automation | Automated monitoring systems maintain 21 CFR 1020.32 standards across dispersed deployment sites. |
| Pediatric Open-Architecture Deployment | Patient-centric designs reduce claustrophobia cancellations in children's hospitals and autism centers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate mobile MRI service demand and supply dynamics. Primary interviews engaged fleet operations directors, rural hospital purchasing committee members, biomedical engineering managers, and GPO contracts specialists. Secondary validation drew from FDA 510(k) filings, CMS Physician Fee Schedule documentation, hospital procurement databases, and helium market trade data. Bottom-up fleet deployment counts and top-down health system expenditure analysis converged on segment-level estimates.
Segment-weighting across service type, end user, technology, and deployment model dimensions structured the analytical framework across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and equipment replacement cycles. Forecast inputs incorporated certificate-of-need regulatory constraints, helium supply chain scenarios, and site-neutral reimbursement policy trajectories specific to Medicare-covered populations.
Helium market disruptions, FDA regulatory timeline shifts, and CMS reimbursement policy revisions are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in site-neutral payment parity implementation or breakthrough adoption of closed-loop cryogenic systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bakery Packaging Market
Others
Billet Market
Others
India Data Center Physical Security Market
Others
Hearables Market
Others
Reef Aquarium Market
Others
5G Tester Market
Others
Asia-Pacific 3D Printing Construction Market
Others
UAE Location-Based Services Market
Others
Animal Feed Alternative Protein Market
Others
AI In Government And Public Services Market
Others
Idaas Market
Others
Wood Stoves Market
Others
Mobile Computer Cart Market
Others
High-End Servers Market
Others
Global Multi-Access Edge Computing Market
Others
Tunnel Lighting Market