
 Global Radar Systems Market | 2026-2036
Global Radar Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radar Systems Market Outlook
United States defense manufacturing is reshaping competitive dynamics across the radar systems value chain. Raytheon Technologies Corporation leverages its consolidated sensor-to-shooter portfolio to dominate missile defense radar architectures. Lockheed Martin Corporation anchors long-range surveillance programs through sustained R&D commitments to gallium nitride transmitter technology. Thales Group competes across European and Middle Eastern markets with specialized naval radar offerings.
Radar systems detect, track, and classify objects by transmitting radio frequency pulses and analyzing return signals, typically operating across L-band through W-band frequencies with pulse repetition rates exceeding thousands per second for fire-control applications. Ground radar and airborne radar segments occupy the largest installed bases, though synthetic aperture radar technology leads growth trajectories due to its all-weather, high-resolution imaging capabilities for reconnaissance and environmental monitoring. Defense applications command the deepest margin pools, while weather monitoring and traffic management segments face pricing pressure from commoditized hardware.
The FAA mandates secondary surveillance radar and Mode S transponder compatibility for national airspace integration, while the EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems deployed by European militaries. NATO standardization agreements further constrain vendor selection for interoperable battlefield networks. Stakeholders must monitor evolving spectrum reallocation decisions by the FCC and European regulators, as 5G expansion threatens C-band radar operations and forces costly filter redesigns or frequency migration investments.
Market Dynamics
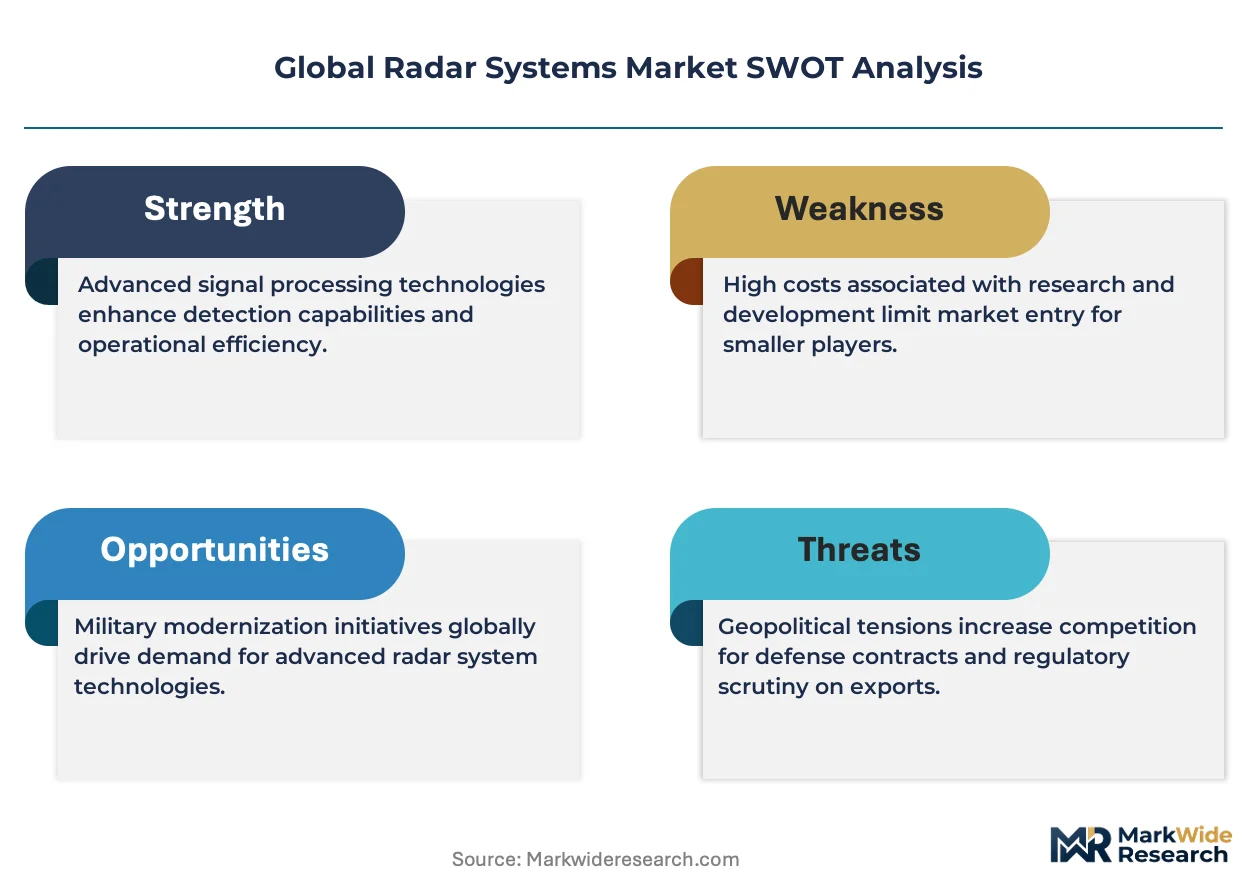
Gallium nitride transmitter technology is collapsing the cost-performance tradeoff that previously constrained active electronically scanned array deployment across mid-tier defense platforms.
Growth Catalysts
- NATO airborne modernization:Alliance members are accelerating radar upgrades for fighter and surveillance fleets, creating sustained demand for interoperable fire-control and early-warning systems.
- FCC spectrum reallocation:The commission's C-band auction for 5G deployment is forcing radar operators toward higher frequencies, stimulating replacement cycles and filter technology investment.
- Synthetic aperture radar:All-weather imaging capabilities are expanding reconnaissance and environmental monitoring applications beyond traditional defense customers.
Market Restraints
- Gallium nitride substrate concentration:High-purity wafer supply concentrates among a handful of specialized foundries, creating single-source vulnerability for transmitter manufacturers.
- EU AI Act compliance friction:Algorithmic transparency mandates for autonomous targeting systems impose documentation and testing burdens that extend development timelines.
- Legacy analog radar substitution:Existing mechanically scanned installations in emerging markets face slower replacement due to sunk capital and training infrastructure.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme and import substitution policies create openings for local assembly partnerships and technology transfer arrangements.
- Weather radar modernization:National meteorological services across Southeast Asia are replacing aging Doppler networks, creating demand for dual-polarization upgrade paths.
- Dual-use spaceborne radar:Convergence of commercial Earth observation constellations with defense surveillance requirements is opening shared-platform architectures.
Industry Challenges
- GaN process engineering talent:The specialized semiconductor fabrication workforce remains concentrated at established defense contractors, constraining new entrant scaling.
- Legacy system integration complexity:New active arrays must interface with existing platform power, cooling, and battle management architectures that were not designed for digital beamforming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radar Systems Market |
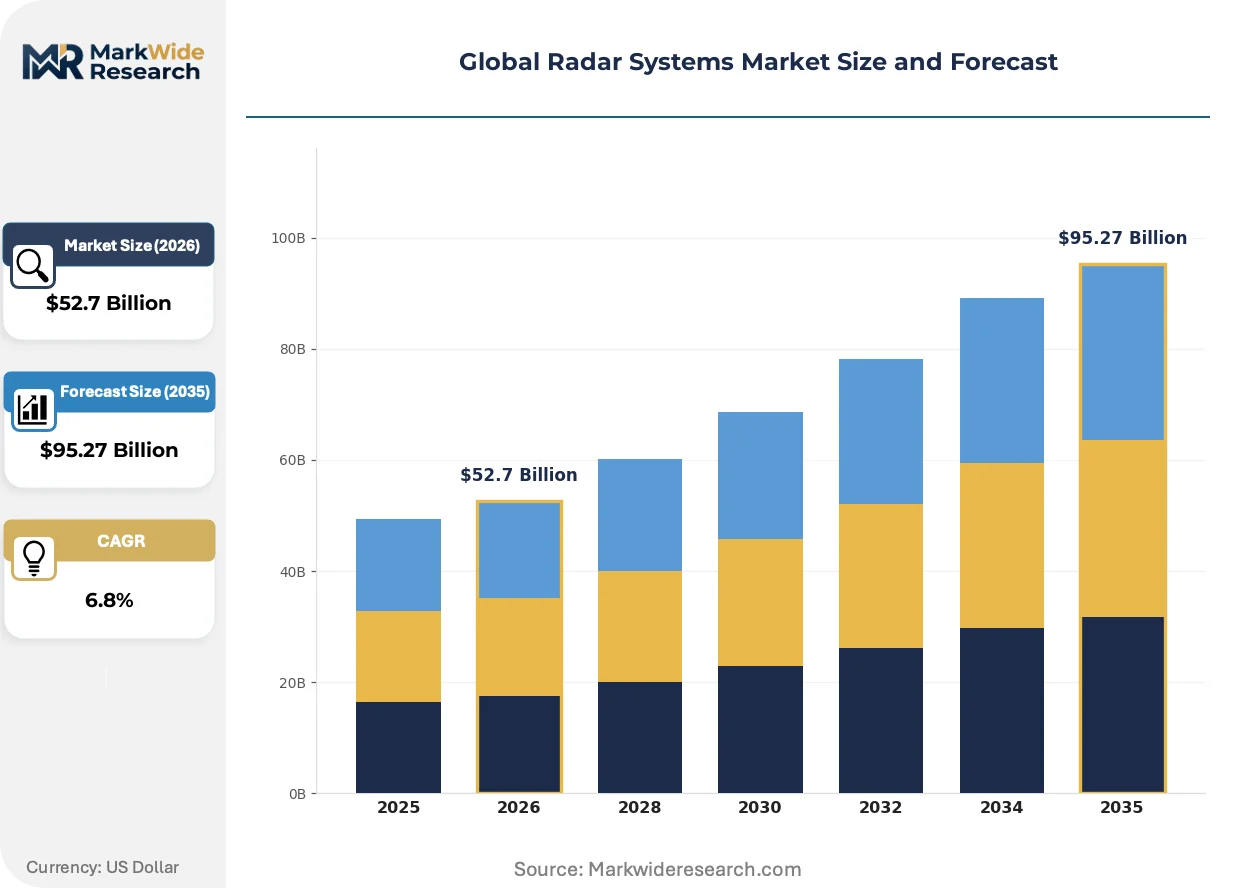
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Radar, Airborne Radar, Naval Radar, Spaceborne Radar Technology: Pulsed Radar, Continuous Wave Radar, Doppler Radar, Synthetic Aperture Radar Application: Surveillance, Weather Monitoring, Traffic Management, Defense End User: Government, Military, Aviation, Maritime |
| Companies Covered | Raytheon Technologies Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, BAE Systems plc, Leonardo S.p.A., SAAB AB, L3Harris Technologies Inc., Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radar Systems Market Strategic Shifts
Digital beamforming and software-defined architectures are dissolving the hardware-software boundary that historically locked radar customers into single-vendor upgrade paths.
Silicon-germanium BiCMOS process technology is collapsing the price barrier for digital receiver channels in fire-control radars. Mid-tier missile defense programs are adopting these chips to achieve active array performance at mechanically scanned cost points. The technology is collapsing the traditional tiering between premium GaN-based systems and economy analog alternatives.
The EU AI Act's algorithmic transparency requirements are mandating explainability documentation for autonomous targeting systems deployed by European militaries. Defense contractors must now maintain audit trails for machine-learning classification decisions. Naval fire-control programs in France, Germany, and Italy are most affected, with integrators adding interpretability layers that extend development schedules.
Defense procurement offices are consolidating sensor purchases into platform-level contracts rather than discrete radar acquisitions. Prime contractors now bundle radar with electronic warfare and communications subsystems, squeezing standalone sensor vendors. This pattern is most visible in United States Navy surface combatant programs, where the shift toward integrated mast architectures eliminates separate radar competition.
Global Radar Systems Market Segmentation
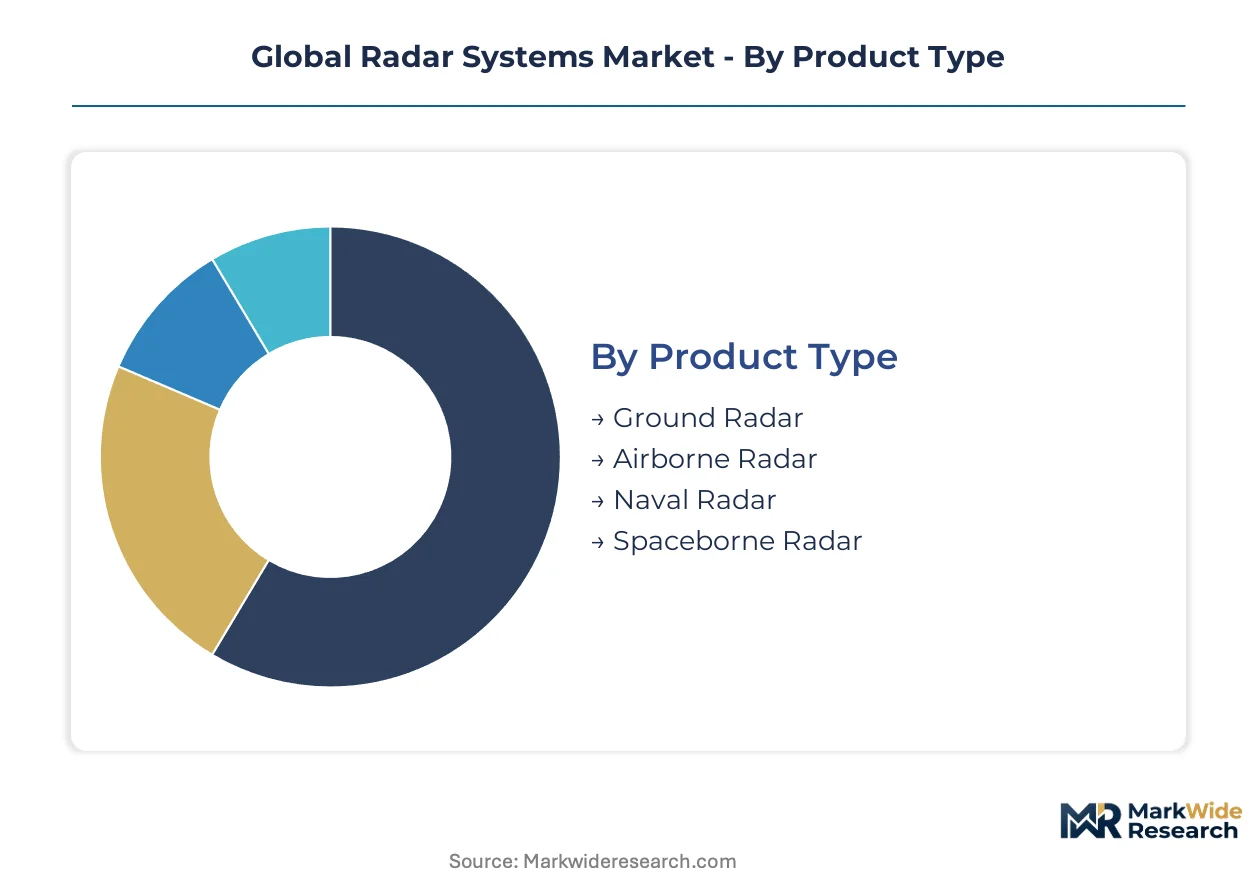
Radar systems fragment across platform types, signal processing architectures, mission profiles, and procurement authorities. Each dimension carries distinct margin structures, certification requirements, and technology refresh cycles that shape vendor positioning and investment priorities.
Product Type:
Platform altitude and mobility requirements create tiered engineering challenges across ground, airborne, naval, and orbital deployments.
- Ground Radar:Fixed installations for air traffic control and missile defense employ large-aperture phased arrays with mechanical rotation or electronic beam steering. Pentagon budgets prioritize next-generation distributed aperture systems for continental defense, while FAA mandates for Mode S transponder compatibility sustain modernization cycles.
- Airborne Radar:Fighter fire-control and surveillance platforms demand compact, high-power density transmitters with active electronically scanned arrays. NATO airborne modernization programs across Germany, the United Kingdom, and Italy are accelerating radar upgrades for fighter and surveillance fleets.
- Naval Radar:Shipboard installations balance 360-degree coverage with mast weight constraints and salt corrosion resistance. Thales Group competes across European and Middle Eastern markets with specialized naval radar offerings.
- Spaceborne Radar:Orbital synthetic aperture systems enable all-weather Earth observation for reconnaissance and environmental monitoring. Dual-use convergence between commercial Earth observation constellations and defense surveillance requirements is opening shared-platform architectures.
Ground radar holds installed capacity. Airborne radar is rotating up the share rankings.
Technology:
Signal generation and processing methods determine resolution, target discrimination capability, and susceptibility to electronic countermeasures.
- Pulsed Radar:Transmits discrete energy bursts and measures time-of-flight for range determination. Legacy mechanically scanned installations in emerging markets face slower replacement due to sunk capital and training infrastructure.
- Continuous Wave Radar:Emits uninterrupted carrier signals for precise velocity measurement through Doppler shift detection. Traffic management and industrial applications favor these systems for cost efficiency.
- Doppler Radar:Processes frequency shifts to isolate moving targets from stationary clutter. National meteorological services across Southeast Asia are replacing aging networks, creating demand for dual-polarization upgrade paths.
- Synthetic Aperture Radar:Coherent processing of multiple pulse returns generates high-resolution imagery independent of weather or illumination. All-weather imaging capabilities are expanding reconnaissance and environmental monitoring applications beyond traditional defense customers.
Pulsed radar dominates legacy inventories. Synthetic aperture radar is climbing the fastest.
Application:
Mission-criticality and funding authority create divergent pricing power and contract structures across operational domains.
- Surveillance:Long-range detection and track initiation for border security and early warning. Border agencies in India and Australia are expanding coastal radar networks.
- Weather Monitoring:Precipitation measurement and storm tracking for public safety and agricultural planning. Dual-polarization upgrades improve hydrometeor classification accuracy.
- Traffic Management:Airport surface surveillance and en-route separation assurance. The FAA mandates secondary surveillance radar compatibility for national airspace integration.
- Defense:Fire-control, target illumination, and missile guidance with electronic protection features. Defense applications command the deepest margin pools while weather monitoring and traffic management segments face pricing pressure from commoditized hardware.
Defense applications anchor revenue concentration. Weather monitoring is gaining share fastest.
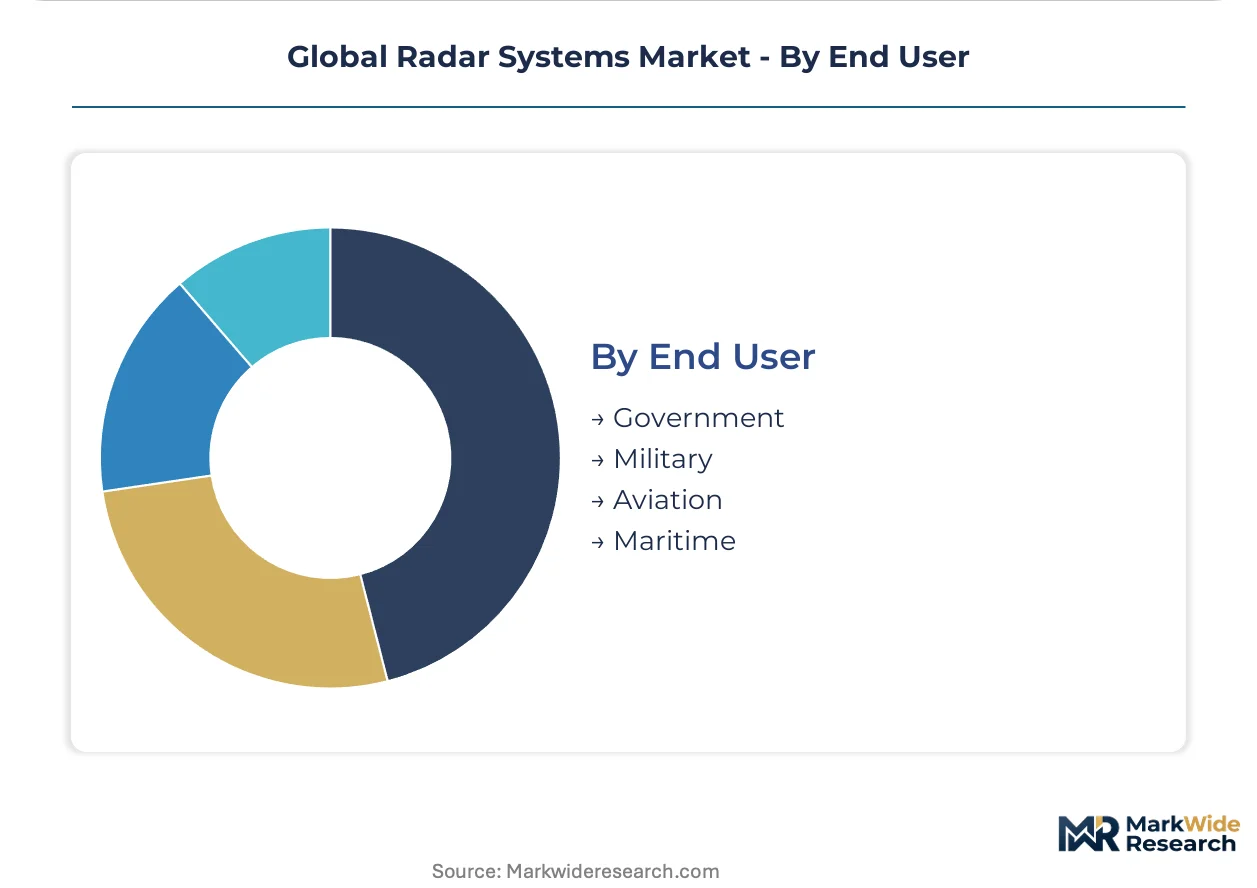
End User:
Procurement authority and budget cycles determine contract size, customization requirements, and compliance obligations.
- Government:Civilian agencies operating meteorological, aviation, and border security networks. India's PLI scheme and import substitution policies create openings for local assembly partnerships.
- Military:Armed forces with classified performance requirements and NATO interoperability mandates. The EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems deployed by European militaries.
- Aviation:Commercial airlines and airport authorities subject to FAA and ICAO equipment mandates. Secondary surveillance radar and Mode S transponder compatibility requirements drive equipment refresh.
- Maritime:Port authorities and commercial shipping operators navigating vessel traffic service regulations. Coastal surveillance networks in Singapore and the United Arab Emirates are expanding coverage.
Military end users dominate program value. Government civilian agencies are expanding procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pentagon's distributed aperture radar networks and FAA's Mode S mandates anchor North American demand. NATO's interoperable battlefield requirements and India's PLI indigenization policies are redrawing procurement geography.
United States
Pentagon budgets prioritize next-generation distributed aperture systems for continental missile defense. The FAA mandates secondary surveillance radar and Mode S transponder compatibility for national airspace integration. Greater Boston's defense technology corridor hosts concentrated radar R&D activity for airborne fire-control architectures.
Germany
NATO airborne modernization programs are accelerating fighter and surveillance fleet radar upgrades across the Bundeswehr. The EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems deployed by European militaries. Bavaria's aerospace engineering cluster around Munich anchors continental radar integration expertise.
India
The country's defense indigenization drive is creating openings for local assembly partnerships and technology transfer arrangements. The PLI scheme and import substitution policies constrain foreign vendor direct sales. Bangalore's electronics manufacturing corridor is emerging as a hub for radar subsystem fabrication and software development.
United Kingdom
Royal Air Force surveillance platform modernization is sustaining demand for long-range airborne early-warning systems. NATO standardization agreements constrain vendor selection for interoperable battlefield networks. The Midlands defense manufacturing belt maintains specialized capabilities for naval radar integration and testing.
Japan
Maritime Self-Defense Force surface combatant programs are driving integrated mast architecture adoption. METI coordinates dual-use technology development between commercial electronics and defense applications. The Nagoya-Tokyo industrial corridor concentrates precision manufacturing capacity for active electronically scanned array components.
Global Radar Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in transmitter and receiver fabrication. The vendor base organizes into three tiers: prime contractors bundling radar with electronic warfare subsystems; mid-tier array specialists competing on gallium nitride transmitter density; and commodity filter and antenna suppliers facing pricing compression. Dominant competitive moves include strategic partnerships for local assembly in indigenizing markets and technology licensing to circumvent export control restrictions.
Within the prime contractor tier, Raytheon Technologies Corporation and Lockheed Martin Corporation exemplify platform-level consolidation strategies. Thales Group occupies a position bridging European defense requirements with Middle Eastern export markets. These three entities represent divergent geographic anchoring and regulatory compliance approaches across NATO, EU AI Act, and FCC jurisdiction environments.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| BAE Systems plc |
| Leonardo S.p.A. |
| SAAB AB |
| L3Harris Technologies Inc. |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
High-purity gallium nitride wafer fabrication concentrates in Japan, the United States, and select European foundries, anchoring margin capture at the transmitter tier while squeezing downstream array integrators. This upstream chokepoint forces defense primes to absorb cost volatility or pass through via long-term fixed-price contracts indexed to substrate availability.
Pricing Analysis
The EU AI Act dictates the pricing tier structure by imposing compliance documentation burdens that stratify offerings across certified-transparent, standard-military, and legacy-analog levels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the weather monitoring segment is intensifying because commoditized hardware from Asian suppliers erodes brand premiums. Government civilian agencies exhibit highest price sensitivity due to budget cycles, while military fire-control programs show lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Gallium nitride substrates, silicon-germanium BiCMOS wafers, and specialized ferrite materials feed from concentrated sources in Japan, the United States, and Germany. Raw material dependencies span high-purity semiconductor substrates, rare-earth magnetic components, and precision-machined antenna arrays. Single-source vulnerability in GaN epitaxy equipment creates procurement risk for new transmitter entrants. Distribution runs through prime contractor platform bundling rather than standalone sensor sales, with NATO standardization agreements further constraining vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radar systems market functions as a defensive-moat arena where regulatory entrenchment through NATO interoperability mandates and FAA certification requirements protects incumbent positions. Switching costs lock customers into multi-decade platform relationships.
For Market Incumbents: Harden supply security through captive gallium nitride substrate partnerships or backward integration into epitaxy equipment. Deepen algorithmic transparency documentation capabilities ahead of expanding EU AI Act enforcement. Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the consolidation trajectory that new entrants must overcome. For New Entrants and Emerging Players: India's defense indigenization corridors present the most penetrable geographic entry point given PLI scheme incentives and technology transfer requirements. Weather radar modernization across Southeast Asia offers second-tier opportunity with lower certification barriers. Pursue joint venture structures with local electronics manufacturers to circumvent import substitution friction. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier array specialists with demonstrated gallium nitride transmitter density and established relationships with platform integrators. Long-term viability hinges on positioning within integrated mast architectures rather than standalone sensor competition. Watch for FCC spectrum reallocation decisions affecting C-band operations as an inflection signal for filter technology investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Transmitter Technology Licensing | Enables mid-tier defense platforms to achieve active array performance at reduced cost points. |
| Local Assembly Partnership Formation | Navigates India's PLI scheme requirements while accessing government procurement pipelines. |
| Algorithmic Transparency System Development | Positions contractors for EU AI Act compliance in French and German naval fire-control programs. |
| Integrated Mast Architecture Integration | Aligns with United States Navy surface combatant procurement consolidation trends. |
| Dual-Use Spaceborne Platform Convergence | Captures shared Earth observation and defense surveillance demand from commercial constellations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, SEC contractor filings, and NATO standardization agreement documentation. Primary interviews engaged platform integration engineers at prime contractors, procurement officers at national meteorological services, and regulatory compliance leads at European defense ministries. Secondary validation drew from Pentagon budget justification materials, FAA equipment mandate records, and EU AI Act implementation guidance. Bottom-up segment sizing triangulates against top-down defense expenditure allocation models.
Forecast inputs include platform retirement schedules, spectrum reallocation timelines, and indigenization policy implementation rates across the projection horizon. Segmentation dimensions span platform type, signal processing architecture, mission profile, and procurement authority. CAGRs derive from installed base replacement cycles and technology refresh intervals. GaN substrate supply expansion and software-defined architecture adoption curves inform growth trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed entrants or accelerated FCC spectrum auctions would shift outcomes. Cross-checking against Pentagon budget request documentation and national meteorological service capital expenditure plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Security Bottles Market
Others
South America Orange Market
Others
Europe Legal Services Market
Others
Asia-Pacific Air Separation Unit Market
Others
Latin America Smart Home Market
Others
Smart TV Platforms Market
Others
Global Tobacco Market
Others
Global Luxury High End Furniture Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Folding Smartphone Market
Others
DNA Data Storage Market
Others
Wearable Brain Devices Market
Others
Next Gen Video Codecs Market
Others
Global Military and Aerospace Sensors Market
Others
Buchner Funnels Market
Others
Smart Home Technologies Market