
 North America Automotive LED Lighting Market | 2026-2036
North America Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive LED Lighting Market Insights
A capital-intensity divergence between players is rotating competitive advantage toward suppliers with captive semiconductor and optical component production. Marelli Holdings Co., Ltd. leverages its integrated electronics division to control LED driver architecture and thermal management subsystems. Koito Manufacturing Co., Ltd. sustains dominance in headlamp assembly through long-standing supply agreements with Japanese transplant factories across the U.S. Southeast. Valeo SA competes by extending its software capabilities into adaptive beam-pattern control, a segment where hardware margins compress.
Automotive LED lighting denotes solid-state illumination systems employing semiconductor diodes with typical luminous efficacy exceeding 100 lumens per watt, operating through electroluminescence in gallium nitride substrates to generate directional light for vehicle exterior and interior functions. These systems replace halogen and xenon architectures to reduce energy draw on alternators and enable precise optical beam shaping for safety and styling differentiation. Headlights command the largest value share among product types, though matrix LED and adaptive LED technologies capture expanding margin pools as OEMs bundle them with advanced driver-assistance systems. Passenger vehicles anchor application volume, while commercial vehicles and heavy-duty trucks represent faster-growing adoption curves as fleet operators prioritize total cost of ownership reductions through reduced maintenance and improved nighttime visibility.
NHTSA Federal Motor Vehicle Safety Standard 108 governs photometric performance and equipment requirements, while EPA Corporate Average Fuel Economy regulations indirectly incentivize LED adoption through parasitic load reduction. Canadian regulators under Transport Canada align with U.S. lighting standards, creating a harmonized compliance corridor that simplifies cross-border component flows. Stakeholders must monitor pending NHTSA rulemaking on adaptive driving beam legality, as full market access for matrix headlamps hinges on federal permitting rather than state-level variance.
Market Dynamics
Adaptive beam-pattern control systems are compressing hardware margins while concentrating value capture among suppliers with integrated software-electronics capabilities across the North American automotive LED lighting market.
Growth Catalysts
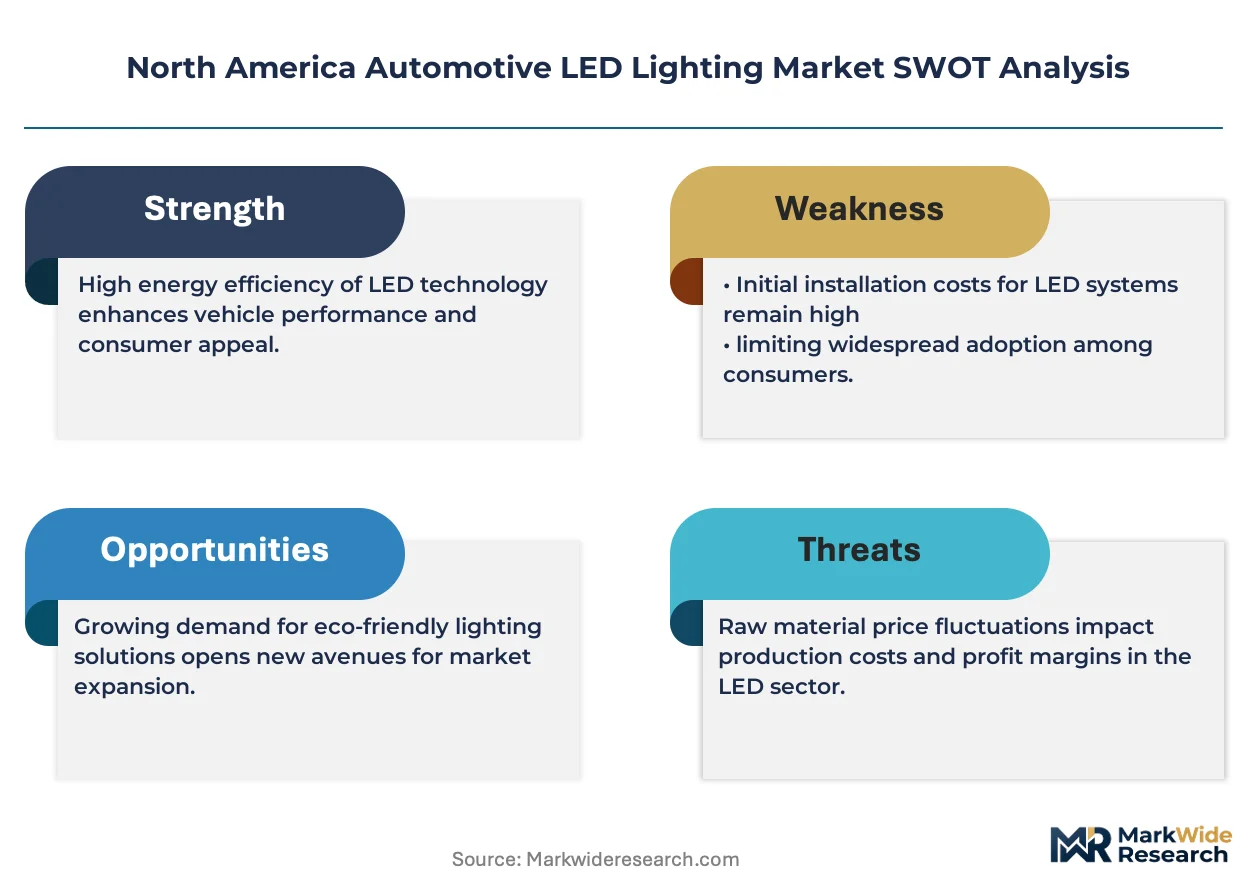
- NHTSA Federal Motor Vehicle Safety Standard 108:Photometric performance mandates are phasing out incandescent architectures and compelling OEM platform redesigns toward solid-state illumination.
- EPA Corporate Average Fuel Economy regulations:Parasitic load reduction requirements are accelerating LED adoption as manufacturers seek alternator efficiency gains.
- Matrix LED technology:Precision optical beam shaping is enabling bundling with advanced driver-assistance systems across premium and mid-range vehicle platforms.
Market Restraints
- Gallium nitride substrate supply concentration:Semiconductor material bottlenecks in Asian wafer fabrication are constraining driver IC availability for North American module assemblers.
- Pending NHTSA adaptive driving beam rulemaking:Federal permitting delays for matrix headlamp legality are fragmenting market access and freezing platform certification timelines.
- High-intensity discharge xenon residual stock:Aftermarket inventory liquidation in the US Southeast is prolonging price pressure on entry-level LED retrofits.
Strategic Opportunities
- Commercial vehicle and heavy-duty truck segments:Fleet operators in Ontario and Ohio are prioritizing total cost of ownership reductions through reduced maintenance intervals and improved nighttime visibility.
- Software-defined lighting architectures:Convergence of adaptive beam control with vehicle-to-infrastructure communication protocols is opening subscription revenue streams for pattern customization.
- Transport Canada harmonization corridor:Aligned lighting standards with US regulations are simplifying cross-border component flows for Michigan and Ontario supply bases.
Industry Challenges
- Thermal management engineering talent scarcity:LED driver architecture optimization requires specialized electroluminescence physics expertise that outpaces regional university pipeline output.
- Legacy halogen platform integration complexity:Retrofit compatibility with existing wiring harnesses and control modules is extending OEM validation cycles.
- Cross-state enforcement variance:NHTSA federal permitting for adaptive driving beams faces implementation friction from state-level inspection protocol inconsistencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive LED Lighting Market |
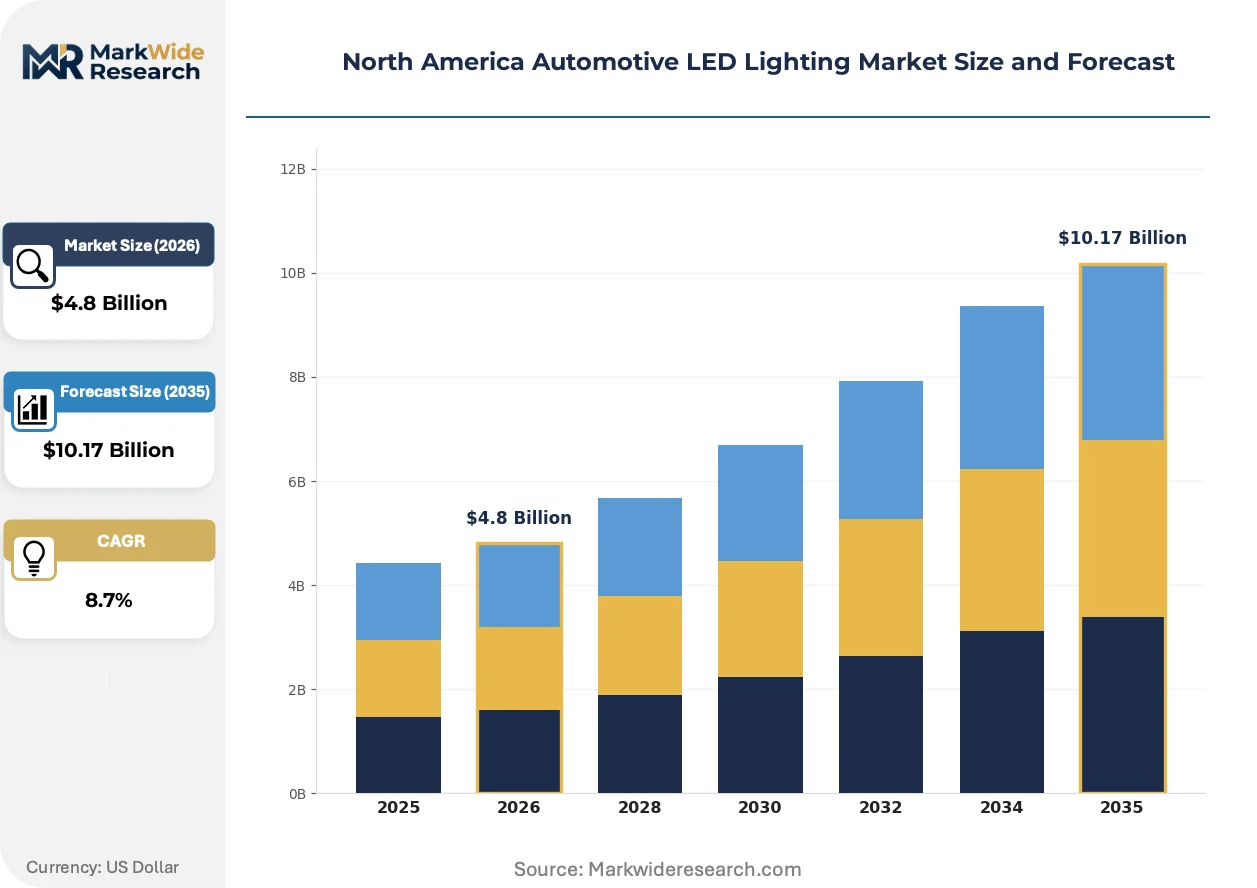
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Turn Signal Lights Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Technology: Standard LED, Matrix LED, Adaptive LED, OLED End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., Valeo SA, Hella GmbH & Co. KGaA, ams-OSRAM AG, Hyundai Mobis Co., Ltd., Denso Corporation, Koito Manufacturing Co., Ltd., Varroc Engineering Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive LED Lighting Market Trends and Innovations
Semiconductor-electronics convergence is redrawing competitive boundaries across the North American automotive LED lighting value chain, with software capabilities now determining margin capture more than optical component manufacturing scale.
Micro-LED pixel arrays are displacing conventional LED chip-on-board architectures in headlamp assemblies by enabling 10,000+ individually addressable light points for precise glare-free beam shaping. Tier-1 suppliers in Michigan and Ohio are accelerating platform integration timelines as OEMs bundle these systems with camera-based adaptive driving functions. This displacement is compressing commodity LED package margins while expanding value pools for thermal management and driver IC design.
NHTSA pending rulemaking on adaptive driving beam legality is creating regulatory uncertainty that fragments product launch timelines across US and Canadian markets. The industrial consequence is a bifurcation between early adopters pursuing conditional compliance certifications and conservative players awaiting federal permitting clarity. Premium passenger vehicle platforms face the greatest exposure, with some OEMs diverting matrix headlamp volumes to European markets where ECE regulations already permit full functionality.
Direct procurement relationships between Detroit-area assemblers and semiconductor foundries are shortening traditional Tier-1 mediation in LED driver supply chains. Japanese transplant factories across the US Southeast are pioneering this disintermediation, negotiating gallium nitride wafer allocations independently of legacy lighting module suppliers. This pattern is most visible in Tennessee and Alabama, where captive electronics divisions of integrated automotive groups are capturing margin previously held by optical component specialists.
North America Automotive LED Lighting Market Segmentation
Channel economics in North American automotive LED lighting vary sharply across product and customer types. OEM procurement concentrates in long-term platform contracts with embedded software requirements, while aftermarket flows through distributor networks with shorter inventory cycles.
Product Type:
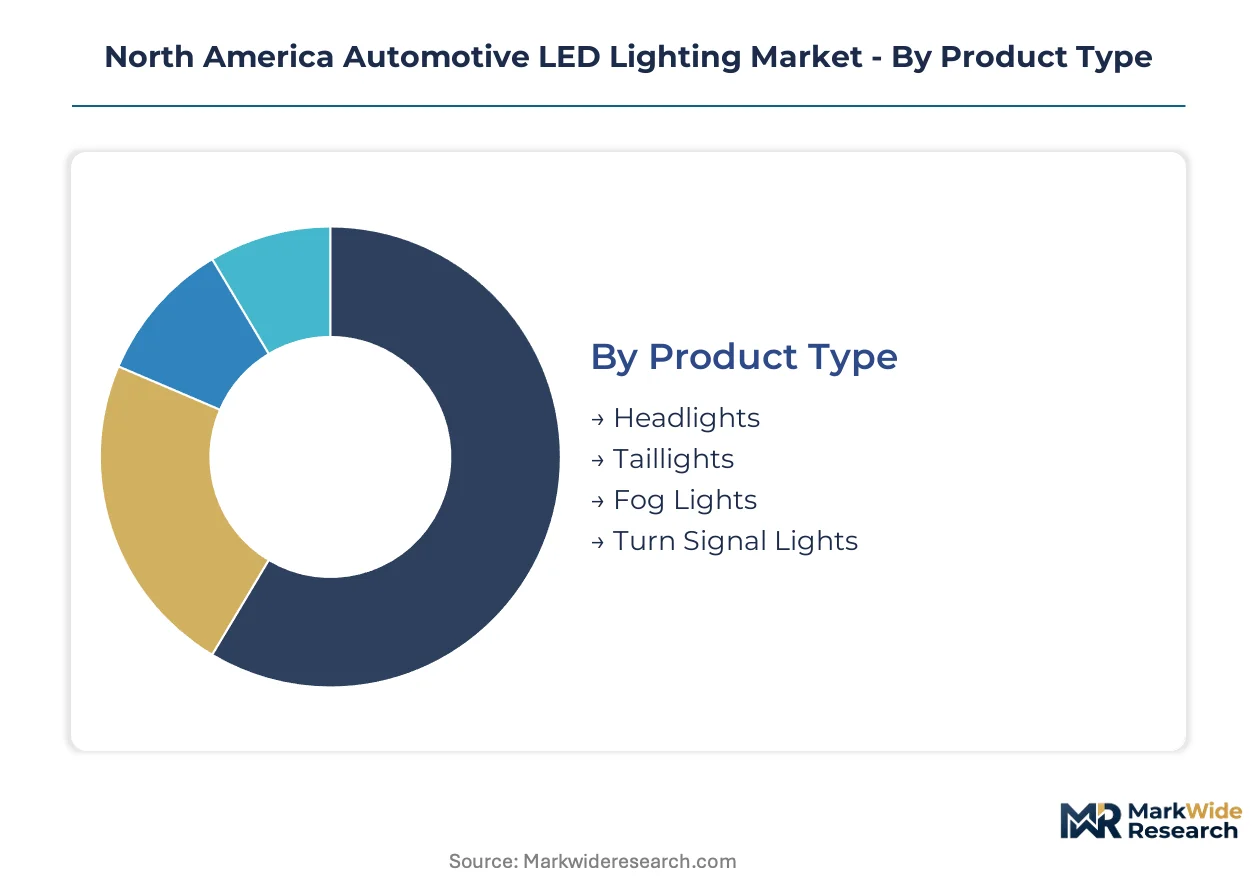
Headlights and taillights flow through distinct channel structures, with OEM direct procurement dominating high-value assemblies and aftermarket distributors capturing replacement demand.
- Headlights:Matrix LED and adaptive beam architectures incorporate gallium nitride driver ICs and thermal management subsystems. Michigan and Ohio OEMs bundle these with camera-based ADAS platforms, though NHTSA pending rulemaking on adaptive driving beam legality constrains full functionality deployment.
- Taillights:Sequential and animated signaling functions employ addressable LED strips for styling differentiation. Japanese transplant factories across Tennessee and Alabama specify these for premium passenger vehicle platforms where rear illumination serves brand recognition.
- Fog Lights:Compact auxiliary units prioritize beam penetration in low-visibility conditions. Fleet operators in Ontario specify these for commercial vehicle safety compliance.
- Turn Signal Lights:Dynamic sweeping indicators replace static flashers across mid-range and premium segments. Aftermarket retrofit demand concentrates in the US Southeast where xenon residual inventory liquidation creates price pressure.
Headlights dominate installed base. Taillights are where expansion concentrates.
Application:
Volume distribution across vehicle classes reflects divergent procurement authority structures, with fleet operators exercising consolidated purchasing power distinct from individual consumer decision-making.
- Passenger Vehicles:Mid-range and premium platforms drive matrix LED adoption as OEMs compete on styling and safety bundling. EPA Corporate Average Fuel Economy regulations accelerate LED adoption for parasitic load reduction across Detroit-area assembler lineups.
- Commercial Vehicles:Fleet operators in Ohio and Ontario prioritize total cost of ownership through reduced maintenance intervals and improved nighttime visibility. Heavy-duty specifications increasingly mandate LED architectures for durability.
- Motorcycles:Compact form factors favor LED miniaturization for headlamp and taillight integration. State-level inspection protocol variance creates compliance fragmentation for adaptive beam aftermarket retrofits.
- Heavy-Duty Trucks:Extended operational hours demand thermal management robustness in driver IC design. Canadian Transport Canada harmonization with US standards simplifies cross-border component flows for Ontario-based fleet suppliers.
Passenger vehicles anchor volume. Heavy-duty trucks are climbing the fastest as fleet operators consolidate procurement specifications.
Technology:
Margin capture redistributes across the value chain as software capabilities displace optical component manufacturing scale in competitive positioning.
- Standard LED:Commodity chip-on-board architectures face margin compression from micro-LED displacement. Entry-level retrofits compete with liquidating HID xenon aftermarket inventory in price-sensitive segments.
- Matrix LED:10,000+ individually addressable light points enable glare-free beam shaping. Tier-1 suppliers in Michigan accelerate platform integration as OEMs bundle with camera-based adaptive driving functions.
- Adaptive LED:Real-time beam-pattern control requires integrated electronics-software capabilities. NHTSA federal permitting delays fragment product launch timelines between early adopters and conservative players.
- OLED:Thin-film organic electroluminescence enables surface-area illumination for distinctive styling signatures. Premium passenger vehicle platforms in the US Southeast specify these for brand differentiation.
Standard LED dominates installed base. Matrix LED is where margin expansion concentrates.
End User:
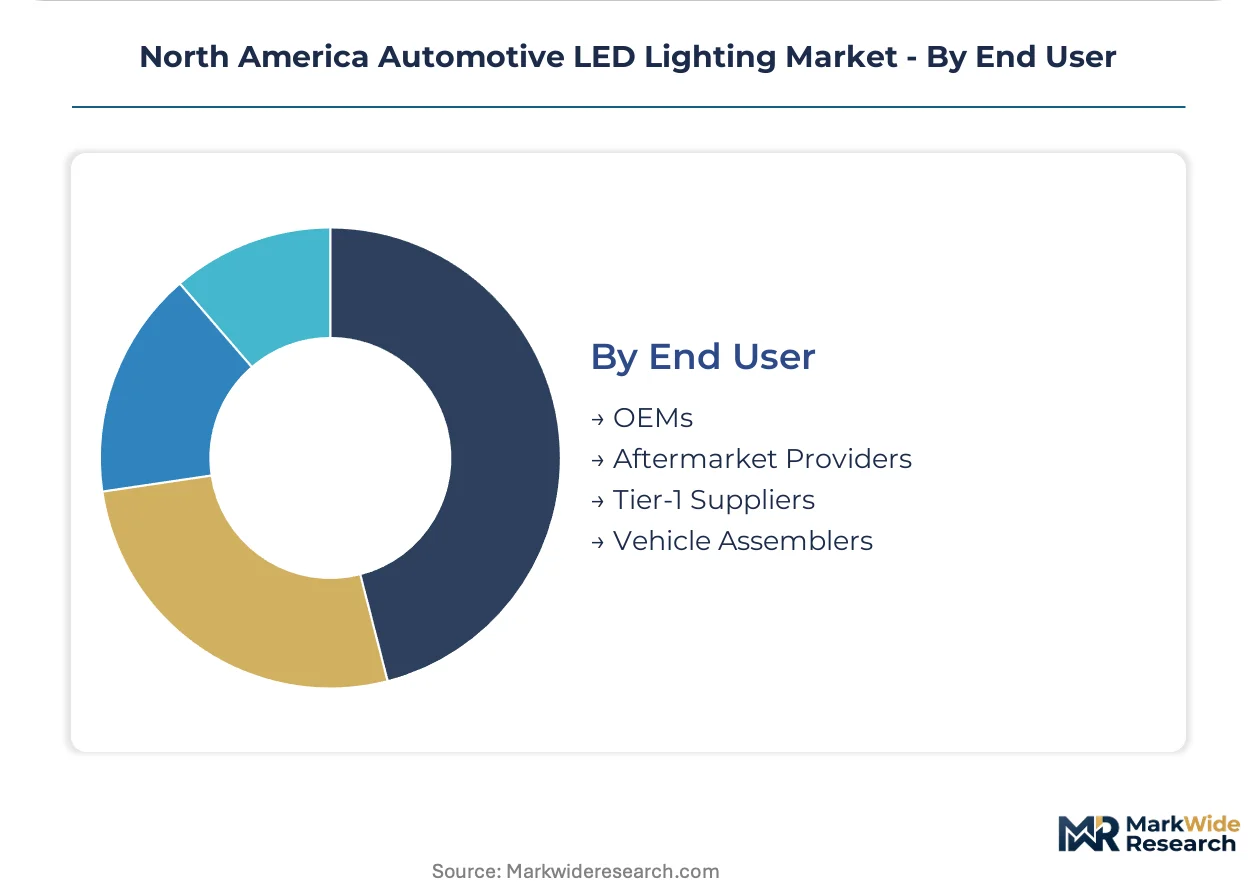
Procurement authority concentration varies sharply, with integrated automotive groups shortening traditional Tier-1 mediation through direct semiconductor foundry relationships.
- OEMs:Detroit-area assemblers specify platform-integrated lighting architectures with embedded thermal management. Long-term supply agreements lock in adaptive beam technology roadmaps contingent on NHTSA rulemaking resolution.
- Aftermarket Providers:Distributor networks serve replacement demand with compatibility constraints across legacy halogen wiring harnesses. Inventory cycles remain shorter than OEM platform procurement timelines.
- Tier-1 Suppliers:Module assemblers face margin pressure from disintermediation as Japanese transplant factories negotiate gallium nitride wafer allocations independently. Captive electronics divisions of integrated groups capture previously held optical component margins.
- Vehicle Assemblers:Transplant factories across Tennessee and Alabama pioneer direct semiconductor procurement, shortening legacy lighting supplier mediation in driver IC supply chains.
OEMs dominate procurement value. Aftermarket providers are gaining share fastest as vehicle age extends replacement cycle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada commands pricing power through Transport Canada harmonization with NHTSA standards, while Mexico's maquiladora clusters compete on assembly cost for entry-level LED modules destined for US aftermarket channels.
United States
Detroit-area assemblers in Michigan and Ohio drive OEM procurement of matrix LED headlamps bundled with camera-based ADAS platforms. NHTSA pending rulemaking on adaptive driving beam legality fragments product launch timelines between early adopters and conservative players. Tier-1 suppliers cluster in the Great Lakes automotive corridor, where thermal management engineering talent scarcity constrains driver IC optimization.
Canada
Ontario-based fleet operators prioritize total cost of ownership reductions through LED adoption in commercial vehicles and heavy-duty trucks. Transport Canada lighting standards alignment with US regulations simplifies cross-border component flows for Michigan and Ontario supply bases. Automotive LED module assemblers concentrate in Windsor and Toronto metro areas serving Detroit-area OEMs.
Mexico
Maquiladora assembly plants in Nuevo León and Chihuahua produce entry-level LED retrofits for US aftermarket distributor networks. Mexican manufacturing cost advantages attract HID xenon inventory liquidation pressure from residual aftermarket stock. Border state logistics corridors expedite component flows to Texas and California distribution hubs.
North America Automotive LED Lighting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American automotive LED lighting market. Consolidation concentrates around integrated automotive groups with captive electronics divisions, while fragmentation persists among optical component specialists facing margin compression from semiconductor-electronics convergence. Two strategic archetypes dominate: vertically integrated systems integrators controlling LED driver architecture, and scale-focused module assemblers competing on manufacturing efficiency. Dominant competitive moves include backward integration into gallium nitride wafer supply chains and strategic partnerships for adaptive beam software licensing.
Within the integrated systems tier, Marelli Holdings Co., Ltd. and Koito Manufacturing Co., Ltd. exemplify divergent geographic positioning strategies. Marelli leverages its electronics division heritage to anchor software-electronics capabilities in adaptive beam-pattern control. Koito occupies a position sustained through long-standing supply relationships with Japanese transplant factories across the US Southeast. Valeo SA represents the European specialist archetype competing through software extension into margin-compressing hardware segments.
| Leading Market Players |
|---|
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| Valeo SA |
| Hella GmbH & Co. KGaA |
| ams-OSRAM AG |
| Hyundai Mobis Co., Ltd. |
| Denso Corporation |
| Koito Manufacturing Co., Ltd. |
| Varroc Engineering Ltd. |
| Others |
Pricing and Supply Chain Analysis
Micro-LED pixel arrays displacing conventional chip-on-board architectures are redrawing supply geography toward Michigan and Ohio thermal management clusters while compressing commodity package margins and expanding premium capture for driver IC design.
Pricing Analysis
The customization-premium spread between matrix LED configured-to-order architectures and standard LED retrofits runs through three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on NHTSA adaptive driving beam certification status and gallium nitride driver IC integration depth. Cost compression in entry-level retrofits is intensifying because HID xenon residual inventory liquidation in the US Southeast prolongs price pressure. Fleet operators in Ontario and Ohio exercise least price sensitivity for heavy-duty specifications, while aftermarket distributors serving replacement demand face greatest buyer resistance.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port congestion constrain gallium nitride wafer flows from Taiwanese and South Korean foundries to Michigan module assemblers. The North American automotive LED lighting supply chain draws from Japan for optical component precision manufacturing, China for substrate material processing, and domestic Great Lakes clusters for final assembly integration. Single-source vulnerability in gallium nitride wafer fabrication creates exposure to Asian semiconductor bottlenecks. Distribution runs through Detroit-area OEM direct procurement for platform-integrated systems and regional distributor networks for aftermarket replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America automotive LED lighting market sits in a cyclical recovery phase as NHTSA adaptive driving beam rulemaking resolution will unlock pent-up platform certification demand across premium passenger vehicle segments.
For Market Incumbents: Shield software-electronics capabilities through captive thermal management engineering talent acquisition in Michigan and Ohio, where university pipeline output lags LED driver architecture optimization requirements. Deepen backward integration into gallium nitride wafer supply chains to offset Japanese transplant factory disintermediation threats in Tennessee and Alabama.
For New Entrants and Emerging Players: Differentiate on commercial vehicle and heavy-duty truck fleet specifications in Ontario and Ohio, where total cost of ownership procurement authority concentrates replacement cycle demand. Target aftermarket retrofit compatibility solutions for legacy halogen wiring harness integration complexity, leveraging shorter inventory cycles than OEM platform timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated automotive groups with captive electronics divisions controlling LED driver architecture and adaptive beam software licensing positions. Over the medium-term horizon, acquisition targets should demonstrate platform-integrated thermal management subsystems and long-term supply agreements with Detroit-area assemblers. The signal to monitor is NHTSA federal permitting clarity for matrix headlamp legality, which would trigger accelerated OEM procurement commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Wafer Supply Agreement | Captive semiconductor sourcing insulates Michigan assemblers from Asian fabrication bottlenecks. |
| Adaptive Beam Software Licensing Partnership | Valeo SA extends electronics capabilities into margin-expanding pattern control beyond hardware. |
| Thermal Management Engineering Center | Regional talent concentration in Ohio addresses LED driver optimization expertise scarcity. |
| Cross-Border Component Flow Harmonization | Transport Canada alignment simplifies Michigan-Ontario supply base logistics integration. |
| Commercial Vehicle Fleet Specification Capture | Ontario and Ohio operators consolidate procurement for total cost of ownership reductions. |
Research Methodology
The analysis maps matrix LED, adaptive LED, standard LED, and OLED technology segments, each validated through Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations managers, and thermal management subsystem specialists. Primary interview intelligence triangulates against vehicle production databases, IHS Markit registration data, NHTSA Federal Motor Vehicle Safety Standard 108 filings, and EPA Corporate Average Fuel Economy regulatory disclosures. Bottom-up segment sizing and top-down market reconciliation ensure consistency across estimation approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derive from trend extrapolation of technology substitution curves and regulatory compliance timelines. Industry-specific forecast inputs include NHTSA rulemaking resolution probability weighting and gallium nitride wafer allocation constraints from Asian foundry capacity.
Material uncertainties — NHTSA adaptive driving beam permitting delays, gallium nitride substrate supply disruptions, and cross-state inspection protocol enforcement variance — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory resolution timing and semiconductor supply normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Basketball Apparel Market
Others
Singapore Retail Market
Others
Enterprise Video Content Management Market
Others
Europe Military 4D Printing Market
Others
North America Industrial Wearable Devices Market
Others
Dandelion Market
Others
Mini Pcs Market
Others
Augmented Reality in Energy and Utilities Market
Others
Radar Speed Signs Market
Others
Cloud Advertising Market
Others
Food Technology Market
Others
South America Orange Market
Others
Latin America Fire Sprinklers Market
Others
Magnesite Market
Others
Gym Wipes Market
Others
Rugged Tablet Market