
 Architectural Fabrics Market | 2026-2036
Architectural Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Fabrics Market Analysis
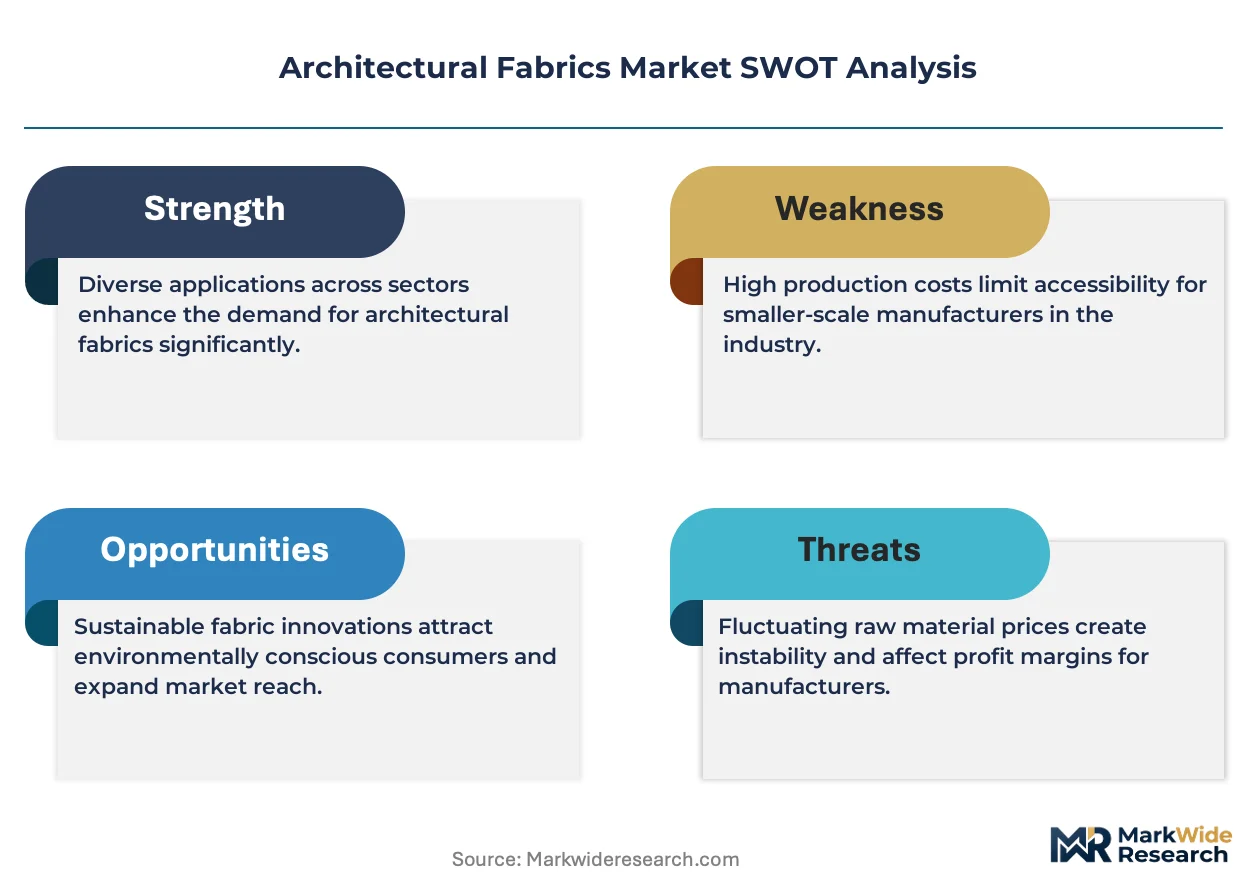
ISO 9001 quality management certification is rotating as the baseline threshold separating qualified membrane suppliers from speculative entrants in major tender processes. Saint-Gobain leverages its vertically integrated fluoropolymer chain to sustain margin control across PVDF-coated fabric grades. Serge Ferrari Group anchors its position through permanent installation expertise in airport and stadium contracts across France and the Gulf states. Taiyo Kogyo Corporation dominates the Asia-Pacific bid landscape with its proprietary PTFE-glass fiber composite technology.
Architectural fabrics are high-performance flexible membranes engineered from coated textiles—typically PTFE-impregnated fiberglass, silicone-coated glass, or PVC-laminated polyester—with tensile strengths exceeding 100 kN/m and designed to span large unsupported areas while transmitting controlled daylight. These materials serve as load-bearing skins for roofs, facades, and temporary enclosures where conventional rigid construction proves structurally inefficient or economically prohibitive. Tensile structures command the largest share of value given their engineering complexity and permanence requirements in aviation and sports infrastructure. Shade sails represent the fastest-expanding material category as municipalities prioritize urban heat mitigation and outdoor commercial viability. Facades are maturing into a margin-rich segment where architects specify multilayer breathable membranes with integrated LED and photovoltaic compatibility.
REACH compliance in Europe and the EU Green Deal's embodied-carbon reporting requirements through CSRD are elevating demand for recyclable polyester and bio-based coating alternatives while restricting legacy PVC formulations in public contracts. Germany's KBA-adjacent building codes and France's RT2012 thermal regulations further specify solar transmittance thresholds that only advanced metallized or ceramic-coated fabrics achieve. Stakeholders must monitor how rapidly evolving fire-safety standards in Saudi Arabia's SBC and the UAE's civil defense codes integrate with European EN 13501 classifications to determine which coating technologies qualify for premium project tiers.
Market Dynamics
Membrane engineering capability is concentrating among suppliers with captive fluoropolymer coating capacity, as project owners in Saudi Arabia and Qatar mandate ISO 9001 certification for tensile structure tenders exceeding specific square-meter thresholds.
Growth Catalysts
- FIFA and Olympic infrastructure deadlines:Sports venues across the Middle East are deploying permanent tensile roofs to meet completion timelines, creating sustained procurement pipelines for PTFE-glass fiber composites.
- Germany's Energy Efficiency Act:Solar-responsive shading mandates for new commercial buildings above defined floor thresholds are accelerating specification of metallized membrane systems in European tenders.
- Urban heat mitigation mandates:Municipalities in arid climate zones are prioritizing shade sail installations to enable outdoor commercial viability and reduce ambient temperatures in pedestrian corridors.
Market Restraints
- Fluoropolymer feedstock volatility:PVDF resin supply concentrates among specialty chemical producers, exposing membrane fabricators to input cost swings that compress margin buffers on fixed-price stadium contracts.
- Legacy PVC formulation restrictions:REACH compliance and CSRD embodied-carbon reporting requirements are disqualifying conventional coated polyester from public sector tenders across European Union member states.
- Technical limitation in fire-safety integration:Saudi Arabia's SBC and UAE civil defense codes are evolving faster than EN 13501 harmonization, creating certification gaps that delay project approvals.
Strategic Opportunities
- Photovoltaic-integrated facades:Multilayer breathable membranes with embedded solar cell compatibility represent an underpenetrated application segment where architects specify premium performance tiers.
- Recyclable polyester advancement:Bio-based coating chemistry aligned with EU Green Deal circularity targets offers a regulatory tailwind for suppliers repositioning away from fluorinated systems.
- Airport terminal modernization:Permanent installation expertise in aviation infrastructure is transferable to emerging markets in Southeast Asia where passenger volume expansion drives roof replacement cycles.
Industry Challenges
- Specialized installation labor scarcity:Tensile structure erection requires certified rigging crews and membrane tensioning specialists, creating project bottlenecks when multiple stadium deadlines converge.
- Multi-standard certification timelines:Qualifying fabrics for simultaneous EN 13501, SBC, and UAE civil defense approvals extends pre-qualification periods and strains technical documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Fabrics Market |
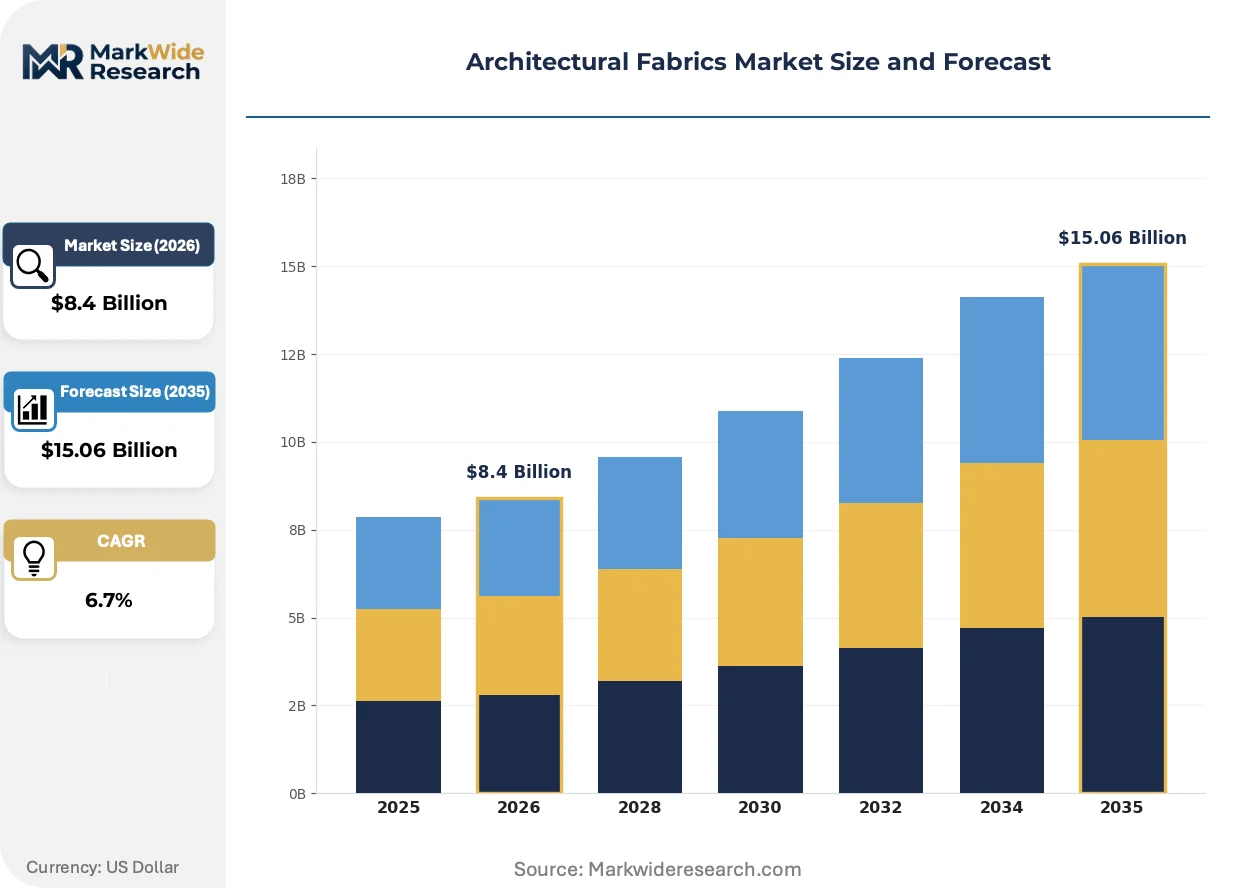
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Structures, Shade Sails, Canopies, Facades Material: Polyester, PVDF, PVC, Canvas Application: Commercial Buildings, Residential Structures, Sports Venues, Exhibition Halls Installation Type: Permanent, Temporary, Modular, Free-standing |
| Companies Covered | Serge Ferrari Group, Sioen Industries NV, Saint-Gobain, Sattler AG, Taiyo Kogyo Corporation, Verseidag-Indutex GmbH, Mehler Texnologies, Glen Raven, Inc., Heytex Bramsche GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Fabrics Market Emerging Trajectories
Material science advancement is fragmenting the competitive landscape into fluoropolymer incumbents and bio-based challengers, while regulatory pressure on embodied carbon forces coating chemistry reinvention.
PTFE-impregnated fiberglass membrane technology is bifurcating the market between permanent aviation and sports infrastructure requiring decades-long service life, and temporary or semi-permanent installations where silicone-coated glass alternatives gain specification share. Airport authorities in Germany and Japan continue specifying PTFE-glass fiber composites for terminal roofs exceeding fifty-year design life, while festival and exhibition venues in France adopt lighter-weight substitutes with accelerated replacement cycles.
CSRD embodied-carbon reporting requirements through the EU Green Deal are compelling membrane suppliers to quantify cradle-to-gate emissions and develop recyclable end-of-life pathways. Public procurement frameworks in Germany and France now weight environmental product declarations alongside technical performance in tender evaluations, disadvantaging legacy PVC-laminated polyester formulations.
Specification authority is migrating from general contractors to specialist tensile engineering consultants who control membrane selection through performance-based rather than brand-driven criteria. Stadium and airport project owners in the Gulf states increasingly retain independent facade engineers who specify coating grades and seam welding protocols independent of installer preferences, compressing brand loyalty and elevating technical documentation standards.
Architectural Fabrics Market Segmentation
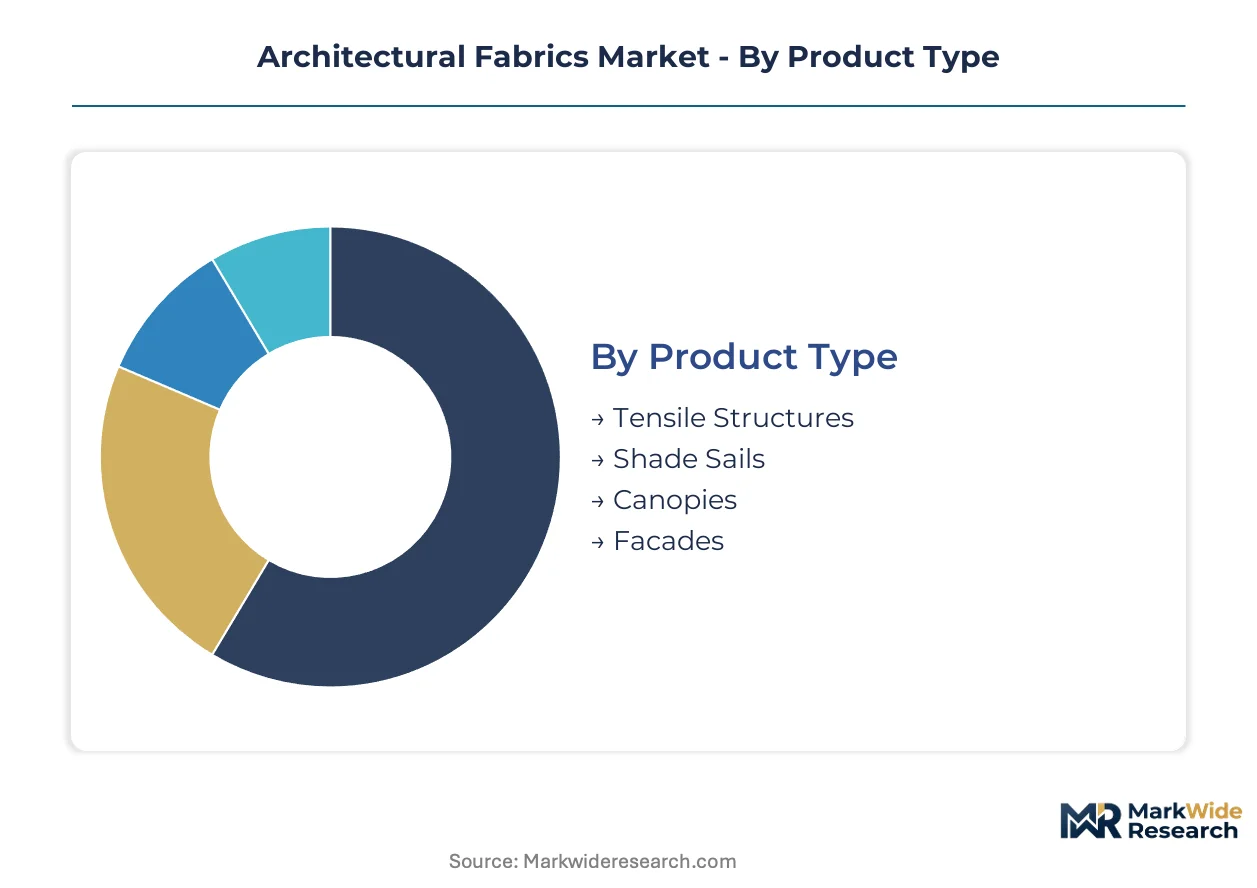
Architectural fabrics serve fundamentally different engineering requirements across load-bearing roofs, solar-responsive skins, and temporary enclosures. Segmentation reveals where specification authority concentrates and which material grades command premium positioning in procurement frameworks.
Product Type:
Margin pools concentrate in permanent infrastructure applications where decades-long service life justifies fluoropolymer-grade specifications and specialized installation expertise.
- Tensile Structures:PTFE-impregnated fiberglass membranes engineered for 50+ year design life span unsupported areas exceeding 100 meters. Demand concentrates in aviation terminals across Germany and Japan, driven by airport authorities specifying EN 13501-compliant fire performance for passenger safety.
- Shade Sails:Lightweight tensioned membranes prioritizing solar transmittance control and urban heat mitigation. Municipal procurement in Saudi Arabia's giga-project corridor and Qatari FIFA infrastructure is accelerating volume fastest as outdoor commercial viability becomes mandatory.
- Canopies:Semi-permanent shelter systems balancing weather protection with rapid deployment for exhibition and festival circuits.
- Facades:Multilayer breathable membranes with integrated LED and photovoltaic compatibility, commanding premium specification in commercial retrofits.
The dominant share belongs to Tensile Structures, while Shade Sails is closing the gap fastest.
Material:
Feedstock chemistry determines qualification for public tenders, with regulatory pressure on embodied carbon fragmenting competitive positioning between fluoropolymer incumbents and bio-based alternatives.
- PVDF:Fluoropolymer-coated textiles delivering superior UV resistance and self-cleaning properties for permanent aviation infrastructure. Saint-Gobain's vertically integrated supply chain sustains margin control as Saudi SBC and UAE civil defense codes elevate fire-safety thresholds.
- Polyester:Recyclable base material gaining specification share as CSRD reporting requirements and REACH compliance disqualify legacy formulations. Bio-based coating chemistry aligned with EU Green Deal circularity targets is repositioning this grade for European public contracts.
- PVC:Conventional laminated formulations facing procurement restrictions across EU member states under embodied-carbon frameworks.
- Canvas:Traditional cotton-based material retained for heritage restoration and temporary aesthetic installations.
PVDF retains the largest installed base, though Polyester is expanding most quickly on regulatory tailwinds.
Application:
End-use concentration follows infrastructure investment cycles, with sports and aviation commanding the longest procurement pipelines.
- Sports Venues:Permanent tensile roofs for FIFA and Olympic deadlines across Qatar and Saudi Arabia. PTFE-glass fiber composites dominate procurement as project owners mandate ISO 9001 certification above specific square-meter thresholds.
- Commercial Buildings:Germany's Energy Efficiency Act mandates solar-responsive shading for new builds above defined floor thresholds, accelerating metallized membrane specifications.
- Exhibition Halls:Temporary and modular installations favoring lighter-weight silicone-coated alternatives with accelerated replacement cycles.
- Residential Structures:Shade sails and small-format canopies for private outdoor spaces, price-sensitive and specification-light.
Sports Venues captures the dominant procurement volume, while Commercial Buildings is gaining share fastest on regulatory mandate density.
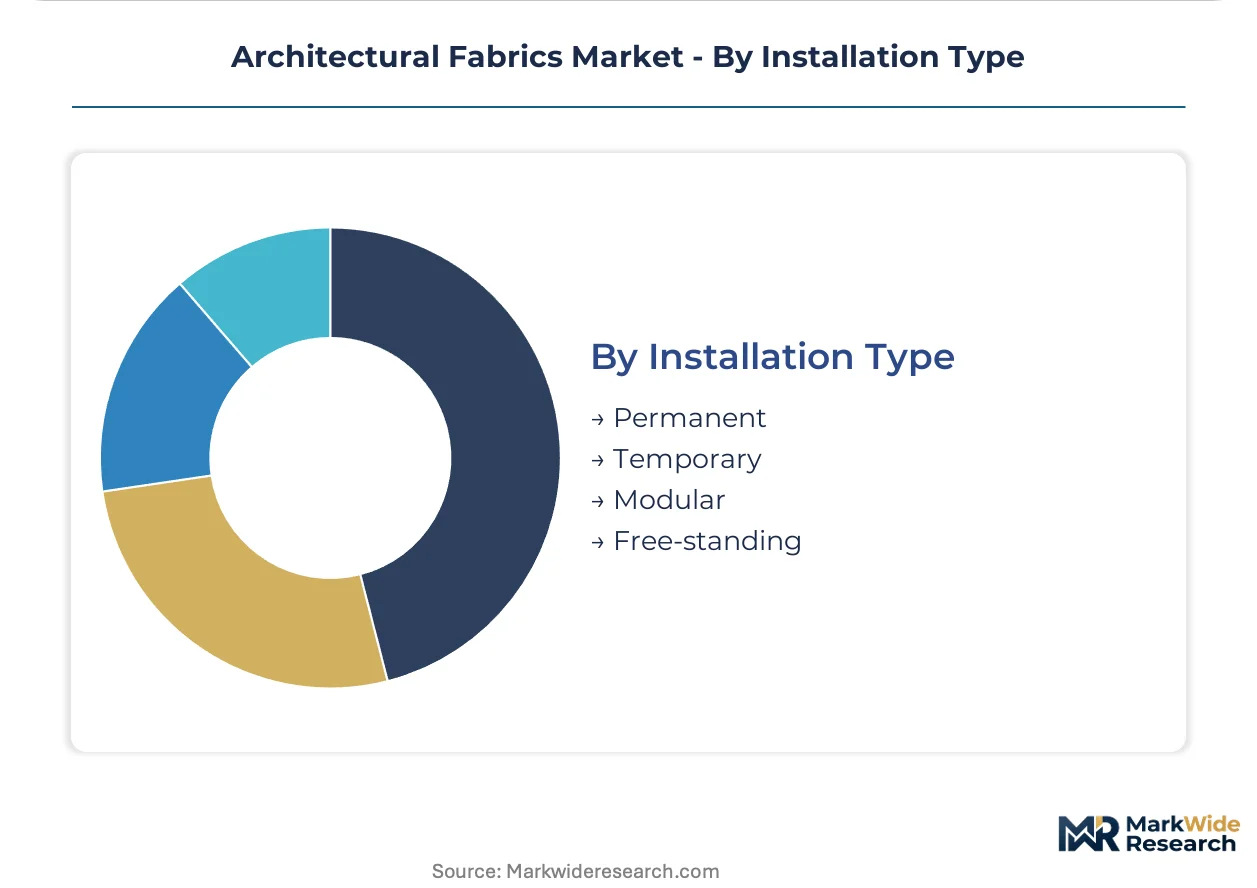
Installation Type:
Project duration and reuse potential determine labor specialization requirements and margin structure.
- Permanent:Requires certified rigging crews and membrane tensioning specialists, creating bottlenecks when multiple stadium deadlines converge. Airport authorities in Japan and Germany specify this grade exclusively for terminal modernization.
- Modular:Reconfigurable systems gaining traction in exhibition and festival circuits across France, balancing deployment speed with repeat-use economics.
- Temporary:Rapid-deployment shelters for event infrastructure with minimal foundation requirements.
- Free-standing:Self-supporting structures for pedestrian corridors and outdoor retail activation.
Permanent installation commands the dominant value share, while Modular is climbing the fastest on reuse economics and labor flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation authorities and sports infrastructure consortia concentrate procurement power across Germany, Japan, Saudi Arabia, Qatar, and the United States. These buyer archetypes mandate ISO 9001 certification and EN 13501 fire performance for permanent tensile installations exceeding defined square-meter thresholds.
Germany
Airport authorities in Frankfurt and Munich specify PTFE-glass fiber composites for terminal modernization programs requiring fifty-year design life. The country's Energy Efficiency Act mandates solar-responsive shading for new commercial builds above specific floor thresholds, accelerating metallized membrane specifications. KBA-adjacent building codes in Bavaria and North Rhine-Westphalia enforce solar transmittance thresholds that only advanced coated fabrics achieve.
Japan
Aviation infrastructure investment in Tokyo and Osaka drives specification of permanent tensile roofs for terminal expansion projects. METI procurement guidelines prioritize EN 13501-compliant fire performance for passenger safety in dense urban airports. The Kansai region hosts engineering consultants who control membrane selection through performance-based criteria independent of installer preferences.
Saudi Arabia
Giga-project developments in Neom and Qiddiya require millions of square meters of high-performance membrane for sports and entertainment infrastructure. The Saudi Building Code evolves fire-safety standards faster than EN 13501 harmonization, creating certification gaps that delay project approvals. Riyadh and the Eastern Province concentrate tender activity as FIFA and Olympic infrastructure deadlines approach.
Qatar
Post-World Cup aviation and hospitality expansion sustains procurement pipelines for permanent tensile structures. The country's civil defense codes integrate with European classifications to determine coating technology qualification for premium project tiers. Doha-based facade engineers specify seam welding protocols and coating grades independent of installer brand loyalty.
United States
Airport terminal modernization in Atlanta and Denver drives roof replacement cycles requiring certified rigging crews and membrane tensioning specialists. FAA procurement frameworks for aviation infrastructure emphasize permanent installation expertise transferable from European and Gulf state projects. The Southeast and Mountain West regions concentrate municipal shade sail deployment for urban heat mitigation.
Architectural Fabrics Market Vendor Landscape
Player mix skews toward vertically integrated chemical conglomerates and specialized membrane fabricators with captive fluoropolymer capacity. The market structure concentrates procurement qualification among suppliers with ISO 9001 certification and EN 13501 documentation resources. Three archetypes dominate: European chemical conglomerates with backward integration into coating feedstocks, Asia-Pacific specialists in PTFE-glass fiber composites, and regional fabricators serving temporary installation markets. Competitive moves center on captive supply of PVDF resin and strategic partnerships with tensile engineering consultants who control specification authority.
Among European-based suppliers, Saint-Gobain and Serge Ferrari Group exemplify the integrated archetype with upstream control over fluoropolymer chains. Taiyo Kogyo Corporation anchors the Asia-Pacific specialist position. These three occupy positions where project owners mandate specific certification thresholds for stadium and airport tenders exceeding defined square-meter minimums.
| Leading Market Players |
|---|
| Serge Ferrari Group |
| Sioen Industries NV |
| Saint-Gobain |
| Sattler AG |
| Taiyo Kogyo Corporation |
| Verseidag-Indutex GmbH |
| Mehler Texnologies |
| Glen Raven, Inc. |
| Heytex Bramsche GmbH |
| Others |
Supply Flow & Price Mechanics
PVDF resin substitution for legacy PVC coatings is redrawing supply geography toward captive fluoropolymer producers in France and Japan while compressing margin buffers for non-integrated fabricators locked into fixed-price stadium contracts.
Pricing Analysis
Cost-plus contracts with PVDF resin indexation dominate procurement for permanent tensile structures exceeding defined square-meter thresholds. Three-tier pricing structure across fluoropolymer-grade, silicone-coated, and PVC-laminated tiers reflects certification grade and volume scale. Pricing pressure stems from feedstock volatility as specialty chemical producers concentrate resin supply. Municipal shade sail buyers exhibit highest price sensitivity, while aviation authorities in Germany and Japan demonstrate lowest sensitivity given fifty-year design life requirements.
Supply Chain Analysis
Inventory lead times for PTFE-impregnated fiberglass extend when multiple FIFA and Olympic deadlines converge, creating certified rigging crew bottlenecks. Manufacturing concentrates in France, Japan, and Germany where captive coating capacity anchors production. Raw material flows draw from fluoropolymer resin specialists, glass fiber weavers, and metallized film suppliers. Single-source vulnerability in PVDF feedstock exposes fabricators to input cost swings. Distribution runs through specialist tensile engineering consultants who control membrane selection independent of installer preferences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent installation expertise and tensioning certification services are expanding faster than membrane hardware sales as project owners in Saudi Arabia and Qatar mandate ISO 9001-qualified rigging crews for complex stadium geometries.
For Market Incumbents: Secure captive fluoropolymer coating capacity to defend margin control against bio-based challengers gaining specification share under CSRD embodied-carbon frameworks. Reinforce permanent installation certification pipelines to capture service-attach revenue as FIFA and Olympic deadlines concentrate demand for qualified rigging crews. For New Entrants and Emerging Players: Anchor in recyclable polyester with bio-based coating chemistry to exploit regulatory tailwinds from EU Green Deal circularity targets. Target municipal shade sail procurement in Saudi Arabia's giga-project corridor where outdoor commercial viability mandates are accelerating volume fastest. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive resin capacity and EN 13501 documentation resources. Long-term viability hinges on positioning ahead of SBC-UAE civil defense code harmonization gaps closing. Watch for PTFE-glass fiber composite qualification thresholds tightening as Saudi Building Code evolution accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fluoropolymer Capacity Expansion | Saint-Gobain's backward integration into PVDF resin insulates margin control against feedstock volatility. |
| Recyclable Polyester Development | Bio-based coating chemistry aligned with REACH compliance repositions suppliers for EU public tenders. |
| Permanent Installation Certification Pipeline | ISO 9001-qualified rigging crew networks capture service-attach revenue from converging stadium deadlines. |
| Photovoltaic Facade Partnership | Multilayer breathable membrane compatibility with embedded solar cells opens premium commercial retrofit specification. |
| Gulf State Engineering Consultant Alliance | Strategic ties with Doha and Riyadh facade engineers secure performance-based specification authority. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across membrane fabricators, tensile engineering consultants, airport authority procurement officers, and municipal urban planning departments. Secondary validation drew from Saudi Building Code amendments, EU Green Deal circularity guidance, EN 13501 fire performance classifications, and customs data on fluoropolymer resin trade flows. Bottom-up project pipeline tracking across Neom, Qiddiya, and FIFA infrastructure timelines was triangulated with top-down coating chemistry demand modeling.
Across the analysis window, forecasts segmented by product type, material chemistry, installation duration, and application vertical were constructed using elasticity-adjusted growth rates derived from infrastructure investment cycles and regulatory mandate density. CAGRs reflect correlation between aviation passenger volume expansion, commercial building energy efficiency thresholds, and urban heat mitigation procurement intensity.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf state infrastructure investment and stable fluoropolymer resin supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Solar Panel Testers Market
Others
Aerospace Tester Market
Others
Europe Digital Experience Platform Market
Others
Level Measuring Instrument Market
Others
Middle East and Africa Home Care Packaging Market
Others
Buchner Funnels Market
Others
Smart Home Solutions Market
Others
North America Compressor Oil Market
Others
Africa Smart Card Market
Others
Hearables Market
Others
Mobile Computing Devices Market
Others
Global Telemetry Market
Others
Balsa Wood Market
Others
Paper Shredder Market
Others
Digital Education Projector Market
Others
US Luxury Travel Market