
 Dry-Cleaning and Laundry Services Market | 2026-2036
Dry-Cleaning and Laundry Services Market Size, Share, and Industry Trends Forecast 2026-2036
Dry-Cleaning and Laundry Services Market Intelligence
The rise of on-demand residential customers using online booking platforms is redrawing the competitive landscape traditionally dominated by walk-in household business. Digital-native providers like Rinse, Inc. specialize in this app-based model, offering convenience and logistical efficiency. Meanwhile, established players such as Cintas Corporation and Aramark sustain strong positions by focusing on large-scale commercial contracts with hotels and healthcare facilities. This creates a clear strategic split between business-to-consumer convenience and business-to-business scale.
Dry-cleaning and laundry services encompass professional textile care using non-aqueous solvents like hydrocarbon or specialized wet cleaning processes with biodegradable detergents. The primary purpose is to clean delicate fabrics, such as wool and silk, that would be damaged by traditional washing machines. On-demand platforms are gaining significant traction over traditional residential drop-off services, while self-service laundromats maintain a stable user base. Subscription pricing models are emerging as a key strategy for customer retention, challenging the conventional pay-per-use structure.
Environmental regulations are a primary force shaping operational standards across the industry. In the United States, the EPA's stringent rules on perchloroethylene use accelerate the shift to alternative solvents. Similarly, Europe's ECHA under the REACH framework and China's MEE enforce chemical safety and wastewater discharge limits, respectively. Operators must now decide whether to invest in advanced, compliant wet cleaning equipment or risk obsolescence from tightening environmental mandates.
Market Dynamics
The convergence of stringent environmental regulations and digital platform-based service models is the central force reconfiguring the dry-cleaning and laundry services market. This dual pressure compels operational investment in greener technologies while simultaneously altering customer acquisition and service delivery channels.
Growth Catalysts
- Commercial Sector Expansion:Sustained growth in the global hospitality and healthcare sectors, particularly in hotels and hospitals, creates consistent, high-volume demand for professional linen and uniform cleaning services.
- Sustainable Technologies:The development and adoption of professional wet cleaning systems using biodegradable detergents and advanced water filtration provides a key growth vector, appealing to environmentally conscious consumers and meeting regulatory mandates.
- Urban On-Demand Services:Rapid urbanization and the proliferation of mobile booking platforms in megacities like London and Shanghai are unlocking new residential demand by offering superior convenience over traditional drop-off locations.
Market Restraints
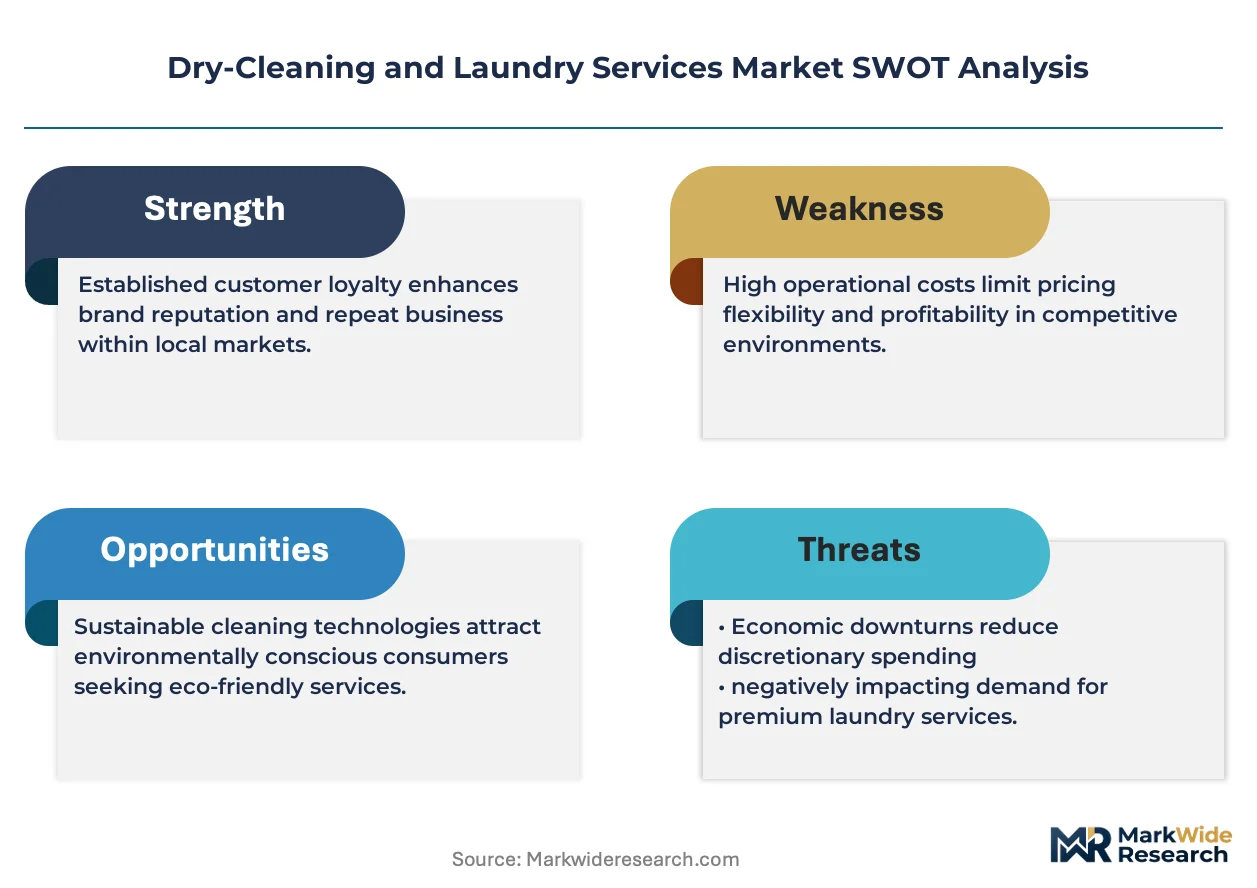
- High Capital Costs:The significant upfront investment required for modern, eco-friendly equipment, such as hydrocarbon or advanced wet cleaning machines, presents a substantial barrier for small, independent operators seeking to upgrade.
- Solvent Price Volatility:Fluctuations in the cost of specialized, green alternative solvents and biodegradable detergents create unpredictable operational expenses, impacting profit margins for cleaners who have moved away from traditional chemicals.
- Regulatory Compliance Burden:Phasing out legacy equipment to comply with mandates like the EPA's rules on perchloroethylene (PERC) imposes significant financial and logistical burdens on established businesses, slowing modernization.
Strategic Opportunities
- Subscription-Based Models:Implementing recurring subscription packages for residential customers offers a pathway to stabilize revenue streams, increase customer lifetime value, and improve logistical planning compared to traditional pay-per-item transactions.
- Specialized Textile Care:Developing expertise in cleaning high-value items, such as luxury fashion, technical outdoor gear, or corporate uniforms with embedded electronics, opens niche, high-margin service lines.
- B2B Vertical Integration:Offering integrated facility services for commercial clients, combining laundry with other services like janitorial or maintenance, can create stickier, larger contracts within the hotel and healthcare verticals.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians trained to operate and maintain sophisticated new solvent and wet cleaning machinery poses a significant operational bottleneck, limiting the speed of technological adoption.
- Digital Integration Friction:Integrating on-demand booking apps and logistics software with legacy, often manual, in-plant workflows is a primary challenge for traditional operators attempting to compete with digital-native startups.
- Energy and Water Costs:Rising utility prices directly impact operational costs, forcing service providers to invest in more efficient machinery or pass costs on to customers, which can affect competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry-Cleaning and Laundry Services Market |
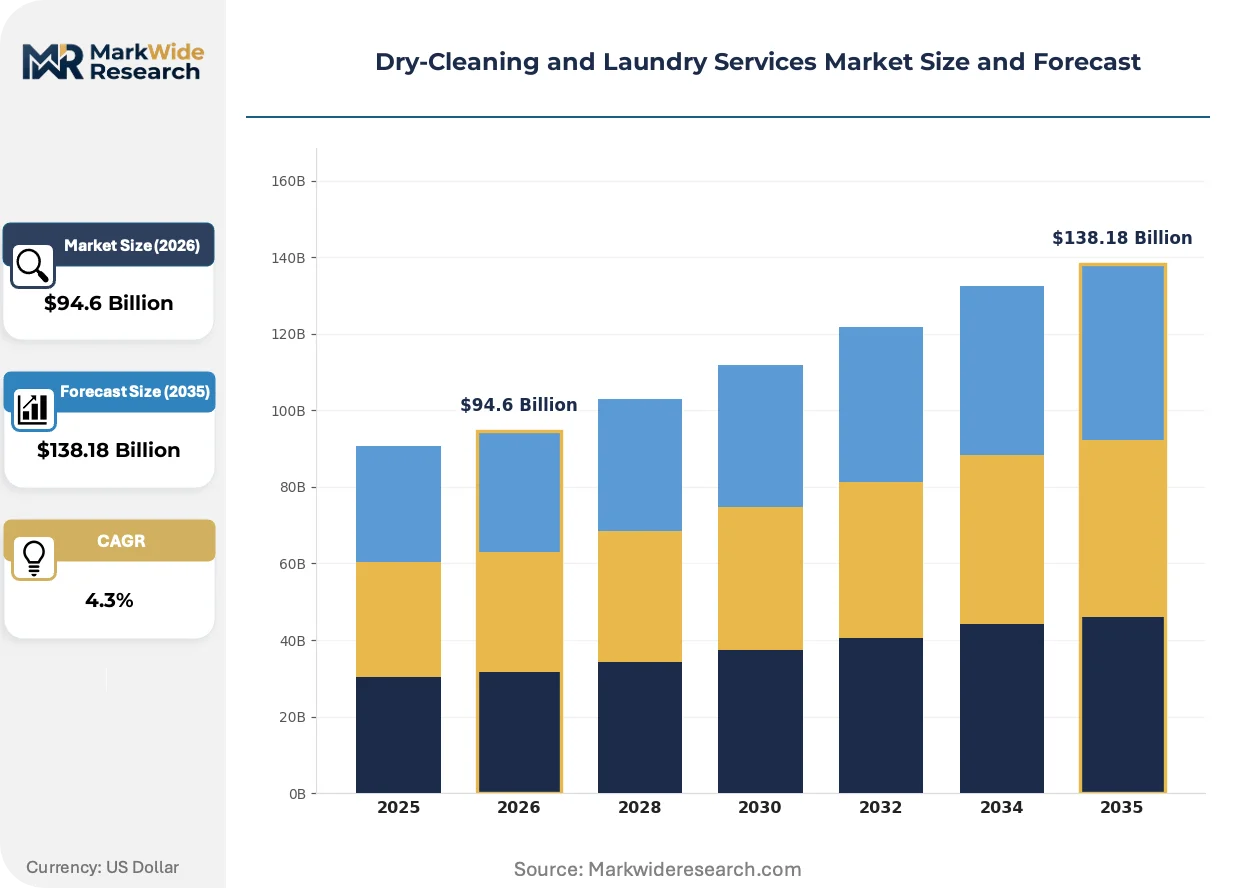
| Market Size in 2026 | $94.6 Billion |
| Market Size in 2035 | $138.18 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
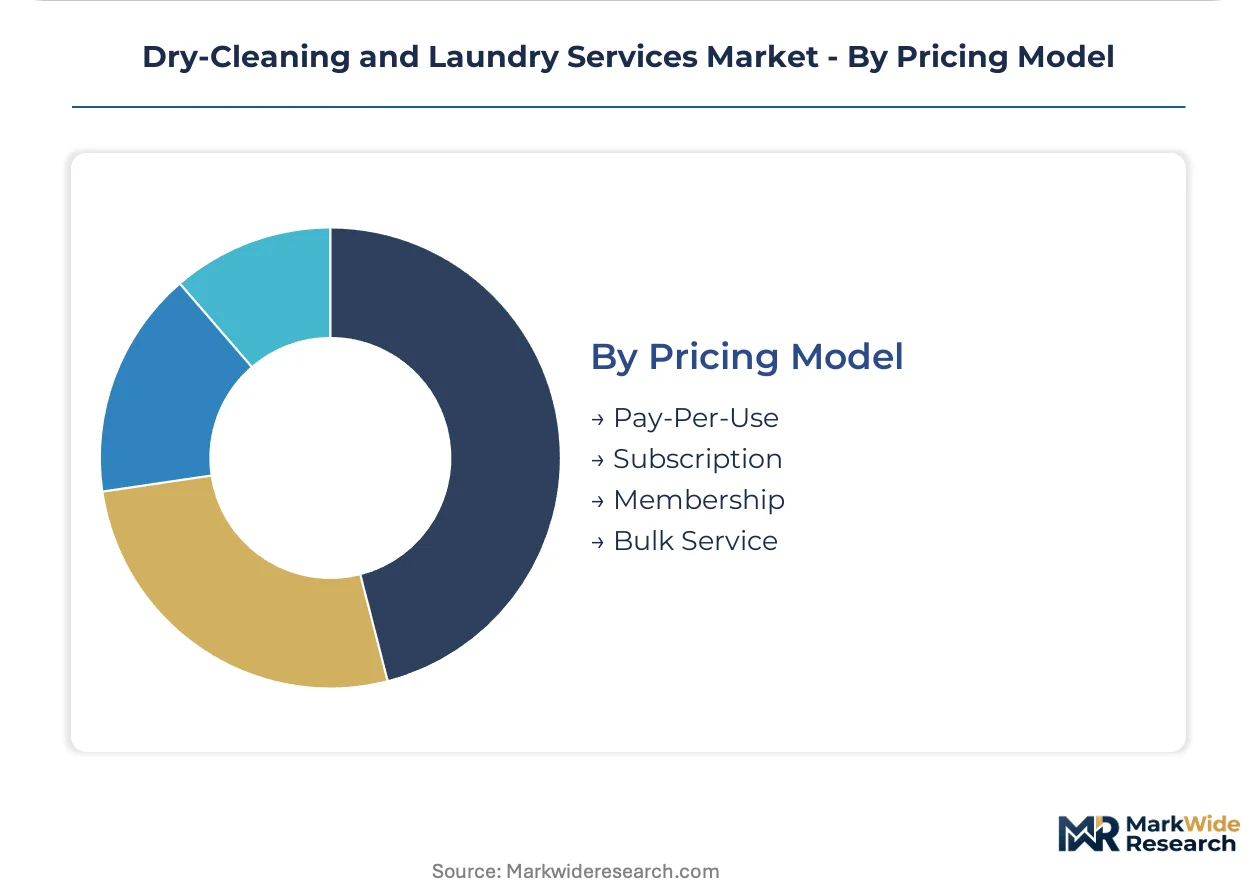
| Segmentation | Service Type: Residential, Commercial, On-Demand, Self-Service End User: Households, Hotels, Restaurants, Retail Stores Technology: Wet Cleaning, Dry Cleaning, Coin-Operated, Online Booking Pricing Model: Pay-Per-Use, Subscription, Membership, Bulk Service |
| Companies Covered | Alliance Laundry Systems LLC, Aramark, Cintas Corporation, Tide Cleaners, ZIPS Dry Cleaners, Alsco, Rinse, Inc., Elis SA, CSC ServiceWorks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry-Cleaning and Laundry Services Market Strategic Shifts & Innovations
The industry's evolution is defined by a technological pivot towards sustainability and efficiency, matched by a commercial shift towards service-oriented, digitally enabled business models. These forces are fundamentally changing how textile care is performed, sold, and delivered.
Technology and Equipment Evolution
Advanced water recycling and filtration systems are a critical component of modern wet cleaning operations. Commercial laundries and eco-conscious boutique cleaners are adopting this technology to comply with wastewater regulations and reduce utility consumption. This on-site water treatment technology is miniaturizing, enabling even small urban storefronts to deploy closed-loop systems that were once only feasible in large industrial plants.
Regulatory and Compliance Shifts
Europe's REACH regulation, enforced by the European Chemicals Agency (ECHA), places stringent controls on the use of certain chemical solvents in textile care. This directive forces operators across the European Union to meticulously document their chemical supply chains and accelerate the transition to approved alternatives. Small cleaners, especially in markets like France and Germany, are most affected, often relying on larger chemical suppliers for guidance on compliant formulations.
Demand and Service Model Shifts
A notable behavioral change is the consumer shift from one-off, transactional service purchases to subscription-based laundry plans. This model directly challenges the unpredictable revenue of traditional walk-in establishments by creating a predictable, recurring income stream. The trend is most pronounced in dense, affluent urban areas of North America and Western Europe, where convenience-focused digital platforms target busy professionals.
Dry-Cleaning and Laundry Services Market Segmentation
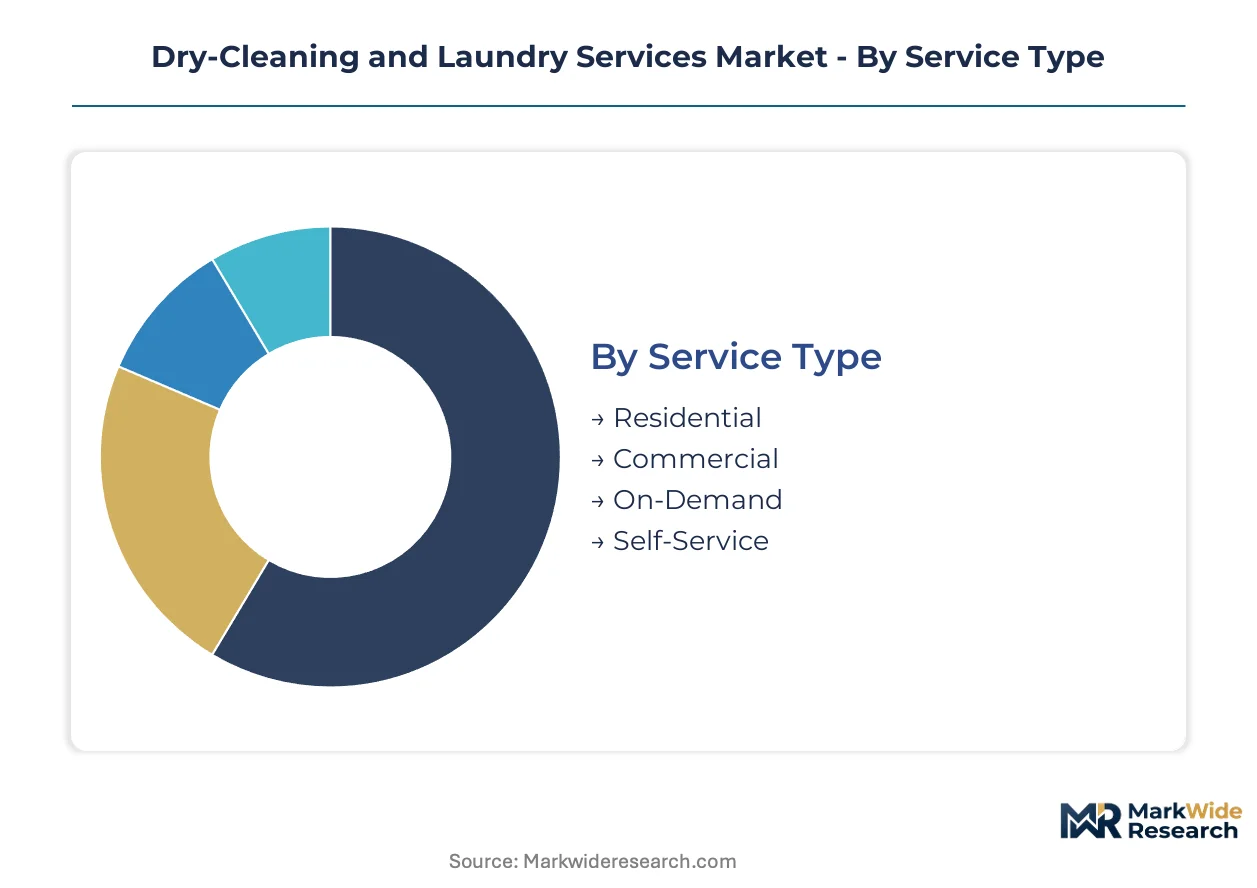
The Dry-Cleaning and Laundry Services Market is segmented to reveal the diverse operational models and customer needs driving its evolution. Understanding these distinct segments helps businesses tailor service offerings and investment strategies, from traditional household care to advanced commercial solutions.
Service Type:
The geographic spread of service types reveals distinct operational models, with some rooted in local community engagement and others extending across urban landscapes.
- Residential:This segment caters to individual households for everyday garment care, including washing, drying, and ironing of personal clothing. These services are widely available in suburban and urban communities globally, driven by convenience for busy individuals.
- Commercial:Commercial services encompass large-scale textile care for businesses such as hotels and hospitals, requiring consistent linen and uniform cleaning. Demand concentrates in major metropolitan areas like London and New York, driven by stringent hygiene standards and high volume requirements.
- On-Demand:On-demand services involve app-based collection and delivery, offering superior convenience for individual consumers seeking quick turnaround times. This model thrives in dense urban centers like Shanghai and Berlin, appealing to busy professionals seeking time-saving solutions.
- Self-Service:Self-service laundromats provide coin-operated or card-operated machines for customers to wash and dry their own laundry. This model maintains a stable presence in local communities, particularly in areas with high apartment densities or lower income demographics.
Commercial services hold the largest share; momentum sits with On-Demand services.
End User:
The volume of textiles processed varies significantly across different end-user segments, influencing operational scale and specialization.
- Households:Households represent the traditional customer base, requiring diverse garment care from everyday wear to special occasion items. Demand is stable across suburban and urban residential areas, driven by convenience and personal garment longevity.
- Hotels:Hotels require consistent, high-volume linen and uniform cleaning to maintain guest satisfaction and operational standards. Major hospitality hubs in Dubai and Paris generate substantial demand, necessitating rapid turnaround times and quality assurance.
- Restaurants:Restaurants need regular cleaning for tablecloths, napkins, uniforms, and kitchen linens to meet hygiene regulations and maintain aesthetic standards. Local demand for these services is consistent in urban dining districts across cities like Tokyo and Rome.
- Retail Stores:Retail stores utilize professional cleaning for staff uniforms, display items, and specialized textile care for high-value merchandise. This segment often requires specialized handling for delicate fabrics and brand-specific care instructions.
Households comprise the largest segment; Hotels are expanding most quickly.
Technology:
The maturity of technologies within the market ranges from established traditional methods to innovative digital solutions.
- Wet Cleaning:Wet cleaning utilizes water-based processes with biodegradable detergents, offering an environmentally friendly alternative to traditional dry cleaning. Adoption is accelerating in Europe due to ECHA regulations, particularly in Germany and France.
- Dry Cleaning:Dry cleaning employs non-aqueous solvents, historically perchloroethylene, to clean delicate fabrics that are sensitive to water. This method remains prevalent for specialized garments like wool and silk, particularly in markets with less stringent environmental mandates.
- Coin-Operated:Coin-operated technology refers to the payment and operation systems found in self-service laundromats, allowing customers direct access to washing and drying machines. This technology is foundational for self-service models, offering accessible and affordable options.
- Online Booking:Online booking platforms provide digital interfaces for scheduling laundry and dry-cleaning services, enhancing customer convenience. These systems are gaining traction in North America and Western Europe, driven by smartphone penetration and busy urban lifestyles.
Dry Cleaning remains a foundational technology; Online Booking exhibits the steepest expansion trajectory.
Pricing Model:
Pricing models are tailored to various customer types, from individual consumers to large commercial entities.
- Pay-Per-Use:Pay-per-use remains the most common model, where customers pay for services on a transactional basis for each item or load. This structure is ubiquitous across traditional laundromats and drop-off services, particularly in less affluent or rural areas.
- Subscription:Subscription models offer recurring service packages, providing predictable revenue streams for providers and cost savings for frequent users. This approach is prevalent among digital-native platforms targeting affluent urban residents in cities like San Francisco and Tokyo.
- Membership:Membership models offer exclusive benefits, discounts, or priority service to enrolled customers, often with an annual or monthly fee. These programs enhance customer loyalty and are adopted by premium dry-cleaning establishments.
- Bulk Service:Bulk service pricing is designed for high-volume commercial clients, offering discounted rates based on the quantity of laundry processed. This model is crucial for securing large contracts with hotels, hospitals, and other institutional clients.
Pay-Per-Use dominates the market; Subscription models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dry-cleaning and laundry services market sees service model innovations flowing from dense urban centers like New York and London to other metropolitan areas. Demand for professional textile care is driven by varying regulatory environments and consumer preferences across key global economies. This market structure reflects localized service delivery across distinct geographical landscapes.
United States
Demand for on-demand residential services and commercial contracts from hospitals fuels market activity in the United States. The EPA's stringent regulations on perchloroethylene use accelerate the shift towards alternative solvents and wet cleaning technologies. Major urban hubs like New York City and Los Angeles are seeing rapid expansion of app-based laundry services.
Germany
Commercial sector expansion, particularly in hospitality, drives demand for professional laundry services in Germany. Europe's ECHA under the REACH framework mandates strict chemical safety and wastewater discharge limits. Cities such as Berlin and Munich are adopting advanced wet cleaning systems to meet these environmental standards.
China
Rapid urbanization and a growing middle class are propelling demand for convenient residential and commercial laundry solutions in China. The MEE enforces chemical safety and wastewater discharge limits, pushing operators towards greener technologies. Megacities like Shanghai and Beijing are experiencing a surge in on-demand service platforms.
United Kingdom
The hospitality sector and busy urban professionals create strong demand for both commercial and on-demand residential services in the United Kingdom. Local environmental agencies are increasingly scrutinizing chemical use and waste disposal practices. London's dense urban environment is a prime market for subscription-based laundry models.
Japan
High demand for specialized textile care and convenience-driven residential services characterizes the market in Japan. METI encourages the adoption of energy-efficient and environmentally friendly technologies within the service sector. Tokyo's affluent urban population shows strong adoption of online booking and subscription laundry services.
Dry-Cleaning and Laundry Services Market Key Industry Players
Listed leaders compete with private specialists across commercial and residential segments, creating a tiered market structure. The competitive environment features both large-scale commercial providers and agile digital-native startups. Major players often pursue strategic partnerships to expand service offerings or adopt new technologies. Smaller, independent operators frequently focus on niche services or specific local markets.
At the scale-driven end, Cintas Corporation and Aramark dominate the commercial segment, providing extensive linen and uniform services to hotels and healthcare facilities. These established firms leverage their logistical networks and long-standing client relationships. In contrast, Rinse, Inc. exemplifies the digital-native archetype, specializing in app-based, on-demand residential laundry and dry-cleaning services, focusing on convenience and efficiency in urban areas.
| Leading Market Players |
|---|
| Alliance Laundry Systems LLC |
| Aramark |
| Cintas Corporation |
| Tide Cleaners |
| ZIPS Dry Cleaners |
| Alsco |
| Rinse, Inc. |
| Elis SA |
| CSC ServiceWorks, Inc. |
| Others |
Cost & Logistics Intelligence
EPA's stringent regulations on perchloroethylene use gate both the qualification of solvent suppliers and the price differentiation for compliant dry-cleaning services. This regulatory pressure directly impacts operational costs and service pricing across the United States market.
Pricing Analysis
The pricing gap between advanced wet cleaning systems and legacy dry cleaning machines influences service charges across the industry. Pay-per-use remains the dominant pricing model for residential customers, while commercial clients often utilize bulk service contracts. Price differentiation stems from specialized textile care for delicate fabrics and the convenience offered by on-demand platforms. Pricing softness reflects intense competition from self-service laundromats, with households exhibiting higher price sensitivity compared to hotels and healthcare facilities.
Supply Chain Analysis
Germany and China anchor the production of advanced wet cleaning equipment and biodegradable detergents for the global market, alongside specialized solvents. The industry relies on these inputs, including hydrocarbon solvents and sophisticated water filtration systems for eco-friendly operations. A structural risk involves solvent price volatility, which impacts operational expenses for cleaners transitioning from traditional chemicals. Distribution runs through a network of local service providers and increasingly via app-based logistics platforms directly to residential and commercial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry-cleaning and laundry services market is experiencing high-growth disruption, driven by the technological inflection towards sustainable wet cleaning systems. This shift fundamentally alters operational requirements and customer expectations across all segments.
For Market Incumbents: Compound existing logistical networks by integrating advanced wet cleaning technologies to counter the threat from digital-native startups. Consolidate smaller, independent operators to gain market share and achieve economies of scale. Invest in certification for eco-friendly operations as a lever to differentiate services and meet evolving environmental mandates. Further, leverage established commercial contracts with hotels and healthcare facilities to stabilize revenue streams. For New Entrants and Emerging Players: Lead with app-based convenience and subscription models to target affluent urban professionals in megacities like London and Tokyo. Focus on the residential on-demand segment as the most penetrable white-space, offering superior logistical efficiency. A strong go-to-market angle involves emphasizing rapid turnaround times and premium textile care for high-value garments. Develop partnerships with local businesses to expand service reach. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the commercial laundry segment due to investments in advanced wet cleaning equipment. The market presents long-term viability over a 5-10 year window, driven by sustained demand for professional textile care. Target acquisition archetypes include digitally integrated on-demand platforms with strong urban customer bases. The adoption rate of subscription models will signal market maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Wet Cleaning Technology | Modern equipment reduces environmental impact and ensures compliance with EPA regulations for dry cleaners. |
| Develop Subscription-Based Service Packages | Subscription models stabilize revenue streams for residential providers and enhance customer loyalty in urban areas. |
| Form Strategic Partnerships with Hospitality Chains | Partnerships secure high-volume commercial contracts, leveraging established logistical networks for hotels. |
| Expand Digital On-Demand Platform Reach | Digital platforms unlock new residential demand by offering superior convenience in dense urban centers. |
| Integrate AI-Driven Logistics Software | AI software optimizes routing and scheduling, significantly improving efficiency for delivery-based laundry services. |
Research Approach
A standing panel of commercial laundry operators, hospitality procurement managers, and environmental regulators provided ongoing calibration for market insights. Primary interviews with industry stakeholders were triangulated with secondary validation from governmental reports, trade association publications, and company financial filings. This approach ensured robust bottom-up and top-down data synthesis.
Market outputs were validated for consistency against external benchmarks and historical growth patterns across the analysis window. The analytical framework modeled segmentation dimensions including service type, end-user, technology, and pricing model, alongside regional regulatory environments. Compound annual growth rates were derived from a multi-factor analysis considering urbanization trends. Forecast inputs included solvent consumption data and commercial linen volumes.
The analysis sits within stated boundaries; outcomes outside significant shifts in environmental regulations or digital adoption rates would require recalibration. Forecasts reflect assumptions regarding technological advancements and consumer behavior. Recalibration cycles align with material shifts in solvent innovation or platform integration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Supply Chain Risk Management Software Market
Others
Global Recruitment and Staffing Market
Others
Japan 3D Printing Construction Market
Others
Quadrant Scale Market
Others
Asia-Pacific Legal Services Market
Others
North America 3D Printing Construction Market
Others
Paper Shredder Market
Others
Military Sensors Market
Others
AI in Precision Medicine Market
Others
Badminton Apparel Market
Others
Industrial Computers Market
Others
Retail Media Platform Market
Others
Mainframe Market
Others
Hypermarket Market
Others
Water and Waste Water Treatment Chemicals Market
Others
United States Cigarette Market