
 Aboveground Storage Tanks Market | 2026-2036
Aboveground Storage Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Aboveground Storage Tanks Market Insights
Modular tank farm configurations is repositioning buyer procurement patterns across the aboveground storage sector. CST Industries leverages its bolted tank platform to capture utility-scale water projects. Tank Connection anchors its position through field-erected dominance in petrochemical corridors. Highland Tank differentiates via specialized fire protection tank assemblies for municipal buyers.
Aboveground storage tanks are welded or bolted containers designed for atmospheric or low-pressure containment of liquids, typically fabricated from carbon steel plate with API 650 compliance for weld quality and shell thickness. These structures serve primary industrial functions including crude oil staging, chemical buffering, and fire suppression water reserve. Fixed roof designs still occupy the largest installed base across mature petrochemical terminals. Floating roof variants are recording the fastest specification growth as volatile organic compound regulations tighten vapor emission limits. Fiberglass reinforced plastic is carving out margin-rich niches in agricultural chemical and brine storage where metallic corrosion accelerates replacement frequency.
EPA spill prevention rules under 40 CFR 112 and API 653 inspection standards shape tank integrity mandates and replacement timelines across US facilities. OSHA 1910.146 confined space protocols add compliance cost layers to maintenance-intensive carbon steel installations. State-level air quality districts in California and Texas layer additional vapor recovery requirements onto floating roof specifications. Buyers must weigh total cost of ownership against regulatory trajectory when committing to twenty-plus year asset cycles.
Market Dynamics
Modular bolted tank configurations are compressing project timelines and redirecting procurement toward standardized field-erected systems that slash on-site welding requirements and accelerate utility-scale deployment cycles.
Growth Catalysts
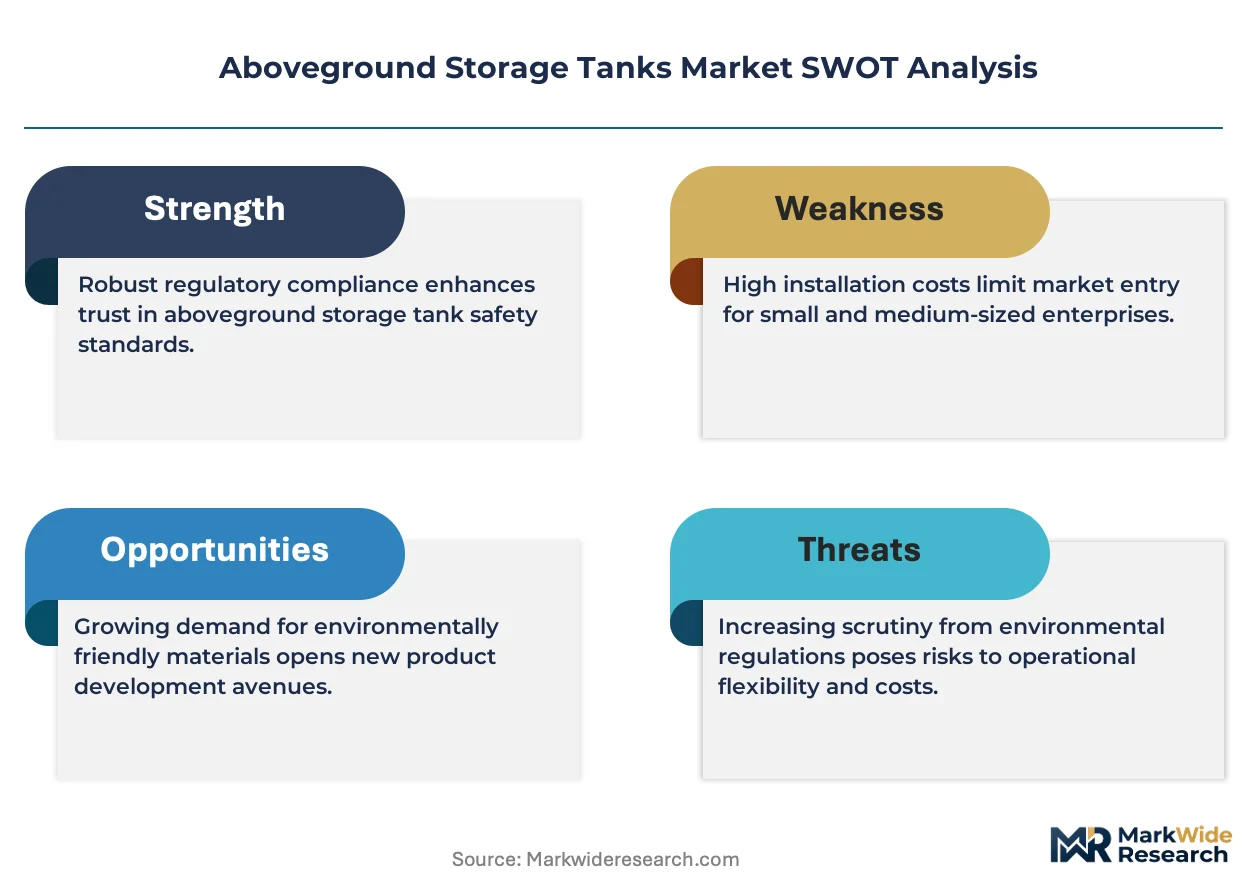
- EPA discharge rule tightening:Water treatment utilities across Texas and Louisiana are accelerating tank replacement schedules to meet 40 CFR 112 spill prevention mandates, driving procurement volume in coastal petrochemical corridors.
- Fiberglass reinforced plastic corrosion resistance:Coastal zone operators are specifying FRP tanks for brine and agricultural chemical storage where salt air accelerates carbon steel degradation and extends asset life cycles.
- Petrochemical cluster density:Concentrated refining and chemical processing infrastructure in the US Gulf Coast generates continuous replacement demand as aging API 650 tanks reach inspection-triggered retirement thresholds.
Market Restraints
- Steel plate price volatility:Carbon steel input costs fluctuate with scrap metal and energy pricing, compressing fabrication margins for welded tank producers serving fixed-budget municipal buyers.
- Specialized coating supply concentration:Protective epoxy and zinc-rich coating systems for tank interiors depend on concentrated chemical suppliers, creating vulnerability to formulation shortages or import delays.
- Concrete foundation substitution:Below-grade concrete containment systems compete for fire suppression water storage in seismic zones where buried capacity satisfies code without aboveground footprint constraints.
Strategic Opportunities
- California air quality district vapor recovery:CARB-aligned districts mandate enhanced floating roof seals, creating specification upgrade opportunities for emission-compliant tank retrofits and new builds.
- Hybrid tank-farm digitization:Integration of IoT level sensors and predictive corrosion monitoring with bolted steel structures enables outcome-based maintenance contracts for industrial buyers.
- Renewable diesel storage expansion:Biorefinery construction in Iowa and Minnesota requires new aboveground capacity for feedstock oils and finished fuel, opening Midwest geography beyond traditional Gulf concentration.
Industry Challenges
- API 653 certified inspector scarcity:Tank integrity assessment and repair oversight requires specialized personnel credentials that lag demand, extending outage durations and compliance backlogs.
- Legacy fixed-roof retrofit complexity:Converting existing cone-roof tanks to floating roof configurations demands structural reinforcement and seal engineering that disrupts active terminal operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aboveground Storage Tanks Market |
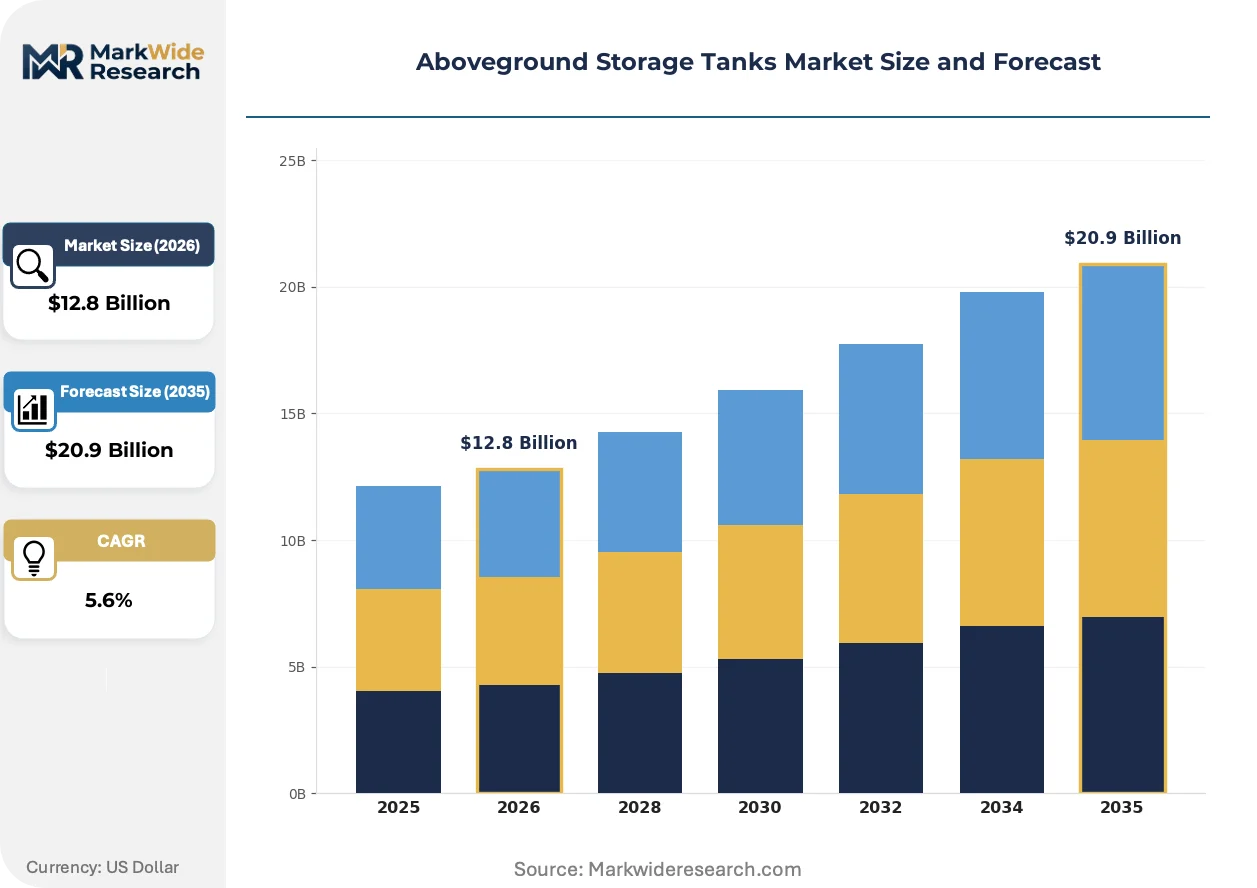
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.9 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Fixed Roof, Floating Roof, Dome Roof, Open Top Material: Carbon Steel, Stainless Steel, Fiberglass Reinforced Plastic, Aluminum Application: Petrochemical Storage, Water Treatment, Agricultural Chemicals, Fire Protection End User Industry: Oil & Gas Extraction, Chemical Manufacturing, Power Generation, Mining Operations |
| Companies Covered | CB&I, CST Industries, HMT Tank, Matrix Service Company, BELLELI ENERGY CPE, Tank Connection, Caldwell Tanks, Highland Tank, Tarsco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aboveground Storage Tanks Market Trends and Innovations
Fabrication automation and material science advances are compressing project delivery timelines while regulatory pressure on emissions and asset integrity accelerates specification evolution across buyer segments.
Aluminum dome roof systems are expanding into crude oil and refined product storage terminals where reduced structural load enables larger diameter tanks without internal column interference. Major terminal operators in the US Gulf Coast are specifying aluminum geodesic designs for new construction, and this shift is expanding into ethanol and biodiesel storage applications where vapor-tight seals matter equally.
OSHA 1910.146 confined space protocols are mandating permanent ventilation and monitoring infrastructure on carbon steel tank installations, adding capital cost layers that favor factory-coated bolted alternatives with fewer field weld seams. Petrochemical operators are responding by pre-qualifying tank fabricators on safety record metrics alongside price, compressing the vendor pool for complex welded projects.
Utility buyers are consolidating procurement through engineer-procure-construct contractors who bundle tank supply with civil and mechanical scope, displacing direct OEM relationships that dominated historical municipal purchasing. This channel compression concentrates volume with integrated EPC firms in Texas and Louisiana while squeezing standalone tank fabricators into specialty niches like fire protection or agricultural applications.
Aboveground Storage Tanks Market Segmentation
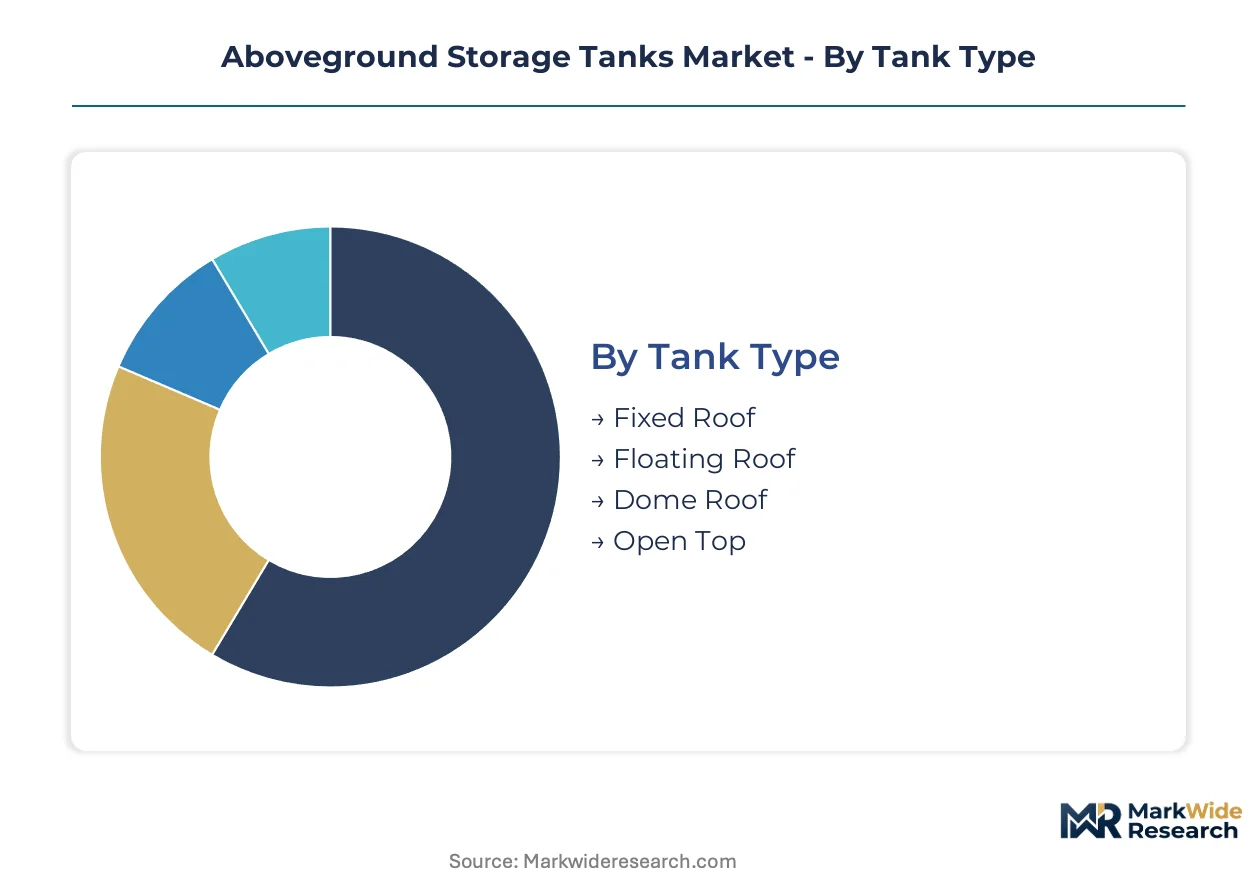
Segmentation in aboveground storage tanks reveals how certification burdens, corrosion environments, and end-use volatility shape procurement decisions. Buyers select tank configurations based on EPA spill prevention mandates, OSHA confined space protocols, and state-level air quality requirements that vary dramatically across application contexts.
Tank Type:
API 650 certification governs all welded designs, while bolted configurations follow AWWA D103 for water applications and FM 4020 for fire protection, creating divergent compliance pathways.
- Fixed Roof:Cone or dome roof designs welded to cylindrical shells provide vapor-tight containment for refined products and chemicals with low volatility. Terminal operators in Texas and Louisiana specify these for gasoline and diesel staging where emission controls remain secondary to structural simplicity.
- Floating Roof:Pontoon or double-deck designs ride directly on liquid surfaces, eliminating vapor space and cutting volatile organic compound losses by orders of magnitude. CARB-aligned districts in California mandate these for crude oil storage, driving specification upgrades as legacy fixed-roof tanks face retrofit deadlines.
- Dome Roof:Geodesic aluminum structures deliver column-free internal clearance for large-diameter tanks handling solids or requiring agitation equipment.
- Open Top:Uncovered basins serve fire suppression water and cooling tower blowdown where evaporation losses are acceptable and cost minimization dominates.
Fixed roof sits at the top of the volume ranking, with floating roof climbing the fastest.
Material:
Material selection pivots on corrosion resistance requirements, weldability constraints, and total cost of ownership across twenty-year asset cycles.
- Carbon Steel:API 650-compliant plate remains the default for petroleum and chemical storage, with interior epoxy linings and exterior zinc-rich coatings extending service life in moderate environments. Fabricators in the US Gulf Coast cluster dominate welded carbon steel supply for petrochemical buyers.
- Stainless Steel:Austenitic grades 304 and 316 serve food-grade, pharmaceutical, and aggressive chemical applications where carbon steel corrosion rates accelerate maintenance costs.
- Fiberglass Reinforced Plastic:Corrosion-proof composite construction eliminates coating maintenance for brine, agricultural chemicals, and coastal installations where salt air degrades metallic tanks.
- Aluminum:Lightweight dome roof systems reduce structural loads and enable larger diameters without internal columns, expanding into ethanol and biodiesel terminals.
Carbon steel commands the largest installed base, while fiberglass reinforced plastic gains share fastest in corrosion-critical niches.
Application:
Application segmentation tracks regulatory intensity, with petrochemical storage facing the densest EPA and state air quality overlays.
- Petrochemical Storage:Crude oil, refined products, and intermediate chemicals demand API 650 compliance, API 653 inspection protocols, and increasingly vapor recovery systems for floating roof seals. Gulf Coast terminal expansions and replacement cycles drive continuous procurement volume.
- Water Treatment:Potable water, wastewater, and process water storage follows AWWA D103 for bolted designs or API 650 for welded municipal installations. EPA discharge rule tightening accelerates tank replacement schedules across Texas and Louisiana utilities.
- Agricultural Chemicals:Fertilizer, pesticide, and herbicide storage favors fiberglass reinforced plastic where chemical compatibility and corrosion resistance outweigh steel's lower first cost.
- Fire Protection:NFPA 22-compliant tanks for municipal and industrial sprinkler reserves specify bolted steel or concrete alternatives, with factory-coated bolted systems displacing field-welded construction.
Petrochemical storage generates the highest absolute revenue, with water treatment expanding most quickly on regulatory replacement demand.
End User Industry:
End user segmentation correlates with geographic clustering and replacement cycle timing, with oil and gas extraction concentrated in the Permian and Bakken formations.
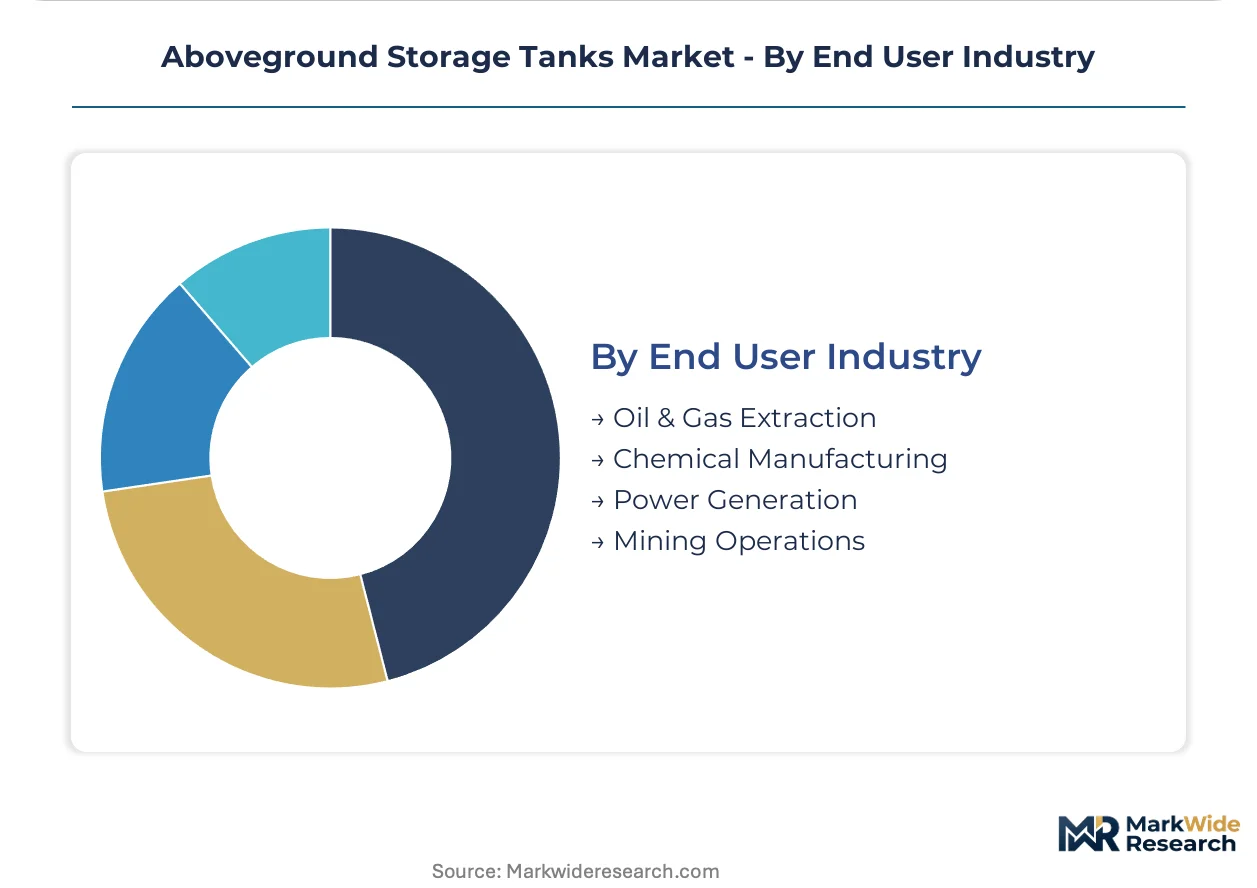
- Oil & Gas Extraction:Upstream operators deploy tanks for crude oil gathering, produced water handling, and drilling fluid storage across shale plays. Midland and Odessa procurement offices specify bolted tanks for rapid field deployment.
- Chemical Manufacturing:Petrochemical complexes along the Houston Ship Channel and Lake Charles corridor generate continuous demand for corrosion-resistant materials and emission-compliant floating roof designs.
- Power Generation:Coal, natural gas, and nuclear facilities require fuel oil backup, cooling water, and fire suppression reserves, with bolted tanks preferred for outage-sensitive installations.
- Mining Operations:Heap leach, process water, and fuel storage in remote locations favor modular bolted configurations that minimize on-site welding and accelerate project timelines.
Oil and gas extraction anchors procurement volume, with chemical manufacturing showing the steepest specification upgrade trajectory on environmental compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aboveground storage tank fabrication originated in the United States during the early twentieth century oil boom, with API standards later codifying weld quality and shell thickness requirements that spread globally. Regional demand patterns now track petrochemical cluster density, water utility capital cycles, and coastal corrosion environments across distinct national markets.
United States
EPA discharge rule tightening under 40 CFR 112 drives replacement schedules across Texas and Louisiana water treatment utilities. OSHA 1910.146 confined space protocols add compliance cost layers to carbon steel maintenance. The Houston Ship Channel and Lake Charles corridor host concentrated petrochemical terminal expansions requiring API 650-compliant capacity.
China
State-owned refinery expansions along the Bohai Rim and Yangtze River Delta sustain demand for large-diameter crude storage. MEE air quality enforcement in Beijing-Tianjin-Hebei accelerates floating roof specifications for volatile organic compound control. Shandong province's independent teapot refineries drive modular bolted tank procurement for rapid deployment.
Germany
REACH chemical registration requirements shape material selection for industrial chemical storage in Ludwigshafen and Leverkusen clusters. ECHA corrosion assessment protocols favor stainless steel and specialized coatings for aggressive media. Bavarian biogas and renewable fuel facilities require new aboveground capacity for feedstock oils and digestate handling.
India
Petroleum Strategic Reserve expansion at Visakhapatnam, Mangalore, and Padur sustains demand for massive welded crude tanks. BIS certification requirements for pressure vessels extend to atmospheric storage in refining applications. Gujarat's Jamnagar and Vadodara petrochemical complexes generate continuous replacement cycles as aging assets reach inspection thresholds.
Saudi Arabia
SABIC and Saudi Aramco downstream integration in Jubail and Yanbu drives specification-grade tank procurement for chemical and refined product storage. The country's national environmental regulator enforces vapor recovery mandates on floating roof installations. NEOM giga-project construction opens new geography for water treatment and industrial process storage demand.
Aboveground Storage Tanks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and field-erection capability dimensions. The vendor base organizes into three tiers: integrated EPC firms bundling civil and mechanical scope, specialized tank fabricators with API 650 and AWWA D103 credentials, and regional bolted-system distributors serving rapid-deployment segments. Dominant competitive moves include backward integration into coating and foundation services, and technology licensing agreements for aluminum geodesic roof systems.
Among US-based fabricators, CB&I exemplifies the integrated EPC archetype with terminal construction capabilities spanning multiple continents. CST Industries occupies a position within the bolted-system premium tier, leveraging standardized field-erected platforms for utility-scale water projects. Tank Connection anchors the field-erected specialist segment, concentrating presence in petrochemical corridor markets where API 650 weld quality determines contract awards.
| Leading Market Players |
|---|
| CB&I |
| CST Industries |
| HMT Tank |
| Matrix Service Company |
| BELLELI ENERGY CPE |
| Tank Connection |
| Caldwell Tanks |
| Highland Tank |
| Tarsco |
| Others |
Pricing and Supply Chain Analysis
Modular bolted tank fabrication is compressing project delivery timelines while simultaneously redrawing cost economics across the supplier base. This production-method transition concentrates procurement power with fabricators who can deliver factory-coated systems without field welding, squeezing margins for traditional welded-tank specialists serving municipal buyers.
Pricing Analysis
Project-based contract pricing dominates aboveground storage tank procurement, with three-tier pricing structure across premium, standard, and economy levels separating API 650-certified field-erected systems from AWWA D103 bolted alternatives and unlicensed regional fabricators. Price differentiation hinges on certification grade and geographic delivery cost, with Gulf Coast proximity commanding premiums for petrochemical corridor access. Cost compression in the economy tier is intensifying because steel plate volatility and coating supply concentration squeeze fabrication margins. Municipal water utilities exhibit the highest price sensitivity, while petrochemical terminal operators prioritize vapor recovery compliance over first cost.
Supply Chain Analysis
Direct-to-EPC channels handle utility-scale and petrochemical terminal demand, while regional distributors serve rapid-deployment mining and agricultural segments. Raw material supply concentrates in the United States, China, and India, with carbon steel plate, epoxy coating systems, and aluminum geodesic roof components anchoring fabrication economics. The supply chain draws from concentrated chemical suppliers for protective coatings, creating single-source vulnerability to formulation shortages or import delays. Distribution runs through engineer-procure-construct contractors who bundle tank supply with civil and mechanical scope, displacing direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as floating roof specifications displace fixed-roof installations under tightening EPA and state air quality mandates. The demand-shift toward emission-compliant premium configurations favors fabricators with API 650 credentials and field-erection capabilities.
For Market Incumbents: Hedge against coating supply concentration by securing captive supply of epoxy and zinc-rich formulations, or backward integration into specialized lining application services. Defensive consolidation through acquisition of regional bolted-system distributors in Texas and Louisiana would lock in utility procurement channels threatened by EPC bundling. For New Entrants and Emerging Players: The mid-tier price-point gap between premium API 650 fabricators and economy bolted-system distributors offers entry space for hybrid offerings targeting biorefinery construction in Iowa and Minnesota. Agricultural chemical storage in coastal zones presents the most penetrable application, with fiberglass reinforced plastic corrosion resistance justifying specification upgrades. A go-to-market angle anchored on IoT-integrated tank farms with predictive maintenance contracts would differentiate against legacy fabricators. For Investors and Strategic Acquirers: Valuations sit cheapest among regional bolted-system distributors lacking API 650 credentials but holding established utility relationships. Long-term viability over a five-to-ten year window favors targets with aluminum geodesic roof licensing agreements and field-erection capabilities in petrochemical corridors. The signal to watch is CARB-aligned district adoption of enhanced floating roof seals as a leading indicator of specification upgrade velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Services | Captive supply of epoxy formulations mitigates single-source vulnerability from concentrated chemical suppliers. |
| Aluminum Geodesic Roof Licensing | Technology partnerships enable column-free large-diameter tanks for ethanol and biodiesel terminal expansions. |
| IoT-Enabled Predictive Maintenance Contracts | Outcome-based service models create recurring revenue from corrosion monitoring and inspection scheduling. |
| Geographic Expansion to Midwest Biorefineries | Renewable diesel construction in Iowa and Minnesota opens capacity demand beyond traditional Gulf Coast concentration. |
| API 653 Inspection Certification Investment | Certified inspector capabilities address scarcity extending outage durations and compliance backlogs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EPC procurement directors, municipal water utility engineers, petrochemical terminal operators, and tank fabricator sales executives with secondary validation from EPA enforcement databases, API standards documentation, state air quality district filings, and customs trade records. Bottom-up tank shipment tracking and top-down petrochemical capital expenditure analysis provided triangulation across the analysis window.
Historical reference periods anchored the projection horizon to replacement cycle timing and regulatory compliance deadlines, with segmentation modeling across tank type, material grade, application, and end-use industry. CAGRs derived from installed base depreciation curves and new build permitting data incorporated EPA discharge rule implementation schedules and OSHA confined space protocol adoption rates as demand drivers.
The model assumes a particular technology adoption path; alternative pathways for fiberglass reinforced plastic substitution would alter the outlook if coastal corrosion environments accelerate composite uptake beyond baseline projections. Forecasts reflect assumptions about steel plate price stability and API 653 inspector training pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Compact Wheel Loaders Market
Others
TWS Micro-Battery Market
Others
Augmented Reality in BFSI Market
Others
Air Purification Systems Market
Others
Global Pregnancy Tracker Apps Market
Others
Printing Machines Market
Others
Nyerereite Market
Others
Global Military Wearable Sensors Market
Others
Deep Sea Mining Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Propanil Market
Others
Asia-Pacific Intercom Devices Market
Others
Connected Homes Market
Others
IT Device Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Global Pumpkin Candles Market