
 Flexible PVC Films and Sheets Market | 2026-2036
Flexible PVC Films and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible PVC Films and Sheets Market Foresight
The EU REACH regulation on phthalate plasticizers is consolidating demand toward non-phthalate flexible PVC formulations across European medical and consumer goods sectors. Sealed Air leverages its vertical integration into resin compounding to secure formulation consistency for healthcare packaging clients. Berry Global Inc. anchors North American supply through multi-site calendering operations serving food wrap and pharmaceutical blister applications. MarvelVinyls specializes in custom embossed and printed films for decorative laminates, competing on short-run flexibility rather than commodity scale.
Flexible PVC films and sheets comprise polyvinyl chloride resin plasticized with phthalate or non-phthalate additives, processed through calendering, extrusion, or casting into gauges ranging from 0.05 mm to 5.0 mm for applications requiring clarity, weldability, and chemical resistance. Calendered films dominate volume production for packaging and stationery due to superior surface finish and throughput economics, while cast films command premium positioning in optical and medical grades where gauge uniformity and low gel content are critical. Extruded sheets maintain structural share in construction signage and stationary displays, though margin pools are thinning as recycled content mandates raise compound costs.
The EPA oversees emissions standards for PVC resin production facilities under the Clean Air Act, while FDA 21 CFR 175.300 governs migration limits for food-contact flexible PVC in the United States. ECHA's REACH Annex XVII restrictions on DEHP, DBP, BBP, and DIBP have forced European compounders to reformulate with DINCH, DOTP, or bio-based plasticizers, reshaping raw material sourcing and qualifying protocols. Stakeholders must monitor the trajectory of state-level extended producer responsibility laws in California and New York, as these will determine whether mechanical recycling infrastructure or chemical depolymerization investments capture post-consumer flexible PVC waste streams.
Market Dynamics
The EU REACH restriction on phthalate plasticizers is redirecting formulation strategies toward bio-based and non-phthalate alternatives, forcing compounders to rebuild supply chains around DINCH and DOTP chemistries. Medical device packaging demand is accelerating uptake across sterile barrier applications, concentrating investment in calendering capacity with FDA 21 CFR 175.300 and ECHA REACH compliance protocols.
Growth Catalysts
- Sterile barrier packaging:Medical device manufacturers are qualifying flexible PVC films for pharmaceutical blister packs and IV bag applications, driving volume through FDA-validated cleanroom extrusion lines.
- REACH Annex XVII reformulation:European compounders are retooling toward DINCH, DOTP, and citrate-based plasticizers, creating qualified supply scarcity that rewards early movers with locked hospital purchasing contracts.
- Germany's industrial corridor clustering:Automotive suppliers and medical converters concentrate around specialized calendering capacity in Baden-Württemberg and Bavaria, reducing logistics costs for just-in-time film delivery.
Market Restraints
- Feedstock cost volatility:Ethylene and chlorine price swings compress compounding margins, particularly for small-batch medical grades requiring tight viscosity specifications.
- Calendering capacity concentration:High-volume film production clusters in Germany, China, and the US Gulf Coast, creating regional supply bottlenecks during maintenance turnarounds or force majeure events.
- Mechanical recycling limitations:Plasticizer migration and additive contamination prevent closed-loop mechanical recycling of post-consumer flexible PVC, forcing reliance on virgin resin or costly chemical depolymerization.
Strategic Opportunities
- India's medical packaging underpenetration:Domestic sterile barrier film production lags behind CDSCO-registered device manufacturing, creating import substitution potential for REACH-compliant European compounders.
- Bio-based plasticizer convergence:Epoxidized soybean oil and succinate ester chemistries are crossing performance thresholds for food-contact films, opening premium positioning against petroleum-derived alternatives.
- California EPR tailwinds:Extended producer responsibility legislation is mandating recycled content floors, positioning chemical recycling investments to capture post-industrial scrap premiums.
Industry Challenges
- Formulation chemist scarcity:Expertise in non-phthalate plasticizer compatibility and heat stability optimization is concentrating at legacy European compounders, raising recruitment costs for Asian market entrants.
- Multi-jurisdiction certification timelines:Simultaneous FDA 21 CFR 175.300, EU 10/2011, and CDSCO filings for medical grades extend qualification cycles beyond 18 months, freezing working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible PVC Films and Sheets Market |
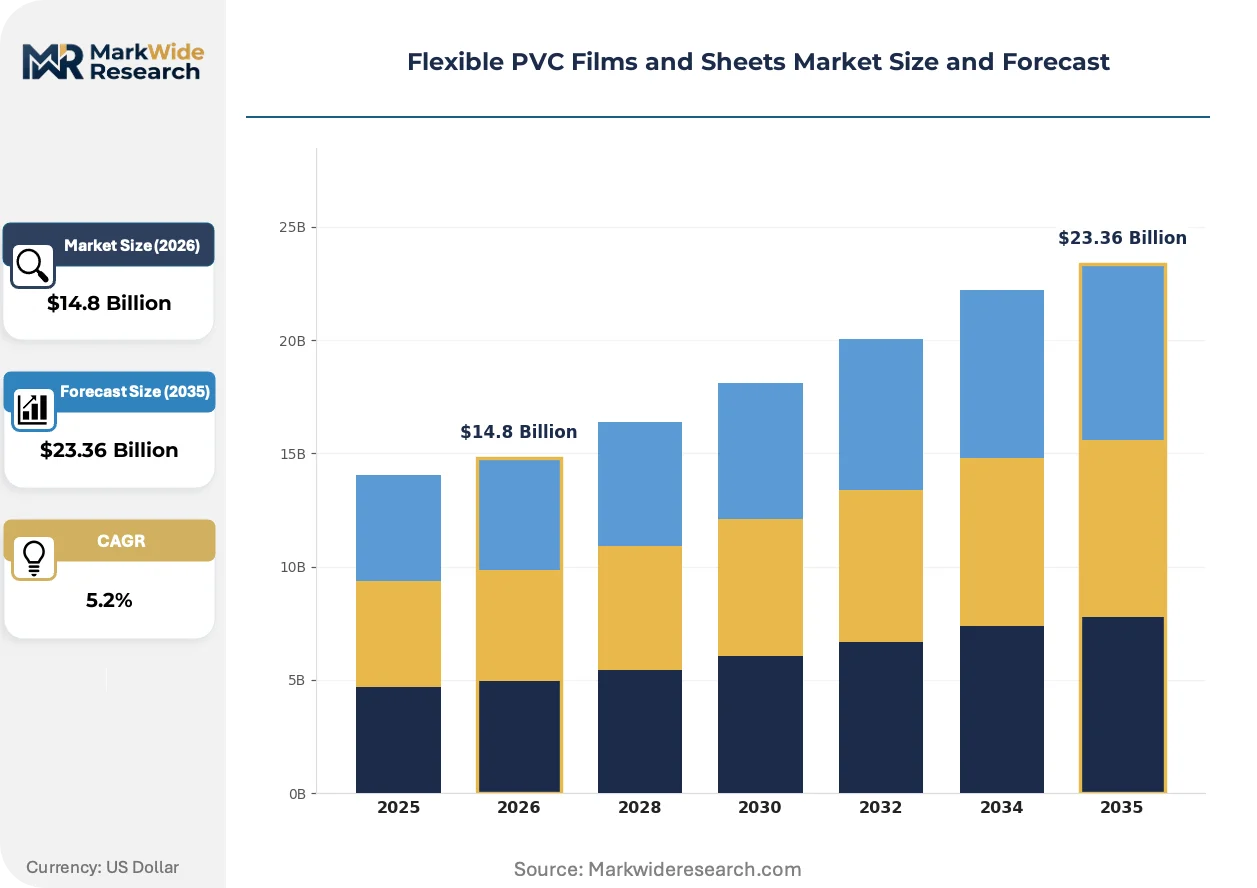
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calendered Films, Extruded Sheets, Cast Films, Laminated Sheets, Foamed Films Application: Packaging, Electrical Insulation, Construction, Automotive Interiors, Consumer Goods End User Industry: Packaging Manufacturers, Electrical Equipment Producers, Building Contractors, Vehicle Furnishers, Household Product Makers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | Sealed Air, MarvelVinyls, NAN YA PLASTICS CORPORATION, Shih-Kuen Plastics Co., Ltd., Uflex Ltd., Berry Global Inc., Ergis S.A., TMI International, LLC, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible PVC Films and Sheets Market Shifts & Advancements
Non-phthalate plasticizer platforms are crossing performance parity with legacy chemistries, enabling formulation shifts that were technically impossible five years ago. Digital thickness gauging and real-time gel detection are compressing quality variance in medical-grade production.
Cast film technology is expanding into pharmaceutical blister and optical display applications where gauge uniformity below 2% tolerance is mandatory. Korean and Japanese display manufacturers are qualifying cast PVC for protective film laminates at volumes that now rival traditional packaging demand. This precision requirement is expanding into medical pouches and diagnostic device covers, displacing calendered film in premium segments.
ECHA's REACH Annex XVII restrictions on DEHP, DBP, BBP, and DIBP have forced European compounders to validate DINCH and DOTP alternatives through extensive migration testing. Medical device notified bodies are extending review timelines for reformulated films, compressing near-term supply availability. German and French converters with early DINCH validation are capturing share from phthalate-dependent competitors in Southern Europe.
Hospital procurement consortiums are consolidating purchasing power through group purchasing organizations, squeezing spot-market volumes and favoring multi-year supply contracts with locked formulations. North American health system alliances are mandating DEHP-free certifications as a threshold qualification, eliminating non-compliant suppliers from bidding pools. This specification tightening is most visible in US neonatal and oncology device packaging, where liability exposure drives conservative material selection.
Flexible PVC Films and Sheets Market Segmentation
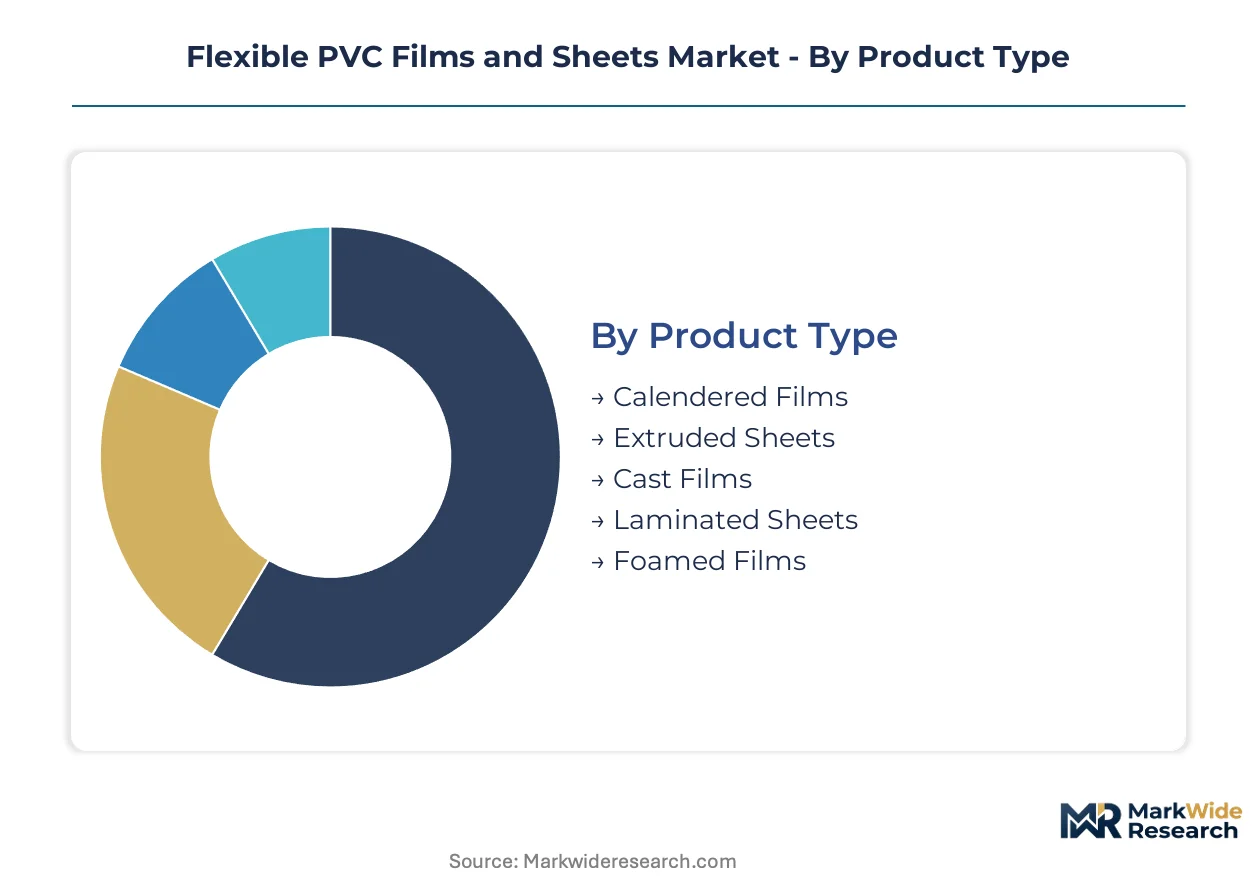
Segmentation in flexible PVC films and sheets tracks how processing technology, end-use performance requirements, and supply chain access determine buyer priorities. Calendering precision separates commodity packaging buyers from medical-grade purchasers, while REACH compliance is fragmenting the European customer base by certification capability.
Product Type:
Cost tier separates buyers seeking throughput economies from those paying premiums for gauge precision and optical clarity.
- Calendered Films:Multi-roll polishing delivers superior surface finish and dimensional stability at high throughput, making this the default choice for food wrap and stationery converters in Germany's industrial corridor. Demand concentrates among automotive suppliers requiring consistent weldability for interior laminates, though REACH Annex XVII reformulation is raising compound costs for phthalate-dependent producers.
- Cast Films:Solution casting achieves gauge uniformity below 2% tolerance and minimal gel content, commanding premium positioning in pharmaceutical blister packs and optical display protection. Korean and Japanese display manufacturers are qualifying cast PVC for protective laminates at volumes now rivaling traditional packaging segments.
- Extruded Sheets:Single-screw or twin-screw extrusion produces structural gauges from 1.0 mm to 5.0 mm for construction signage and point-of-sale displays.
- Laminated Sheets:Multi-layer bonding combines PVC with barrier films or decorative substrates for high-end consumer goods applications.
- Foamed Films:Chemical or physical foaming reduces density for lightweight cushioning and insulation uses in packaging and building applications.
Volume sits with Calendered Films; growth tilts toward Cast Films.
Application:
Application priority tracks regulatory exposure, with FDA and ECHA compliance requirements fragmenting demand by certification depth.
- Packaging:Sterile barrier films for medical devices and pharmaceutical blisters drive the most stringent qualification protocols, with FDA 21 CFR 175.300 migration limits and ECHA REACH restrictions forcing reformulation toward DINCH and DOTP plasticizers. Hospital group purchasing organizations are consolidating procurement power, squeezing spot volumes and favoring locked multi-year contracts.
- Electrical Insulation:Dielectric strength and flame-retardant specifications govern tape and cable jacketing applications, with UL and IEC certification requirements concentrating supply among compounders with validated additive packages.
- Construction:Weatherability and UV resistance specifications dominate signage and protective covering uses, though margin pools are thinning as recycled content mandates raise compound costs.
- Automotive Interiors:Low-fogging and heat-aging resistance requirements from OEMs like Volkswagen and BMW cluster demand around Baden-Württemberg calendering capacity.
- Consumer Goods:Decorative laminates and stationery applications compete on short-run flexibility and custom embossing rather than commodity scale.
Volume sits with Packaging; growth tilts toward Electrical Insulation.
End User Industry:
Customer type determines whether procurement emphasizes formulation lock-in, technical service intensity, or logistics reliability.
- Packaging Manufacturers:Medical device converters require validated cleanroom extrusion lines and locked plasticizer specifications, with qualification cycles extending beyond 18 months for multi-jurisdiction filings. Early movers in DINCH validation are capturing share from phthalate-dependent competitors.
- Electrical Equipment Producers:Cable and tape manufacturers prioritize dielectric consistency and flame-retardant performance, sourcing through direct sales relationships with compounders holding IEC and UL certifications.
- Building Contractors:Construction signage and protective film buyers prioritize availability and gauge range over formulation complexity, purchasing through distributors and wholesalers.
- Vehicle Furnishers:Automotive tier suppliers cluster around specialized calendering capacity in Germany's industrial corridor, reducing logistics costs for just-in-time film delivery.
- Household Product Makers:Decorative laminate and stationery producers compete on short-run flexibility, sourcing custom embossed and printed films from specialists.
Volume sits with Packaging Manufacturers; growth tilts toward Electrical Equipment Producers.
Distribution Channel:
Channel selection reflects order size, technical service requirements, and geographic proximity to compounding capacity.
- Direct Sales:Medical and automotive buyers with locked formulations and multi-year contracts bypass intermediaries to secure supply continuity and technical collaboration on heat stability optimization.
- Distributors:Regional film distributors inventory standard gauges for construction and consumer goods segments, absorbing demand volatility and extending credit to smaller converters.
- Online Retailers:E-commerce platforms serve hobbyist and small-batch industrial buyers with limited technical requirements and immediate delivery needs.
- Wholesalers:Volume aggregators supply building contractors and signage producers with commodity grades where formulation flexibility is acceptable.
- Specialty Stores:Local outlets serve stationery and craft segments with cut-size offerings and immediate availability.
Volume sits with Direct Sales; growth tilts toward Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany, China, and the United States, while consumption spreads across medical device clusters in Western Europe, automotive corridors in East Asia, and packaging converters in North America.
Germany
Automotive suppliers and medical converters cluster around specialized calendering capacity in Baden-Württemberg and Bavaria. ECHA's REACH Annex XVII restrictions on DEHP, DBP, BBP, and DIBP have forced compounders to validate DINCH and DOTP alternatives. German converters with early non-phthalate validation are capturing hospital purchasing contracts across the EU.
United States
FDA 21 CFR 175.300 migration limits govern food-contact flexible PVC, with hospital group purchasing organizations mandating DEHP-free certifications for neonatal and oncology device packaging. The EPA oversees emissions standards for PVC resin production facilities under the Clean Air Act. Texas and Louisiana host Gulf Coast resin and compounding capacity serving domestic medical packaging demand.
China
MIIT standards and GB regulations shape domestic quality frameworks, with NMPA oversight extending to medical-grade film exports. Yangtze River Delta and Pearl River Delta manufacturing bases supply global packaging converters, though REACH-compliant reformulation lags European capabilities. Display manufacturers in Jiangsu and Zhejiang are qualifying cast films for optical protection applications.
India
Domestic sterile barrier film production trails CDSCO-registered device manufacturing, creating import dependence for REACH-compliant medical grades. Maharashtra and Gujarat host emerging calendering operations serving pharmaceutical blister pack converters. The PLI scheme for medical devices is accelerating local device production without matching film supply infrastructure.
Japan
METI industrial standards and PMDA medical device regulations enforce stringent migration limits for pharmaceutical packaging films. Kanto and Kansai regions concentrate precision cast film production for display protection and diagnostic device covers. Japanese display manufacturers are qualifying domestic cast PVC volumes that now rival traditional packaging segments.
Flexible PVC Films and Sheets Market Competitive Landscape
The competitive structure tilts toward vertically integrated compounders with captive resin sourcing and validated cleanroom extrusion lines. Tiered positioning separates global packaging specialists with multi-site calendering networks from regional specialists competing on short-run flexibility and custom embossing. Two strategic archetypes dominate: formulation-locked healthcare suppliers and scale-driven commodity producers. Consolidation pressure is intensifying through M&A targeting REACH-compliant European compounders and capacity expansion in underpenetrated medical packaging markets.
Within the integrated packaging tier, Sealed Air anchors North American healthcare supply through backward integration into resin compounding. Berry Global Inc. exemplifies multi-site calendering operations serving food wrap and pharmaceutical blister applications across regional production nodes. MarvelVinyls occupies a position among specialists competing on short-run flexibility for decorative laminates rather than commodity throughput scale.
| Leading Market Players |
|---|
| Sealed Air |
| MarvelVinyls |
| NAN YA PLASTICS CORPORATION |
| Shih-Kuen Plastics Co., Ltd. |
| Uflex Ltd. |
| Berry Global Inc. |
| Ergis S.A. |
| TMI International, LLC |
| Toray Industries, Inc. |
| Others |
Supply & Pricing Matrix
Calendering-to-cast film migration across German and Japanese medical packaging clusters simultaneously elevates precision requirements and concentrates supply among compounders with validated DINCH and DOTP formulations. This technical shift tightens procurement alternatives for buyers seeking sub-2% gauge tolerance, amplifying pricing power at qualified production nodes while squeezing margins for legacy phthalate-dependent producers.
Pricing Analysis
Margin tightening in medical-grade cast films reflects DINCH plasticizer premiums and extended FDA-ECHA dual-qualification timelines. Three-tier pricing structure across REACH-certified premium, FDA-validated standard, and commodity calendered economy levels separates hospital GPO contracts from spot-market construction grades. Cost-down pressure on phthalate-based calendered films accelerates because ECHA Annex XVII restrictions disqualify legacy formulations from neonatal and oncology device packaging. Building contractors exhibit highest price sensitivity, accepting wider gauge variance for signage applications, while medical device converters lock multi-year formulations with limited substitution elasticity.
Supply Chain Analysis
California and New York extended producer responsibility mandates are reshaping raw material sourcing toward chemically recycled resin feedstocks. Geographic supply concentration centers on Germany, China, and the United States Gulf Coast, where integrated resin-compounding-calendering clusters minimize logistics friction. Raw material dependencies draw from ethylene and chlorine feedstocks, DINCH/DOTP plasticizer chemistries, and additive masterbatches. Single-source vulnerability concentrates in Baden-Württemberg calendering capacity serving Volkswagen and BMW just-in-time interior programs. Distribution runs through direct sales relationships for medical and automotive tiers, with regional distributors absorbing volatility for construction and consumer goods segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible PVC films and sheets competitive positioning hinges on backward integration into resin compounding and captive plasticizer formulation capabilities. Players securing upstream control over DINCH and DOTP supply chains capture margin pools unavailable to formulation-dependent converters.
For Market Incumbents: Hedge phthalate-exposed capacity positions by accelerating DINCH validation timelines and acquiring REACH-compliant European compounders before qualification scarcity hardens. Lock multi-year hospital GPO contracts with formulation guarantees that freeze competitor substitution. Defensive consolidation through calendering capacity expansion in underpenetrated medical packaging corridors protects share against cast film displacement in pharmaceutical blister applications. For New Entrants and Emerging Players: Distributor relationships in India's Maharashtra and Gujarat pharmaceutical corridors offer lowest barrier-to-entry pathways for REACH-compliant European compounders seeking CDSCO-registered device manufacturing linkages. Target sterile barrier film production lagging behind domestic device assembly under India's PLI scheme. Specialty embossing and short-run decorative laminate segments reward flexibility over scale, enabling margin capture without confronting Sealed Air or Berry Global volume positions. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated packaging conglomerates seeking REACH certification breadth and cleanroom extrusion line assets. Long-term viability frames around chemical recycling infrastructure positioning as EPR mandates tighten virgin resin substitution requirements. Watch California SB 54 implementation velocity as inflection signal determining whether mechanical or chemical depolymerization investments capture post-consumer flexible PVC waste stream premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive DINCH formulation supply secures margin pools for hospital GPO contract bidding. |
| REACH-Compliant Capacity Expansion | Early DINCH validation in Baden-Württemberg clusters captures share from Southern European phthalate producers. |
| Cleanroom Extrusion Line Investment | FDA 21 CFR 175.300 compliance enables sterile barrier film qualification for IV bag applications. |
| Chemical Recycling Infrastructure Partnership | California EPR compliance positions post-industrial scrap premiums ahead of virgin resin mandates. |
| Joint Venture with Display Manufacturers | Korean and Japanese optical protection demand rivals traditional packaging volume for cast film output. |
Research Methodology
Independent corroboration across plant managers at German calendering facilities, procurement leads at automotive Tier 1 suppliers, and distribution channel partners in North American construction markets underwrites the qualitative findings. Secondary validation draws from ECHA REACH Annex XVII regulatory filings, FDA 21 CFR 175.300 migration limit documentation, SEC 10-K disclosures from integrated packaging conglomerates, and Cefic plastics industry reports. Bottom-up demand modeling across medical device converters, automotive interior suppliers, and pharmaceutical blister pack manufacturers triangulates against top-down resin consumption data from ethylene and chlorine derivative tracking.
Rate-of-change decomposition across the projection horizon separates volume drivers by processing technology, plasticizer chemistry migration, and end-use regulatory exposure. Segmentation dimensions modeled include calendered versus cast versus extruded product types, packaging versus electrical insulation versus automotive interior applications, and direct sales versus distributor channel structures. CAGRs derive from plasticizer reformulation adoption curves, hospital GPO contract renewal velocities, and display manufacturer cast film qualification pipelines. Industry-specific inputs incorporate ECHA restriction enforcement timelines and FDA validation backlog durations.
Several conditions sit outside the modeled scope, including force majeure disruptions at Gulf Coast chlorine production facilities, abrupt REACH plasticizer blacklist expansion beyond DEHP-DBP-BBP-DIBP, and breakthrough bio-based plasticizer performance parity shifts. Forecasts reflect documented assumptions regarding DINCH supply elasticity and chemical recycling technology cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Egg and Egg Products Market
Others
Global Learning Analytics Market
Others
Global Animal Feed Protein Ingredients Market
Others
Air Separation Module Kit Market
Others
UK Cat Food Market
Others
Brazil Lime Market
Others
Ammeters Market
Others
Liquid Density Meters Market
Others
Idaas Market
Others
India Smart Home Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Sprockets Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
North America Agricultural Enzymes Market
Others
Bicycle Panniers Market
Others
India Foundry Market