
 Middle East Location-Based Services Market | 2026-2036
Middle East Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Location-Based Services Market Insights
ISO/IEC 27001 certification for geospatial data handling is rotating the competitive landscape, filtering out vendors lacking audited information security management systems. HERE Technologies leverages its HD mapping heritage to anchor premium navigation contracts with regional automakers. Google LLC competes through its Android location stack embedded across the Gulf's smartphone base. Esri specializes in ArcGIS deployments for Saudi municipal planning authorities.
Location-based services encompass hardware-software systems that determine geographic position through satellite triangulation, radio frequency identification, or wireless signal triangulation, then process this coordinate data into actionable spatial intelligence for commercial or governmental decision-making. GPS technology dominates outdoor positioning infrastructure across the Middle East, while Bluetooth and Wi-Fi modalities are displacing it in indoor retail analytics environments where satellite signals degrade. Fleet management applications command substantial margin pools due to fuel cost sensitivity among regional logistics operators, whereas retail analytics represents the fastest-expanding application segment as mall operators deploy footfall heatmapping.
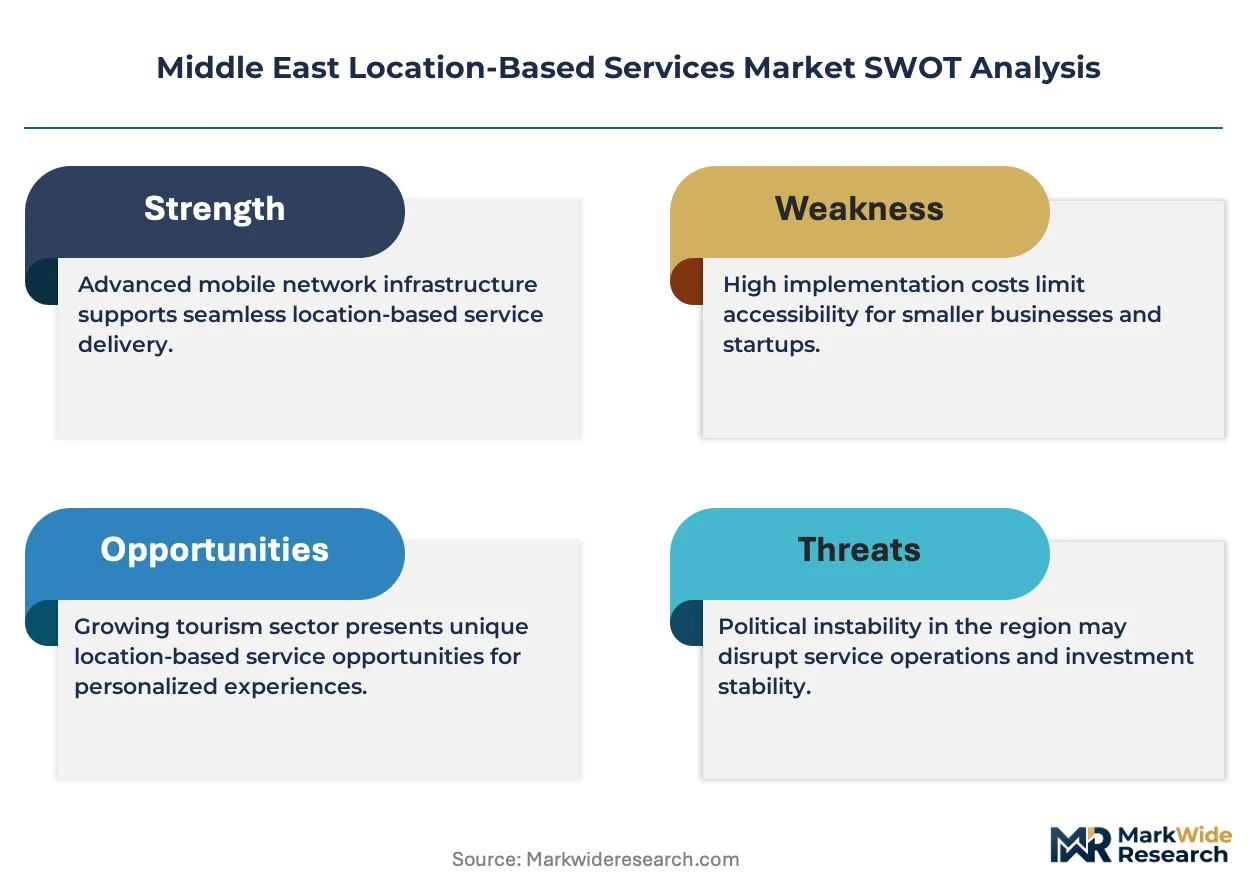
SFDA in Saudi Arabia and MOHAP in the UAE govern location data integration into healthcare emergency response systems, while the UAE's Telecommunications and Digital Government Regulatory Authority shapes cross-border data residency requirements for cloud-hosted geospatial platforms. Saudi Arabia's National Data Management Office mandates localization standards that constrain foreign-hosted service architectures. Stakeholders must monitor evolving data sovereignty frameworks as Gulf states assert jurisdictional control over citizen movement datasets.
Market Dynamics
Smart city infrastructure investments across Gulf Cooperation Council states are compressing deployment timelines for location-based service platforms, while Saudi Arabia's National Data Management Office standards are forcing architectural redesigns of foreign-hosted geospatial systems.
Growth Catalysts
- SFDA and MOHAP mandates:Saudi Arabia's SFDA and the UAE's MOHAP require location data integration into healthcare emergency response systems, creating procurement pull from hospital networks and ambulance fleet operators.
- Bluetooth and Wi-Fi modalities:Indoor retail analytics environments across Dubai's mall ecosystem are displacing GPS with Bluetooth and Wi-Fi triangulation for footfall heatmapping applications.
- Jebel Ali logistics corridor:The UAE's freight concentration around Dubai's port infrastructure is generating fuel cost-sensitive demand for fleet management optimization systems.
Market Restraints
- Data residency requirements:The UAE's Telecommunications and Digital Government Regulatory Authority imposes cross-border data localization constraints that inflate cloud hosting costs for geospatial platforms.
- Satellite signal degradation:Indoor positioning accuracy limitations in steel-reinforced retail complexes force redundant infrastructure deployment.
- ISO/IEC 27001 audit costs:Certification requirements for geospatial data handling create fixed cost barriers for mid-tier service providers seeking public sector contracts.
Strategic Opportunities
- Saudi municipal planning:ArcGIS deployment gaps among Saudi Arabia's secondary city authorities present white space for integrated spatial intelligence platforms.
- HD mapping convergence:The intersection of high-definition road mapping with autonomous vehicle testing zones in Abu Dhabi creates premium service tier demand.
- Android location stack penetration:Smartphone-native positioning infrastructure offers channel innovation for consumer-facing navigation application developers.
Industry Challenges
- Geospatial data science talent scarcity:The shortage of GIS-certified engineers fluent in Arabic regulatory frameworks delays project implementation timelines for foreign vendors.
- Legacy system integration complexity:Saudi municipal authorities operate decades-old cadastral databases that resist API-based connectivity with modern location platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Location-Based Services Market |
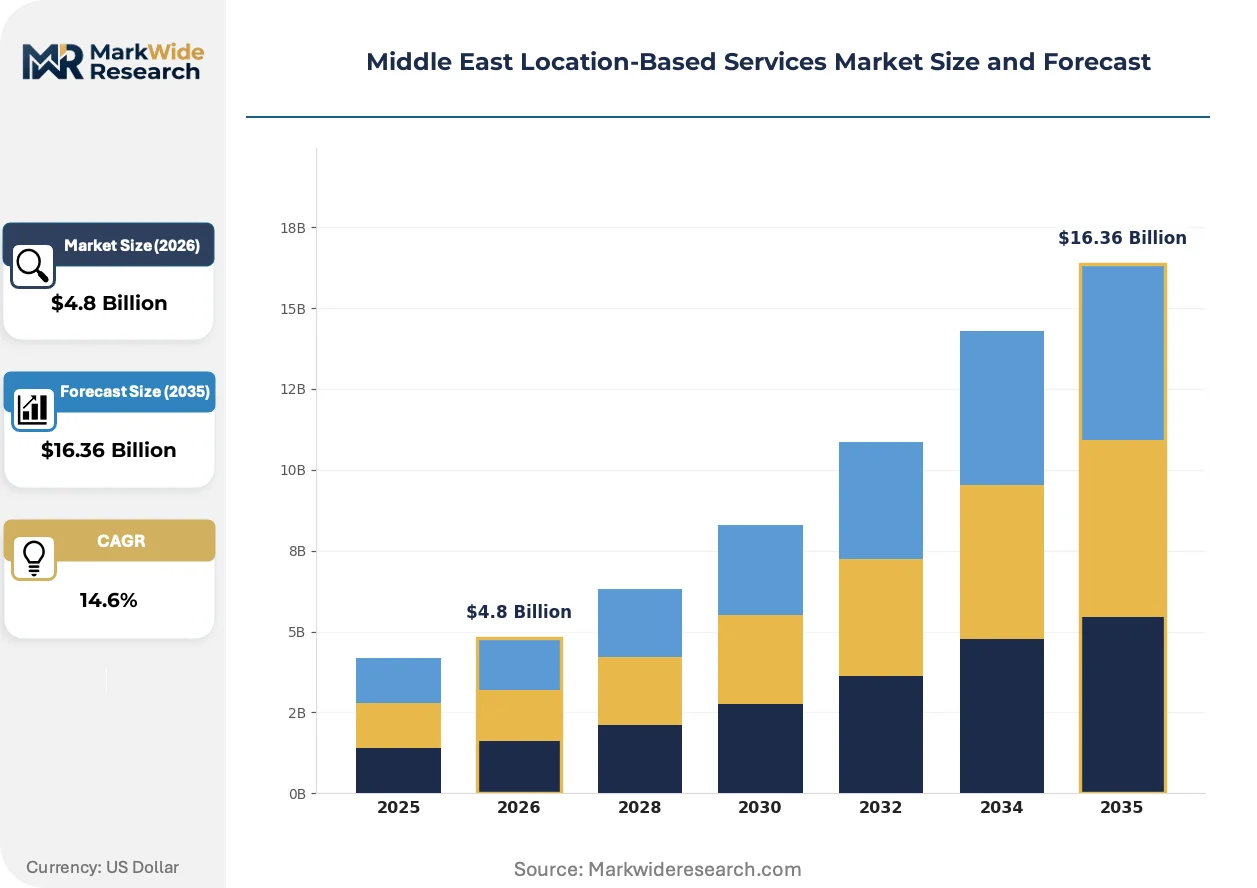
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, RFID, Wi-Fi, Bluetooth Application: Retail Analytics, Fleet Management, Emergency Services, Navigation Solutions End User: Retailers, Transportation Companies, Healthcare Providers, Governments Service Type: Data Analytics, Tracking Services, Software Development, API Integration |
| Companies Covered | Google LLC, HERE Technologies, TomTom International BV, ALE International, Location Solutions Telemetrics LLC, Cisco Systems, Microsoft Corporation, Esri, Zebra Technologies, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Location-Based Services Market Trends and Innovations
Positioning technology architectures are splitting between outdoor satellite-dependent systems and indoor radio-frequency alternatives, with regulatory frameworks simultaneously mandating tighter data controls while expanding use-case permissions.
Ultra-wideband indoor positioning is bifurcating the retail analytics segment from legacy Bluetooth beacon deployments. Mall operators in Dubai and Abu Dhabi are adopting sub-meter accuracy systems for asset tracking and customer journey mapping. This precision tier is compressing margins for Wi-Fi fingerprinting providers while enabling premium pricing for spatial intelligence vendors.
Saudi Arabia's National Data Management Office localization standards are mandating on-shore data processing for all citizen movement datasets. Foreign cloud providers must establish Saudi-based infrastructure or forfeit public sector contracts. Healthcare and transportation verticals are most affected, with emergency response system vendors accelerating local partnership structures.
Fleet operators are unbundling hardware procurement from software subscription models. Logistics companies across the UAE's Jebel Ali corridor now source GPS telematics devices through separate vendor relationships while negotiating platform access fees independently. This procurement fragmentation is most visible among mid-sized freight operators seeking to optimize total cost of ownership across multi-year contracts.
Middle East Location-Based Services Market Segmentation
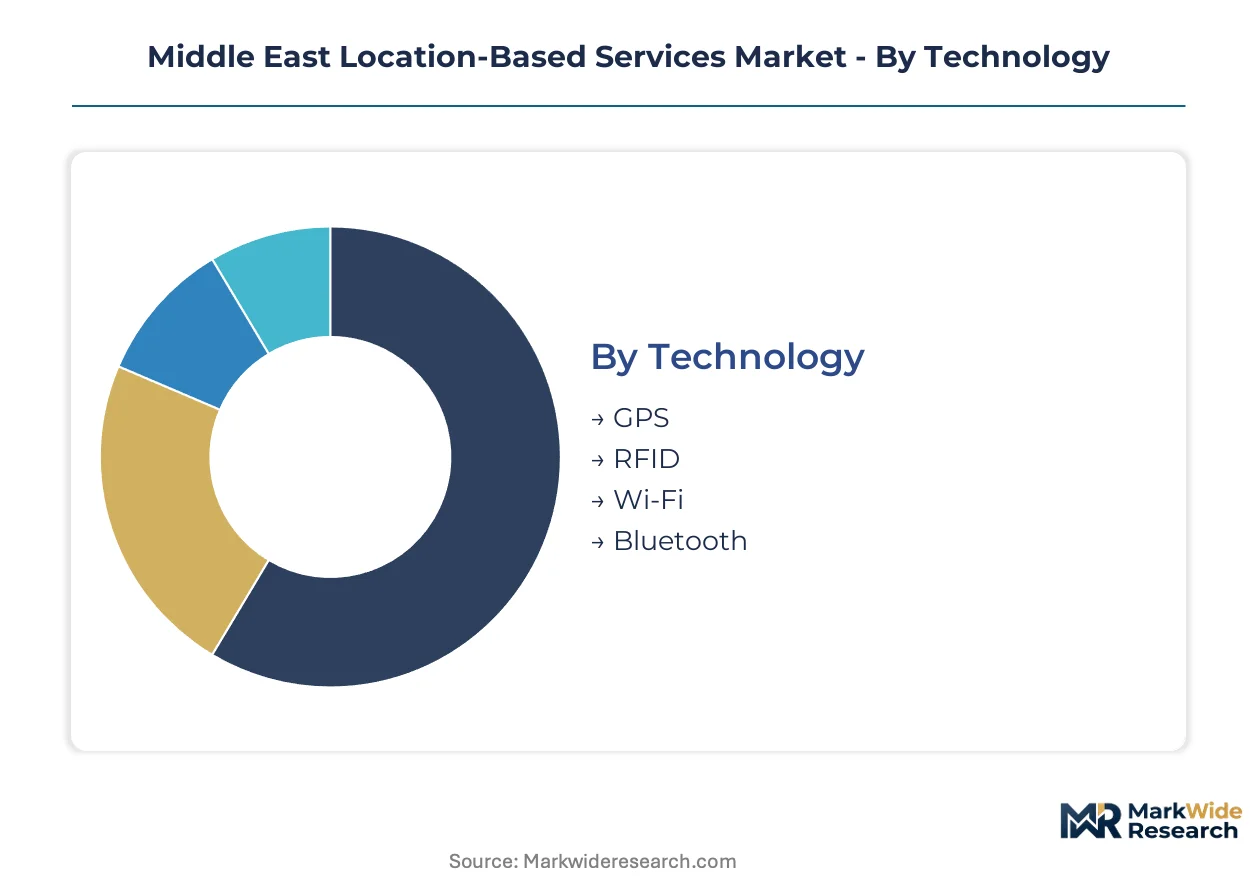
Location-based services in the Middle East fragment across four distinct dimensions, each reflecting different pressure points from substitute technologies and regulatory frameworks. Understanding these boundaries clarifies where vendor margins concentrate and where architectural investments face obsolescence risk.
Technology:
GPS faces the most acute substitution pressure from radio-frequency alternatives as indoor positioning requirements expand across Gulf retail and logistics infrastructure.
- GPS:Satellite triangulation systems dominate outdoor fleet tracking across Saudi Arabia's highway networks and the UAE's Jebel Ali logistics corridor. Fuel cost sensitivity among regional freight operators sustains demand despite signal degradation in urban canyons and indoor environments.
- Bluetooth:Low-energy beacon networks are displacing GPS in Dubai's mall ecosystem for sub-meter footfall heatmapping. Mall operators prioritize battery-efficient deployments that minimize maintenance overhead across multi-level retail complexes.
- Wi-Fi:Fingerprinting systems offer intermediate accuracy for indoor analytics where Bluetooth infrastructure remains uninstalled. Retailers leverage existing wireless access point networks to avoid incremental hardware capital.
- RFID:Passive and active radio-frequency identification serves asset tracking in controlled environments like hospital inventory systems and warehouse fulfillment operations.
GPS retains volume leadership across transportation verticals; Bluetooth holds the steepest expansion curve as precision retail analytics demand accelerates.
Application:
Cost tier stratification separates high-infrastructure emergency systems from lightweight consumer navigation deployments.
- Fleet Management:Telematics platforms integrating GPS hardware with fuel optimization algorithms command substantial margin pools. The UAE's Jebel Ali freight concentration generates procurement pull from operators seeking to minimize diesel expenditure across long-haul routes.
- Retail Analytics:Footfall heatmapping and customer journey mapping represent the most rapidly expanding application segment. Dubai mall operators deploy Bluetooth and ultra-wideband systems to optimize tenant mix and premium space pricing.
- Emergency Services:SFDA and MOHAP mandates require location data integration into healthcare response systems, creating regulated procurement channels for hospital networks and ambulance operators in Saudi Arabia and the UAE.
- Navigation Solutions:Consumer-facing routing applications compete on map data freshness and real-time traffic integration across smartphone-native platforms.
Fleet management dominates current revenue concentration; retail analytics is expanding most quickly as mall digitization accelerates.
End User:
Customer type determines compliance burden intensity, with government contracts imposing the most stringent certification requirements.
- Transportation Companies:Logistics operators across the GCC prioritize total cost of ownership optimization, unbundling hardware procurement from software subscriptions. Mid-sized freight companies in the UAE increasingly negotiate multi-year platform access fees separately from telematics device sourcing.
- Governments:Saudi municipal planning authorities and UAE smart city programs require ISO/IEC 27001 certified geospatial data handling, filtering vendor pools to audited information security management systems.
- Retailers:Mall operators and retail chains demand indoor positioning precision for asset tracking and customer analytics, driving adoption of radio-frequency alternatives to satellite-dependent systems.
- Healthcare Providers:Hospital networks integrate location data into emergency response workflows under SFDA and MOHAP governance, requiring localized data processing architectures.
Transportation companies anchor current deployment volumes; healthcare providers are gaining share fastest as regulatory mandates harden.
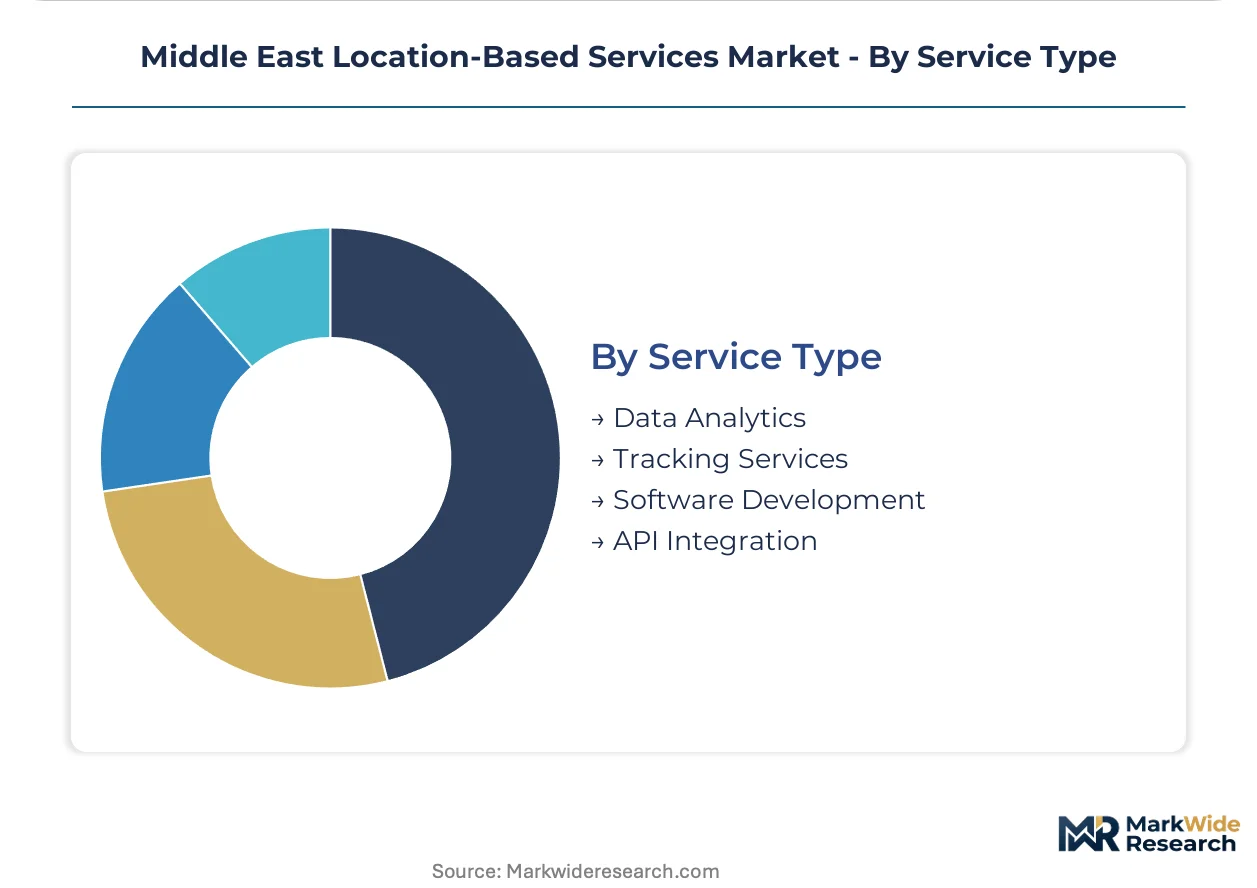
Service Type:
Margin structure varies sharply between commoditized tracking and premium analytics layers.
- Data Analytics:Spatial intelligence platforms processing coordinate streams into actionable business intelligence command premium pricing. Saudi municipal authorities seek ArcGIS-integrated solutions for secondary city planning.
- Tracking Services:Real-time location monitoring for fleet and asset applications faces commoditization pressure as hardware costs decline and platform competition intensifies.
- API Integration:Connectivity layers enabling legacy cadastral database interoperability with modern location platforms address Saudi Arabia's decades-old municipal system constraints.
- Software Development:Custom application builds for specialized vertical requirements, including Arabic-language regulatory compliance interfaces.
Tracking services retain the broadest installed base; data analytics shows the steepest margin expansion trajectory as intelligence layers differentiate commodity positioning infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators and municipal governments anchor procurement across the Middle East, with regulatory divergence between Saudi localization mandates and UAE cross-border data frameworks reshaping vendor deployment strategies.
Saudi Arabia
The National Data Management Office mandates on-shore processing for all citizen movement datasets, forcing foreign cloud providers to establish local infrastructure or exit public sector contracts. SFDA requires location data integration into healthcare emergency response systems, creating regulated procurement channels for hospital networks. Riyadh's smart city investments are compressing deployment timelines for spatial intelligence platforms serving municipal planning authorities.
United Arab Emirates
MOHAP governs location data integration into healthcare emergency response systems, while the Telecommunications and Digital Government Regulatory Authority imposes cross-border data residency constraints that inflate cloud hosting costs. Dubai's Jebel Ali port ecosystem concentrates freight operators seeking fuel cost optimization through fleet telematics. Mall operators across Dubai and Abu Dhabi are displacing GPS with Bluetooth and ultra-wideband systems for sub-meter footfall analytics.
Qatar
Transportation infrastructure investments ahead of major international events have accelerated smart city platform procurement from logistics operators and municipal authorities. The country's communications regulator shapes data localization requirements for geospatial platforms serving government contracts. Doha's urban development zones are deploying integrated location systems for traffic management and emergency response coordination.
Kuwait
Oil sector logistics operators drive demand for fleet management optimization across refinery supply chains and port operations. National data governance frameworks are evolving toward stricter residency requirements for citizen movement datasets. Kuwait City's commercial district is piloting indoor positioning systems for retail analytics and asset tracking in mixed-use developments.
Oman
Port modernization at Salalah and Sohar is generating procurement pull from maritime logistics operators seeking vessel and container tracking capabilities. The national transport authority is mandating location data integration into public transit and emergency response systems. Muscat's urban expansion is creating demand for cadastral mapping and municipal planning platforms among secondary city authorities.
Middle East Location-Based Services Market Competitive Landscape
Player mix skews toward technology conglomerates with mapping heritage and specialized geospatial software vendors, creating a tiered structure where certification requirements filter mid-tier providers from public sector contracts. Two strategic archetypes dominate: HD mapping specialists leveraging automotive navigation contracts, and enterprise software vendors with ArcGIS-integrated municipal planning platforms. Competitive moves center on ISO/IEC 27001 certification acquisition for geospatial data handling and local partnership structures to satisfy Saudi Arabia's National Data Management Office localization mandates.
Within the mapping heritage tier, HERE Technologies and TomTom International BV exemplify vendors anchoring premium navigation contracts through high-definition road data assets. Among enterprise geospatial platforms, Esri occupies a position representing the ArcGIS-integrated specialization targeting Saudi municipal planning authorities. Google LLC sits within the consumer-facing tier, leveraging Android location stack penetration across the Gulf's smartphone base to channel navigation application distribution.
| Leading Market Players |
|---|
| Google LLC |
| HERE Technologies |
| TomTom International BV |
| ALE International |
| Location Solutions Telemetrics LLC |
| Cisco Systems |
| Microsoft Corporation |
| Esri |
| Zebra Technologies |
| Others |
Pricing and Supply Chain Analysis
Bluetooth beacon displacement of GPS hardware simultaneously compresses component sourcing geography toward East Asian semiconductor foundries and erodes pricing power for satellite-dependent system vendors. This substitution dynamic redirects procurement flows from legacy automotive-grade GPS module suppliers toward low-energy radio-frequency chip specialists, fragmenting supplier concentration while compressing margins on commoditized positioning infrastructure.
Pricing Analysis
Cost-plus contracts with fuel-indexed adjustments dominate fleet management procurement across the UAE's Jebel Ali corridor, insulating operators from diesel volatility while locking in platform provider margins. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 27001-certified vendors from uncertified competitors, with certification premiums widening as Saudi municipal authorities harden compliance requirements. Pricing pressure stems from unbundled hardware-software procurement patterns among mid-sized freight operators seeking total cost optimization. Transportation companies exhibit acute price sensitivity, whereas healthcare providers under SFDA and MOHAP mandates accept premium tiers for localized data architectures.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical semiconductor import routes for GPS and Bluetooth module assembly operations across GCC states, exposing positioning hardware supply chains to maritime chokepoint risk. Component sourcing draws from Taiwan, South Korea, and China for RF chips, satellite receivers, and telematics processors. Battery cell supply for beacon deployments rests on Chinese and South Korean cathode production. Single-source vulnerability concentrates in high-precision timing crystal manufacturing. Distribution runs through Dubai-based logistics integrators serving Saudi Arabia and UAE end-users directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-sized UAE freight operators consolidating procurement volumes through multi-year platform negotiations, shifting margin capture toward logistics aggregators and away from fragmented hardware vendors.
For Market Incumbents: Shield installed base relationships by accelerating ISO/IEC 27001 certification acquisition ahead of Saudi National Data Management Office enforcement waves, while deepening backward integration into Saudi-based data center infrastructure to satisfy localization mandates. The priority lever centers on captive cloud capacity in Riyadh, neutralizing foreign-hosted competitors facing architectural redesign costs. For New Entrants and Emerging Players: Lead with ultra-wideband precision tier offerings targeting Dubai mall operators dissatisfied with Wi-Fi fingerprinting accuracy limitations, positioning against legacy Bluetooth beacon vendors. The most penetrable white space sits in Saudi secondary city municipal planning authorities lacking ArcGIS-integrated spatial intelligence platforms. A channel partnership strategy with established local system integrators accelerates regulatory navigation and contract access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet telematics providers facing margin compression from unbundled procurement trends and hardware commoditization. Long-term viability favors vendors with vertical integration into data analytics layers and regulatory-compliant localization infrastructure. The signal to watch is Saudi National Data Management Office enforcement intensity against foreign-hosted architectures, which would trigger accelerated consolidation toward on-shore capable platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Saudi Data Center Localization | Establishes compliant infrastructure for National Data Management Office citizen movement dataset processing requirements. |
| Ultra-Wideband Platform Launch | Captures premium positioning tier in Dubai mall ecosystem displacing legacy Bluetooth accuracy limitations. |
| ISO/IEC 27001 Certification Pathway | Unlocks public sector procurement channels among Saudi municipal planning authorities and UAE smart city programs. |
| Fleet Analytics Software Acquisition | Integrates intelligence layer atop commoditized GPS hardware to restore margin compression from unbundled procurement. |
| Healthcare System Partnership | Secures regulated revenue streams under SFDA and MOHAP emergency response system mandates. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations managers, municipal GIS directors, hospital emergency response coordinators, retail mall technology officers, and geospatial platform engineers, and refined through secondary validation against Telecommunications and Digital Government Regulatory Authority filings, Saudi National Data Management Office standards documentation, SFDA and MOHAP procurement guidelines, GCC customs trade data, and SEC disclosures from listed positioning technology vendors. Bottom-up demand modeling across transportation, retail, healthcare, and government verticals was triangulated with top-down market sizing from technology shipment data.
Variance decomposition structured the analytical framework across technology modality, application use case, end-user compliance intensity, and service type margin tier throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including smart city infrastructure investment trajectories and regulatory mandate implementation schedules. Modeled inputs incorporated fleet telematics adoption curves, indoor positioning precision requirements, and data localization compliance timelines specific to GCC geospatial markets.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council infrastructure investment commitment or accelerated regulatory enforcement timelines would require recalibration. Forecasts reflect assumptions regarding Bluetooth and ultra-wideband substitution rates, Saudi cloud localization cost structures, and healthcare emergency system procurement continuity. Revision becomes warranted when National Data Management Office enforcement crosses thresholds triggering mass foreign vendor exit or when maritime logistics disruptions exceed historical Strait of Hormuz closure patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Tablet PC Market
Others
Global Food Fiber Market
Others
Global Extruded Plastics Market
Others
Thiamethoxam Market
Others
Thailand Travel Retail Market
Others
Fenoxanil Market
Others
Bicycle Panniers Market
Others
Profiling Floats Market
Others
Boston Round Bottle Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Agitation System Market
Others
Traditional PC Market
Others
Europe Medical Simulation Market
Others
Insoluble Sulfur Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Smart Home Gateways Market