
 Sandwich Maker Market | 2026-2036
Sandwich Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Maker Market Analysis
Commercial kitchen buyers are unwinding the historical dominance of home-use purchasers as quick-service restaurants and cloud kitchen operators scale their equipment procurement. Philips leverages its European manufacturing footprint to sustain premium positioning in panini grill segments. Hamilton Beach competes on volume through broad retail distribution across North American mass-market channels. Bajaj Electricals anchors its position in South Asian commercial kitchens with cost-optimized stainless steel constructions.
A sandwich maker is an electromechanical or manually operated appliance designed to heat, compress, and seal bread-based preparations between two hinged cooking plates, typically operating at 750–1500 watts with aluminum or cast iron plate substrates coated in food-grade non-stick polymers. Its primary commercial purpose is to deliver consistent throughput of hot-pressed sandwiches with minimal operator skill. Electric sandwich makers generate the largest revenue pool among product types, though panini grills command superior margins in European cafe and food truck deployments. Removable plate configurations represent the fastest-growing feature segment, as health inspectors in multiple jurisdictions mandate easier sanitization protocols.
The U.S. Department of Energy enforces minimum efficiency standards for residential kitchen appliances, while the EU Ecodesign Directive and CE marking requirements govern standby power and material safety for units sold across member states. India's BIS certification mandates thermal safety testing for imported electric cooking equipment, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving efficiency thresholds and regional labeling schemes to determine where product redesign investments will preserve market access against tightening regulatory baselines.
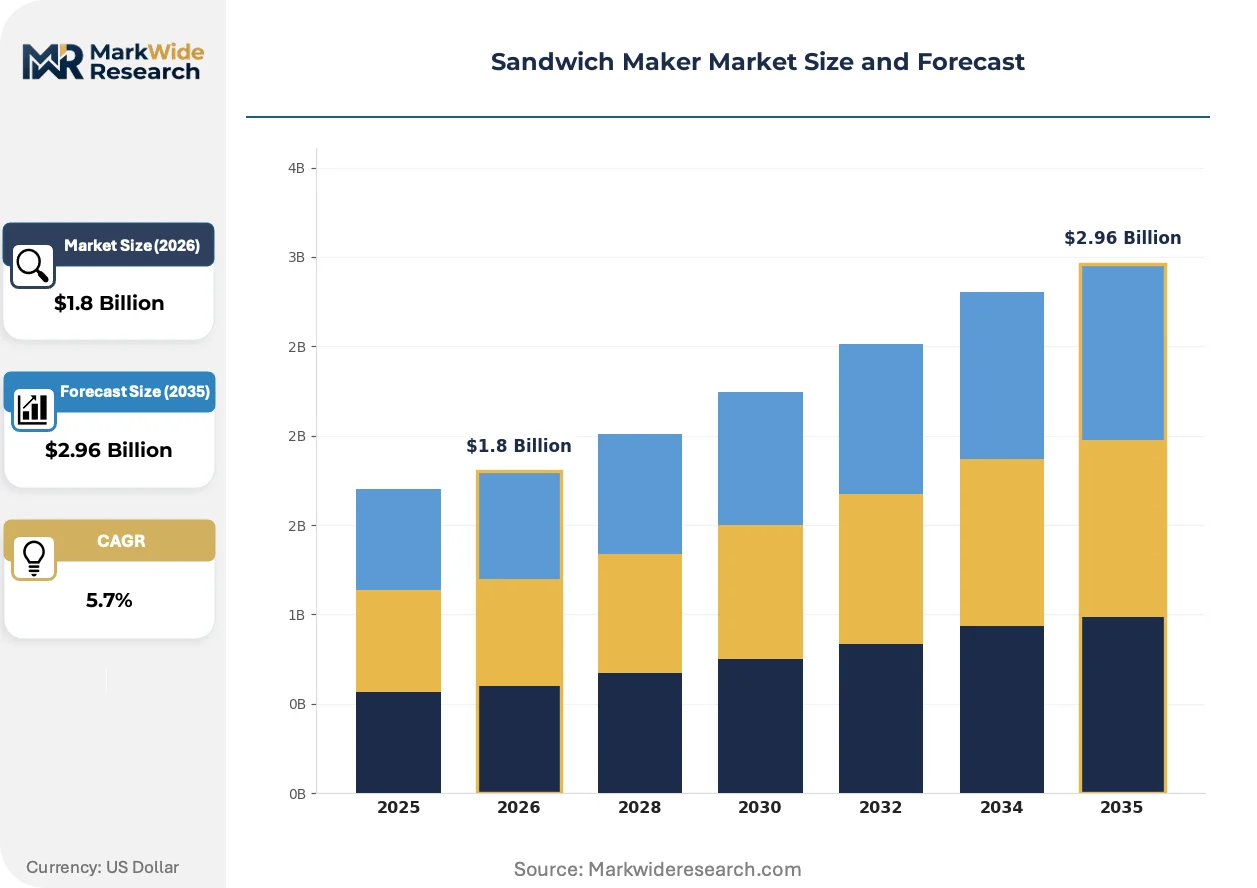
Market Dynamics
Quick-service restaurants are compressing equipment replacement cycles as labor costs tighten and throughput consistency becomes a competitive weapon. This demand rotation from residential to commercial buyers is restructuring supplier priorities across product development and channel investment.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates are accelerating demand for low-wattage models across European commercial kitchens. Operators face compliance deadlines that favor equipment replacement over retrofit.
- Cloud kitchen proliferation:Ghost kitchen operators in urban clusters require compact, high-throughput equipment that minimizes footprint and skill requirements. This segment is scaling procurement faster than traditional brick-and-mortar expansion.
- Removable plate technology:Health inspector protocols in multiple jurisdictions now mandate easier sanitization access. Manufacturers offering tool-free plate removal are capturing preference share in institutional bidding.
Market Restraints
- Aluminum price volatility:Cast aluminum plate substrates face input cost swings that compress margin stability for mid-tier manufacturers. Hedging programs add administrative overhead that smaller suppliers struggle to absorb.
- Supply concentration in East Asian component sourcing:Control electronics and heating element supply clusters create vulnerability to logistics disruptions. Buyers face extended lead times during port congestion events.
- Induction heating substitution:Commercial kitchens with existing induction infrastructure increasingly favor compatible press equipment over dedicated electric sandwich makers. This technical displacement threatens volume in retrofit scenarios.
Strategic Opportunities
- German equipment replacement wave:Commercial foodservice equipment replacement cycles have shortened in this market. Suppliers with local service networks can capture upgrade demand from aging panini grill installed bases.
- Food truck mobility requirements:Mobile operators need lightweight, dual-voltage equipment compatible with generator and shore power. This application segment remains underpenetrated by incumbent residential-focused suppliers.
- U.S. Department of Energy appliance standards:Tightening efficiency thresholds create regulatory tailwind for manufacturers with advanced thermal engineering. Early compliance investments position suppliers for federal procurement eligibility.
Industry Challenges
- Sanitation certification timelines:NSF International and equivalent hygiene certifications require extended testing protocols. Product launches face 4-6 month delays that miss seasonal procurement windows.
- Legacy kitchen integration:Commercial buyers need equipment compatible with existing ventilation hoods and electrical circuits. Retrofit complexity slows adoption in older foodservice facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Maker Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Sandwich Makers, Manual Sandwich Presses, Panini Grills, Toasters Application: Commercial Kitchens, Home Use, Food Trucks, Cafes Material: Stainless Steel, Non-Stick Coating, Cast Iron, Aluminum Feature: Adjustable Temperature, Removable Plates, Indicator Lights, Compact Design |
| Companies Covered | Black+Decker, Panasonic, Philips, George Foreman, De'Longhi Appliances, Hamilton Beach, Breville, Bajaj Electricals, Cuisinart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Maker Market Emerging Trajectories
Ceramic non-stick coatings are displacing traditional PTFE formulations as thermal stability and durability requirements intensify in high-cycle commercial environments. This materials transition is compressing supplier R&D timelines and reshaping coating chemistry partnerships.
Smart temperature control systems with IoT connectivity are displacing mechanical thermostats in premium commercial deployments. Hotel chains and contract foodservice operators are adopting these systems to standardize output across distributed locations and enable remote diagnostics. The technology is compressing warranty cost structures while raising upfront equipment pricing.
The EU Ecodesign Directive's standby power limits are forcing redesign of control board architectures. Manufacturers serving European markets must eliminate parasitic power draw below one watt, adding component cost but preserving market access. German and French commercial buyers are prioritizing compliant models in public sector tenders.
Equipment-as-a-service models are penetrating quick-service restaurant procurement. Franchise operators favor fixed monthly payments covering maintenance and replacement over capital purchases. This shift is most visible in U.S. coastal markets where liquidity constraints and tax optimization drive leasing preference.
Sandwich Maker Market Segmentation
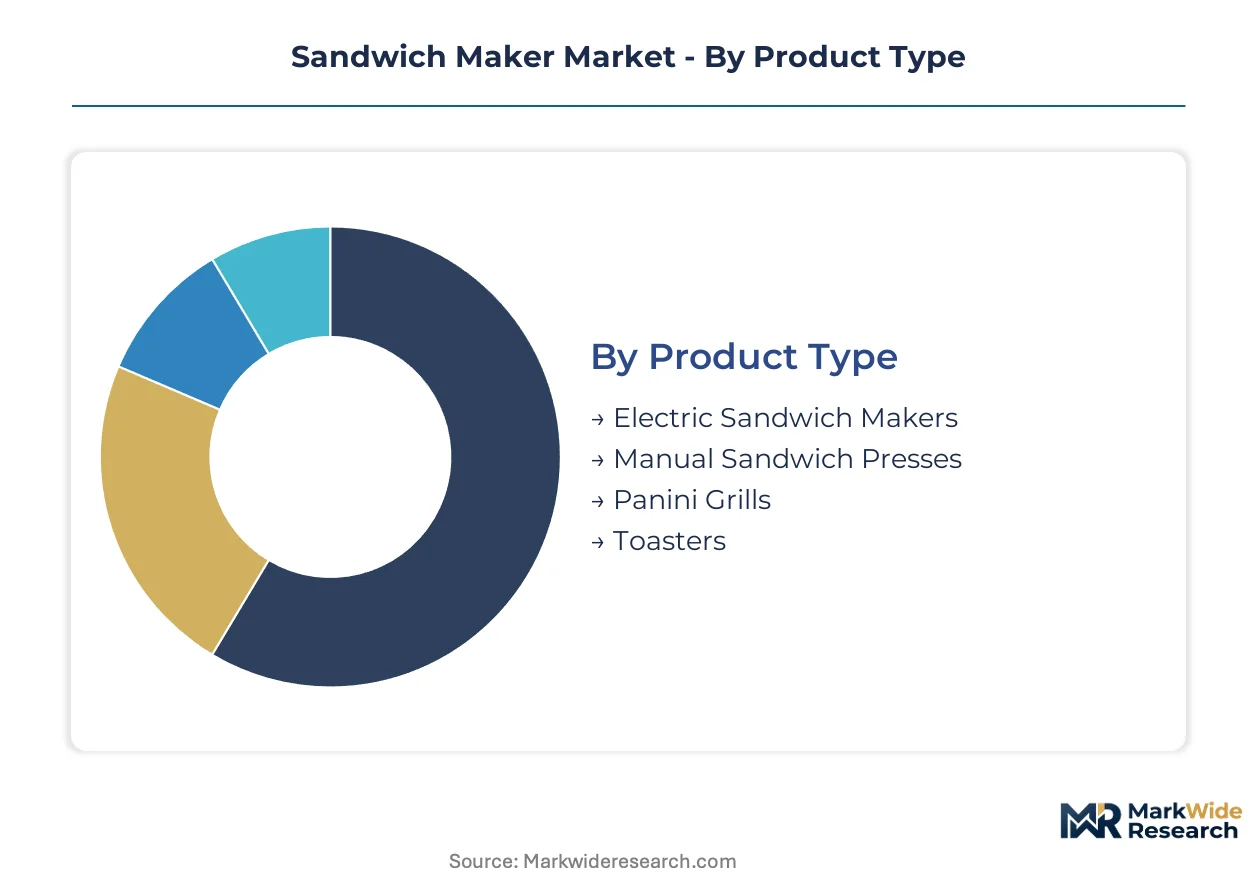
Equipment buyers in the sandwich maker market face divergent technical and economic trade-offs across product architectures, use environments, and material specifications. Segmentation clarity enables suppliers to align R&D investment with the specific throughput, durability, and compliance requirements of each buyer cohort.
Product Type:
Panini grills face the strongest substitution pressure from induction-compatible press equipment in commercial retrofit scenarios, while electric sandwich makers confront efficiency mandates that threaten legacy control architectures.
- Electric Sandwich Makers:These units operate at 750–1500 watts with aluminum or cast iron plate substrates coated in food-grade non-stick polymers. Demand concentrates in quick-service restaurant chains across Germany and the United States as operators replace aging equipment to meet tightening EU Ecodesign Directive and U.S. Department of Energy efficiency thresholds.
- Panini Grills:Hinged cooking plates with ribbed surfaces deliver characteristic sear marks and superior thermal retention for artisan bread applications. European cafe and food truck deployments in France and Italy command premium positioning, though induction heating substitution threatens volume in kitchens with existing compatible infrastructure.
- Manual Sandwich Presses:Non-electric compression tools suit off-grid food trucks and outdoor catering operations with generator constraints.
- Toasters:Single-function browning equipment occupies the lowest price tier in residential mass-market channels.
Electric sandwich makers anchor the volume base while panini grills gain share at the steepest rate in European commercial deployments.
Application:
Cost tier stratification separates capital-intensive commercial procurement from price-sensitive residential purchasing, with mobility requirements creating a distinct mid-tier segment.
- Commercial Kitchens:High-throughput operations in quick-service restaurants and cloud kitchens demand equipment with NSF International sanitation certification, tool-free removable plates, and IoT-enabled temperature standardization across distributed locations.
- Food Trucks:Mobile operators require lightweight, dual-voltage equipment compatible with generator and shore power configurations. This segment remains underpenetrated by incumbent residential-focused suppliers despite expanding urban food truck clusters in U.S. coastal markets.
- Home Use:Residential buyers prioritize compact footprint and retail availability through mass-market channels.
- Cafes:European independent coffee shops favor premium panini grills with ceramic non-stick coatings for high-cycle durability.
Commercial kitchens dominate absolute revenue contribution while food trucks present the most rapid procurement acceleration among emerging application segments.
Material:
Supply concentration in East Asian aluminum sourcing creates margin volatility that reshapes material selection priorities across manufacturer tiers.
- Aluminum:Cast aluminum plate substrates offer rapid heat-up and lightweight construction ideal for high-turnover commercial environments. Price volatility in London Metal Exchange aluminum contracts compresses margin stability for mid-tier manufacturers lacking hedging program scale.
- Stainless Steel:Corrosion-resistant housings and structural components satisfy health inspector protocols in institutional bidding across India, where BIS certification mandates thermal safety testing for imported equipment.
- Non-Stick Coating:PTFE formulations face displacement by ceramic alternatives as thermal stability requirements intensify.
- Cast Iron:Superior thermal mass suits low-and-slow cooking applications in premium European cafe deployments.
Aluminum maintains the broadest installed base while ceramic coating substitution accelerates most quickly in high-cycle commercial specifications.
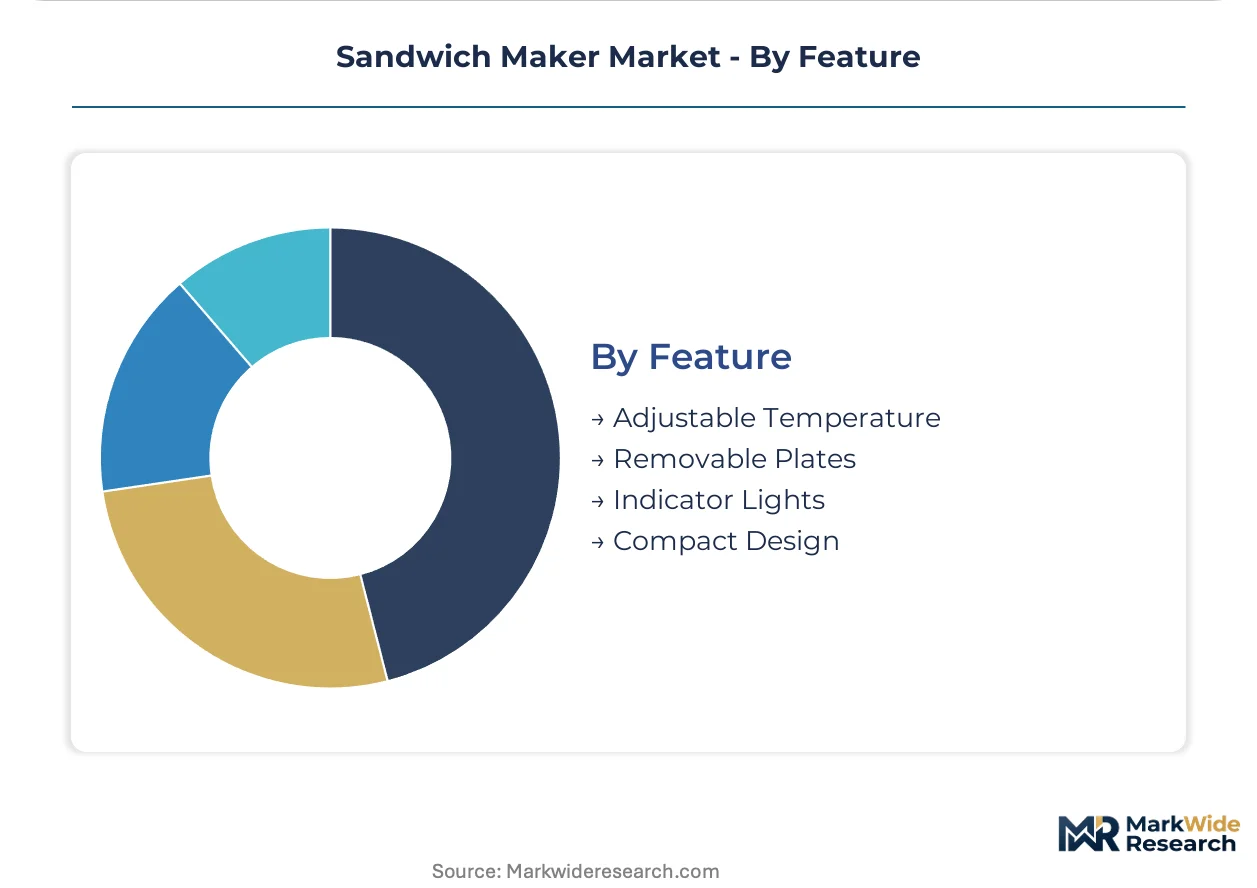
Feature:
Maturity gradients separate established indicator light configurations from emerging smart connectivity architectures that compress warranty cost structures.
- Removable Plates:Tool-free plate removal configurations enable compliance with health inspector sanitization mandates in multiple U.S. jurisdictions and European member states. Manufacturers offering this feature capture preference share in institutional bidding against fixed-plate legacy equipment.
- Adjustable Temperature:Microprocessor-controlled thermal management supports product versatility across bread types and filling compositions. Hotel chains adopt these systems to standardize output quality across distributed franchise locations.
- Indicator Lights:Simple heating status signaling occupies the lowest feature tier in economy residential models.
- Compact Design:Footprint minimization targets cloud kitchen operators in dense urban real estate markets.
Removable plates constitute the largest feature-driven revenue pool while adjustable temperature systems with IoT connectivity climb the fastest in premium commercial deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary distribution hub for European commercial foodservice equipment, with direct rail links to industrial clusters in the Ruhr and Bavaria enabling rapid inland penetration of imported cooking appliances.
Germany
Commercial kitchen equipment replacement cycles have compressed to 4-5 years as operators face EU Ecodesign Directive compliance deadlines. The Federal Environment Agency enforces standby power limits below one watt for all new electrical cooking equipment. Industrial concentration centers on Stuttgart and Munich, where precision engineering suppliers serve premium panini grill manufacturers with ceramic coating substrates.
United States
Cloud kitchen operators in urban clusters scale procurement of compact, high-throughput sandwich makers faster than traditional brick-and-mortar expansion. The Department of Energy appliance standards mandate minimum efficiency thresholds that threaten legacy control architectures. Equipment distribution concentrates in Chicago and Dallas logistics hubs, where foodservice distributors maintain regional inventory pools for quick-service restaurant chains.
India
Cost-optimized stainless steel constructions dominate commercial kitchen procurement as cloud kitchen startups proliferate in Mumbai and Bangalore. BIS certification mandates thermal safety testing for imported electric cooking equipment, creating compliance barriers for non-domestic suppliers. Manufacturing clusters in Pune and Ahmedabad supply housing components and heating elements to domestic assemblers serving South Asian markets.
France
Independent cafe operators in Paris and Lyon favor premium panini grills with ceramic non-stick coatings for high-cycle durability. ANSM hygiene protocols align with EU-wide health inspector mandates for tool-free plate removal configurations. The Rhône-Alpes region hosts specialized coating chemistry partnerships that supply thermal stability formulations to commercial equipment fabricators.
China
Control electronics and heating element manufacturing clusters in Shenzhen and Dongguan supply component assemblies to global sandwich maker brands. GB standards govern electrical safety and electromagnetic compatibility for domestic market sales. Yangtze River Delta port infrastructure enables export consolidation for East Asian component sourcing networks serving European and North American assembly operations.
Sandwich Maker Market Vendor Landscape
Concentration sits with diversified appliance conglomerates that leverage scale economies across multiple kitchen equipment categories. The vendor base stratifies across three tiers: premium European engineering houses, volume-driven North American mass-market suppliers, and cost-optimized Asian fabricators. Strategic moves center on geographic licensing agreements and component supply partnerships that secure aluminum plate sourcing against London Metal Exchange volatility.
Among diversified conglomerates, Panasonic and Philips exemplify the premium-tier archetype through European manufacturing footprints and ceramic coating technology partnerships. Hamilton Beach represents the volume-driven North American position, competing through broad retail distribution across mass-market channels. Bajaj Electricals anchors the cost-optimized Asian tier, occupying a position in South Asian commercial kitchens with stainless steel construction expertise.
| Leading Market Players |
|---|
| Black+Decker |
| Panasonic |
| Philips |
| George Foreman |
| De'Longhi Appliances |
| Hamilton Beach |
| Breville |
| Bajaj Electricals |
| Cuisinart |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Shenzhen and Dongguan component clusters shapes both supply concentration and price floors for mid-tier manufacturers lacking hedging scale. This dynamic compresses margin stability for electric sandwich makers while premium panini grill suppliers preserve pricing power through ceramic coating partnerships.
Pricing Analysis
Volume-discount tiering structures separate premium European engineering houses from mass-market North American suppliers and cost-optimized Asian fabricators. Three-tier pricing structure across premium, standard, and economy levels differentiates by NSF International certification grade and ceramic versus PTFE coating chemistry. Pricing pressure stems from aluminum price volatility on the London Metal Exchange, which erodes margin buffers for cast aluminum plate substrates. Quick-service restaurant chains exhibit the least price sensitivity due to equipment-as-a-service adoption, while residential mass-market buyers drive the steepest discount demands.
Supply Chain Analysis
Just-in-time inventory strategies dominate among quick-service restaurant chains seeking to minimize working capital, while strategic stockpiling prevails among premium panini grill manufacturers hedging against ceramic coating substrate shortages. Control electronics and heating element supply concentrates in China, with secondary clusters in South Korea and Japan. Raw material dependencies center on cast aluminum from East Asian smelters, food-grade non-stick polymers from specialized chemical suppliers, and stainless steel housings from Indian domestic mills. Single-source vulnerability in control board architectures creates exposure to port congestion events at Yangtze River Delta terminals. Distribution runs through foodservice equipment distributors maintaining regional inventory pools in Chicago and Dallas logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service models represent a service-attach opportunity expanding faster than hardware sales, with fixed monthly payment structures covering maintenance and replacement now preferred by franchise operators in U.S. coastal markets.
For Market Incumbents: Shield installed base revenue against induction heating substitution by accelerating IoT-enabled temperature standardization deployments that compress warranty cost structures. Deepen backward integration into ceramic coating chemistry partnerships in the Rhône-Alpes region to secure thermal stability formulations. Fortify channel control through exclusive service network agreements that lock out emerging competitors from institutional bidding. For New Entrants and Emerging Players: Lead with food truck mobility requirements as the most penetrable white-space segment, where dual-voltage lightweight configurations remain underaddressed by residential-focused incumbents. Target cloud kitchen operators in dense urban real estate markets demanding compact footprint equipment. Pursue a direct-to-operator go-to-market angle bypassing traditional foodservice distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified appliance conglomerates with scale economies across multiple kitchen equipment categories. Long-term viability hinges on regulatory compliance capabilities spanning EU Ecodesign Directive standby power limits and U.S. Department of Energy efficiency thresholds. Acquisition targets should display established NSF International certification pathways and local service network density. Watch for aluminum price volatility crossing thresholds that trigger margin compression events among mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Technology Partnership | Rhône-Alpes chemistry suppliers enable thermal stability formulations displacing PTFE in high-cycle environments. |
| IoT-Enabled Temperature Standardization | Hotel chains adopt remote diagnostics to compress warranty costs across distributed franchise locations. |
| Equipment-as-a-Service Model Expansion | Fixed monthly payments covering maintenance accelerate procurement preference among liquidity-constrained operators. |
| Dual-Voltage Product Development | Food truck operators require generator and shore power compatibility in underpenetrated mobile segments. |
| NSF International Certification Investment | Tool-free removable plate configurations capture institutional bidding preference against fixed-plate legacy equipment. |
Methodological Framework
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with quick-service restaurant procurement directors, cloud kitchen operators, foodservice equipment distributors, and ceramic coating chemistry suppliers. Primary fieldwork captured equipment replacement cycle compression patterns and sanitation certification timeline constraints. Secondary validation drew from EU Ecodesign Directive implementation guidance, U.S. Department of Energy appliance standard dockets, and Indian BIS certification protocols. Bottom-up unit shipment estimates triangulated against top-down revenue segmentation.
Variance decomposition across product type, application environment, material specification, and feature configuration anchored the analytical framework over the projection horizon. Modeled dimensions included electric sandwich maker versus panini grill architectures, commercial kitchen versus food truck versus residential end-uses, and aluminum versus stainless steel versus cast iron substrates. CAGRs derived from replacement cycle dynamics, regulatory compliance deadlines, and cloud kitchen proliferation rates. Industry-specific inputs incorporated London Metal Exchange aluminum price trajectories and NSF International certification pipeline durations.
The analysis sits within stated boundaries; outcomes outside sustained cloud kitchen expansion or aluminum price stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding EU Ecodesign Directive enforcement timelines and U.S. Department of Energy threshold tightening schedules. Revision becomes warranted when induction heating substitution rates cross critical adoption thresholds in commercial retrofit scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Modular Zero-Waste Kitchen Appliance Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Global Portable Blenders Market