
 Global Ceramic Tableware Market | 2026-2036
Global Ceramic Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Tableware Market Analysis
Fine-dining restaurant procurement is realigning toward artisan-grade ceramic collections as experiential hospitality operators trade up from generic white-ware. Villeroy & Boch leverages its German manufacturing heritage to dominate European contract hospitality supply. Churchill China PLC anchors the UK foodservice channel through dedicated kiln-to-table logistics networks. Noritake Co., Ltd. competes across Asia-Pacific with specialized bone china formulations for luxury hotel chains.
Ceramic tableware comprises fired clay bodies—typically porcelain, stoneware, earthenware, or bone china—shaped through slip casting or jiggering and finished with lead-free glazes meeting food-contact standards. The primary commercial purpose spans durable service vessels for prepared food and beverage presentation across residential and institutional dining environments. Porcelain commands the premium margin pool due to translucency and chip resistance, while stoneware extends volume leadership through durability-to-cost ratios in casual dining. The restaurant end-user segment concentrates growth as chain operators standardize tabletop identity across locations.
REACH in Europe restricts heavy metal migration in glazed surfaces, while FDA food-contact regulations govern lead and cadmium leachate thresholds for US-bound shipments. China's GB standards and SAMR enforcement impose parallel domestic purity benchmarks that export-oriented kilns must simultaneously satisfy. Stakeholders must monitor tightening alignment between EU Green Deal material traceability requirements and emerging carbon-border adjustments affecting kiln-fired goods.
Market Dynamics
Hospitality procurement consolidation is compressing supplier margins while simultaneously demanding traceable, low-carbon kiln operations from ceramic tableware vendors.
Growth Catalysts
- EU Green Deal alignment:Carbon-border adjustments on kiln-fired imports are accelerating decarbonization investments among export-oriented manufacturers in Foshan and Jingdezhen.
- Boutique hotel expansion:Experiential hospitality operators in Portugal, Morocco, and Vietnam are commissioning artisan-grade collections that command 3-4x standard white-ware pricing.
- Digital glaze formulation:AI-driven color-matching systems are reducing R&D cycles from months to weeks, enabling rapid customization for restaurant chain rollouts.
Market Restraints
- Natural gas price volatility:Kiln firing costs in Germany and Italy have fluctuated 40-60% since 2022, forcing mid-tier producers toward electric tunnel kilns with steep retrofit capex.
- Kaolin supply concentration:High-grade deposits in Brazil and Ukraine face extraction constraints, with ceramic-grade material prioritization competing against paper and pharmaceutical demand.
- Lead-free glaze technical ceiling:Cadmium-free red pigments still exhibit color drift above 1,200°C, limiting design palettes for premium bone china collections.
Strategic Opportunities
- Indonesia foodservice underpenetration:Jakarta and Surabaya hotel construction is outpacing local kiln capacity, creating import substitution openings for Vietnamese and Thai producers.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates are rewarding ceramic vendors with verified Scope 1-3 data, differentiating compliant suppliers in contract bids.
- Direct-to-chef platforms:Instagram-native tableware marketplaces are bypassing traditional hospitality distributors, connecting Jingdezhen studios directly to Michelin-starred kitchens in Singapore and Sydney.
Industry Challenges
- Glaze chemist talent scarcity:Formulation expertise concentrated among aging specialists in Stoke-on-Trent and Arita is not transferring to younger technicians at sufficient rates.
- Dual certification timelines:Simultaneous FDA and REACH compliance testing for new colorants extends product launch windows by 8-14 months, freezing seasonal collection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Tableware Market |
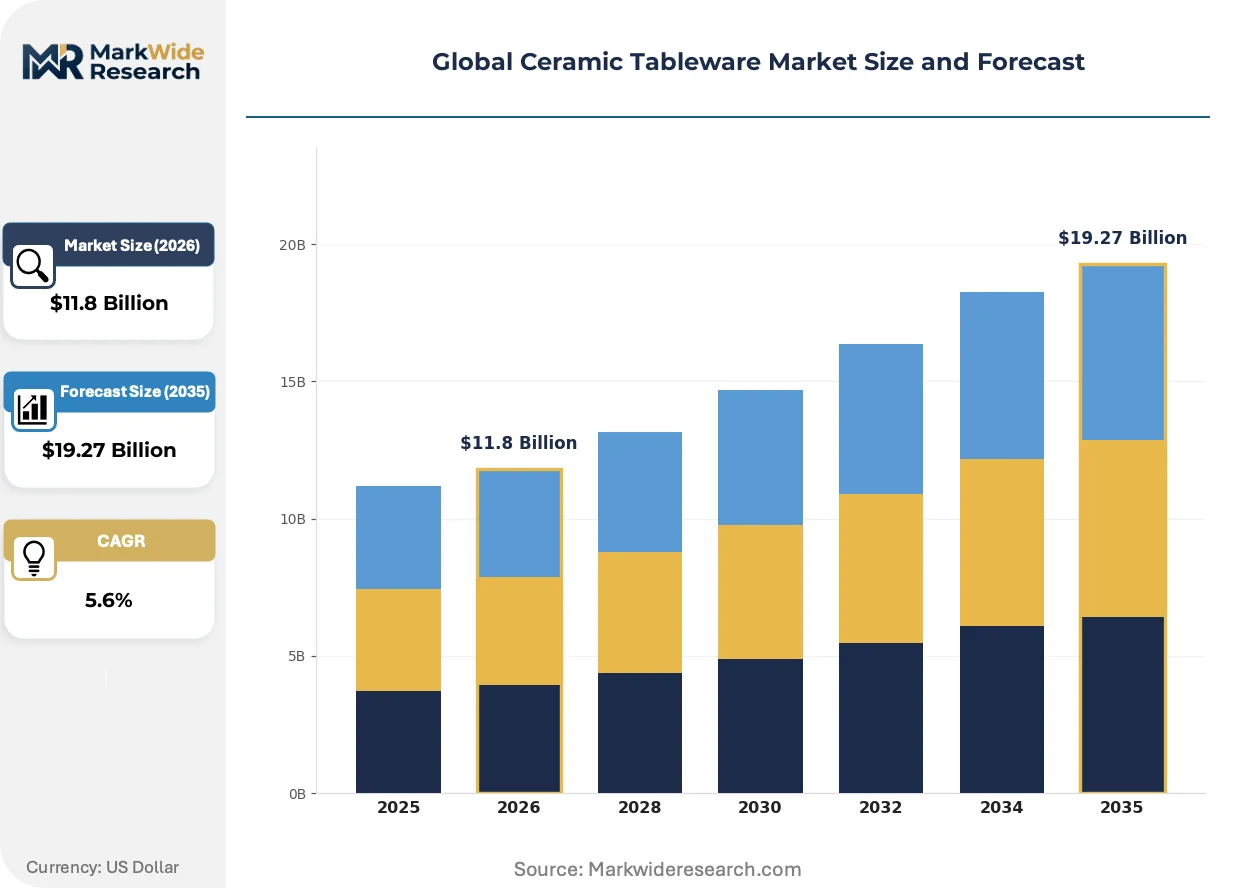
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dishes, Bowls, Mugs, Plates End User: Households, Restaurants, Cafes, Catering Services Material Grade: Porcelain, Stoneware, Earthenware, Bone China Design Style: Traditional, Modern, Artistic, Minimalist |
| Companies Covered | Villeroy & Boch, Lenox Corporation, Corelle Brands, Noritake Co., Ltd., Churchill China PLC, Fiskars Group, Wedgwood, Royal Doulton, Portmeirion Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Tableware Market Emerging Trajectories
Kiln technology and procurement digitization are converging to reshape how ceramic tableware moves from clay body to tabletop, with sustainability verification becoming as critical as chip resistance.
Electrified tunnel kiln systems are integrating renewable energy sourcing with predictive maintenance algorithms to stabilize firing curves. Large-format hotel chains in Scandinavia are specifying these kilns as mandatory vendor qualifications. The technology is integrating carbon accounting directly into production cost structures, compressing the premium gap between conventional and clean-fired porcelain.
REACH Annex XVII amendments on crystalline silica exposure are mandating wet-process reforms in European grinding operations. Industrial ceramic workers in Spain and Poland now require respiratory protection protocols that add 12-15% to finishing costs. Bone china manufacturers with legacy dry-grinding assets in Portugal are accelerating relocation to Turkey to maintain EU market access.
Chef-driven tabletop curation is displacing procurement-by-catalog among independent restaurant groups. Younger operators in Melbourne, Mexico City, and Copenhagen are sourcing mixed-material place settings through direct studio relationships rather than consolidated hospitality suppliers. This pattern is most visible in the 50-150 cover segment, where Instagram presentation drives repeat visitation and justifies per-cover equipment spend 2-3x above chain benchmarks.
Global Ceramic Tableware Market Segmentation
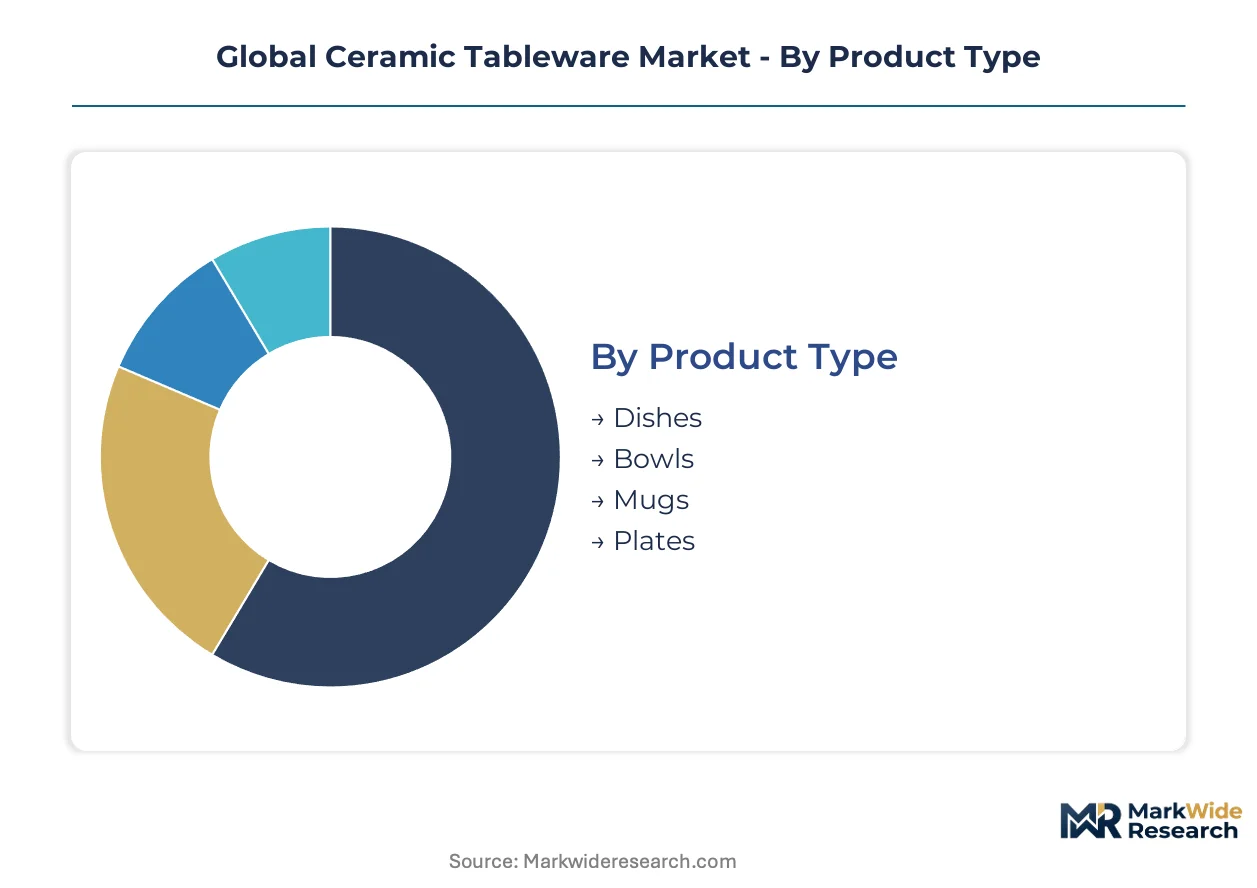
Segmentation in ceramic tableware reveals how kiln economics, hospitality procurement patterns, and regulatory compliance intersect to determine margin distribution. Understanding these divides exposes where manufacturers can defend pricing power versus where commoditization pressures dominate.
Product Type:
Supply concentration in dish and plate manufacturing favors producers with tunnel kiln scale in Foshan and Jingdezhen, while mugs and bowls attract fragmented artisan competition.
- Dishes:Broad rimmed vessels fired at 1,200-1,350°C, typically glazed for scratch resistance. Demand concentrates in fine-dining chains across Germany and Japan where tabletop identity standardization requires 10,000+ unit orders with color consistency guarantees.
- Plates:Flat service pieces demanding dimensional uniformity for automated dishwashing systems. European contract hospitality procurement in Portugal and Morocco drives specifications for thermal shock resistance above 180°C.
- Bowls:Curved vessels with higher clay body thickness requirements. Ramen shops in Tokyo and Sydney commission specialized 800-1,200ml formats with underglaze decoration durability.
- Mugs:Handle-integrated cylinders facing the strictest handle-attachment strength testing. Coffee chain procurement in the United States prioritizes 340-470ml capacity standardization with stackability metrics.
Today's leader: Plates. Tomorrow's challenger: Bowls.
End User:
Application-based cost tiers separate institutional procurement with 3-5 year replacement cycles from residential purchasing driven by aesthetic turnover.
- Restaurants:High-velocity service environments requiring chip-resistant formulations and rapid reorder fulfillment. Michelin-starred kitchens in Copenhagen and Singapore source through direct-to-chef platforms bypassing traditional distributors.
- Households:Residential replacement purchasing concentrated in China's tier-1 cities and India's metropolitan corridors, with online marketplace penetration reshaping brand access.
- Cafes:Mid-velocity operators balancing durability with Instagram-presentable design. Melbourne and Mexico City independent operators drive mixed-material place setting trends.
- Catering Services:Rental and event-based procurement demanding stackability and transport durability. Scandinavian hotel chains now specify electrified kiln sourcing as mandatory vendor qualification.
Volume concentrates with Restaurants. Margin expansion favors Households.
Material Grade:
Margin stratification across material grades reflects kaolin purity requirements and firing temperature energy intensity, with premium grades capturing certification-driven pricing premiums.
- Porcelain:Kaolin-dominant body fired above 1,300°C yielding translucency and vitrified density. Luxury hotel chains in Vietnam and boutique properties in Morocco commission artisan-grade collections commanding substantial premiums over standard white-ware.
- Stoneware:Feldspathic composition at 1,200-1,280°C balancing durability against energy costs. Casual dining standardization across chain operators in the United States and Germany drives volume leadership through cost-to-performance ratios.
- Bone China:Bone ash incorporation requiring specialized grinding protocols. REACH Annex XVII crystalline silica mandates are accelerating relocation of legacy dry-grinding assets from Portugal to Turkey.
- Earthenware:Porous low-fire body below 1,100°C with higher glaze absorption. Artisan studio production in Jingdezhen and Arita maintains decorative technique traditions for collector markets.
Porcelain commands margin leadership. Stoneware extends volume dominance.
Design Style:
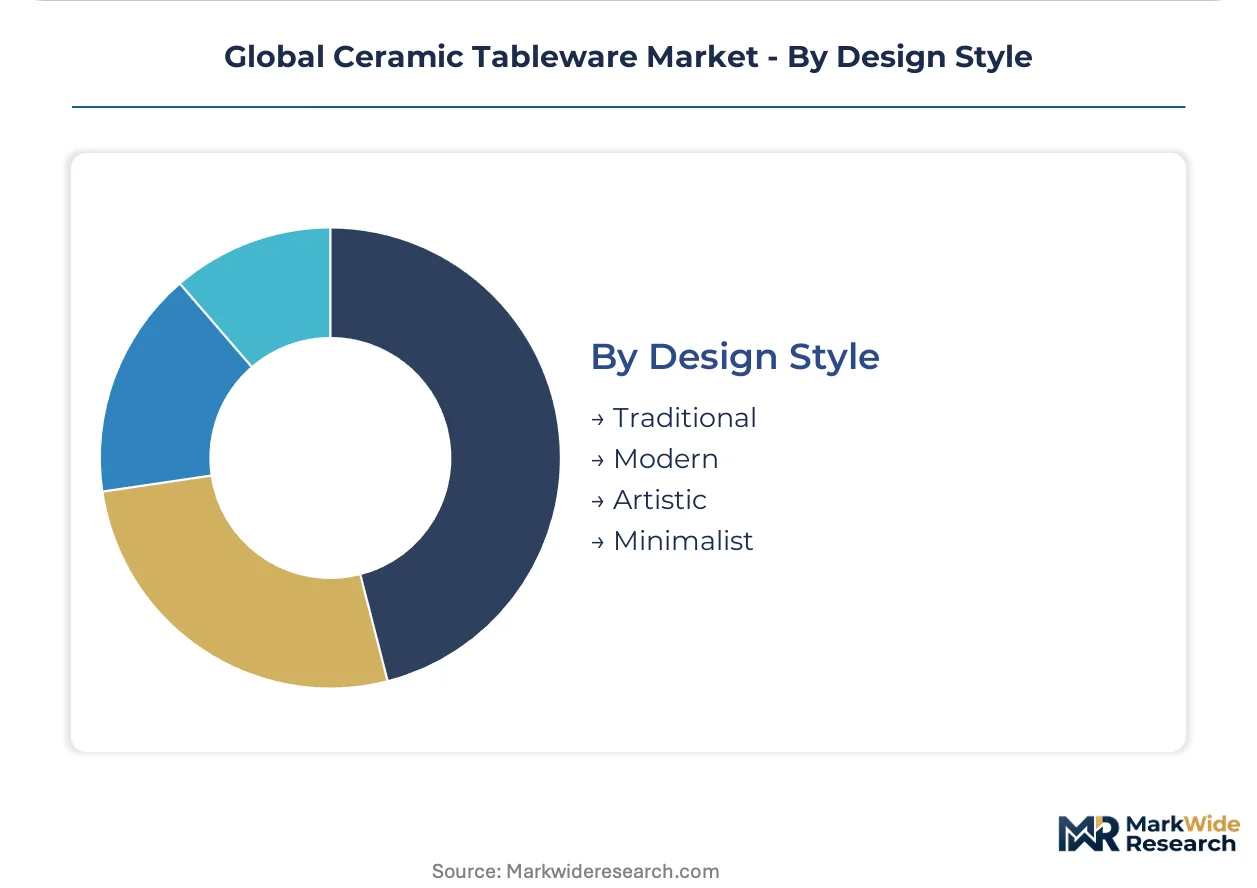
Customer type differentiation separates procurement-by-catalog hospitality buyers from chef-driven curators seeking studio-direct relationships.
- Modern:Clean geometric profiles with matte glaze finishes. Younger operators in Australia's 50-150 cover segment justify per-cover equipment spend multiples above chain benchmarks for Instagram presentation value.
- Traditional:Historic pattern reproductions requiring specialized mold archives. European heritage manufacturers leverage German and UK manufacturing lineage for contract hospitality supply.
- Minimalist:Reduced silhouette vocabulary with single-tone glaze systems. AI-driven color-matching from digital glaze formulation enables rapid customization for restaurant chain rollouts.
- Artistic:Hand-finished variability and mixed-media integration. Direct-to-chef platforms connect Jingdezhen studios to Michelin-starred kitchens in Singapore and Sydney.
Modern captures hospitality procurement. Artistic gains share in independent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jingdezhen anchors global ceramic tableware production through centuries of accumulated kiln expertise and concentrated artisan networks. Export-oriented manufacturers in this Jiangxi cluster now face carbon-border adjustment pressures from EU Green Deal implementation. The regional map below traces how regulatory divergence and hospitality procurement patterns reshape competitive positioning across five critical markets.
China
Domestic consumption in Shanghai and Beijing drives premium porcelain demand as tier-1 households trade up from basic white-ware. SAMR enforces GB standards on heavy metal migration that export kilns must satisfy alongside REACH and FDA requirements. Foshan manufacturers are electrifying tunnel kilns to meet Scandinavian hotel chain carbon specifications.
Germany
Boutique hotel construction in Berlin and Munich sustains artisan-grade procurement at 3-4x standard pricing multiples. ECHA REACH Annex XVII amendments on crystalline silica exposure mandate wet-process reforms in grinding operations. Villeroy & Boch leverages manufacturing heritage to dominate European contract hospitality supply from Saarland facilities.
United States
Fine-dining chains standardizing tabletop identity across locations concentrate growth in the restaurant end-user segment. FDA food-contact regulations govern lead and cadmium leachate thresholds for imported shipments. Corelle Brands anchors mass-market distribution through dedicated logistics networks serving casual dining operators.
Japan
Specialized bone china formulations for luxury hotel chains sustain premium margin pools in Tokyo and Osaka markets. METI oversees alignment between domestic JIS standards and evolving international purity benchmarks. Arita maintains decorative technique traditions for collector markets despite aging glaze chemist expertise.
United Kingdom
Foodservice channel procurement runs through Stoke-on-Trent's concentrated kiln infrastructure despite talent transfer challenges to younger technicians. CSRD supply chain disclosure mandates reward vendors with verified Scope 1-3 carbon data. Churchill China PLC anchors contract supply through kiln-to-table logistics specialization.
Global Ceramic Tableware Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit electric tunnel kilns to meet carbon-border adjustment requirements. The vendor base stratifies between heritage European manufacturers with archival mold collections and Asian scale producers serving institutional procurement. Three archetypes define competitive positioning: artisan-grade studios commanding chef-direct relationships, mid-tier contract specialists optimizing hospitality logistics, and mass-market operators leveraging volume standardization. M&A activity concentrates among European heritage brands consolidating archival assets, while strategic partnerships emerge between Jingdezhen kilns and Scandinavian hotel chains seeking verified low-carbon sourcing.
Among heritage European manufacturers, Villeroy & Boch and Wedgwood occupy positions defined by manufacturing lineage and archival pattern libraries. Noritake Co., Ltd. exemplifies the Asia-Pacific premium specialist archetype, while Corelle Brands represents scale-driven mass-market positioning. These three anchors illustrate how geographic origin and company structure correlate with divergent strategic postures across the procurement spectrum from Michelin-starred kitchens to casual dining chains.
| Leading Market Players |
|---|
| Villeroy & Boch |
| Lenox Corporation |
| Corelle Brands |
| Noritake Co., Ltd. |
| Churchill China PLC |
| Fiskars Group |
| Wedgwood |
| Royal Doulton |
| Portmeirion Group |
| Others |
Supply Flow & Price Mechanics
Glaze chemist expertise concentrated in Stoke-on-Trent and Arita generates labor-cost differentials that widen pricing-tier spreads between artisan-grade bone china and mass-market stoneware. European REACH compliance and FDA food-contact certification requirements add fixed-cost layers that premium producers absorb through brand premiums while mid-tier competitors face margin compression.
Pricing Analysis
Input-cost pass-through from kaolin and natural gas volatility shapes contract structures across the ceramic tableware market. Three-tier pricing structure across premium, standard, and economy levels separates artisan-grade porcelain collections from institutional white-ware and discount retail lines. Price differentiation rests on certification tier—REACH and FDA compliance versus domestic-only standards—and volume scale with chain hospitality procurement. Cost compression in mid-tier stoneware is intensifying because electrified kiln retrofits add capex burdens without immediate energy savings. Casual dining chains exhibit highest price sensitivity through standardized tender processes, while boutique hotel operators accept substantial premiums for traceable low-carbon provenance.
Supply Chain Analysis
Dual-sourcing requirements from Scandinavian hotel chains and European contract hospitality operators mandate multi-supplier qualification across Chinese and Turkish production bases. Geographic supply concentrates in China, Turkey, and Portugal, with high-grade kaolin drawing from Brazilian and Ukrainian deposits facing extraction constraints. Raw material dependencies center on ceramic-grade kaolin, bone ash for china formulations, and lead-free glaze minerals including zircon and feldspar. Single-source vulnerability runs through Jingdezhen's concentrated artisan networks for specialized decorative techniques. Distribution runs through dedicated kiln-to-table logistics networks serving contract hospitality, direct-to-chef platforms for independent restaurants, and consolidated retail channels for residential replacement purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic tableware market offers margin-expansion pathways through electrified kiln cost-down curves and chef-driven premium-tier shifts toward artisan-grade collections. Stakeholders should align capability investments with the sustainability verification and customization velocity now separating winning suppliers from commodity players.
For Market Incumbents: Lock in carbon-verified supply relationships with Scandinavian hotel chains before EU Green Deal alignment hardens into mandatory specifications. Consolidate archival mold assets and glaze formulation IP through targeted acquisitions of distressed Portuguese bone china manufacturers facing REACH Annex XVII relocation pressures. Defend against direct-to-chef platform disintermediation by building studio-direct relationships with Michelin-starred kitchens in Singapore and Sydney. For New Entrants and Emerging Players: AI-driven digital glaze formulation offers a technology-first wedge into restaurant chain procurement cycles compressed from months to weeks. Target Indonesia's underpenetrated foodservice market where Jakarta and Surabaya hotel construction outpaces local kiln capacity. Establish go-to-market positioning through Instagram-native tableware marketplaces connecting production studios directly to independent operators in Melbourne and Mexico City. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European heritage brands with stranded dry-grinding assets facing Turkish relocation decisions. Long-term viability across the analysis window favors producers with verified Scope 1-3 carbon data rewarded by CSRD supply chain disclosure mandates. Watch electrified kiln adoption rates among Foshan manufacturers as the inflection indicator for carbon-border adjustment preparedness and contract hospitality qualification access.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Tunnel Kiln Retrofit | Carbon-border adjustment preparedness secures Scandinavian hotel chain contract eligibility. |
| Direct-to-Chef Platform Launch | Instagram-native marketplaces bypass traditional hospitality distributors for Michelin-starred access. |
| AI-Driven Glaze Formulation Investment | Color-matching algorithms compress R&D cycles for rapid restaurant chain customization. |
| Backward Integration into Kaolin Sourcing | Captive supply of Brazilian ceramic-grade material secures purity benchmarks against paper industry competition. |
| CSRD-Aligned Carbon Verification Program | Scope 1-3 data differentiation rewards compliant vendors in EU corporate sustainability reporting bids. |
Methodological Framework
Coverage spans China, Germany, Japan, the United States, and the United Kingdom, with primary inputs from each market's ceramic production clusters and hospitality procurement centers. Primary interviews combined perspectives from kiln operations managers, glaze formulation chemists, hospitality procurement directors, chef-owner operators, and ceramic studio founders with secondary validation from SAMR enforcement records, ECHA REACH Annex XVII amendments, FDA food-contact guidance documents, and customs trade data. Bottom-up unit economics from individual production facilities triangulated against top-down hospitality spend analysis across the projection horizon.
Rate-of-change decomposition separated volume growth from pricing evolution across material grade, end-user segment, and design style dimensions. The analytical framework modeled porcelain, stoneware, bone china, and earthenware tiers alongside restaurant, household, cafe, and catering service applications through regional regulatory cluster variations. CAGRs derived from fitted growth curves applied to baseline consumption estimates, with kiln capacity utilization and electrification capex cycles serving as industry-specific forecast inputs throughout the modeling period.
The model holds under stable regulatory enforcement of REACH and FDA heavy metal migration standards; deviation in carbon-border adjustment implementation timelines or kaolin supply disruption would shift volume and value trajectories. Forecasts reflect assumptions around electrified kiln cost curves and chef-driven procurement pattern persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Microwave Safe Utensils Market
Household Items
Book Light Market
Household Items
Insulated Drinkware Market
Household Items
Towel Warmers Market
Household Items
Toilet Cistern Blocks Market
Household Items
Candle Air Fresheners Market
Household Items
Dryer Sheets Market
Household Items
Kuwait Gas Hobs Market
Household Items
MENA POU Water Purifiers Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Europe Cookware Market
Household Items
Water Purifier Bottle Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Soap Dispenser Market