
 Camping Cookware Market | 2026-2036
Camping Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Cookware Market Insights
The split between premium titanium systems and mass-market aluminum kits is recalibrating how manufacturers allocate production capacity and channel investment. GSI Outdoors leverages its deep retail partnerships with specialty outdoor chains to sustain volume in the mid-tier aluminum segment. Snow Peak differentiates through design-forward titanium collections that command shelf space in boutique camping retailers across Japan and North America. MSR anchors its competitive position with technical cookware systems engineered for high-altitude expeditions where reliability outweighs cost sensitivity.
Camping cookware encompasses portable vessels and heating apparatus purpose-built for meal preparation in off-grid environments, typically constructed from aluminum alloys, stainless steel, titanium, or cast iron with thermal efficiency ratings and weight specifications calibrated to specific activity intensities. The material dimension reveals titanium gaining ground among backpackers who prioritize gram-count reduction, while cast iron maintains durable loyalty in car-camping and basecamp contexts where heat retention trounces portability concerns. Stove-integrated systems represent the fastest-growing product type as consumers seek nested, fuel-efficient solutions that minimize pack volume and setup complexity.
The US Consumer Product Safety Commission and California Proposition 65 impose strict leaching and labeling requirements on cookware coatings and metal compositions, compelling manufacturers to reformulate non-stick treatments and document material provenance. The EU REACH framework restricts certain chemical additives in anodized aluminum finishes, redirecting R&D investment toward ceramic and plasma-hardened surface technologies. Stakeholders must monitor evolving state-level chemical disclosure laws and third-party certification programs such as OEKO-TEX and bluesign as these standards increasingly filter into retail procurement criteria and consumer purchase decisions.
Market Dynamics
The titanium-aluminum material split is forcing manufacturers to reconfigure production lines and inventory strategies around divergent weight-performance tradeoffs demanded by backpackers versus car campers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants in aerosol coatings is accelerating ceramic-based non-stick formulations across European supply chains.
- Ultralight trekking:Gram-conscious backpackers are driving titanium nesting systems into specialty retail assortments previously dominated by aluminum.
- Vanlife infrastructure:Purpose-built vehicle kitchens in Germany and the American West are sustaining demand for compact, multi-fuel stove-integrated cookware.
Market Restraints
- Raw material volatility:Sponge titanium prices fluctuate with aerospace demand cycles, compressing margins for premium cookware producers.
- Anodizing chemical restrictions:REACH Annex XVII limits on hexavalent chromium in surface treatments are raising compliance costs for aluminum finishers.
- Cast iron weight penalty:The 2-4 kilogram mass of traditional Dutch ovens excludes this material from fast-growing ultralight segments.
Strategic Opportunities
- Nordic backcountry skiing:Norway and Sweden's hut-to-hut trail networks present underdeveloped demand for collapsible titanium kettles.
- Plasma-hardened surfaces:Ceramic-metal matrix coatings are converging with induction-compatible bases to create premium hybrid product tiers.
- Direct-to-trailhead fulfillment:Partnerships with outdoor gear rental platforms in Colorado and British Columbia enable try-before-buy distribution models.
Industry Challenges
- Welding certification gaps:Thin-gauge titanium fabrication requires specialized orbital welding expertise that remains scarce in contract manufacturing pools.
- Multi-standard labeling:Simultaneous compliance with California Proposition 65, EU REACH, and Japan's Food Sanitation Act extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Cookware Market |
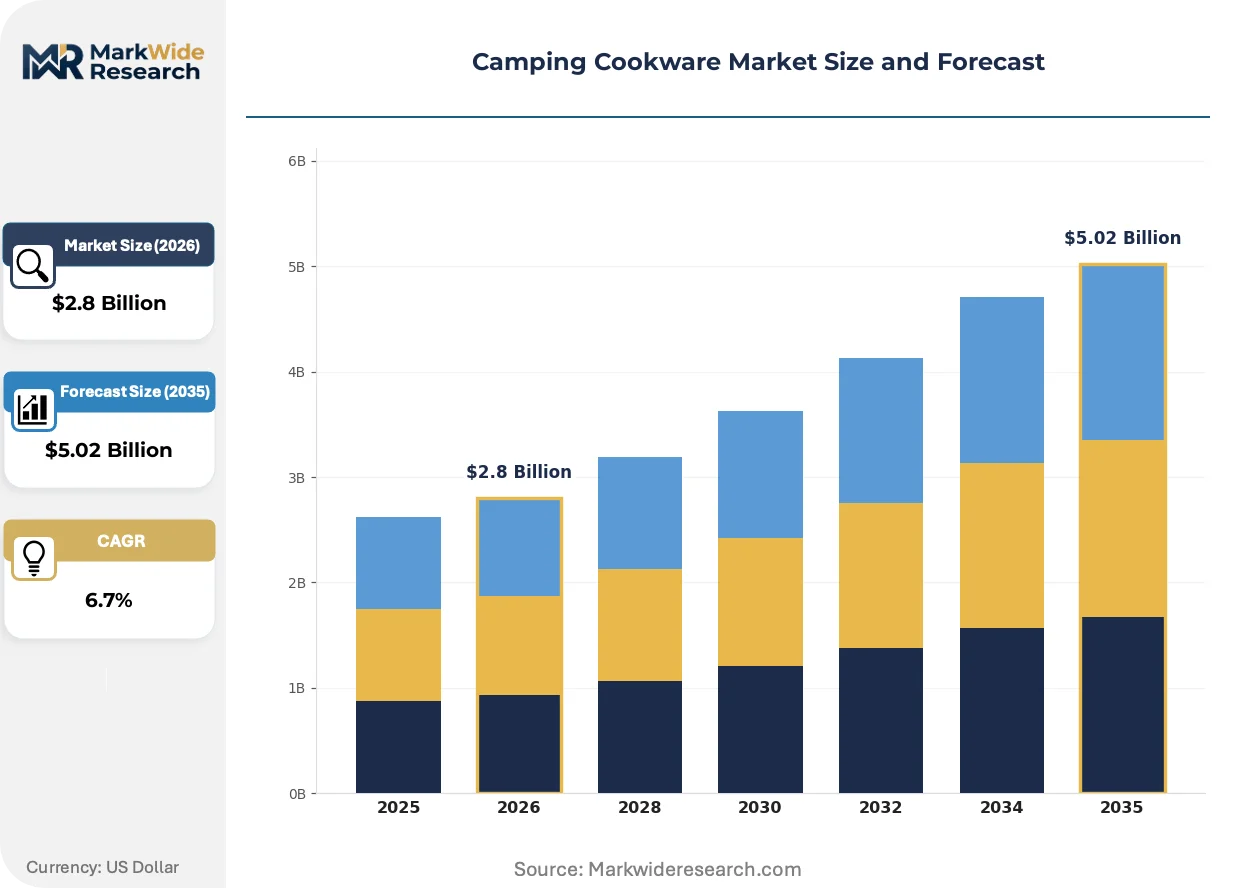
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pans, Grills, Stoves, Utensils Material: Aluminum, Stainless Steel, Titanium, Cast Iron End User: Outdoor Enthusiasts, Casual Campers, Survivalists, Backpackers Distribution Channel: Retail Stores, Online Marketplaces, Camping Equipment Shops, Wholesale |
| Companies Covered | Primus, Lodge Cast Iron, GSI Outdoors, Stanley, Sea to Summit, MSR, Camp Chef, Petromax, Snow Peak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Cookware Market Trends and Innovations
Material science breakthroughs and regulatory chemical phaseouts are compressing traditional product lifecycles while opening premium positioning opportunities for compliant manufacturers.
Plasma electrolytic oxidation surface treatments are converging with anodized aluminum substrates to create scratch-resistant, non-reactive cooking surfaces that outperform conventional PTFE coatings. Alpine guide services and search-and-rescue teams are adopting these systems for field durability. The technology is converging with induction-compatible base layers to capture stove-integrated system growth.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are compelling reformulation of non-stick coatings across European manufacturing. Anodizers are redirecting capital toward sol-gel ceramic deposition equipment. The mid-tier aluminum segment faces the steepest compliance burden as it lacks R&D scale to absorb rapid chemical substitution cycles.
Subscription-based gear access models are displacing outright ownership among urban millennials entering camping. Specialty retailers in Portland and Denver are piloting seasonal cookware rental alongside tent and sleeping bag programs. The Pacific Northwest represents the most concentrated testbed for this behavioral shift, with REI and regional cooperatives reporting 40% trial-to-purchase conversion on titanium sets.
Camping Cookware Market Segmentation
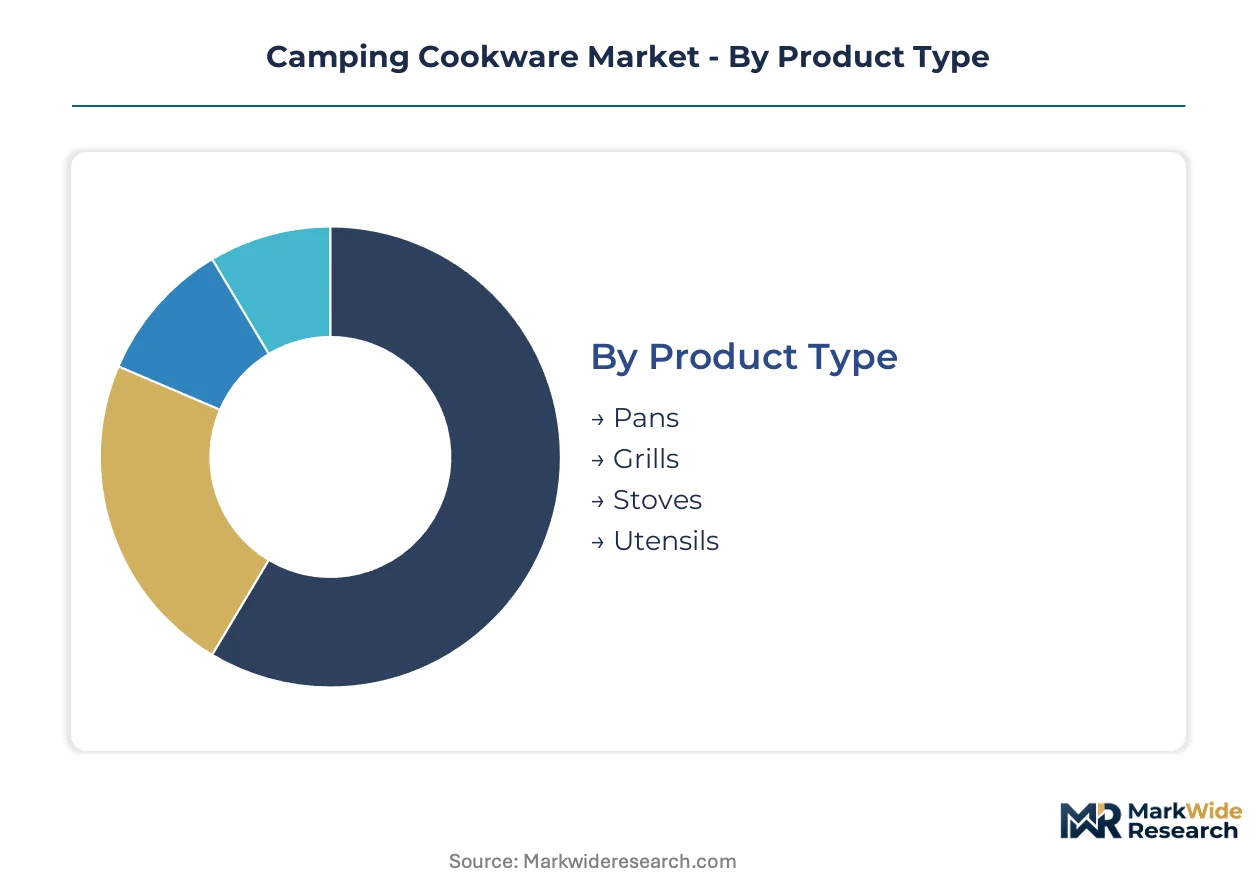
Camping cookware manufacturers calibrate product portfolios across four intersecting dimensions that determine pricing power and channel placement. Material selection and end-user intensity create the sharpest fault lines between mass-market aluminum kits and expedition-grade titanium systems.
Product Type:
Stove-integrated systems embed cookware into unified heating platforms, while standalone vessels require separate burner pairing.
- Pans:Aluminum frypans with ceramic non-stick coatings dominate REI and specialty retail assortments. German vanlife communities sustain premium demand for nesting pan sets with detachable handles that collapse into vehicle galley storage.
- Grills:Portable grate systems with folding legs capture car-camping and overlanding segments where open-fire cooking remains central to the experience. Cast iron grill plates retain heat for searing but exclude themselves from backpacker kits.
- Stoves:Integrated stove-cookware combinations from Jetboil and MSR categories reduce pack volume for alpine expeditions.
- Utensils:Spork-and-cup nesting kits complete system sales in outdoor specialty channels.
Pans lead volumes today; stove-integrated systems are gaining share fastest.
Material:
Cost tiers separate aerospace-grade titanium from commodity aluminum, with stainless steel occupying the durability-per-dollar midpoint.
- Aluminum:Anodized 6061-T6 alloys deliver thermal conductivity at sub-100-gram pot weights for budget-conscious segments. REACH Annex XVII restrictions on hexavalent chromium anodizing are redirecting European production toward ceramic-hardened surface technologies.
- Titanium:Grade 2 and Grade 5 titanium alloys achieve strength-to-weight ratios that justify 3-5x price premiums for gram-counting backpackers. Sponge titanium price volatility tied to aerospace demand cycles compresses margins for cookware specialists.
- Stainless Steel:304-grade vessels resist denting in group camping and basecamp contexts where weight matters less than longevity.
- Cast Iron:Pre-seasoned Dutch ovens and skillets anchor car-camping and cabin rental markets in the American West and Scandinavian lake districts.
Aluminum leads volumes today; titanium climbs the fastest.
End User:
Activity intensity determines whether buyers prioritize durability, weight reduction, or cost minimization.
- Backpackers:Ultralight trekkers on the Pacific Crest Trail and Alpine Haute Route drive titanium kettle and single-pot system sales. Subscription rental platforms in Colorado and British Columbia report 40% trial-to-purchase conversion on premium titanium sets.
- Outdoor Enthusiasts:Weekend hikers and paddlers balance weight against versatility, sustaining mid-tier aluminum and stainless steel volumes.
- Casual Campers:Family car-campers prioritize capacity and price over packability, anchoring cast iron and enamelware demand.
- Survivalists:Preppers and bushcraft practitioners favor multi-fuel compatibility and field-repairability in stainless steel and titanium systems.
Outdoor enthusiasts lead volumes today; backpackers expand most quickly.
Distribution Channel:
Channel selection determines margin capture and brand positioning, with direct-to-consumer growth pressuring traditional wholesale structures.
- Online Marketplaces:Amazon and brand-direct sites capture price-sensitive comparison shoppers. REI's digital platform drives 40% of titanium set trials through seasonal rental-to-own programs.
- Camping Equipment Shops:Specialty retailers in Portland, Denver, and Munich provide tactile evaluation and staff expertise that sustains premium titanium pricing.
- Retail Stores:Big-box outdoor departments move volume in aluminum starter kits for casual entrants.
- Wholesale:Guide services and outdoor education programs procure through institutional channels.
Camping equipment shops lead volumes today; online marketplaces accelerate fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metalworking talent pools in Germany, Japan, and the United States anchor titanium fabrication capabilities for premium cookware production. Alpine guide services in Switzerland and hut-to-hut trail networks in Norway concentrate demand for ultralight systems. Vanlife communities across the American West and Pacific Northwest sustain compact stove-integrated product development.
Germany
Alpine tourism and vanlife culture drive premium titanium and nesting cookware purchases through Munich and Hamburg specialty retailers. The EU F-Gas Regulation and REACH compliance reshape anodizing processes across Baden-Württemberg manufacturing clusters. Thuringia's metalworking heritage supports plasma-hardened surface technology development for export markets.
United States
Backpackers on the Pacific Crest Trail and Appalachian Trail anchor titanium kettle demand through Colorado and British Columbia rental platforms. The Consumer Product Safety Commission and California Proposition 65 enforce strict leaching standards on non-stick coatings. Portland and Denver specialty retailers pilot subscription-based gear access models with 40% trial-to-purchase conversion rates.
Japan
Design-forward consumers in Tokyo and Osaka sustain boutique titanium collections through precision metalworking traditions. METI standards and the Food Sanitation Act govern surface treatment compliance for food-contact materials. Nagoya's aerospace supply base provides orbital welding expertise for thin-gauge titanium fabrication.
Sweden
Hut-to-hut backcountry skiing networks generate underdeveloped demand for collapsible titanium kettles among Nordic outdoor enthusiasts. EU REACH Annex XVII restrictions on hexavalent chromium redirect Stockholm-area anodizers toward ceramic deposition equipment. Jönköping's outdoor manufacturing corridor specializes in nesting systems for Scandinavian export markets.
Canada
Guide services in British Columbia and Alberta procure expedition-grade systems for high-altitude reliability requirements. Health Canada and PMRA oversee chemical safety standards for cookware coatings entering North American distribution. Vancouver's outdoor retail cooperatives test direct-to-trailhead fulfillment partnerships with gear rental platforms.
Camping Cookware Market Competitive Landscape
Top-tier vendors anchor premium titanium positioning, while mid-tier aluminum specialists compete on volume through retail partnerships. The vendor base organizes around three archetypes: design-forward lifestyle brands, technical expedition-grade manufacturers, and heritage cast iron foundries. Consolidation pressure concentrates among aluminum finishers facing REACH chemical substitution costs. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure compliant coating supply chains.
Within the technical expedition-grade tier, MSR and Sea to Summit exemplify positioning around high-altitude reliability requirements. GSI Outdoors occupies a position within mid-tier aluminum volume distribution through specialty retail channel depth. Lodge Cast Iron anchors heritage foundry archetypes serving car-camping and basecamp segments where heat retention outweighs portability constraints. Snow Peak represents design-forward lifestyle positioning through boutique retail placement. Primus and Petromax sit within European fabrication traditions serving multi-fuel stove-integrated system demand.
| Leading Market Players |
|---|
| Primus |
| Lodge Cast Iron |
| GSI Outdoors |
| Stanley |
| Sea to Summit |
| MSR |
| Camp Chef |
| Petromax |
| Snow Peak |
| Others |
Pricing and Supply Chain Analysis
Backward integration into titanium sponge sourcing anchors premium cookware manufacturers' supply position and pricing power against aerospace demand cycles. German and Japanese fabricators with captive aerospace supply relationships command margin stability that outsourced aluminum finishers cannot replicate under REACH chemical substitution pressure.
Pricing Analysis
Bundled stove-integrated systems command 40-60% price premiums over standalone vessels by collapsing fuel efficiency and packability into single purchase decisions. Three-tier pricing structure across premium titanium, mid-grade stainless steel, and economy aluminum levels segments buyers by activity intensity rather than brand loyalty alone. Cost compression in mid-tier aluminum is intensifying because REACH Annex XVII compliance redirects anodizing investment toward ceramic deposition equipment. Casual campers exhibit highest price sensitivity, while alpine expedition buyers prioritize reliability metrics over unit cost.
Supply Chain Analysis
Certification gating through EU REACH, US CPSC, and Japan Food Sanitation Act compliance extends product launch timelines and concentrates qualified supplier pools in Germany, Japan, and the United States. Raw material flows draw from sponge titanium suppliers in aerospace corridors, 6061-T6 aluminum mills in Baden-Württemberg, and precision metalworking clusters in Nagoya. Single-source vulnerability in orbital welding expertise for thin-gauge titanium fabrication constrains capacity expansion. Distribution runs through specialty outdoor retailers in Munich, Denver, and Portland alongside direct-to-consumer platforms with rental-to-own conversion programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through plasma-hardened surface technology premiums and captive titanium supply positions that insulate against aerospace demand volatility.
For Market Incumbents: Anticipate REACH chemical phaseouts by redirecting R&D capital toward sol-gel ceramic deposition and plasma electrolytic oxidation before mid-tier competitors achieve compliance scale. Secure orbital welding certification programs in Nagoya and Thuringia to lock in thin-gauge titanium fabrication capacity. Defensive consolidation of anodizing capacity in Germany and Sweden captures stranded aluminum finishers facing hexavalent chromium restrictions. For New Entrants and Emerging Players: Plasma-hardened surface technology offers entry wedge into premium tier gaps between Snow Peak design positioning and MSR technical expedition anchoring. Nordic backcountry skiing hut networks in Norway and Sweden represent underpenetrated white space for collapsible titanium kettle systems. Direct-to-trailhead fulfillment partnerships with Colorado and British Columbia rental platforms enable low-CAC customer acquisition before specialty retail slotting fee exposure. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap aluminum finishers with REACH-compliant coating capabilities because regulatory compliance barriers prevent new entrant supply expansion. Target fabrication specialists with dual titanium-aluminum production lines and existing OEKO-TEX or bluesign certification infrastructure. Watch sponge titanium price spreads against aerospace contract volumes as inflection signal for premium cookware margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Deposition Equipment Investment | REACH Annex XVII compliance redirects Baden-Württemberg anodizing capacity toward sol-gel surface technologies. |
| Orbital Welding Certification Program | Nagoya aerospace supply base provides scarce thin-gauge titanium fabrication expertise for premium cookware expansion. |
| Direct-to-Trailhead Fulfillment Partnership | Colorado and British Columbia rental platforms enable 40% trial-to-purchase conversion on titanium nesting systems. |
| Plasma-Hardened Surface Technology Launch | Induction-compatible ceramic-metal matrix coatings converge with stove-integrated system growth in German vanlife markets. |
| Captive Titanium Sponge Supply Agreement | Backward integration insulates margin stability against aerospace demand cycle volatility in sponge pricing. |
Research Methodology
Coverage spans Germany, Japan, the United States, Sweden, and Canada, with primary inputs from each market's specialty outdoor retail channels and manufacturing clusters. Primary interviews with titanium fabrication plant managers, specialty retailer category buyers, alpine guide service procurement leads, and outdoor gear rental platform operators combined with secondary validation from EU REACH regulatory filings, US CPSC safety databases, Japan METI standards documentation, and customs trade data. Bottom-up demand modeling across backpacker, outdoor enthusiast, casual camper, and survivalist segments triangulated against top-down titanium and aluminum production capacity estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across material type, product configuration, end-user intensity, and distribution channel dimensions. CAGRs were derived through segment-level demand elasticity modeling and supply capacity constraints over the projection horizon. Forecast inputs incorporate REACH chemical substitution timelines, sponge titanium aerospace contract volumes, and vanlife vehicle registration patterns in Germany and the American West.
The model holds under stable regulatory phaseout schedules and continued aerospace demand absorption of sponge titanium supply; deviation in EU F-Gas Regulation acceleration or titanium aerospace contract surges would shift premium tier margin assumptions. A model refresh is warranted upon material change in REACH Annex XVII enforcement scope or plasma-hardened surface technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
LED Fishing Light Market