
 Reading Glasses Market | 2026-2036
Reading Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Reading Glasses Market Analysis
The EU Green Deal is realigning material sourcing priorities across European eyewear supply chains. EssilorLuxottica leverages its vertically integrated manufacturing footprint to control acetate and metal alloy procurement. Zenni Optical competes through pure-play digital distribution, stripping out optical shop overhead. Hoya Corporation anchors its position in high-index lens technology for premium reading glass applications.
Reading glasses are corrective eyewear with convex lenses manufactured through precision surfacing or molding processes, typically specified in diopter increments from +1.00 to +3.50, designed to compensate for age-related loss of near-focus accommodation. Plastic frames dominate unit volume due to injection-molding scalability and color versatility, while metal frames command higher average selling prices through titanium and stainless-steel compositions. Progressive lenses represent the fastest-expanding lens type as consumers reject visible bifocal lines, and online retail is displacing optical shops among price-sensitive young adult and professional segments.
FDA oversight of medical device classification for corrective eyewear shapes product labeling and import documentation in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in frame coatings and metal alloys. The EU's MDR and CE marking requirements govern lens optical performance claims and impact market access for non-compliant manufacturers. Stakeholders must monitor evolving state-level vision care mandates and reimbursement policy shifts that could redirect consumer spending between retail channels and clinical dispensing.
Market Dynamics
Direct-to-consumer digital distribution is compressing traditional optical retail margins while Medicare reimbursement structures in the United States redirect volume toward clinical dispensing channels.
Growth Catalysts
- Presbyopia Demographics:Aging populations in Japan, Germany, and the United States are expanding the addressable consumer base for near-vision correction products.
- REACH Compliance:The EU's F-Gas Regulation and REACH frameworks are elevating material standards, forcing frame manufacturers toward sustainable acetate and bio-based alternatives.
- High-Index Lens Technology:Thinner, lighter lens substrates are reducing material waste per unit while improving wearer comfort for higher diopter prescriptions.
Market Restraints
- Acetate Supply Concentration:Italian and Chinese suppliers dominate cellulose acetate pellet production, creating input cost volatility for frame manufacturers.
- Progressive Lens Adaptation Period:Consumer dissatisfaction with initial peripheral distortion limits rapid switching from single-vision reading glasses.
- FDA Medical Device Classification:Import documentation and labeling requirements for corrective eyewear create friction for cross-border e-commerce fulfillment.
Strategic Opportunities
- India's Underserved Presbyopic Population:Low penetration of organized retail vision care in tier-2 and tier-3 cities creates white space for affordable reading glass distribution.
- Blue-Light Filtering Coatings:Convergence of screen-time awareness with near-vision correction is opening a premium product tier for office workers.
- Subscription Replenishment Models:Direct-to-consumer brands are piloting automated reorder cycles based on prescription expiration and frame wear patterns.
Industry Challenges
- Optical Surfacing Technician Shortage:Precision lens manufacturing requires skilled operators for free-form surfacing equipment, with training pipelines failing to match replacement demand.
- CE Marking Timeline Compression:The EU's MDR transition is extending certification cycles for lens performance claims, delaying product launches by 8-14 months.
- Legacy ERP Integration:Established manufacturers struggle to synchronize inventory systems with real-time e-commerce fulfillment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reading Glasses Market |
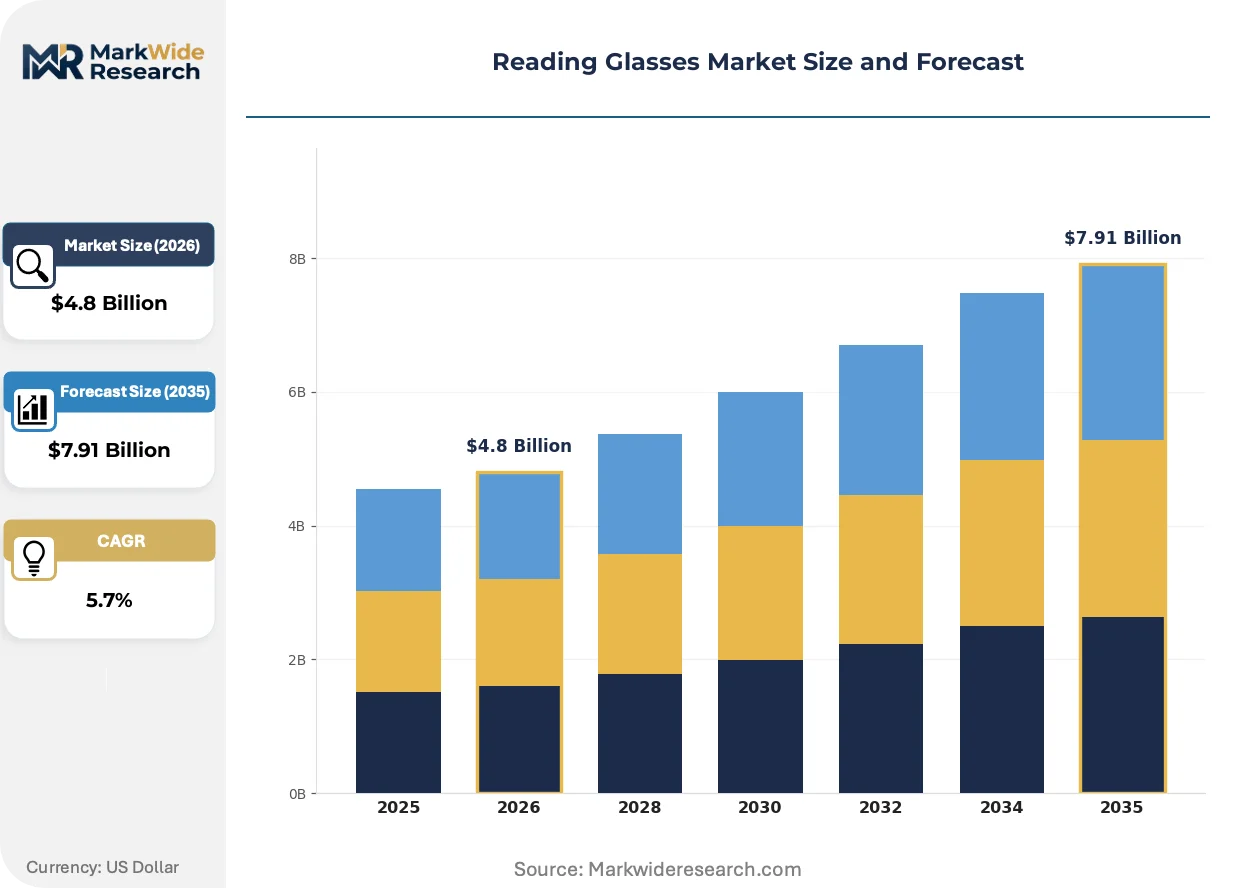
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Frame Material: Plastic, Metal, Wood, Combination Lens Type: Bifocal, Progressive, Single Vision, Photochromic Target Audience: Seniors, Young Adults, Professionals, Students Distribution Channel: Online Retail, Optical Shops, Supermarkets, Specialty Stores |
| Companies Covered | EssilorLuxottica, Carl Zeiss, Bausch & Lomb Incorporated, Hoya Corporation, Safilo Group, Warby Parker, Zenni Optical, Johnson & Johnson Vision Care, De Rigo Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reading Glasses Market Emerging Trajectories
Digital lens surfacing and automated edging systems are compressing production lead times while regulatory pressure on frame materials accelerates sustainable chemistry adoption across supply chains.
Free-form digital surfacing technology is automating the production of customized progressive lenses with individualized corridor placement. Mid-market optical labs in the United States and South Korea are adopting five-axis generators at replacement rates of 12-18% annually. This equipment is automating the elimination of manual fining and polishing stages, reducing per-laboratory headcount requirements by 30-40% while improving surface accuracy tolerances.
The EU Green Deal's chemical sustainability mandates are restricting phthalate plasticizers and heavy-metal pigments in cellulose acetate frame production. Frame manufacturers in Italy and France are reformulating injection-molding compounds to meet ECHA substance restrictions. Small-batch producers are responding by shifting toward castor-oil-derived bioplastics and mineral-based colorants, accepting 15-25% material cost premiums for compliance positioning.
Young adult professionals are abandoning optical shop dispensing in favor of online vision testing apps paired with home try-on programs. This channel rotation is most visible in the United States and United Kingdom, where employer-sponsored vision benefits increasingly permit out-of-network reimbursement for direct-to-consumer purchases. Independent opticians are countering by unbundling eye examination fees from product sales, transparently pricing lens packages to retain service revenue.
Reading Glasses Market Segmentation
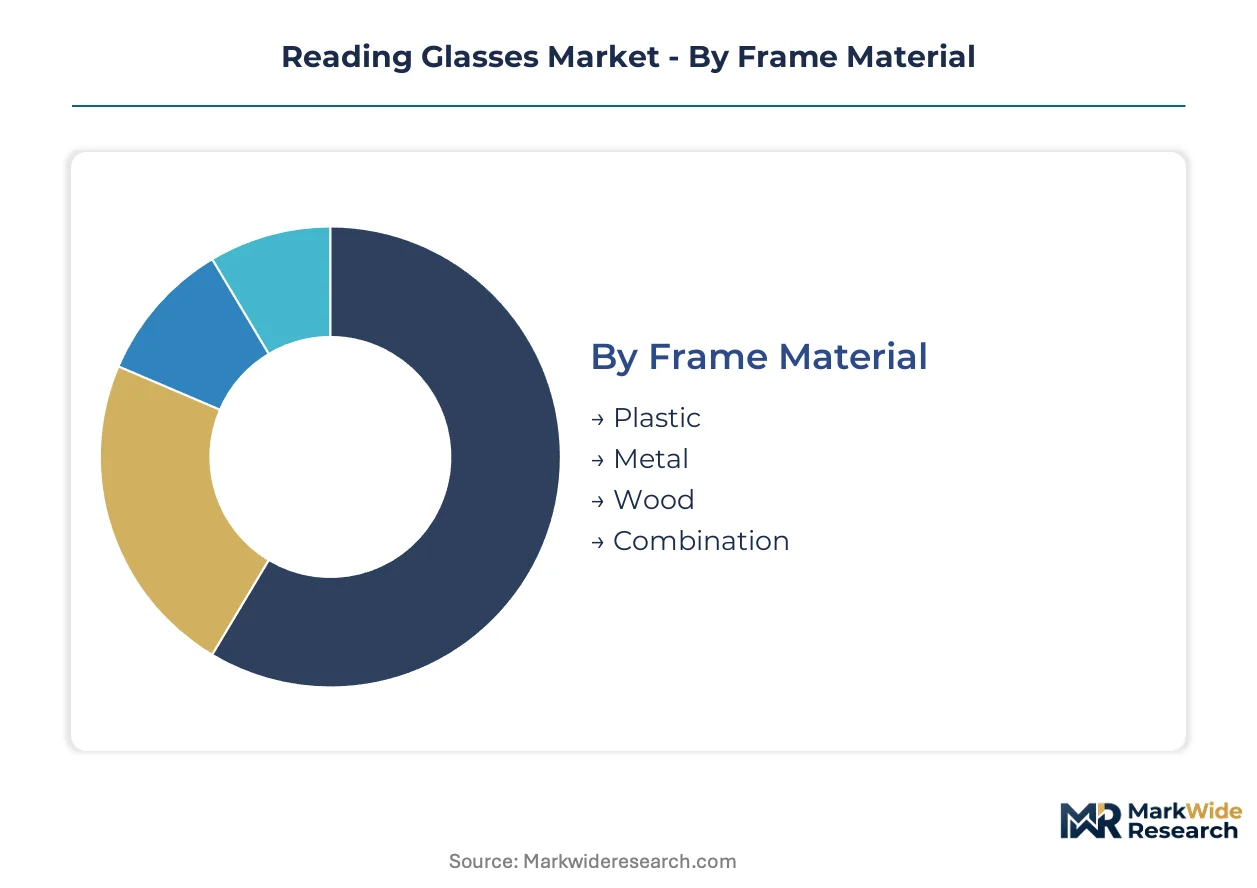
Reading glasses manufacturers allocate capital across divergent production technologies—frame fabrication demands molding and metalworking infrastructure, while lens surfacing requires precision optical equipment. Segmentation reveals where fixed costs concentrate and which product configurations justify specialized capacity investments.
Frame Material:
Capital intensity peaks with metal alloy processing, where titanium vacuum deposition and CNC machining centers require seven-figure equipment outlays. Plastic injection molding scales more linearly but still demands multi-cavity tooling for acetate pellet conversion.
- Plastic:Cellulose acetate pellets undergo multi-cavity injection molding to achieve color versatility and lightweight comfort. Demand clusters in mass-market channels across Germany and the United States where price sensitivity dominates purchasing decisions. REACH compliance is elevating material costs as ECHA restrictions force reformulation away from phthalate plasticizers.
- Metal:Titanium and stainless-steel compositions command premium pricing through vacuum deposition and precision CNC machining. Japanese consumers prioritize hypoallergenic titanium frames for daily wear durability. The segment absorbs the highest per-unit tooling amortization but sustains margin structures above commodity alternatives.
- Wood:Laminated timber and bamboo composites target sustainability-positioned niches with limited production scalability.
- Combination:Hybrid constructions merge metal temples with plastic fronts to balance weight distribution and style flexibility.
Plastic absorbs the bulk of installed capacity; metal is expanding most quickly as premium positioning justifies higher capital deployment.
Lens Type:
Application context determines optical complexity—office workers need intermediate-range clarity, while dedicated readers prioritize near-field sharpness. Manufacturing investment scales with surface customization requirements.
- Progressive:Free-form digital surfacing creates variable power corridors without visible segment lines. Young adult professionals in the United Kingdom and United States reject bifocal aesthetics, driving channel migration toward online retailers offering home try-on programs. Adaptation periods and peripheral distortion complaints create post-purchase service costs.
- Single Vision:Uniform diopter specifications from +1.00 to +3.50 dominate over-the-counter volume through standardized molding processes. Supermarket and drugstore distribution in Japan and Germany relies on immediate availability of common corrections. Margins compress with commoditization but volume velocity supports operational leverage.
- Bifocal:Visible segment lines persist in budget-conscious senior segments despite aesthetic drawbacks.
- Photochromic:Light-reactive coatings add processing steps for indoor-outdoor versatility.
Single vision commands the widest distribution footprint; progressive lenses are gaining share fastest among employed demographics.
Target Audience:
Customer lifecycle stage shapes purchasing frequency, price tolerance, and channel preference—creating distinct service models rather than product differentiation alone.
- Seniors:Presbyopia correction needs intensify with age, generating repeat purchases as prescriptions evolve. Medicare reimbursement structures in the United States redirect volume toward clinical dispensing channels where examination bundling persists.
- Professionals:Screen-time convergence with near-vision demands sustains premium positioning for blue-light filtering coatings. Employer-sponsored vision benefits in the United States increasingly permit out-of-network direct-to-consumer reimbursement.
- Young Adults:Digital-native consumers favor app-based vision testing and subscription replenishment models.
- Students:Budget constraints drive price-focused purchasing in retail pharmacy environments.
Seniors generate the highest absolute unit volume; professionals are expanding fastest through benefit-structured purchasing.
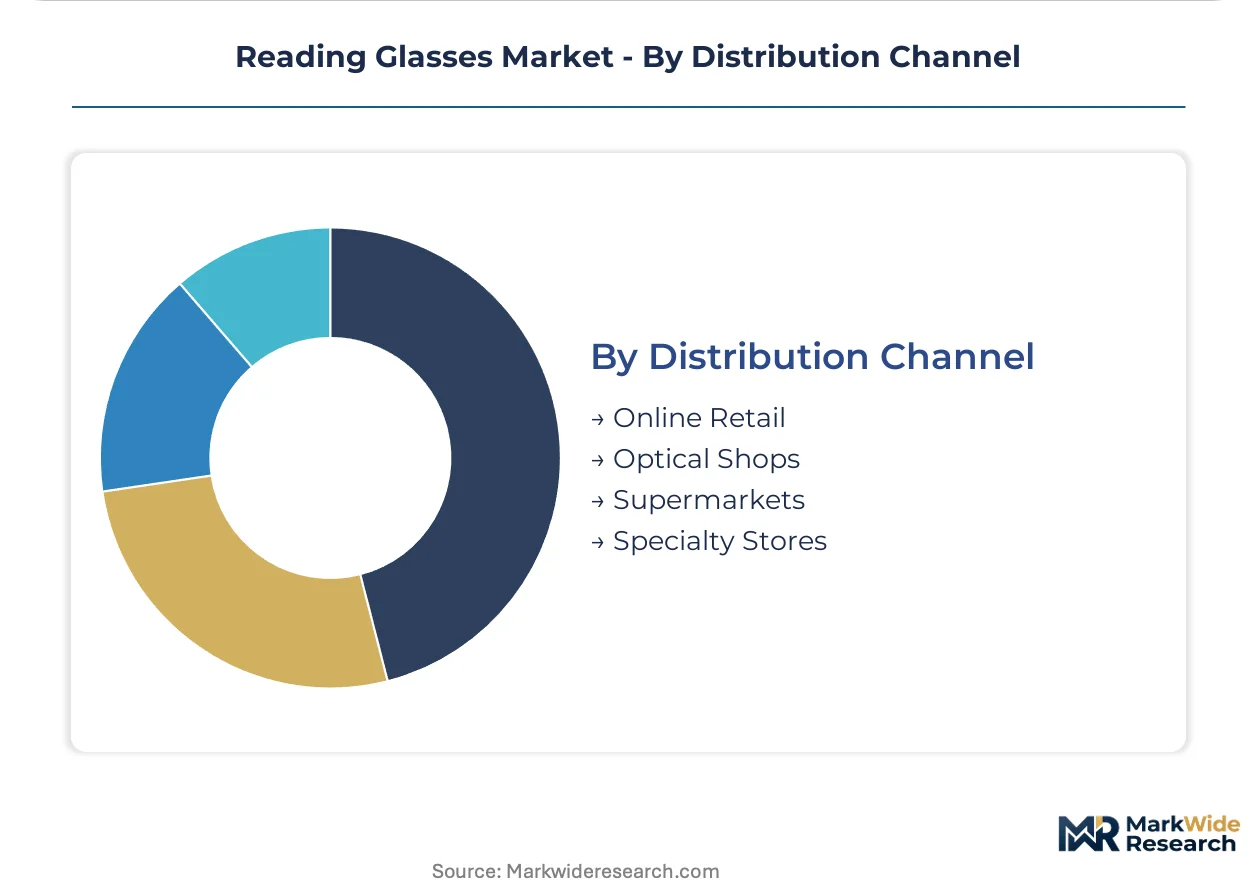
Distribution Channel:
Channel economics determine working capital intensity—inventory carrying costs vary dramatically between centralized e-commerce fulfillment and distributed retail footprints.
- Online Retail:Pure-play digital distribution strips optical shop overhead while enabling precision targeting through prescription data capture. Zenni Optical and direct-to-consumer competitors concentrate demand in the United States through automated reorder cycles tied to prescription expiration.
- Optical Shops:Clinical dispensing maintains service revenue through examination bundling despite product margin compression. Independent opticians in France and Italy unbundle fees transparently to retain customers.
- Supermarkets:Impulse placement of over-the-counter readers captures convenience-driven purchasing.
- Specialty Stores:Curated fashion positioning commands premium pricing through experiential retail.
Optical shops retain the largest installed service infrastructure; online retail is climbing the fastest as fulfillment automation improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors European eyewear manufacturing through vertically integrated acetate processing and precision metalworking clusters that supply frame components worldwide.
United States
Medicare reimbursement structures and employer-sponsored vision benefits drive channel fragmentation between clinical dispensing and direct-to-consumer platforms. FDA medical device classification governs corrective eyewear import documentation and labeling requirements. California's Silicon Valley corridor hosts digital health startups developing app-based vision testing technologies for remote prescription verification.
Germany
Precision optics engineering heritage sustains demand for high-index lens substrates and free-form surfacing equipment. REACH and RoHS frameworks restrict hazardous substances in frame coatings and metal alloys. The Munich-Stuttgart industrial corridor concentrates mid-market optical laboratories adopting five-axis digital generators for progressive lens production.
Japan
Hypoallergenic titanium frame preferences reflect aging demographic priorities for daily-wear durability. METI industrial standards govern optical performance specifications for corrective lenses. The Fukui prefecture maintains specialized machining capacity for premium metal eyewear components serving domestic and export markets.
Italy
Fashion-positioned frame design commands premium pricing through luxury retail channels and experiential flagship stores. EU Green Deal chemical sustainability mandates are forcing acetate reformulation away from phthalate plasticizers. The Cadore valley in Belluno province retains concentrated artisanal frame production expertise alongside automated injection-molding facilities.
India
Underserved presbyopic populations in tier-2 and tier-3 cities create distribution whitespace for affordable over-the-counter readers. BIS standards govern optical product quality and safety specifications for domestic market access. The Mumbai-Pune industrial corridor is developing injection-molding capacity for cellulose acetate frames targeting price-sensitive consumer segments.
Reading Glasses Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material sophistication and distribution channel control dimensions. The market exhibits tiered concentration with vertically integrated conglomerates commanding upstream acetate and metal alloy supply against pure-play digital distributors stripping optical retail overhead. Three archetypes dominate: integrated material-lens-frame manufacturers, direct-to-consumer platform operators, and specialized high-index lens technology developers. Competitive moves center on backward integration into raw material sourcing and fulfillment automation investments.
Within the integrated manufacturing tier, EssilorLuxottica and Hoya Corporation exemplify upstream control strategies over optical substrate and frame component supply chains. Among platform-native distributors, Warby Parker occupies a position bridging digital convenience with physical retail presence. Carl Zeiss represents the precision optics heritage archetype, anchoring high-performance lens specification standards across clinical and consumer channels.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Carl Zeiss |
| Bausch & Lomb Incorporated |
| Hoya Corporation |
| Safilo Group |
| Warby Parker |
| Zenni Optical |
| Johnson & Johnson Vision Care |
| De Rigo Vision |
| Others |
Supply Flow & Price Mechanics
Cellulose acetate pellet costs cascade from Italian and Chinese chemical suppliers through injection-molding facilities to frame manufacturers, with REACH-compliant reformulation adding 15-25% material premiums that concentrate in premium titanium and bio-based product tiers.
Pricing Analysis
Optical clarity outcomes anchor value-based pricing for progressive lens configurations, with free-form digital surfacing commanding premiums over standardized single-vision molding. Three-tier pricing structure across premium, standard, and economy levels separates titanium CNC-machined frames from injection-molded acetate and over-the-counter drugstore readers. Cost compression in economy tiers intensifies because pure-play digital distributors strip optical shop overhead and automate reorder cycles. Young adult professionals exhibit lowest price sensitivity through employer-sponsored vision benefits, while students and rural seniors in tier-2 Indian cities drive volume at marginal price points.
Supply Chain Analysis
Acetate pellet supply rests on Italian specialty chemical producers and Chinese petrochemical processors, with vacuum-deposited titanium feedstock concentrated in Japanese and German metallurgical facilities. Frame fabrication draws from cellulose acetate, stainless steel alloys, and castor-oil-derived bioplastics, while lens surfacing hinges on high-index monomer substrates and precision optical coatings. Single-source vulnerability in Italian acetate concentration exposes mid-market manufacturers to input cost volatility. Distribution runs through vertically integrated conglomerates controlling upstream material procurement, direct-to-consumer fulfillment platforms, and clinical dispensing networks with examination bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-form digital surfacing technology is displacing legacy manual fining and polishing equipment, compressing production lead times while requiring capital redeployment toward five-axis generator infrastructure.
For Market Incumbents: Acquire automated edging and surfacing equipment fleets to defend manufacturing scale against platform-native entrants stripping optical retail margins. EssilorLuxottica's captive acetate sourcing demonstrates how upstream control over cellulose pellet supply buffers REACH compliance cost shocks. Independent opticians counter channel migration by unbundling examination fees from product sales to retain service revenue. For New Entrants and Emerging Players: Launch via app-based vision testing paired with home try-on programs to penetrate young adult professional segments in the United States and United Kingdom. India's tier-2 and tier-3 cities present white-space distribution opportunity for affordable over-the-counter readers. Subscription replenishment models tied to prescription expiration cycles offer recurring revenue architecture absent from transactional retail. For Investors and Strategic Acquirers: FDA medical device classification timeline extensions for corrective eyewear imports are the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets. Long-term viability favors platform operators with fulfillment automation and manufacturers with backward integration into sustainable frame materials. Watch CE marking backlog duration under EU MDR transition as the signal for European market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Free-Form Digital Surfacing Deployment | Five-axis generators reduce laboratory headcount requirements while improving progressive lens surface accuracy tolerances. |
| REACH-Compliant Acetate Reformulation | Bioplastic and mineral-based colorant adoption positions frame manufacturers for EU Green Deal chemical sustainability mandates. |
| Direct-to-Consumer Platform Expansion | Automated reorder cycles tied to prescription data capture concentrate demand among employer-benefit-structured purchasers. |
| Blue-Light Filtering Coating Integration | Screen-time convergence with presbyopia correction opens premium tier targeting for office worker segments. |
| Clinical Dispensing Network Optimization | Medicare reimbursement structures in the United States redirect volume toward examination-bundled service revenue models. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of optical laboratory directors, frame manufacturing procurement leads, direct-to-consumer platform operations heads, independent optician practice owners, and vision benefits administrators at US employers. FDA 510(k) submissions, ECHA substance restriction updates, EU MDR certification databases, and Medicare reimbursement policy documents provided regulatory trajectory validation. Bottom-up unit volume modeling triangulated against top-down value estimates from channel-specific ASP analysis.
Shipment volume reconciliation against prescription verification data streams anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include frame material sophistication, lens type optical complexity, target audience lifecycle stage, and distribution channel working capital intensity. CAGRs derived from fitted growth curves applied to demographic-driven demand expansion and technology adoption S-curves. Free-form equipment replacement rates and REACH compliance cost pass-through assumptions shaped manufacturing capacity forecasts.
The model assumes a particular technology adoption path; alternative pathways for automated digital surfacing would alter the outlook if training pipeline shortages persist for precision optical technicians. Forecasts reflect assumptions on Medicare reimbursement stability and EU MDR certification timeline normalization. Supply concentration in Italian acetate and regulatory restriction evolution represent specific risk factors. A small set of named triggers—CE marking backlog duration, employer vision benefit policy shifts, and presbyopia demographic inflection points—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Smart Eyewear Market
Eyewear
Sunglasses Pouch Market
Eyewear
Wooden Eyewear Market
Eyewear
Middle East Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Plano Sunglasses Market
Eyewear
Anti-Fog Lens Market
Eyewear
North America Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
Smart Sunglasses Market
Eyewear
Eyeglass Market
Eyewear
Goggles Market