
 Cutlery Steel Market | 2026-2036
Cutlery Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Cutlery Steel Market Analytics
Specialty retail channels is narrowing as direct-to-consumer platforms capture premium cutlery transactions. Zwilling J.A. Henckels leverages its Solingen heritage to sustain brand authority in forged blade categories. Wüsthof anchors German craftsmanship positioning across North American specialty stores. Victorinox competes through multi-category penetration beyond kitchen knives into professional tools.
Cutlery steel denotes corrosion-resistant alloys formulated for blade and utensil fabrication, typically containing 12-18% chromium with carbon content calibrated between 0.3% and 1.2% to balance edge retention against stain resistance. These alloys undergo austenitizing, quenching, and tempering cycles to achieve Rockwell hardness values of 55-66 HRC for commercial cutting performance. Stainless steel dominates material grade selection due to established supply chains and food safety compliance, while carbon steel commands artisan and professional segments where edge sharpness outweighs maintenance demands. The residential application category absorbs volume through replacement cycles, whereas commercial and catering segments generate premium pricing through durability specifications and institutional procurement standards.
EU REACH restrictions on nickel and chromium migration constrain alloy formulations for European distribution, while FDA food-contact substance notifications govern import eligibility into the United States. BIS certification requirements in India add compliance layers for stainless steel flatware entering that market. Stakeholders must track evolving material restrictions and align R&D investments with regional certification thresholds before committing to capacity expansion.
Market Dynamics
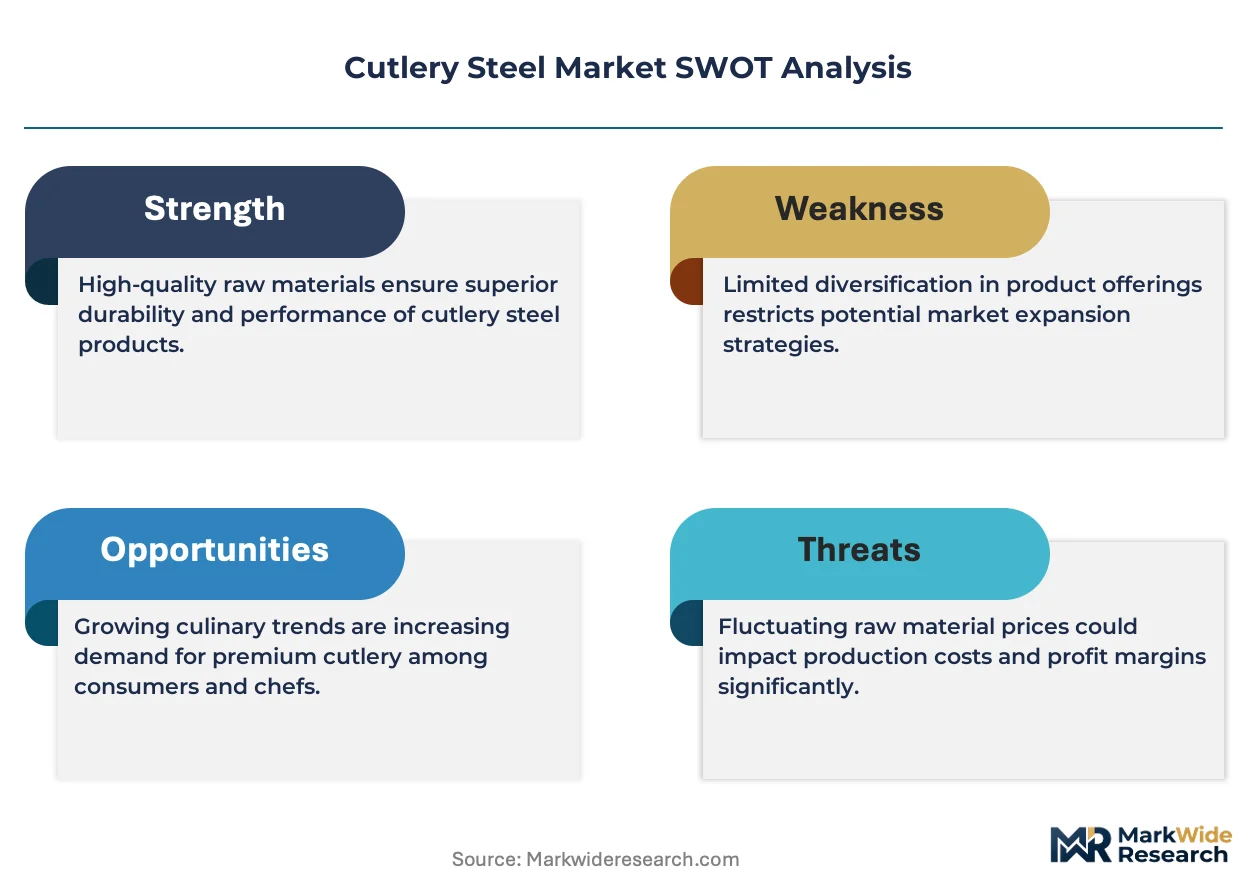
REACH compliance in Europe is collapsing legacy alloy formulations across the cutlery steel supply chain, forcing manufacturers to redesign chromium and nickel migration profiles before products enter European distribution channels.
Growth Catalysts
- Professional kitchen equipment replacement cycles:Hospitality sector procurement standards in Germany and France mandate Rockwell hardness thresholds above 58 HRC, pulling premium alloy volumes through institutional channels.
- ECHA substance restriction amendments:Updated REACH Annex XVII limits on nickel release rates below 0.5 μg/cm²/week are accelerating certified alloy development for food-contact applications.
- Powder metallurgy adoption:Crucible particle metallurgy processes enable vanadium carbide distributions that extend edge retention in high-frequency commercial cutting environments.
Market Restraints
- Scrap nickel price volatility:Stainless steel 300-series production depends on nickel inputs from Indonesian and Philippine laterite mines, exposing margins to LME price swings exceeding 40% annually.
- Supply concentration in Solingen:German blade-making clusters control 60% of European forged premium output, creating single-point vulnerability for specialized heat-treatment capacity.
- Carbon steel maintenance burden:Professional users in humid climates face accelerated oxidation rates that disqualify high-carbon blades from warranty-covered institutional procurement.
Strategic Opportunities
- Indian BIS certification expansion:Stainless steel flatware imports into India require IS 9873 compliance, creating first-mover advantage for alloy producers establishing local testing partnerships.
- Direct-to-consumer blade subscriptions:Sharpening-as-a-service models bypass traditional specialty retail markups while capturing lifetime customer value through recurring alloy replenishment.
- EU Green Deal circularity mandates:Ecodesign for Sustainable Products Regulations will require recycled content thresholds in steel products by 2030, rewarding early investment in electric arc furnace scrap sorting.
Industry Challenges
- Heat-treatment technician scarcity:Austenitizing and cryogenic quenching expertise concentrates among aging specialists in Solingen and Seki, Japan, constraining quality-controlled capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact notifications, REACH SVHC declarations, and BIS laboratory testing extend product launch cycles by 14-18 months.
- Legacy ERP integration with traceability systems:Batch-level alloy composition tracking required by EU Digital Product Passports demands middleware investment that mid-tier forges lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutlery Steel Market |
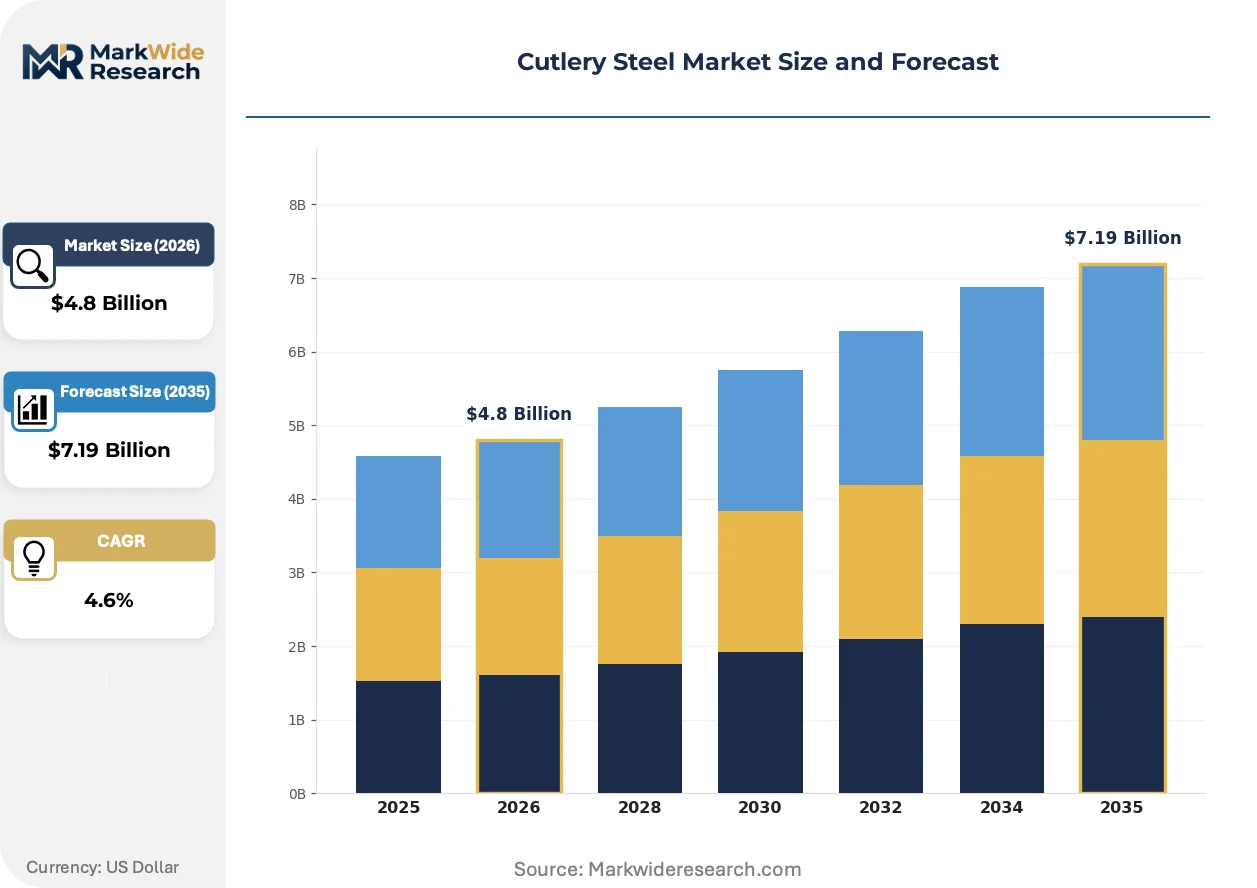
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knives, Forks, Spoons, Other Cutlery Material Grade: Stainless Steel, Carbon Steel, Alloy Steel, Tool Steel Finish Type: Polished, Matte, Coated, Textured Application: Residential, Commercial, Industrial, Catering |
| Companies Covered | Groupe SEB, Fissler, Zwilling J.A. Henckels, Cutco Corporation, Newell Brands, Wüsthof, WMF, Global Knives, Victorinox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutlery Steel Market Evolving Landscape
Powder metallurgy and additive manufacturing are collapsing traditional forging economics while regulatory digitization and procurement centralization reshape how buyers evaluate blade performance credentials.
Powder metallurgy production using gas atomization and hot isostatic pressing is collapsing cost differentials between conventionally forged and particle metallurgy blades. Commercial kitchens in Nordic countries now specify CPM S30V and equivalent grades for volume procurement, compressing the premium tier into mid-market pricing bands. This technology is collapsing the historical three-tier market structure by enabling superior edge retention at forged-blade cost points.
ECHA's 2023 restriction proposal on chromium trioxide in surface treatments is forcing conversion to trivalent chromium passivation and plasma electrolytic oxidation alternatives. German manufacturers face the steepest compliance curves as Solingen's heritage finishing houses retool electropolishing lines. Small-batch artisan producers in Thiers, France, are responding fastest through collaborative testing consortia that spread certification costs across regional competitors.
Centralized procurement through hospitality group purchasing organizations is displacing independent chef purchasing authority in North American and Western European foodservice. Multi-unit restaurant chains now mandate Rockwell certification documentation and alloy traceability through digital supplier portals. This consolidation is most visible in the United States, where contract foodservice management companies like Compass and Sodexo have standardized blade specifications across thousands of institutional kitchens.
Cutlery Steel Market Segmentation
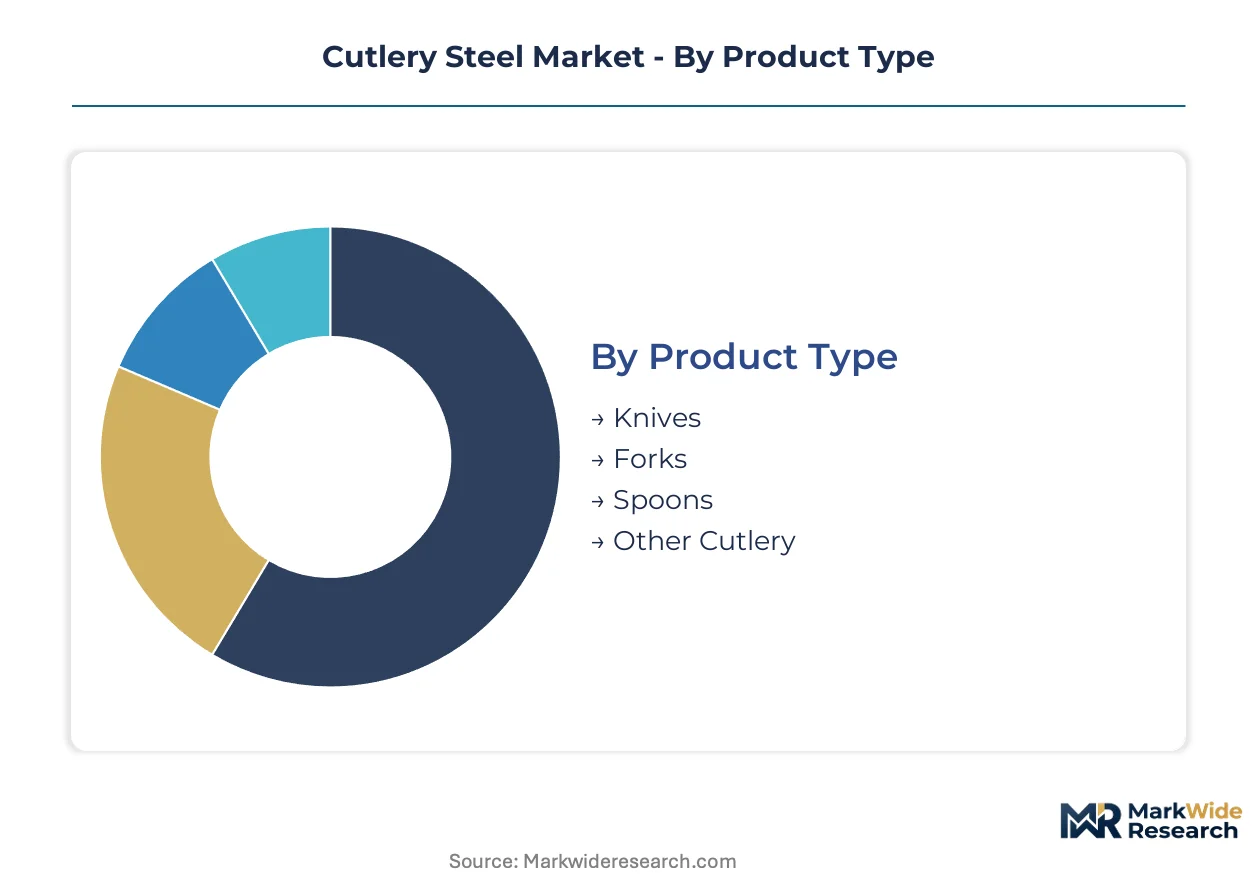
Cutlery steel segmentation reveals how alloy specifications, surface engineering, and procurement standards fragment demand across price tiers and regulatory jurisdictions. Each dimension carries distinct compliance burdens and performance thresholds that reshape supplier positioning.
Product Type:
Blade geometry and stress concentration factors determine alloy selection across utensil categories.
- Knives:Rockwell hardness requirements of 55-66 HRC govern martensitic stainless formulations. German commercial kitchens in Frankfurt and Hamburg specify forged blades with vanadium carbide distributions for institutional procurement.
- Forks:Tine deflection resistance drives austenitic 300-series adoption where corrosion tolerance outweighs edge retention. French hospitality groups in Lyon and Paris mandate 18/10 chromium-nickel ratios for front-of-house service durability.
- Spoons:Deep-drawing formability favors lower-carbon austenitic grades with nickel content below 10% to control material costs in high-volume flatware production.
- Other Cutlery:Serving utensils and specialty tools incorporate duplex stainless structures where mechanical loading varies unpredictably across use cycles.
Established volume favors knives; emerging adoption favors other cutlery as serving-piece customization expands.
Material Grade:
Cost tiers separate maintenance-intensive performance alloys from commodity stainless with standardized corrosion resistance.
- Stainless Steel:Austenitic 304 and 316 grades dominate food-contact applications through established supply chains and REACH-compliant migration profiles. Indian BIS certification requirements now constrain nickel release rates for imported flatware entering Mumbai and Delhi distribution channels.
- Carbon Steel:High-carbon formulations above 0.8% carbon content deliver superior edge sharpness for artisan and professional segments. Japanese blade-making clusters in Seki and Sakai maintain heat-treatment expertise that justifies premium positioning despite oxidation maintenance burdens.
- Alloy Steel:Molybdenum and vanadium additions enhance wear resistance in institutional cutting environments where blade replacement cycles extend beyond residential norms.
- Tool Steel:Powder metallurgy grades including CPM S30V penetrate commercial kitchen specifications as Nordic procurement groups consolidate supplier qualification around particle metallurgy performance credentials.
Commodity procurement concentrates in stainless steel; performance differentiation favors tool steel as hardness certification becomes mandatory.
Finish Type:
Surface engineering determines both aesthetic positioning and regulatory compliance for food-contact migration.
- Polished:Electropolishing removes surface irregularities that trap food particles, satisfying FDA food-contact substance notifications for US import eligibility. German manufacturers face ECHA pressure to convert chromium trioxide passivation lines to trivalent alternatives.
- Matte:Bead-blasted surfaces mask scratching in high-frequency commercial use while reducing visible fingerprint retention for front-of-house presentation standards.
- Coated:Ceramic and diamond-like carbon coatings extend edge retention in specialized cutting applications where base alloy properties prove insufficient.
- Textured:Hammered and patterned finishes differentiate premium positioning in direct-to-consumer channels where visual craftsmanship signals quality.
Functional specifications favor polished finishes; aesthetic differentiation favors textured surfaces in subscription and specialty retail.
Application:
Customer type dictates certification depth, batch traceability, and procurement centralization intensity.
- Residential:Replacement cycles drive volume through retail and e-commerce channels with minimal documentation requirements. German consumers in Bavaria and Baden-Württemberg sustain demand for Solingen-heritage forged sets.
- Commercial:Hospitality group purchasing organizations in the United States now mandate Rockwell certification and alloy traceability through digital supplier portals. Compass and Sodexo specifications cascade through thousands of institutional kitchens.
- Industrial:Food processing equipment blades face USDA compliance for meat-contact surfaces with stringent sanitation protocols and disassembly requirements.
- Catering:Rental and event-service operators prioritize dent resistance and stackability over edge performance, favoring lower-cost austenitic grades with work-hardening formability.
Procurement standardization concentrates in commercial; margin expansion favors industrial as equipment-integrated blade demand climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's steel handling infrastructure anchors European alloy distribution for blade manufacturing clusters. Germany's Solingen heritage forges and Seki's heat-treatment specialists in Japan depend on this logistics backbone for raw material throughput.
United States
FDA food-contact substance notifications govern import eligibility for flatware entering through New York and Los Angeles ports. Compass and Sodexo procurement standardization cascades blade specifications across thousands of institutional kitchens. Chicago's foodservice equipment distributors consolidate purchasing authority previously held by independent chefs.
Germany
REACH Annex XVII nickel release limits below 0.5 μg/cm²/week force alloy reformulation for Solingen's heritage blade houses. ECHA substance restriction amendments accelerate certified alloy development timelines. Frankfurt and Hamburg hospitality procurement mandates Rockwell hardness thresholds above 58 HRC for institutional contracts.
Japan
METI industrial standards certification maintains quality thresholds for Seki and Sakai blade-making clusters. Aging heat-treatment technician scarcity constrains capacity expansion despite commercial kitchen demand. Osaka-based procurement groups specify powder metallurgy grades for high-frequency cutting environments.
India
BIS IS 9873 certification requirements for stainless steel flatware create compliance barriers at Mumbai and Delhi entry points. Central government PLI scheme incentives target domestic alloy production scale-up. Tamil Nadu and Gujarat manufacturing zones attract testing laboratory partnerships for first-mover certification advantage.
France
ANSM food-contact material regulations align with EU REACH migration limits for Thiers artisan blade producers. Collaborative testing consortia spread certification costs across regional competitors facing ECHA chromium trioxide restrictions. Lyon hospitality groups mandate 18/10 chromium-nickel ratios for front-of-house service durability.
Cutlery Steel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in alloy formulation and heat-treatment capacity. The vendor base clusters around heritage manufacturing geography rather than scale economics. Three archetypes dominate: Solingen-heritage forged blade houses, Seki-based precision metallurgy specialists, and multi-category tool manufacturers leveraging brand equity across kitchen and professional segments. Competitive moves concentrate on direct-to-consumer channel bypass and powder metallurgy process licensing.
Among German heritage houses, Zwilling J.A. Henckels and Wüsthof occupy positions anchored in Solingen craftsmanship credentials. Victorinox exemplifies the multi-category penetration archetype, extending brand presence beyond kitchen knives into professional tool segments. These three represent distinct competitive vectors: geographic heritage authentication, hardness certification standardization, and category-spanning brand leverage.
| Leading Market Players |
|---|
| Groupe SEB |
| Fissler |
| Zwilling J.A. Henckels |
| Cutco Corporation |
| Newell Brands |
| Wüsthof |
| WMF |
| Global Knives |
| Victorinox |
| Others |
Value Network & Pricing Analysis
Nickel laterite mining concentration in Indonesia and the Philippines directly determines margin distribution across stainless steel 300-series production tiers. Solingen's heat-treatment capacity scarcity feeds premium pricing power into forged blade categories while commodity flatware faces cost compression from scrap volatility.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from direct-to-consumer subscription models. Three-tier pricing stratifies across Rockwell-certified premium grades, mid-market austenitic stainless, and economy flatware with reduced nickel content. Cost compression in standard grades intensifies because Indonesian nickel export policies create input instability. Hospitality group purchasing organizations exhibit highest price sensitivity through centralized tender processes, while artisan segments accept premium markups for heritage authentication.
Supply Chain Analysis
Upstream feedstock flows from Indonesian and Philippine laterite mines through Chinese stainless steel mills before reaching German forging clusters. Chromium and molybdenum additions draw from South African and Kazakh mining operations. Single-source vulnerability concentrates in Solingen's specialized heat-treatment capacity where aging technician scarcity constrains expansion. Distribution runs through Rotterdam's steel handling infrastructure into blade-making clusters across Germany, Japan, and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sharpening-as-a-service subscriptions expand faster than hardware replacement cycles, converting transactional blade sales into recurring revenue streams with superior lifetime value capture.
For Market Incumbents: Pre-empt powder metallurgy cost convergence by locking exclusive licensing agreements with Crucible Industries before particle metallurgy grades commoditize forged-blade premiums. Defend Solingen heritage positioning through batch-level Digital Product Passport compliance ahead of EU Green Deal circularity mandates. Backward integration into scrap sorting capabilities secures recycled content thresholds required by Ecodesign for Sustainable Products Regulations. For New Entrants and Emerging Players: Indian BIS certification partnerships in Tamil Nadu and Gujarat manufacturing zones represent the most penetrable entry point before domestic alloy production scales under central government PLI scheme incentives. Direct-to-consumer blade subscriptions bypass specialty retail markups while capturing institutional customers through sharpening-as-a-service bundling. Collaborative testing consortia modeled on Thiers artisan networks spread REACH SVHC declaration costs across regional competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German heritage houses facing ECHA chromium trioxide conversion costs and ERP integration burdens for traceability systems. Five-to-ten year viability favors targets with established powder metallurgy process licensing and digital supplier portal certification documentation. Monitor Nordic procurement group consolidation around CPM-grade specifications as inflection indicator for particle metallurgy market penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Powder Metallurgy Process Licensing | Crucible particle metallurgy adoption collapses cost differentials between forged and premium grades. |
| Digital Product Passport Compliance | EU Green Deal circularity mandates require batch-level alloy composition tracking by 2030. |
| Direct-to-Consumer Subscription Launch | Sharpening-as-a-service models capture lifetime customer value through recurring alloy replenishment. |
| BIS Certification Partnership Expansion | Indian IS 9873 compliance creates first-mover advantage for imported flatware entering Mumbai distribution. |
| Trivalent Chromium Passivation Conversion | ECHA restriction proposals force Solingen finishing houses to retool electropolishing lines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed manufacturers, ECHA substance restriction databases, and hospitality procurement portal specifications. Blade-making executives, heat-treatment specialists, group purchasing organization contract managers, and flatware import compliance officers provided qualitative input. Bottom-up alloy consumption estimates triangulate against top-down market value reconstruction across material grade segments.
Forecast inputs include professional kitchen equipment replacement cycles, REACH Annex XVII amendment timelines, powder metallurgy adoption curves in Nordic procurement specifications, and BIS certification expansion rates. Segmentation dimensions span product type, material grade, finish type, and application with regional regulatory cluster overlays. CAGRs derive from regression analysis of historical stainless steel price elasticity and institutional procurement volume trends.
Stress conditions across nickel LME price volatility bands, Solingen capacity utilization thresholds, and ECHA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospitality sector capital expenditure stability and alloy substitution elasticity. Cross-checking against German mechanical engineering association production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Knife Set Market
Household Items
Flatware Market
Household Items
Wipes Market
Household Items
Heated Towel Rail Market
Household Items
Lunch Box Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Enameled Cookware Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Permanent Marker Market
Household Items
Soap Tablet Market
Household Items
Global Ceramic Tableware Market
Household Items
Mexico Cookware Market
Household Items
MENA POU Water Purifiers Market
Household Items
Electric Shoe Dryer Market
Household Items
Europe Handheld Fans Market
Household Items
Coffin and Cremation Urn Market