
 Electric Countertop Griddles Market | 2026-2036
Electric Countertop Griddles Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Countertop Griddles Market Foresight
The ENERGY STAR program for commercial foodservice equipment is hardening efficiency requirements for electric countertop griddles, compelling manufacturers to redesign heating elements and insulation systems. Vulcan leverages its institutional kitchen heritage to dominate the heavy-duty segment with durable stainless steel construction. Hamilton Beach competes aggressively in the residential and light-commercial tier through broad retail distribution and aggressive price positioning. Equipex anchors the premium European-style niche with compact, high-wattage models engineered for front-of-house display cooking.
An electric countertop griddle is a self-contained, plug-in cooking appliance featuring a flat, thermostatically controlled metal plate—typically cast iron, stainless steel, or ceramic-coated aluminum—heated by embedded electric elements to temperatures between 150°F and 450°F for searing, grilling, and batch cooking proteins, vegetables, and breakfast items. The product type segment shows stainless steel and cast iron configurations commanding the commercial margin pool due to thermal mass retention and durability under cyclic loading, while non-stick coatings sustain growth in residential settings where ease of cleaning drives repeat purchase. Capacity segmentation reveals 3-4 burner and multi-zone units leading restaurant adoption as operators seek flexible surface zoning for simultaneous temperature control across proteins and delicate items.
The EPA's ENERGY STAR program and the DOE's appliance efficiency standards govern minimum thermal efficiency and standby energy consumption for electric griddles sold in the United States, while NSF International certification mandates sanitation-safe materials and cleanability for commercial kitchen deployment. The FDA's Food Code provisions indirectly shape griddle surface material requirements through food-contact safety protocols that manufacturers must embed in coating chemistry and seam welding. Stakeholders must monitor evolving federal efficiency rulemakings and state-level electrification mandates in commercial building codes to anticipate product redesign cycles and qualification barriers.
Market Dynamics
Commercial kitchen electrification mandates and mobile foodservice expansion are compressing equipment replacement cycles while tightening thermal efficiency requirements across procurement specifications.
Growth Catalysts
- ENERGY STAR Certification:The EPA's tightening efficiency benchmarks for commercial foodservice equipment are compelling food truck operators and catering services to upgrade to certified electric griddles.
- Mobile Foodservice Proliferation:Texas, California, and Florida are witnessing concentrated expansion of food trucks and pop-up kitchens requiring compact, plug-in cooking solutions.
- Cast Iron Thermal Mass:Heavy-duty stainless steel and cast iron configurations with superior heat retention are capturing commercial margin pools through durability under cyclic loading.
Market Restraints
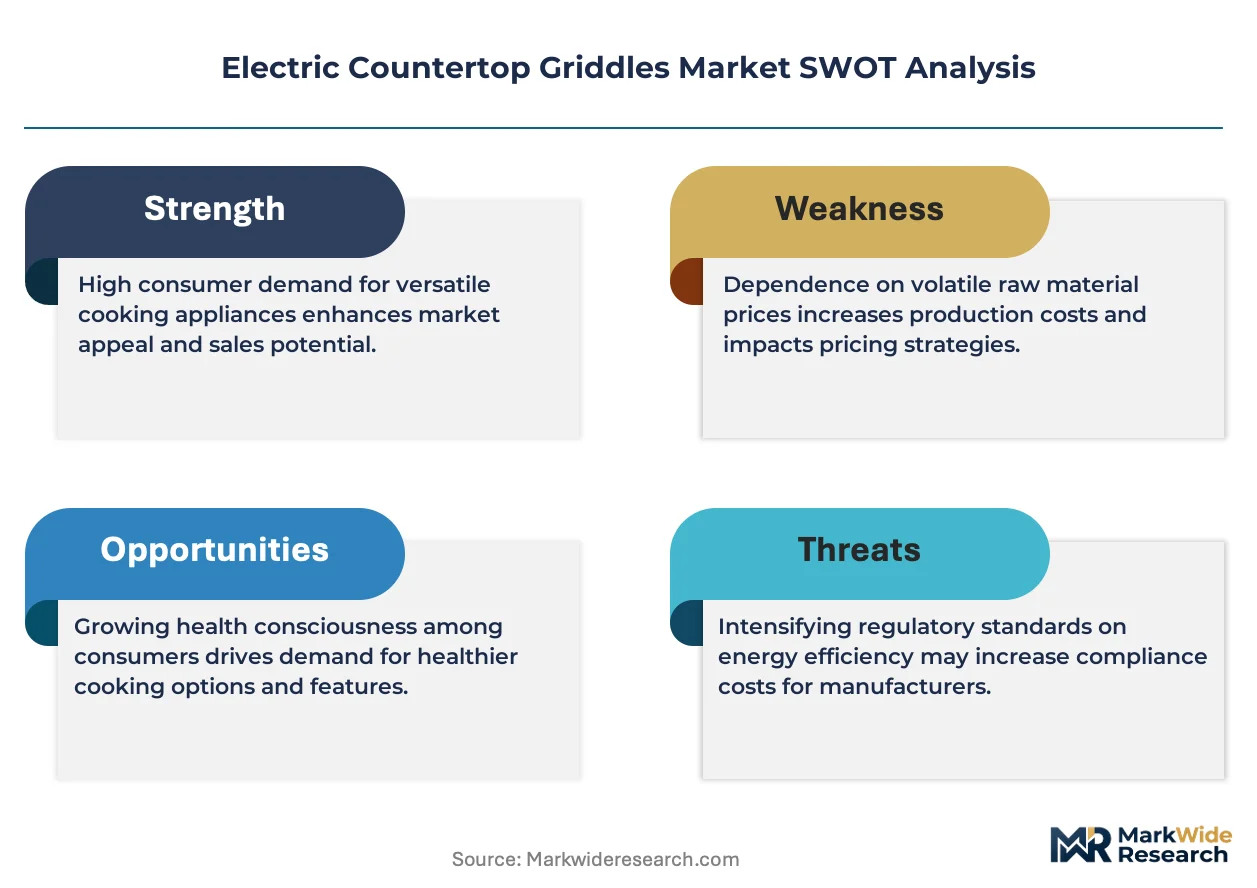
- Aluminum and Steel Input Volatility:Raw material price swings for cast iron plates and stainless steel housings compress manufacturer margins and destabilize distributor pricing.
- Electrification Infrastructure Gaps:Legacy commercial buildings in older urban cores lack adequate electrical capacity for high-wattage countertop equipment without costly panel upgrades.
- Gas Equipment Substitution:Propane-powered griddles retain cost advantages in off-grid locations and jurisdictions without carbon pricing mechanisms.
Strategic Opportunities
- Multi-Zone Temperature Control:3-4 burner units with independent surface zoning enable simultaneous protein searing and delicate item preparation, opening premium restaurant segments.
- Front-of-House Display Cooking:Compact European-style high-wattage models engineered for visible customer-facing installations are penetrating hotel breakfast bars and open-kitchen concepts.
- State Electrification Mandates:California's Title 24 building energy efficiency standards and similar codes in New York and Washington are accelerating replacement demand for gas-to-electric conversions.
Industry Challenges
- NSF Certification Timelines:Sanitation-safe material validation and cleanability testing for commercial kitchen deployment create 6-12 month product launch delays.
- Coating Chemistry Compliance:FDA Food Code food-contact safety protocols require reformulation of non-stick surface treatments, forcing R&D redirection.
- Embedded Element Integration:Heating element redesign for efficiency compliance demands coordination with insulation system suppliers, complicating supply chain synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Countertop Griddles Market |
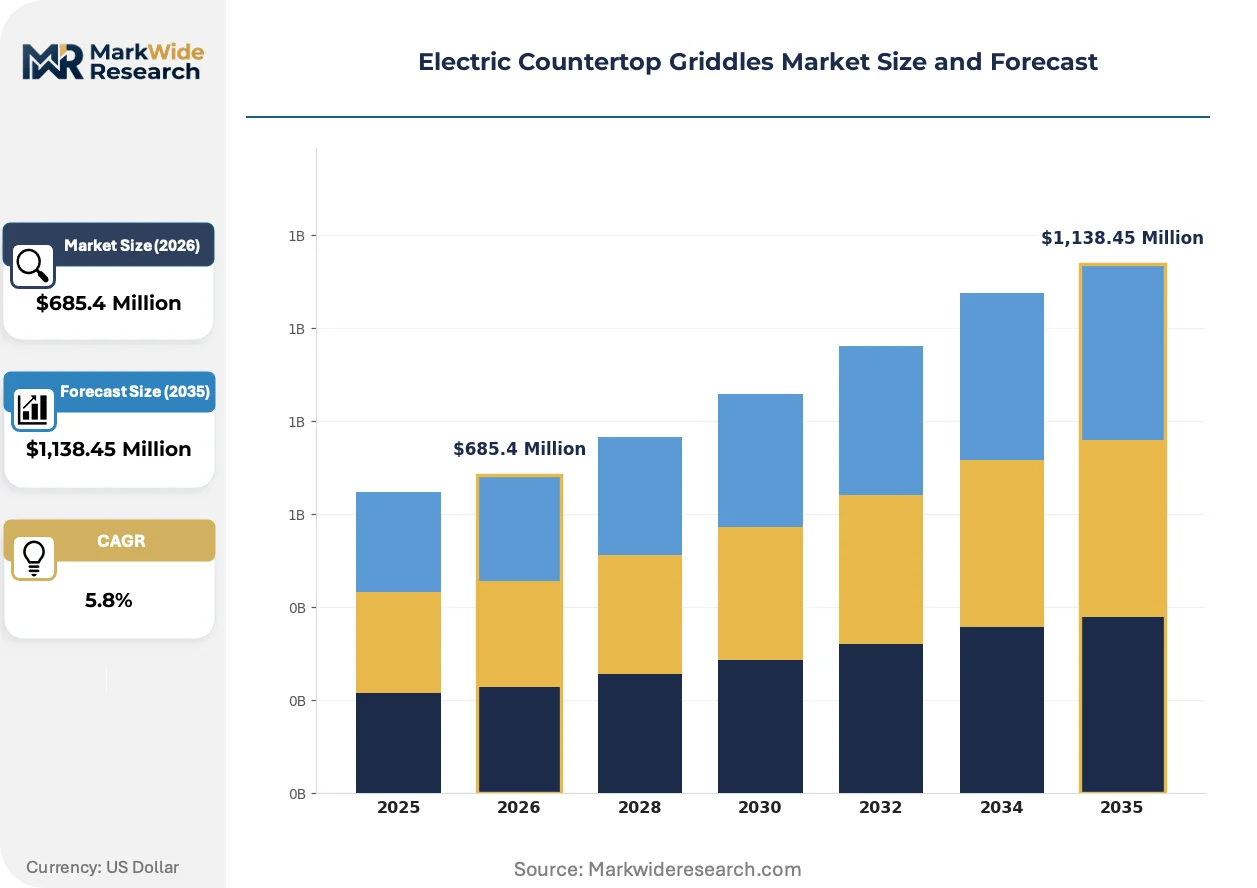
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Stick, Stainless Steel, Cast Iron, Ceramic End User: Residential, Restaurants, Catering Services, Food Trucks Capacity: 1-2 Burner, 3-4 Burner, 5-6 Burner, Multi-Zone Technology: Infrared, Induction, Conventional Heating, Electric |
| Companies Covered | Hamilton Beach, Black+Decker, Philips, Vulcan, Presto, Waring, Equipex, Garland, Ninja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Countertop Griddles Market Shifts & Advancements
Intelligent thermal management systems and modular cooking platforms are reconfiguring how commercial operators deploy countertop equipment across constrained kitchen footprints.
Precision temperature control technology using embedded sensors and microprocessor-driven feedback loops is automating heat recovery and reducing energy waste during idle periods. QSR chains and institutional cafeterias in high-turnover environments are adopting these systems to maintain consistent surface temperatures across batch cooking cycles. The technology is automating operator decision-making around preheat timing and load balancing, compressing training requirements for transient kitchen staff.
The EPA's ENERGY STAR Version 3.0 specifications for commercial griddles are mandating minimum cooking energy efficiency and maximum idle energy rates. Manufacturers must redesign heating element geometry and insulation packages to qualify for federal procurement preference programs. Heavy-duty stainless steel configurations targeting institutional kitchens face the steepest compliance costs, while compact residential-tier models gain relative advantage through simpler thermal envelopes.
Equipment-as-a-service financing models are displacing capital purchase arrangements among independent restaurant operators and emerging food truck entrepreneurs. Distributors and manufacturer captive finance arms are bundling maintenance, warranty extension, and upgrade rights into monthly payment structures. This shift is most visible in Texas and Florida mobile foodservice clusters where operators prioritize cash flow preservation over asset ownership.
Electric Countertop Griddles Market Segmentation
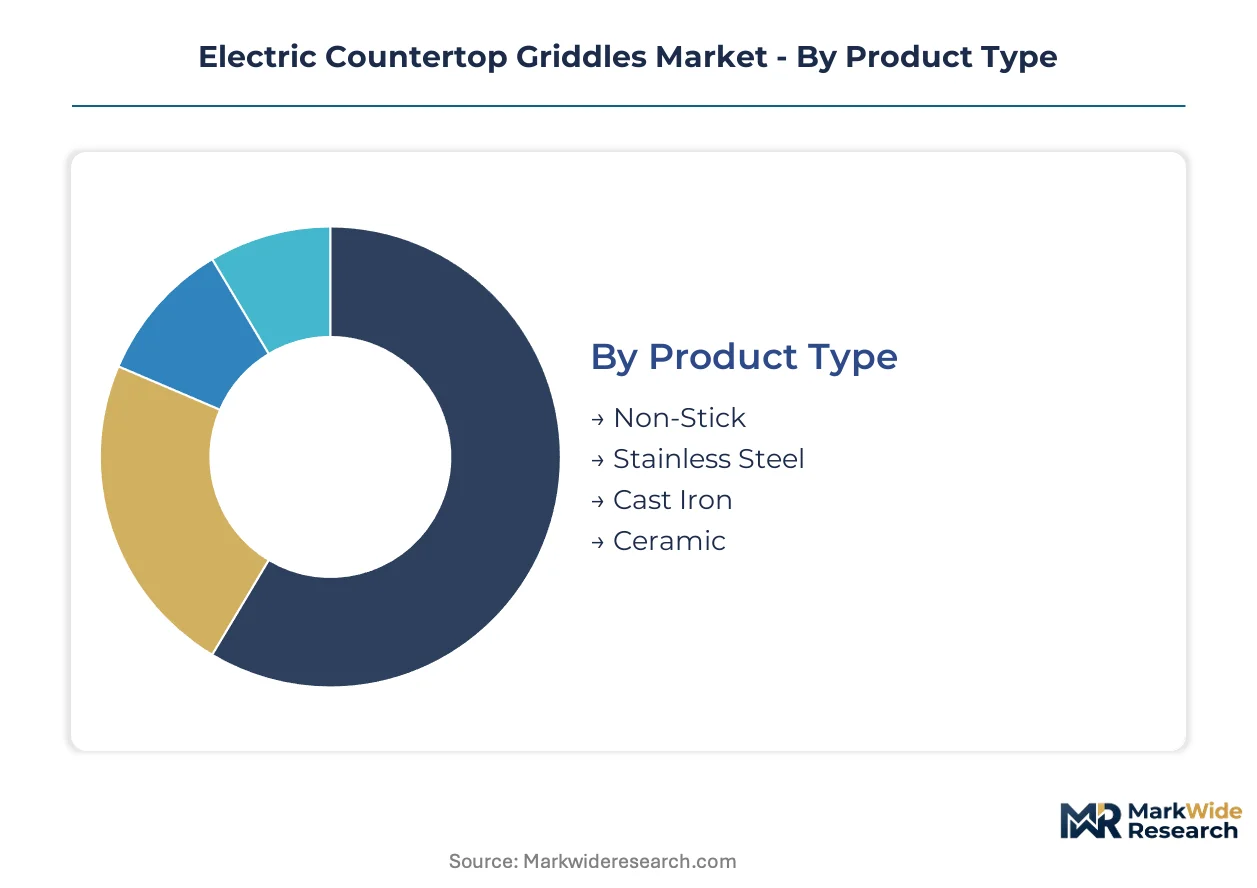
Electric countertop griddles fragment across material composition, thermal technology, and operational scale. Procurement patterns diverge sharply between residential convenience buyers and commercial operators facing NSF certification requirements and ENERGY STAR compliance deadlines.
Product Type:
Standalone surface materials dominate residential replacement cycles while embedded coating systems integrate into commercial kitchen buildouts.
- Stainless Steel:Heavy-gauge 304 and 430-grade plates withstand cyclic thermal loading in institutional cafeterias and QSR chains. Texas and Florida food truck clusters specify brushed finishes for corrosion resistance in humid coastal operations.
- Cast Iron:Dense ferrous plates retain thermal mass across batch cooking cycles, commanding premium positioning in steakhouse and diner segments. The material's porosity demands seasoned surfaces, limiting adoption to trained kitchen staff environments.
- Non-Stick:Ceramic-reinforced PTFE coatings reduce oil consumption and cleaning labor for residential users and front-of-house display installations.
- Ceramic:Sol-gel derived surfaces offer PTFE-free alternatives for health-conscious residential buyers and organic-certified commercial operations.
Stainless steel leads volumes today; ceramic coatings are gaining share fastest.
End User:
Cost tiers separate capital-rich institutional buyers from cash-constrained mobile operators financing through equipment-as-a-service arrangements.
- Restaurants:Full-service and fast-casual operators specify 3-4 burner units with independent zone control for simultaneous protein and vegetable preparation. California's Title 24 electrification mandates accelerate gas-to-electric conversion timelines for legacy kitchen infrastructure.
- Food Trucks:Compact 1-2 burner plug-in units dominate mobile foodservice procurement in Texas, California, and Florida where generator capacity constraints limit wattage draw. Operators prioritize NSF-certified models for health department inspection compliance.
- Catering Services:Event-based operators demand rapid heat recovery and transportable footprints for off-premise banquet execution.
- Residential:Countertop convenience buyers drive volume through retail channels, favoring non-stick surfaces and sub-1500W circuits for standard kitchen outlets.
Restaurant procurement anchors revenue concentration; food truck adoption is climbing the fastest.
Capacity:
Application intensity determines burner count, with throughput requirements scaling from breakfast batch cooking to continuous protein searing operations.
- 3-4 Burner:Mid-scale units with dual-zone thermostats enable simultaneous 350°F protein searing and 200°F holding temperatures. Independent restaurants and hotel breakfast bars in Florida and California specify this configuration for menu flexibility without full kitchen line investment.
- Multi-Zone:Microprocessor-controlled surface segmentation automates temperature gradients for complex menu execution in open-kitchen concepts and front-of-house display cooking environments.
- 1-2 Burner:Compact footprints serve residential kitchens, food trucks, and auxiliary prep stations where space constraints override throughput requirements.
- 5-6 Burner:Institutional-scale units target university cafeterias, hospital foodservice, and centralized commissary operations with continuous production schedules.
3-4 burner configurations dominate current installation bases; multi-zone systems show the steepest expansion trajectory.
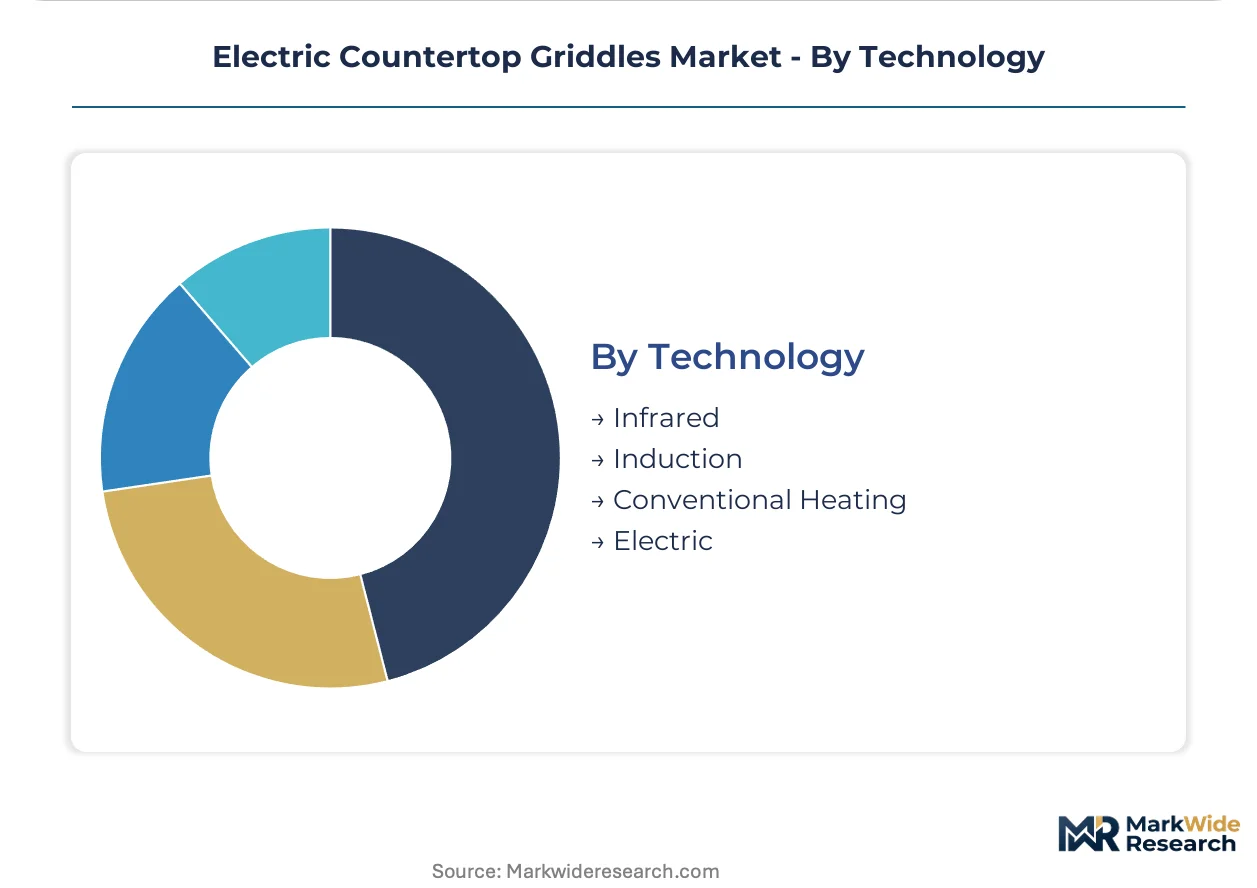
Technology:
Thermal delivery mechanisms differentiate on efficiency compliance, with EPA ENERGY STAR Version 3.0 specifications forcing heating element redesign cycles.
- Conventional Heating:Calrod-style embedded elements with bimetallic thermostats remain the installed base majority across institutional kitchens. The technology faces the steepest efficiency compliance costs under tightening federal procurement standards.
- Induction:Electromagnetic coil systems deliver 90%+ thermal efficiency with instantaneous response, penetrating premium commercial segments and residential markets where electrical infrastructure supports high-amperage circuits.
- Infrared:Quartz and ceramic radiant elements reduce preheat intervals for high-turnover breakfast operations and catering applications.
- Electric:Generic resistive heating category captures legacy equipment and price-sensitive residential tier without advanced control systems.
Conventional heating retains volume leadership; induction technology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric countertop griddle industry traces its commercial origins to American diner culture and post-war institutional foodservice expansion, with early manufacturing concentrated in the industrial Midwest before diversifying across coastal innovation corridors.
United States
Texas, California, and Florida food truck clusters drive concentrated procurement of compact plug-in units for mobile operations. The EPA's ENERGY STAR Version 3.0 specifications tighten federal efficiency benchmarks for commercial foodservice equipment. Houston and Miami metropolitan areas witness accelerated gas-to-electric kitchen conversions under state electrification mandates.
Germany
Precision engineering traditions support premium European-style griddle manufacturing for front-of-house display cooking applications. The EU Green Deal and national efficiency regulations accelerate demand for induction-compatible countertop equipment. Bavarian industrial zones host specialized stainless steel fabrication for institutional kitchen exports.
China
Domestic foodservice electrification and export manufacturing capacity expand simultaneously across coastal manufacturing belts. The country's national quality standards and energy efficiency labeling programs tighten product certification requirements. Yangtze River Delta production clusters supply global OEM demand for resistive heating element assemblies.
Japan
Compact kitchen footprints in urban residential towers sustain demand for sub-1500W countertop appliances. METI appliance efficiency standards and JIS certification protocols govern thermal performance benchmarks. Osaka-Kansai manufacturing corridors specialize in ceramic-coated surface treatments for premium export tiers.
United Kingdom
Hotel breakfast bar renovations and pub kitchen modernizations drive replacement cycles for multi-zone temperature control units. The country's building energy efficiency regulations and commercial kitchen safety standards shape procurement specifications. London metropolitan foodservice operators prioritize NSF-certified models for health inspection compliance.
Electric Countertop Griddles Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates into durable equipment fabricators with captive foundry capacity and assembly specialists sourcing thermal components from distributed supplier networks. Three archetypes dominate: institutional-grade stainless steel specialists, retail-channel residential brands, and compact European-style premium engineers. Competitive moves center on heating element geometry redesign for efficiency compliance and equipment-as-a-service financing bundling.
Among North American heritage manufacturers, Vulcan occupies a position within the heavy-duty institutional tier, Hamilton Beach exemplifies broad retail distribution scale, and Equipex anchors the compact premium European-style niche for front-of-house applications. These three represent divergent strategic postures on thermal mass retention, price positioning, and channel specialization without direct portfolio overlap.
| Leading Market Players |
|---|
| Hamilton Beach |
| Black+Decker |
| Philips |
| Vulcan |
| Presto |
| Waring |
| Equipex |
| Garland |
| Ninja |
| Others |
Supply & Pricing Matrix
Induction heating technology adoption is simultaneously compressing manufacturing cost curves and redistributing supplier power toward electromagnetic coil specialists in Germany and Japan. This transition forces legacy resistive-heating assemblers to absorb margin erosion while premium-tier producers capture pricing power through efficiency certification bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial units from residential retail models and unbranded import tiers. Price differentiation hinges on ENERGY STAR Version 3.0 qualification status and captive foundry capacity for cast iron plate production. Pricing pressure stems from aluminum and steel input volatility compressing manufacturer margins. Food truck operators in Texas and Florida exhibit highest price sensitivity due to equipment-as-a-service financing constraints, while institutional cafeteria buyers prioritize total cost of ownership over upfront expenditure.
Supply Chain Analysis
Domestic-content mandates under California's Title 24 and New York's electrification codes are reshaping sourcing patterns toward North American stainless steel fabrication. Supply concentrates in China for resistive heating element assemblies, Germany for precision induction coils, and the United States for heavy-gauge institutional housings. Raw material dependencies encompass 304-grade stainless steel, cast iron feedstock, and ceramic-coated aluminum substrates. Tariff exposure on Chinese electrical components constitutes the primary structural risk. Distribution runs through foodservice equipment distributors with captive finance arms bundling maintenance and warranty extensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric countertop griddles market reads as a late-cycle quality story, with procurement specifications hardening around EPA ENERGY STAR certification and NSF sanitation validation. Demand is concentrating toward premium multi-zone configurations with embedded sensor systems.
For Market Incumbents: Cement institutional kitchen relationships through captive foundry investments in cast iron thermal mass production. Deepen vertical integration into heating element geometry design to compress ENERGY STAR compliance costs. Defend against induction technology substitution by accelerating conventional system efficiency gains.
For New Entrants and Emerging Players: Foodservice equipment distributors with equipment-as-a-service financing capabilities offer the most penetrable channel wedge. Target Texas and Florida food truck clusters with compact 1-2 burner NSF-certified units. Pursue white-label partnerships with European-style front-of-house display cooking specialists.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier stainless steel fabricators lacking induction technology portfolios. Long-term viability favors producers with dual conventional-induction platform capabilities and captive North American manufacturing. Watch EPA rulemaking timelines for ENERGY STAR Version 4.0 specifications as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Heating Element Redesign | EPA ENERGY STAR Version 3.0 compliance secures federal procurement preference access. |
| Equipment-as-a-Service Launch | Monthly payment bundling penetrates Texas and Florida food truck financing constraints. |
| Multi-Zone Temperature Control | Independent surface zoning opens premium restaurant and hotel breakfast bar segments. |
| NSF Certification Investment | Sanitation-safe material validation unlocks commercial kitchen deployment channels. |
| Front-of-House Display Engineering | Compact European-style models penetrate open-kitchen and visible cooking installations. |
Research Methodology
Multiple input streams — primary interviews with foodservice equipment distributors, commercial kitchen operators, and NSF certification specialists, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Secondary sources encompassed EPA ENERGY STAR product databases, NSF International certification registries, and foodservice equipment customs records. Primary fieldwork captured procurement specification evolution across Texas, California, and Florida mobile foodservice clusters.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions encompassed surface material composition, end-user operational scale, burner count capacity, and thermal delivery technology. CAGRs were derived from installed base replacement cycle analysis and electrification mandate penetration curves. Industry-specific forecast inputs included state-level commercial building code adoption timelines and ENERGY STAR qualification rate assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal efficiency rulemaking acceleration and raw material price volatility. Forecasts reflect documented assumptions regarding electrification infrastructure buildout pace and gas-to-electric conversion subsidy durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Europe Small Kitchen Appliances Market