
 UK Cookware Market | 2026-2036
UK Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
UK Cookware Market Insights
Premium-grade ceramic and stainless steel specifications is bifurcating the UK cookware landscape into health-conscious and durability-seeking buyer pools. Groupe SEB leverages its multi-brand architecture to cover both mass-market and professional kitchen channels. ProCook Ltd. anchors its position through direct-to-consumer specialty retail with strong UK geographic concentration. Zwilling J.A. Henckels AG differentiates via German-engineered forged aluminum and tri-ply stainless steel construction.
UK cookware encompasses vessels and containers designed for stovetop or oven-based food preparation, typically fabricated from aluminum alloys with ceramic sol-gel coatings, cast iron with enamel vitreous layers, or austenitic stainless steel with copper or aluminum disc bases for thermal conductivity. The primary commercial purpose spans residential meal preparation, commercial catering operations, and culinary training environments where heat distribution uniformity and food safety compliance determine equipment selection. Non-stick pans and ceramic cookware represent the fastest-expanding material categories as PFAS-phaseout pressures reshape consumer preferences and retailer stocking policies. Stainless steel pots sustain the largest installed base among hospitality chains requiring induction-compatible, metal-utensil-durable equipment with extended service life.
The Food Standards Agency governs food contact material compliance, while BSI kitemark certification addresses product safety and performance claims for UK-sold cookware. REACH restrictions on per- and polyfluoroalkyl substances directly constrain non-stick coating formulations available to manufacturers serving the British market. Stakeholders must monitor evolving UKCA marking requirements and potential divergence from EU chemical regulations as determinants of supply chain configuration and product development priorities.
Market Dynamics
REACH restrictions on PFAS compounds are forcing UK cookware manufacturers to reformulate non-stick coatings, triggering a wholesale material transition across the supply base and reshaping competitive positioning around compliance speed.
Growth Catalysts
- PFAS Phaseout Mandates:The Food Standards Agency's tightening food contact material standards are pulling demand toward ceramic sol-gel and tri-ply stainless steel alternatives that eliminate fluorinated compounds entirely.
- Induction Infrastructure Rollout:Residential kitchen renovations across Greater London and the South East are accelerating replacement cycles as households upgrade to flat-base, ferromagnetic-compatible cookware.
- Hospitality Sector Modernization:Commercial catering chains are standardizing on induction-ready stainless steel equipment to reduce energy costs and meet carbon reduction commitments.
Market Restraints
- Aluminum Alloy Supply Concentration:UK cookware fabricators depend on a narrow supplier base for aerospace-grade aluminum sheet, exposing margins to energy-driven price volatility.
- Ceramic Coating Durability Gap:Sol-gel ceramic formulations exhibit 40-50% shorter service life versus traditional PTFE, creating buyer skepticism that slows premium conversion.
- UKCA Marking Transition Friction:Divergence from EU conformity assessment procedures is extending product approval timelines and duplicating certification costs for import-dependent brands.
Strategic Opportunities
- Scottish and Northern England Penetration:Lower cookware replacement rates in these regions present white-space demand for direct-to-consumer specialty retailers with localized marketing.
- Professional Kitchen Leasing Models:Subscription-based equipment provisioning for restaurant groups addresses capital constraints while locking in long-term service relationships.
- Carbon-Labeling Differentiation:Anticipated UK mandatory climate disclosure rules for consumer goods will reward early adopters of lifecycle-assessed, low-emission manufacturing.
Industry Challenges
- Coating Formulation Talent Scarcity:The UK lacks sufficient industrial chemists experienced in PFAS-free sol-gel development, forcing reliance on continental European R&D partnerships.
- Legacy Equipment Compatibility:Cast iron and copper-core inventory in hospitality chains requires staged replacement programs that complicate supplier consolidation efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Cookware Market |
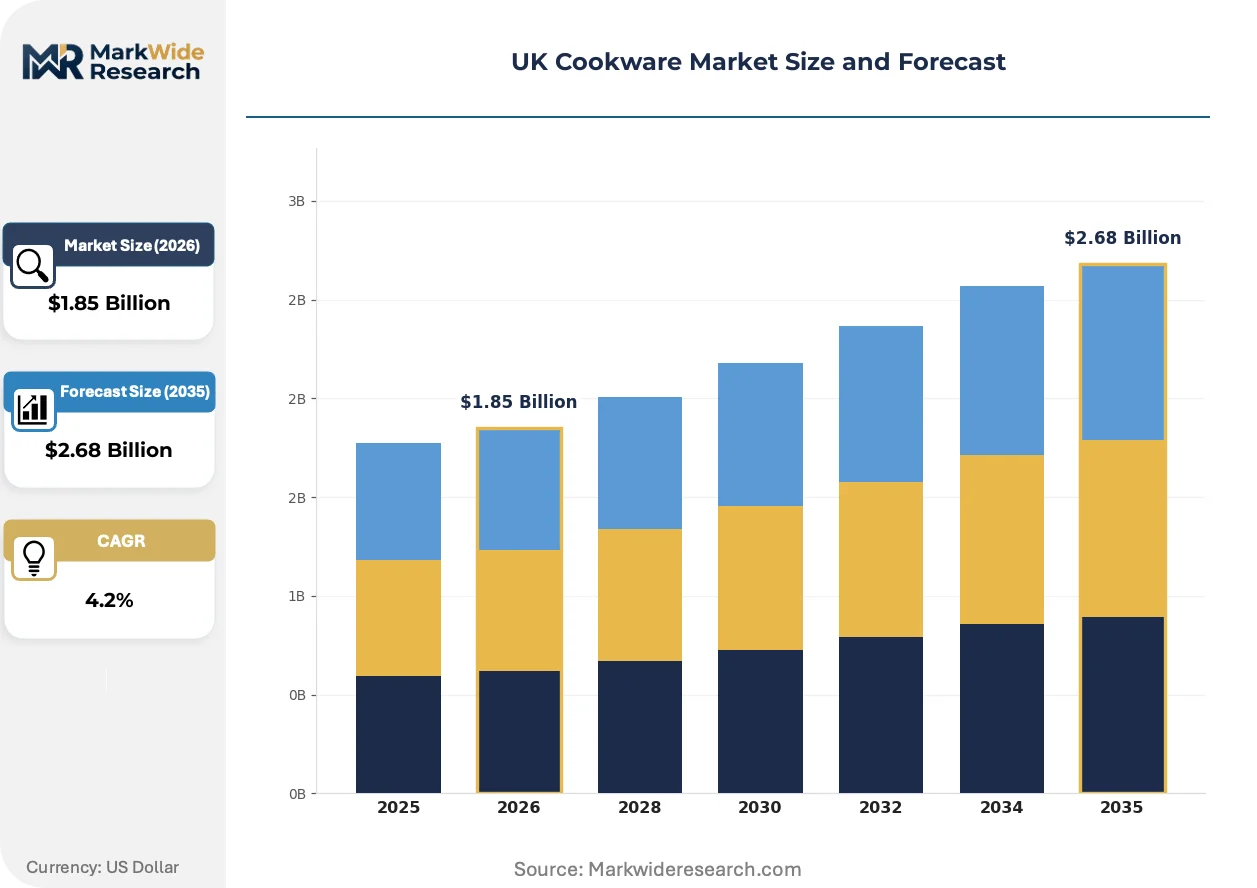
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-stick Pans, Cast Iron Skillets, Stainless Steel Pots, Ceramic Cookware, Copper Bottom Pan, Aluminum Saucepans Material: Aluminum, Cast Iron, Stainless Steel, Ceramic, Copper, Carbon Steel Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Department Stores, Direct Sales End User: Household Consumers, Catering Businesses, Culinary Schools, Hospitality Chains, Food Trucks |
| Companies Covered | Le Creuset, Groupe SEB, Meyer Corporation, Newell Brands, Tramontina, Cuisinart, ProCook Ltd., Scanpan, Zwilling J.A. Henckels AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Cookware Market Trends and Innovations
Ceramic sol-gel coating technology is displacing conventional fluoropolymer formulations across UK retail channels. Three interconnected developments are compressing innovation cycles and redrawing competitive boundaries.
Sol-gel ceramic coatings are displacing PTFE-based non-stick surfaces in mid-market frying pan segments. Retailers including John Lewis and Lakeland are expanding shelf space for these PFAS-free alternatives. The displacement is compressing margins for manufacturers slow to certify compliant formulations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are constraining coating imports into the British market. Manufacturers must submit updated safety dossiers to ECHA for continued market access. Professional kitchen buyers are now specifying PFAS-free equipment in procurement tenders to preempt liability exposure.
Direct-to-consumer specialty retail is capturing share from general merchandise department stores for premium cookware purchases. ProCook and similar operators leverage physical showroom networks with digital fulfillment. This channel shift concentrates in Greater London and commuter belt postcodes where experiential purchasing drives conversion.
UK Cookware Market Segmentation
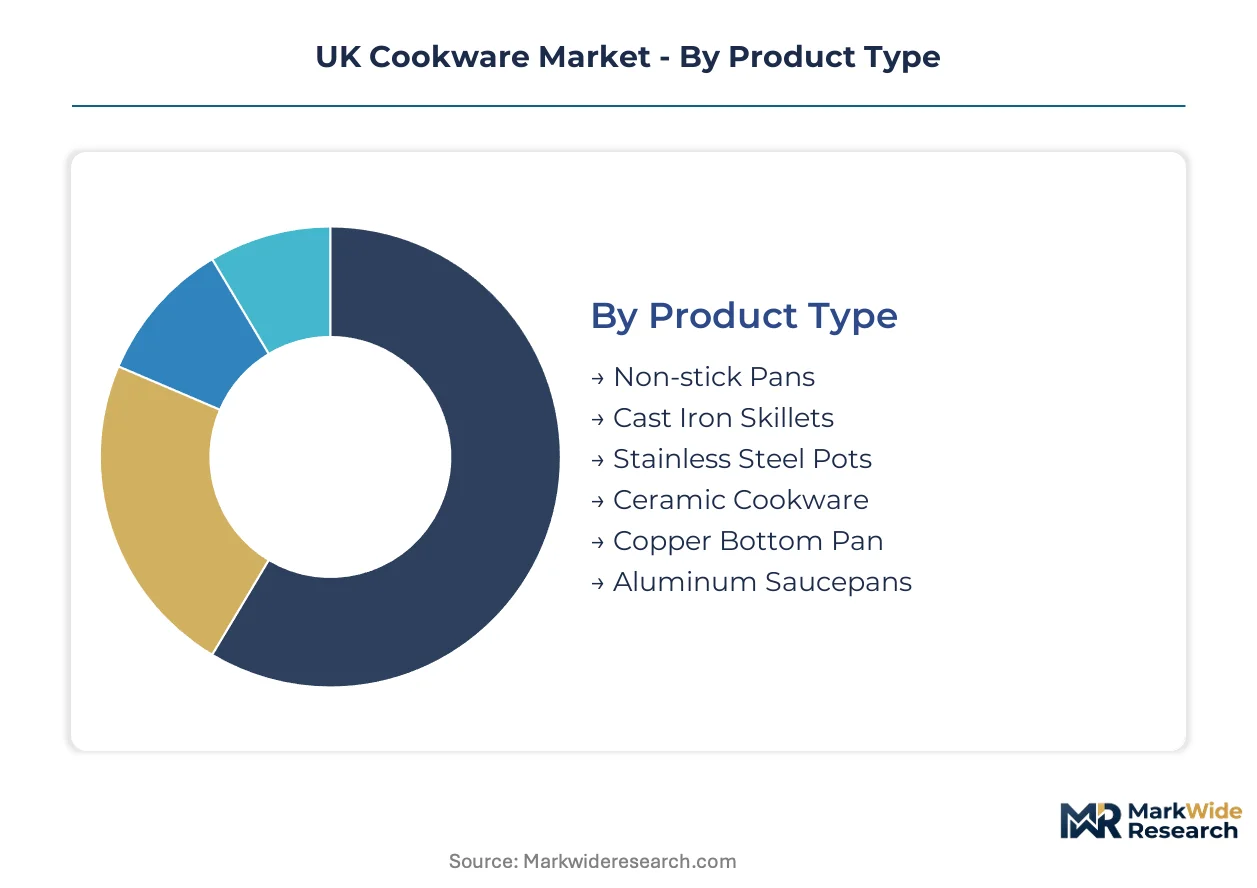
Segmentation reveals how PFAS-phaseout pressures and induction infrastructure upgrades are fragmenting demand across material specifications and channel preferences. Each dimension carries distinct regulatory exposure and margin profiles that determine supplier positioning.
Product Type:
Domestic manufacturing concentrates on stainless steel and cast iron lines, while non-stick and ceramic formulations rely heavily on continental European coating partnerships.
- Non-stick Pans:Sol-gel ceramic coatings are displacing PTFE formulations under REACH Annex XVII constraints. Greater London households drive replacement demand as induction compatibility becomes non-negotiable in kitchen renovations.
- Stainless Steel Pots:Austenitic grades with copper or aluminum disc bases dominate commercial procurement. Hospitality chains across the South East specify these for induction durability and metal-utensil tolerance in high-volume operations.
- Cast Iron Skillets:Enamel-vitreous layered designs from French and UK foundries serve heritage-focused consumers.
- Ceramic Cookware:Sol-gel coated aluminum bodies attract health-conscious buyers seeking PFAS elimination.
- Copper Bottom Pan:Traditional construction persists in premium segments despite induction incompatibility.
- Aluminum Saucepans:Uncoated lines retain budget-positioning in supermarket channels.
Stainless steel pots hold the largest share; momentum sits with ceramic cookware.
Material:
Cost tiers separate aerospace-grade aluminum sheet from commodity recycled grades, with premium thermal conductivity specifications commanding 40-60% price premiums.
- Stainless Steel:Austenitic 304 and 316 grades with impact-bonded aluminum bases deliver induction compatibility and corrosion resistance. Professional kitchen buyers in Manchester and Birmingham procurement consortia prioritize these specifications for lifecycle cost reduction.
- Aluminum:Anodized and ceramic-coated variants serve mid-market frying pan demand. Supply concentrates in a narrow base of aerospace-grade sheet suppliers, exposing fabricators to energy-driven volatility.
- Cast Iron:Enamel-coated production centers on French and UK foundry partnerships.
- Ceramic:Sol-gel formulations require continental European R&D collaboration due to UK chemist scarcity.
- Copper:Laminates retain niche positioning in professional pastry applications.
- Carbon Steel:Seasoned French and UK imports capture chef-influenced residential demand.
Aluminum maintains volume leadership; carbon steel is climbing the fastest.
Distribution Channel:
Channel selection correlates with customer technical sophistication, with specification-heavy buyers favoring assisted-selling environments.
- Specialty Stores:ProCook and similar operators combine physical Greater London showrooms with digital fulfillment. Experiential purchasing drives conversion for premium tri-ply and ceramic lines where tactile evaluation matters.
- Online Retailers:Amazon and direct-to-consumer platforms capture replacement-cycle demand for standardized specifications. Review-driven selection favors brands with established PFAS-free certification visibility.
- Supermarkets:Sainsbury's and Tesco stock entry-level aluminum and basic stainless for impulse replacement.
- Department Stores:John Lewis and Lakeland curate expanded ceramic sol-gel shelf space.
- Direct Sales:B2B provisioning targets hospitality chain standardization programs.
Specialty stores command premium positioning; online retailers are gaining share fastest.
End User:
Application maturity varies sharply, with commercial buyers prioritizing total-cost-of-ownership while residential segments respond to health-framed messaging.
- Household Consumers:Greater London and South East postcodes concentrate upgrade demand as disposable incomes support PFAS-free ceramic and tri-ply stainless conversions. Induction infrastructure rollout accelerates replacement cycles.
- Hospitality Chains:Whitbread, Compass Group, and similar operators standardize on induction-ready stainless equipment. Carbon reduction commitments and energy cost targets drive procurement consolidation.
- Catering Businesses:Independent operators balance capital constraints against durability requirements.
- Culinary Schools:Le Cordon Bleu London and similar institutions specify professional-grade forged aluminum.
- Food Trucks:Space-constrained operations favor lightweight aluminum and carbon steel.
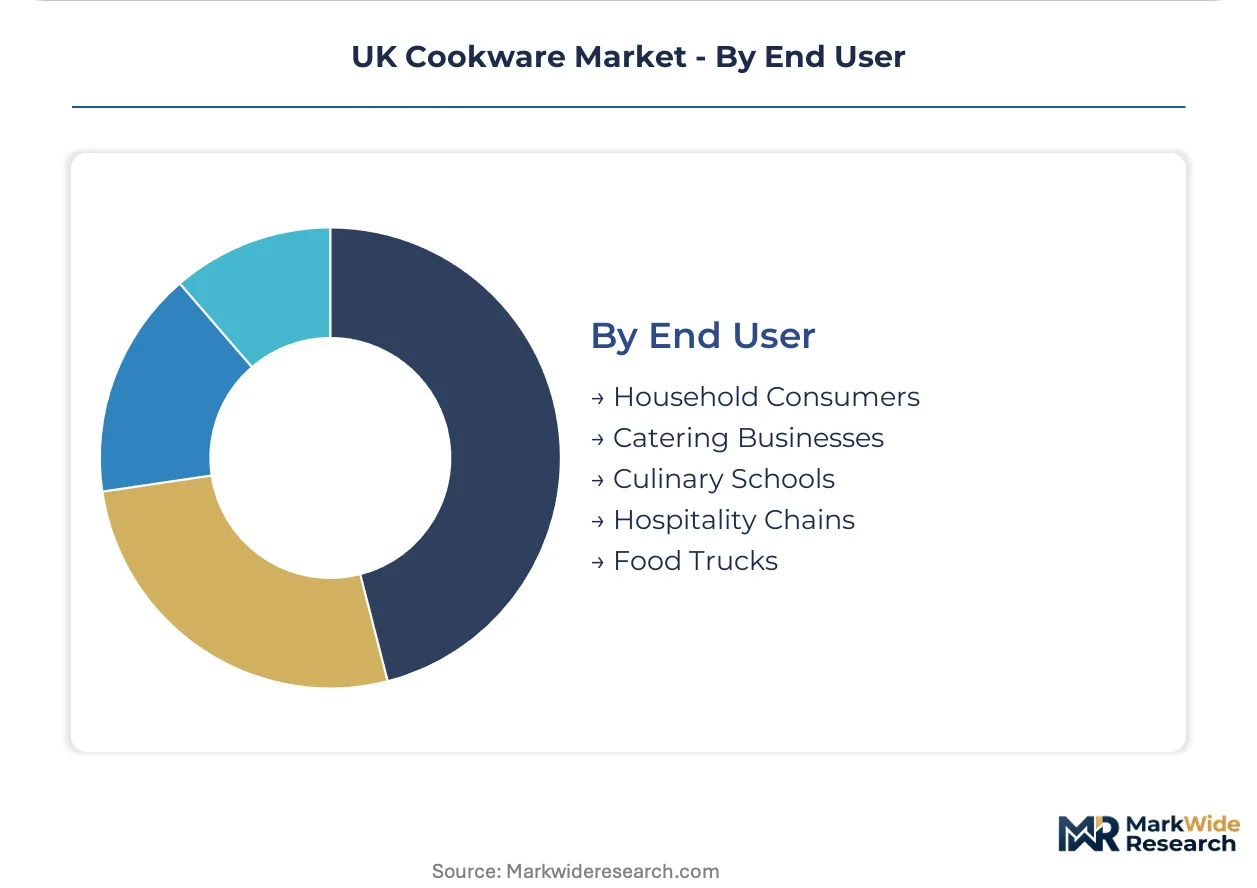
Household consumers represent the largest addressable base; hospitality chains show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity for premium cookware concentrates in Greater London and the South East, where induction-compatible stainless steel demand aligns with higher disposable incomes. The Midlands and North England host secondary distribution nodes, while Scotland and Wales present underpenetrated replacement cycles.
Greater London and South East
Induction infrastructure rollout in Kensington, Chelsea, and Surrey commuter belts accelerates replacement demand for flat-base ferromagnetic cookware. The Food Standards Agency's PFAS-phaseout guidance pulls households toward ceramic sol-gel and tri-ply stainless alternatives. John Lewis and Lakeland flagship locations in Oxford Street and Kingston anchor experiential purchasing for premium lines.
Midlands
Birmingham and Manchester procurement consortia standardize on austenitic stainless equipment for hospitality chain modernization. UKCA marking transition friction extends product approval timelines for import-dependent brands serving these industrial centers. Local fabricators in Stoke-on-Trent leverage historical ceramics expertise to develop enamel-coated cast iron partnerships.
North England
Lower cookware replacement rates in Leeds, Sheffield, and Newcastle create white-space demand for direct-to-consumer specialty retailers. REACH restrictions on per- and polyfluoroalkyl substances constrain coating formulations available to distributors serving budget-positioned supermarket channels. ProCook showroom expansion targets Manchester and Liverpool for localized marketing penetration.
Scotland
Edinburgh and Glasgow households exhibit slower upgrade cycles but rising health-consciousness around PFAS-free ceramic alternatives. Scottish hospitality operators balance carbon reduction commitments against capital constraints in equipment procurement. Le Cordon Bleu London's satellite training partnerships in Edinburgh sustain professional-grade forged aluminum specification demand.
Wales and Northern Ireland
Cardiff and Belfast markets remain underpenetrated by premium specialty retail, with supermarket channels dominating entry-level aluminum and basic stainless distribution. UKCA marking divergence from EU conformity assessment procedures disproportionately impacts cross-border supply chains serving these regions. Local catering businesses favor lightweight aluminum and carbon steel for space-constrained mobile food operations.
UK Cookware Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK cookware supply base. Premium-grade ceramic sol-gel formulation expertise concentrates among continental European R&D partnerships, while scale-driven aluminum fabrication anchors mass-market positioning. Three archetypes dominate: multi-brand conglomerates with professional kitchen channel coverage, direct-to-consumer specialty retailers with geographic concentration, and German-engineered forged metal specialists. Competitive moves center on PFAS-free certification speed and induction compatibility portfolio expansion.
Within the multi-brand tier, Groupe SEB and Zwilling J.A. Henckels AG occupy positions spanning mass-market and professional segments. ProCook Ltd. anchors the direct-to-consumer specialty retail vector with Greater London showroom concentration. These three exemplify how compliance speed with REACH Annex XVII restrictions and UKCA marking requirements determines competitive positioning in the British market.
| Leading Market Players |
|---|
| Le Creuset |
| Groupe SEB |
| Meyer Corporation |
| Newell Brands |
| Tramontina |
| Cuisinart |
| ProCook Ltd. |
| Scanpan |
| Zwilling J.A. Henckels AG |
| Others |
Pricing and Supply Chain Analysis
Scale economies in aerospace-grade aluminum sheet fabrication concentrate supply among a narrow European supplier base, compressing margins for UK cookware fabricators while establishing price floors that resist downward pressure from supermarket private-label competition. REACH Annex XVII compliance costs for PFAS-free ceramic sol-gel coatings add certification premiums that bifurcate pricing power between continental European R&D partnerships and domestic assemblers lacking formulation expertise.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the UK cookware landscape, separating premium ceramic sol-gel lines from commodity PTFE-alternatives through compliance-driven cost layering. Three-tier pricing stratifies across induction-compatible tri-ply stainless, mid-market anodized aluminum, and entry-level uncoated supermarket offerings. Cost compression in mid-market frying pans intensifies because ceramic coating durability gaps force warranty provisioning that erodes manufacturer margins. Hospitality chains show least price sensitivity, prioritizing lifecycle cost over unit acquisition, while supermarket impulse buyers drive volume at razor-thin spreads.
Supply Chain Analysis
France and Germany anchor ceramic sol-gel coating formulation, while China and Italy concentrate aluminum sheet and enamel-cast iron fabrication respectively. UK assembly draws from aerospace-grade aluminum disc bases, copper-clad impact-bonding materials, and continental European sol-gel chemistry partnerships. Single-source vulnerability runs through the narrow aerospace aluminum supplier base exposed to energy-driven volatility. Distribution runs through direct-to-consumer specialty retail in Greater London, mass-market supermarket channels, and B2B provisioning for hospitality standardization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK cookware market operates as a substitution defense against ceramic sol-gel alternatives displacing legacy PTFE formulations, requiring incumbents to navigate compliance speed gaps that threaten brand equity erosion among health-conscious household buyers.
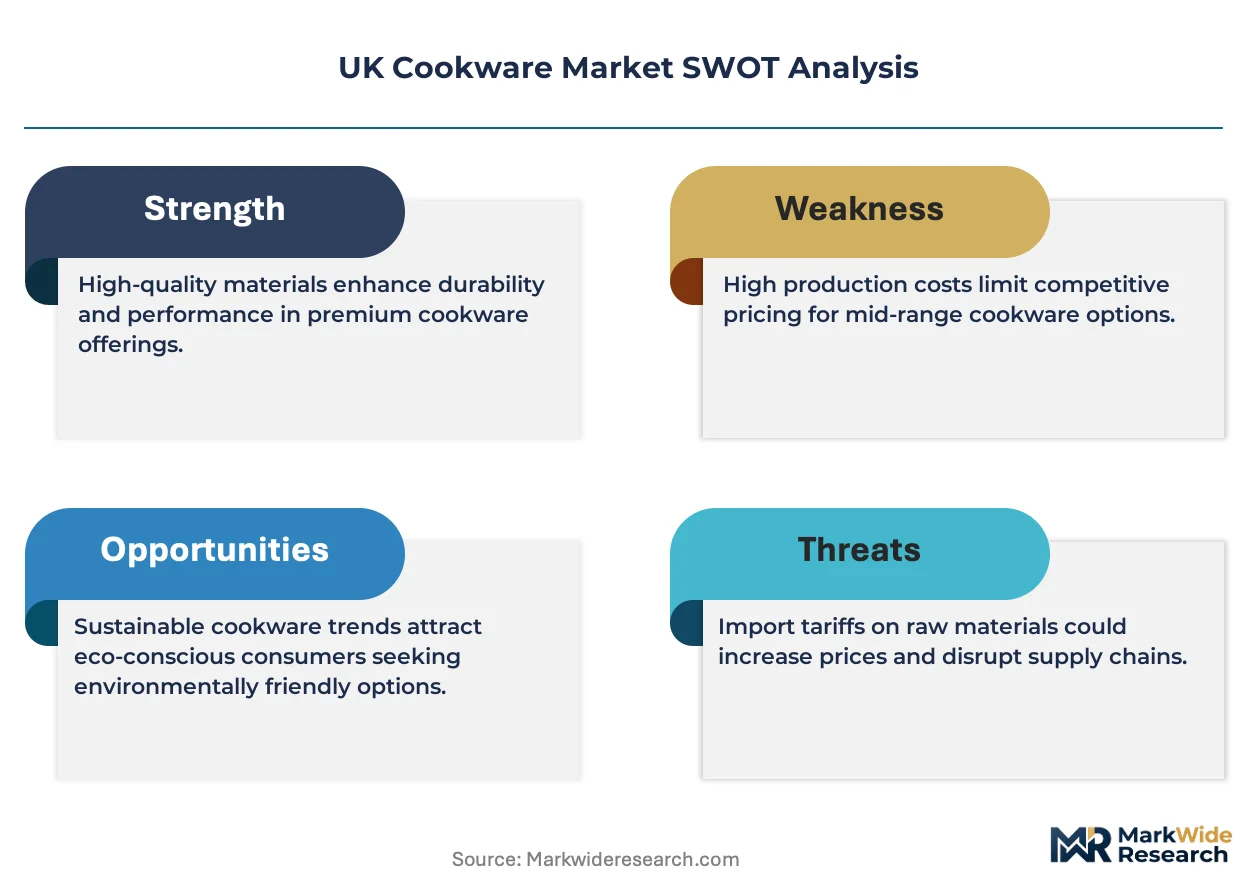
For Market Incumbents: Secure PFAS-free certification speed through continental European R&D partnerships before UKCA marking divergence extends approval timelines. Lock in long-term aerospace-grade aluminum supply agreements to buffer energy-driven price volatility. Channel control through Greater London showroom density remains the priority lever against direct-to-consumer specialty retail encroachment. For New Entrants and Emerging Players: Lead with white-space penetration in Scottish and Northern England markets where cookware replacement rates lag Greater London by significant margins. Target Manchester and Liverpool for localized experiential retail deployment. Subscription-based professional kitchen leasing models address hospitality capital constraints while building service relationship lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors direct-to-consumer specialty retailers with UK geographic concentration and sol-gel formulation partnerships. Long-term viability hinges on carbon-labeling readiness ahead of anticipated UK mandatory climate disclosure rules. Watch for UKCA marking divergence from EU conformity assessment procedures as inflection signal for supply chain reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Partnership | REACH Annex XVII compliance secures retail shelf access at John Lewis and Lakeland. |
| Induction-Compatible Portfolio Expansion | Flat-base ferromagnetic designs capture replacement demand from Greater London kitchen renovations. |
| Direct-to-Consumer Showroom Network | Physical tactile evaluation drives conversion for premium tri-ply and ceramic lines. |
| Professional Kitchen Leasing Model | Subscription provisioning addresses Whitbread and Compass Group capital constraints. |
| Carbon-Labeling Early Adoption | Lifecycle-assessed manufacturing positions ahead of UK mandatory climate disclosure rules. |
Research Methodology
The analysis maps stainless steel fabrication, ceramic sol-gel coating, cast iron enameling, and aluminum anodization sub-sectors, each validated through procurement directors at hospitality chains, category buyers at John Lewis and Lakeland, plant managers at UK assembly operations, and R&D leads at continental European coating partnerships. Primary interview insights combined with secondary validation from FSA food contact material guidance, ECHA REACH dossier submissions, UKCA marking technical documentation, and customs trade data for aluminum sheet imports. Bottom-up channel volume estimates and top-down macroeconomic alignment provided triangulation integrity.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled material specifications, distribution channel mix, end-user application maturity, and regional induction infrastructure penetration as core segmentation dimensions. CAGRs derived from replacement cycle analysis, regulatory compliance timelines, and hospitality sector modernization trajectories. Industry-specific forecast inputs included aerospace aluminum price volatility indices and PFAS-phaseout regulatory milestone sequencing.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, UKCA divergence trajectory, or induction infrastructure rollout pace would require recalibration. Forecasts reflect documented assumptions regarding ceramic coating durability improvements and hospitality carbon reduction commitment durability. Specific risks that could revise projections include ECHA restriction scope expansion, UK-EU regulatory divergence acceleration, or energy price shock impacts on aluminum supply. Recalibration cycles align with material shifts in FSA guidance, ECHA annex updates, and UKCA technical standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Household Coffee Machine Market