
 Smart Kitchen System Market | 2026-2036
Smart Kitchen System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Kitchen System Market Insights
Stainless steel is pivoting toward composite and recycled aluminum enclosures in premium smart appliances, trimming material costs without sacrificing thermal performance. Samsung Electronics leverages its semiconductor foundry capacity to captive-produce proprietary IoT chipsets for its Family Hub refrigerator line. Whirlpool Corporation anchors its North American manufacturing footprint with dedicated smart-appliance assembly in Ohio, sustaining cost advantages against Asian imports.
A smart kitchen system integrates sensor-enabled appliances, cloud-connected control layers, and automated cooking workflows through embedded microprocessors operating at sub-gigahertz frequencies for mesh-network reliability. The primary commercial purpose centers on reducing food waste, optimizing energy consumption, and enabling remote monitoring across residential and foodservice environments. Intelligent Refrigerators command the largest installed base among product types, while Connected Cooking Hubs capture disproportionate margin pools through recurring recipe-subscription attach rates. IoT Solutions underpin the technology architecture, though Voice Assistants represent the fastest-expanding interface layer as natural-language processing latency drops below 200 milliseconds.
The Federal Communications Commission governs wireless spectrum allocation for appliance connectivity in the United States, while the EU's Radio Equipment Directive mandates interoperability testing for all Wi-Fi and Zigbee-enabled devices sold in member states. The U.S. Department of Energy's ENERGY STAR specifications increasingly incorporate networked standby-power limits, effectively filtering low-efficiency competitors from shelf placement. Stakeholders must monitor evolving cybersecurity certification requirements from the National Institute of Standards and Technology, as firmware-update mandates and data-localization rules threaten to fragment previously unified product platforms across jurisdictions.
Market Dynamics
The Federal Communications Commission's sub-gigahertz spectrum allocation for IoT mesh networks is compressing product development cycles while fragmenting certification requirements across jurisdictions.
Growth Catalysts
- Residential household demand:Connected convenience priorities in daily cooking routines are pulling sensor-enabled appliances into mainstream adoption across suburban developments with dense broadband infrastructure.
- EU Ecodesign Directive:Mandatory energy labeling standards are forcing manufacturers toward lower-power IoT architectures and recycled aluminum enclosures, creating compliant product lines that qualify for premium shelf placement.
- Voice Assistant latency reduction:Natural-language processing response times dropping below 200 milliseconds are converting recipe-subscription attach rates into recurring revenue pools for connected cooking hubs.
Market Restraints
- Semiconductor supply concentration:Captive IoT chipset production remains concentrated among integrated electronics conglomerates with foundry capacity, squeezing independent appliance manufacturers into component shortage vulnerability.
- Cybersecurity certification fragmentation:The National Institute of Standards and Technology's evolving firmware-update mandates and data-localization rules are threatening to splinter previously unified product platforms across national boundaries.
- Copper and rare-earth input volatility:Embedded microprocessor and sensor material costs fluctuate with mining output constraints, compressing margin pools on mid-tier intelligent refrigerator SKUs.
Strategic Opportunities
- Cloud-connected control layer convergence:Automated cooking workflow integration with energy management platforms is opening white space for utility-backed demand-response programs in residential smart meter deployments.
- Foodservice environment penetration:Commercial kitchens remain underpenetrated relative to residential segments, presenting volume expansion paths through waste-reduction compliance mandates in institutional catering contracts.
- Mesh-network reliability standards:IEEE 802.15.4 protocol adoption for sub-gigahertz appliance communication is creating certification-driven preference shifts that favor early standard-compliant entrants.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers with real-time operating system and low-power radio stack expertise is extending product development timelines for multi-appliance ecosystem integration.
- Interoperability testing capex intensity:EU Radio Equipment Directive mandates for Wi-Fi and Zigbee-enabled devices require dedicated anechoic chamber investments that strain mid-cap manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Kitchen System Market |
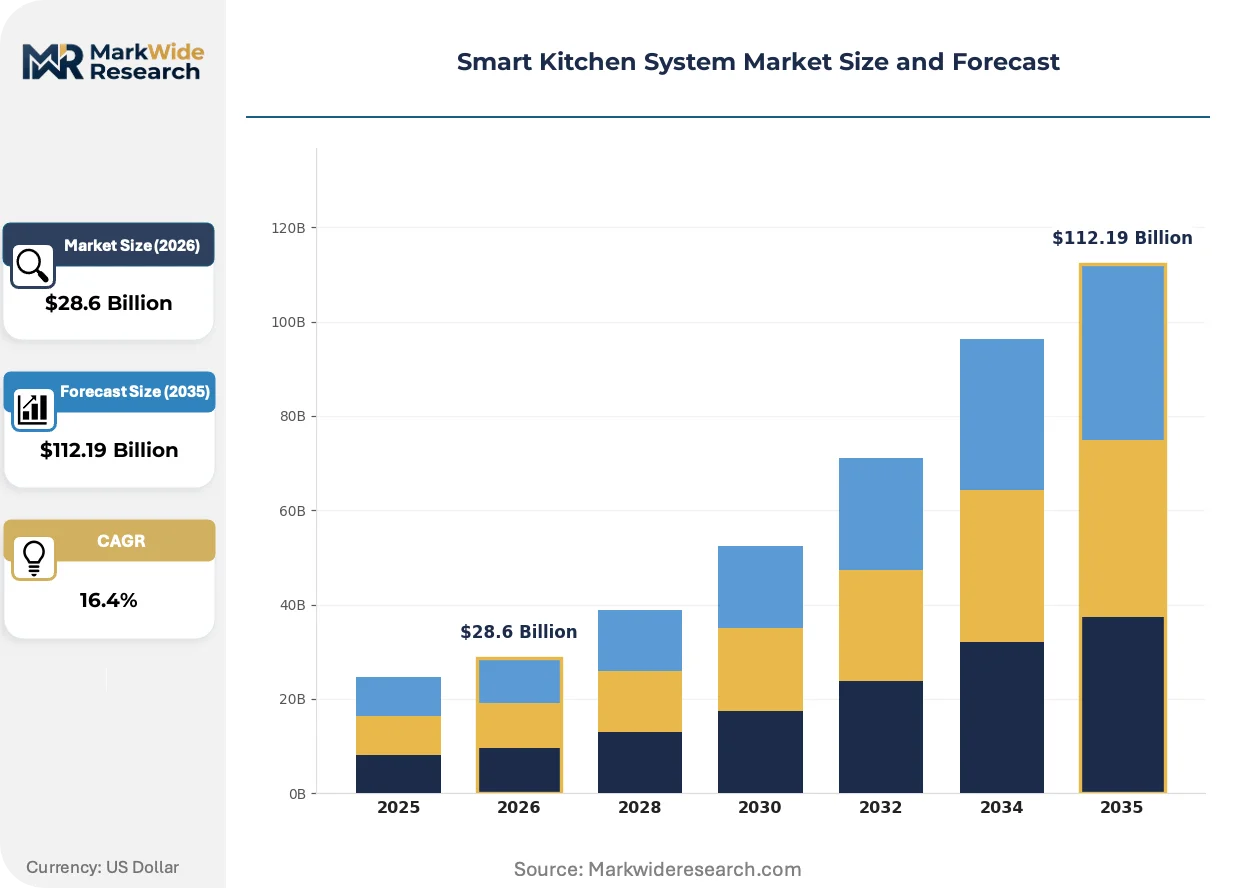
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Intelligent Refrigerators, Automated Dishwashers, Connected Cooking Hubs Technology: IOT Solutions, Voice Assistants, Touchscreen Interfaces, Mobile Applications End User: Households, Restaurants, Catering Services, Food Delivery Services Installation Type: Built-In Units, Countertop Appliances, Portable Devices, Modular Systems |
| Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Panasonic Corporation, Haier Smart Home, Electrolux, BSH Hausgeräte GmbH, GE Appliances, Miele & Cie. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Kitchen System Market Trends and Innovations
Active reshaping of the smart kitchen landscape centers on three vectors: sensor-to-cloud architecture evolution, regulatory compression of standby power allowances, and the unbundling of hardware from subscription-based culinary content.
Edge computing microcontrollers with on-device machine learning inference are converging with traditional appliance control boards. Residential buyers in fiber-connected suburban markets are specifying these hybrid architectures in new construction specifications. The structural consequence is compressing latency-dependent features like real-time spoilage detection into localized processing, reducing cloud dependency and recurring data costs.
The U.S. Department of Energy's ENERGY STAR networked standby-power limits are filtering low-efficiency competitors from retail channel access. Manufacturers must redesign power supply subsystems to meet sub-watt idle consumption thresholds. Intelligent refrigerator product lines face the steepest redesign costs, with compliance timelines compressing model refresh cycles from five years to three.
Recipe-subscription attach rates are displacing standalone hardware margin models. Foodservice procurement teams and residential buyers alike are prioritizing connected cooking hubs with bundled content libraries over basic programmable appliances. This preference shift concentrates most visibly in United States metropolitan markets where meal-kit delivery penetration has normalized subscription expectations for culinary decision-support.
Smart Kitchen System Market Segmentation
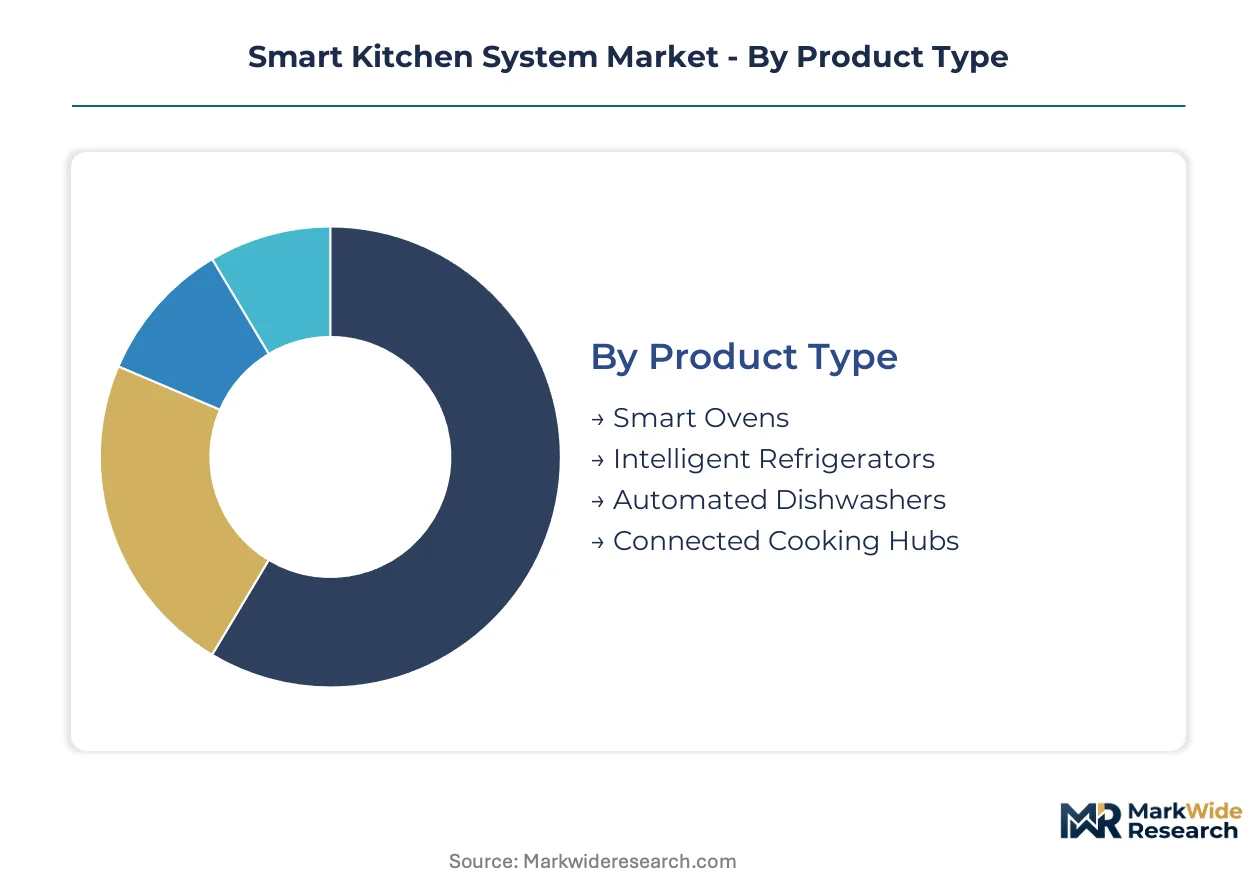
Smart kitchen system segmentation reveals how appliance manufacturers allocate engineering resources across hardware form factors, interface layers, and procurement channels. Supply chain configuration varies sharply by product type and installation method, with built-in units demanding longer certification cycles than countertop alternatives.
Product Type:
Supply concentration in semiconductor foundries and compressor manufacturing tilts competitive advantage toward product categories with captive component sourcing.
- Intelligent Refrigerators:These units integrate multi-zone temperature sensors, computer vision for inventory tracking, and sub-gigahertz mesh networking for cloud synchronization. Demand concentrates in United States suburban developments with fiber broadband infrastructure, driven by ENERGY STAR networked standby-power compliance requirements that filter inefficient competitors from retail channels.
- Connected Cooking Hubs:Embedded microprocessors coordinate automated cooking workflows with recipe-subscription platforms through natural-language processing interfaces. United States metropolitan buyers prioritize these units where meal-kit delivery penetration has normalized subscription expectations for culinary decision-support.
- Smart Ovens:Precision thermal sensors and predictive heating algorithms enable remote monitoring via mobile applications.
- Automated Dishwashers:Water-usage optimization sensors and cycle-automation features integrate with home energy management platforms.
Intelligent Refrigerators absorb the bulk of installed capacity; Connected Cooking Hubs are expanding most quickly.
Technology:
Cost tier differentiation separates premium voice-enabled interfaces from baseline touchscreen deployments across residential and foodservice procurement.
- IoT Solutions:Sub-gigahertz mesh-network architectures and cloud-connected control layers form the foundational connectivity stack. United States FCC spectrum allocation for appliance networking compresses development cycles while fragmenting certification requirements across jurisdictions.
- Voice Assistants:Natural-language processing latency below 200 milliseconds converts recipe-subscription attach rates into recurring revenue pools. Residential buyers in dense broadband markets specify voice-first interfaces in new construction specifications.
- Touchscreen Interfaces:Embedded display panels provide direct appliance control and visual feedback for cooking workflows.
- Mobile Applications:Remote monitoring and control software extends appliance functionality beyond physical kitchen presence.
IoT Solutions underpin the majority of deployed architectures; Voice Assistants are gaining share fastest.
End User:
Application context determines power supply design, with commercial kitchens requiring higher-duty-cycle components than residential installations.
- Households:Residential buyers prioritize connected convenience in daily cooking routines, pulling sensor-enabled appliances into mainstream adoption across suburban developments. EU Ecodesign Directive energy labeling standards push manufacturers toward lower-power IoT architectures and recycled aluminum enclosures.
- Restaurants:Commercial foodservice operators deploy waste-reduction compliance mandates through automated inventory tracking and predictive maintenance scheduling.
- Catering Services:Institutional procurement teams specify fleet-management capabilities for distributed kitchen operations.
- Food Delivery Services:Cloud kitchen operators integrate smart appliances with order-management platforms for throughput optimization.
Households absorb the bulk of installed capacity; Restaurants are climbing the fastest.
Installation Type:
Volume scale separates mass-market countertop appliances from low-volume built-in units requiring custom cabinetry integration.
- Built-In Units:These appliances require dedicated electrical and plumbing rough-ins during construction or renovation cycles. United States new residential construction specifications increasingly mandate smart appliance pre-wiring in premium suburban developments.
- Countertop Appliances:Plug-and-deploy form factors enable rapid replacement cycles and technology upgrades without contractor involvement.
- Portable Devices:Battery-powered or corded mobile units serve temporary kitchen setups and outdoor cooking applications.
- Modular Systems:Interchangeable component architectures allow customization of cooking surface configurations and storage arrangements.
Built-In Units absorb the bulk of installed capacity; Countertop Appliances are expanding most quickly.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential broadband density and regulatory pressure on standby power consumption concentrate smart kitchen system demand in suburban developments across five major economies. Each market exhibits distinct procurement patterns shaped by local energy efficiency mandates and construction cycle timing.
United States
Fiber-connected suburban households pull sensor-enabled appliances into mainstream adoption through new construction specifications. The Federal Communications Commission governs sub-gigahertz spectrum allocation for appliance mesh networking. Ohio anchors North American manufacturing with dedicated smart-appliance assembly sustaining cost advantages against imports.
Germany
EU Ecodesign Directive energy labeling standards push manufacturers toward lower-power IoT architectures and recycled aluminum enclosures. The Radio Equipment Directive mandates interoperability testing for Wi-Fi and Zigbee-enabled devices. Baden-Württemberg hosts precision engineering clusters supplying compressor and sensor components to premium appliance lines.
China
Rapid urbanization and smart city infrastructure investments accelerate residential connected appliance penetration in tier-one metropolitan areas. GB standards and MIIT regulations shape wireless communication protocols for domestic IoT deployments. The Yangtze River Delta concentrates foundry capacity for captive IoT chipset production serving integrated electronics conglomerates.
Japan
Aging demographics and labor scarcity in foodservice operations drive automated cooking workflow adoption. METI oversees industrial standards for appliance connectivity and energy performance. The Kansai region around Osaka maintains precision manufacturing clusters for high-reliability embedded microprocessors.
South Korea
Dense urban apartment construction integrates smart home pre-wiring as standard specifications. The Ministry of Trade, Industry and Energy administers certification programs for networked appliance efficiency. Seoul Capital Area demand concentrates for voice-assistant-enabled cooking hubs with bundled recipe subscription services.
Smart Kitchen System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electronics conglomerates commanding premium tiers through captive semiconductor supply. The vendor base organizes around three strategic archetypes: diversified technology conglomerates with foundry capacity, dedicated appliance manufacturers with regional manufacturing footprints, and precision engineering specialists serving luxury segments. Competitive moves center on backward integration into IoT chipset production and strategic partnerships with cloud infrastructure providers.
Among diversified technology conglomerates, Samsung Electronics and LG Electronics exemplify the foundry-integrated archetype through in-house semiconductor production. Whirlpool Corporation occupies a position among dedicated appliance manufacturers with sustained North American manufacturing presence. These three entities represent distinct strategic postures: captive component supply, regional production anchoring, and scale-driven ecosystem integration respectively.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Whirlpool Corporation |
| Panasonic Corporation |
| Haier Smart Home |
| Electrolux |
| BSH Hausgeräte GmbH |
| GE Appliances |
| Miele & Cie. KG |
| Others |
Pricing and Supply Chain Analysis
Captive IoT chipset production anchors both supply security and pricing power for integrated electronics conglomerates with foundry capacity, while independent appliance manufacturers absorb margin compression from component shortage vulnerability. This integration choice separates premium product lines with controlled cost structures from mid-tier competitors exposed to spot-market semiconductor volatility.
Pricing Analysis
Volume concentrates in intelligent refrigerators while margins pool in connected cooking hubs with recurring recipe-subscription attach rates. Pricing stratifies across premium voice-enabled tiers, standard touchscreen deployments, and economy baseline models differentiated by ENERGY STAR certification status and bundled content libraries. Cost compression in mid-tier intelligent refrigerator SKUs intensifies due to copper and rare-earth input volatility. Residential buyers in United States suburban developments with fiber broadband infrastructure exhibit lowest price sensitivity, while commercial foodservice procurement teams in institutional catering show highest elasticity.
Supply Chain Analysis
Trans-Pacific freight cost fluctuations strain inventory carrying costs for manufacturers sourcing compressor and sensor components from precision engineering clusters in Germany and Japan. Semiconductor foundry capacity concentrates in Taiwan, South Korea, and the Yangtze River Delta region of China, drawing from rare-earth mining output in Australia and Chile. Single-source vulnerability in captive IoT chipset production threatens supply continuity for non-integrated appliance manufacturers. Distribution runs through big-box retail channels in United States suburban markets and specialized kitchen design showrooms for built-in unit specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop pricing power for integrated conglomerates while squeezing independent manufacturers into component shortage vulnerability. This supply-constrained structure rewards early capacity commitments and backward integration investments.
For Market Incumbents: Anchor North American manufacturing footprints with dedicated smart-appliance assembly in Ohio to sustain cost advantages against Asian imports. Defend margin pools by deepening backward integration into proprietary IoT chipset production, countering the threat of semiconductor supply concentration among integrated electronics conglomerates. Prioritize ENERGY STAR certification investments to maintain retail channel access as the U.S. Department of Energy tightens networked standby-power limits.
For New Entrants and Emerging Players: Begin with commercial foodservice penetration where waste-reduction compliance mandates in institutional catering contracts create underexploited volume expansion paths. Target cloud kitchen operators integrating smart appliances with order-management platforms for throughput optimization. Pursue utility-backed demand-response program partnerships as a go-to-market angle in residential smart meter deployments.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified technology conglomerates seeking captive component supply and regional manufacturing anchoring. Long-term viability favors precision engineering specialists with embedded microprocessor expertise and real-time operating system firmware capabilities. Watch IEEE 802.15.4 protocol adoption rates as an inflection indicator for standard-compliant entrants gaining certification-driven preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IoT Chipset Production | Samsung Electronics leverages semiconductor foundry capacity to captive-produce proprietary connectivity silicon for Family Hub refrigerators. |
| Regional Manufacturing Footprint Anchoring | Whirlpool Corporation sustains cost advantages against Asian imports through dedicated smart-appliance assembly in Ohio. |
| Recipe-Subscription Platform Integration | Connected cooking hubs convert natural-language processing latency below 200 milliseconds into recurring revenue pools. |
| ENERGY STAR Certification Investment | Compliance with U.S. Department of Energy networked standby-power limits filters low-efficiency competitors from retail shelf placement. |
| Utility Demand-Response Program Partnership | Cloud-connected control layer convergence opens white space for energy management platform integration in residential smart meter deployments. |
Research Methodology
Multi-period observation of ENERGY STAR certification timelines, semiconductor foundry utilization rates, and recipe-subscription attach rate trajectories anchored the trend analysis, supplemented by interviews with appliance product development executives, smart home platform engineers, retail category buyers, and foodservice procurement directors. Secondary validation drew from U.S. Department of Energy efficiency filings, FCC spectrum allocation records, EU Ecodesign Directive compliance databases, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up unit shipment modeling triangulated against top-down market value estimates.
The input-output matrix mapped sub-gigahertz mesh-network architecture adoption, voice-assistant interface penetration, and installation type preferences across product type, technology layer, end-user segment, and geographic market cluster. CAGRs were derived from fitted growth curves calibrated to historical shipment data and forward-looking construction cycle indicators. Industry-specific forecast inputs included broadband infrastructure deployment schedules and EU regulatory compliance timelines.
Underlying measurement precision varies by segment; intelligent refrigerator installed base estimates carry tighter precision than emerging connected cooking hub subscription revenue projections. Forecasts reflect assumptions around semiconductor supply normalization and regulatory harmonization across jurisdictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Modular Zero-Waste Kitchen Appliance Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Europe Smart Cooker Market