
 Popcorn Makers Market | 2026-2036
Popcorn Makers Market Size, Share, and Industry Trends Forecast 2026-2036
Popcorn Makers Market Analytics
Stainless steel is restructuring the interior architecture of mid-tier and premium popcorn makers as manufacturers abandon chrome-plated aluminum to cut corrosion risk and extend warranty terms. Gold Medal Products leverages its foundry relationships in Ohio to control casting costs for commercial kettle assemblies. Cretors anchors the North American theater supply channel through direct service contracts with cinema circuits. Presto competes on price at mass retail by sourcing stamped housings from established Asian metalworking zones.
A popcorn maker is an electromechanical or thermal appliance designed to agitate and heat corn kernels to their popping temperature of approximately 180°C, using forced convection, conductive surface contact, or microwave radiation to achieve uniform expansion with minimal unpopped waste. Electric poppers with integrated stirring mechanisms and oil-distribution ports dominate household sales volumes, while air poppers command premium placement among health-positioned buyers seeking fat-free preparation. Commercial operators in movie theaters and snack shops favor large-batch kettles with calibrated thermostat feedback loops that sustain throughput during peak concession rushes.
The US Consumer Product Safety Commission enforces electrical cord and heating-element safety standards that shape domestic product liability exposure, while the EU's REACH framework restricts certain coatings and solder compositions in appliances sold across member states. China's GB standards for household electrical appliances set baseline insulation and thermal cutoff requirements for export-manufactured units bound for multiple jurisdictions. Stakeholders must weigh whether to pursue modular platform designs that span regulatory zones or to fragment production across region-specific toolings.
Market Dynamics
The EU's Ecodesign Directive is forcing wattage reductions in heating elements, compelling manufacturers to redesign thermal architectures while maintaining popping efficiency. This regulatory compression is cascading through supply chains as foundries retool casting specifications and retailers renegotiate energy-label placement.
Growth Catalysts
- Streaming Subscription Density:Household penetration of streaming platforms in Germany and the United States is pulling air poppers into living rooms as consumers replicate theater-style snacking environments.
- REACH Compliance Migration:Manufacturers abandoning chrome-plated aluminum for stainless steel interiors are capturing extended warranty terms and reduced corrosion liability.
- Ohio Foundry Cluster:Concentrated kettle-casting capacity in the Midwestern United States is sustaining commercial-grade supply for theater operators.
Market Restraints
- Nickel Price Volatility:Stainless steel feedstock costs fluctuate with Indonesian ore export policies, compressing margin on mid-tier units.
- Single-Source Heating Element Supply:Calibrated thermostat assemblies for commercial kettles concentrate among two German component suppliers.
- Air Popper Throughput Ceiling:Fat-free preparation methods sacrifice batch size and speed, limiting penetration in high-volume concession environments.
Strategic Opportunities
- India Appliance Retail Expansion:Organized retail corridors in Mumbai and Bangalore remain underpenetrated for electric poppers relative to microwave penetration rates.
- Smart Home Integration:Voice-activation modules and app-controlled timing are converging with kitchen appliance ecosystems.
- Extended Producer Responsibility Schemes:France's repairability index mandates are creating competitive differentiation for modular, field-serviceable designs.
Industry Challenges
- Electrical Safety Certification Lag:China's GB standard updates for thermal cutoffs require retesting cycles that delay product launches by four to six months.
- Die-Casting Tooling Reconfiguration:Shifting between region-specific wattage specifications fragments production runs and inflates per-unit fixed costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popcorn Makers Market |
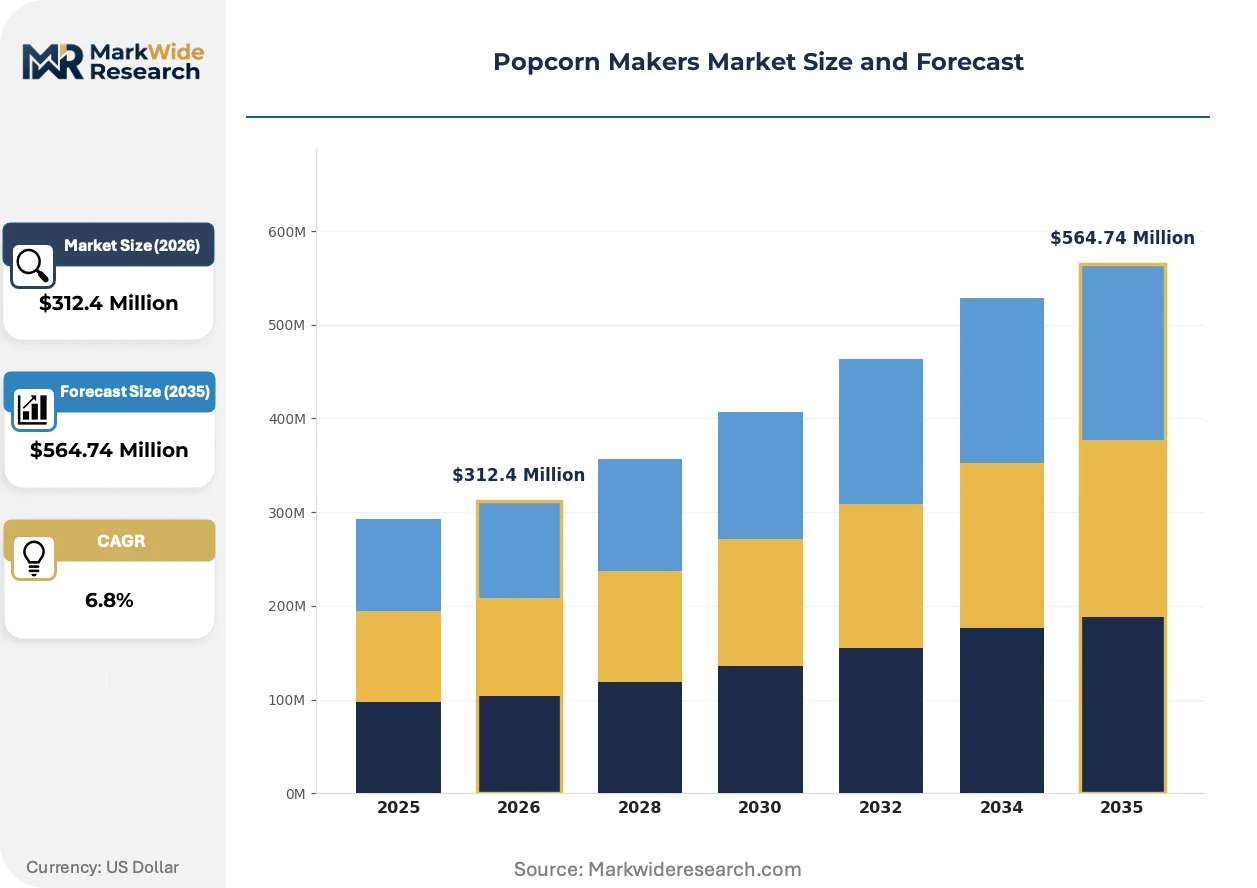
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Popper, Stovetop Popper, Microwave Popper, Electric Popper End User: Household, Commercial, Movie Theaters, Snack Shops Technology: Hot Air, Electric Heating, Induction, Manual Capacity: Small Batch, Medium Batch, Large Batch, Extra Large Batch |
| Companies Covered | Gold Medal Products, Cretors, Nostalgia Electrics, Great Northern Popcorn, Presto, Paragon-Manufactured Fun, West Bend, Hamilton Beach Brands, Jarden Consumer Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popcorn Makers Market Evolving Landscape
Intelligent thermal management and material substitution are compressing traditional design cycles. Manufacturers now face simultaneous pressure to reduce energy draw, extend service intervals, and integrate with connected kitchen ecosystems.
Precision induction heating is automating temperature calibration in premium residential units. Health-positioned buyers in Scandinavia and the Pacific Northwest are specifying these systems to eliminate hot-spot scorching and reduce unpopped kernel waste. The technology is automating quality consistency previously requiring manual stirring intervention.
REACH Annex XVII restrictions on certain solder compositions are forcing assembly line conversions across contract manufacturers in Guangdong and Zhejiang. Industrial consequence includes accelerated migration to laser-welded stainless steel joints. Small-batch artisan producers in Italy and Portugal face disproportionate compliance burden relative to volume scale.
Direct-to-consumer refurbishment channels are emerging as warranty-service differentiators. Theater operators and institutional buyers in the United States now expect manufacturer-managed parts availability rather than third-party repair networks. This behavioral shift concentrates aftermarket revenue with original equipment makers and compresses independent service organization margins.
Popcorn Makers Market Segmentation
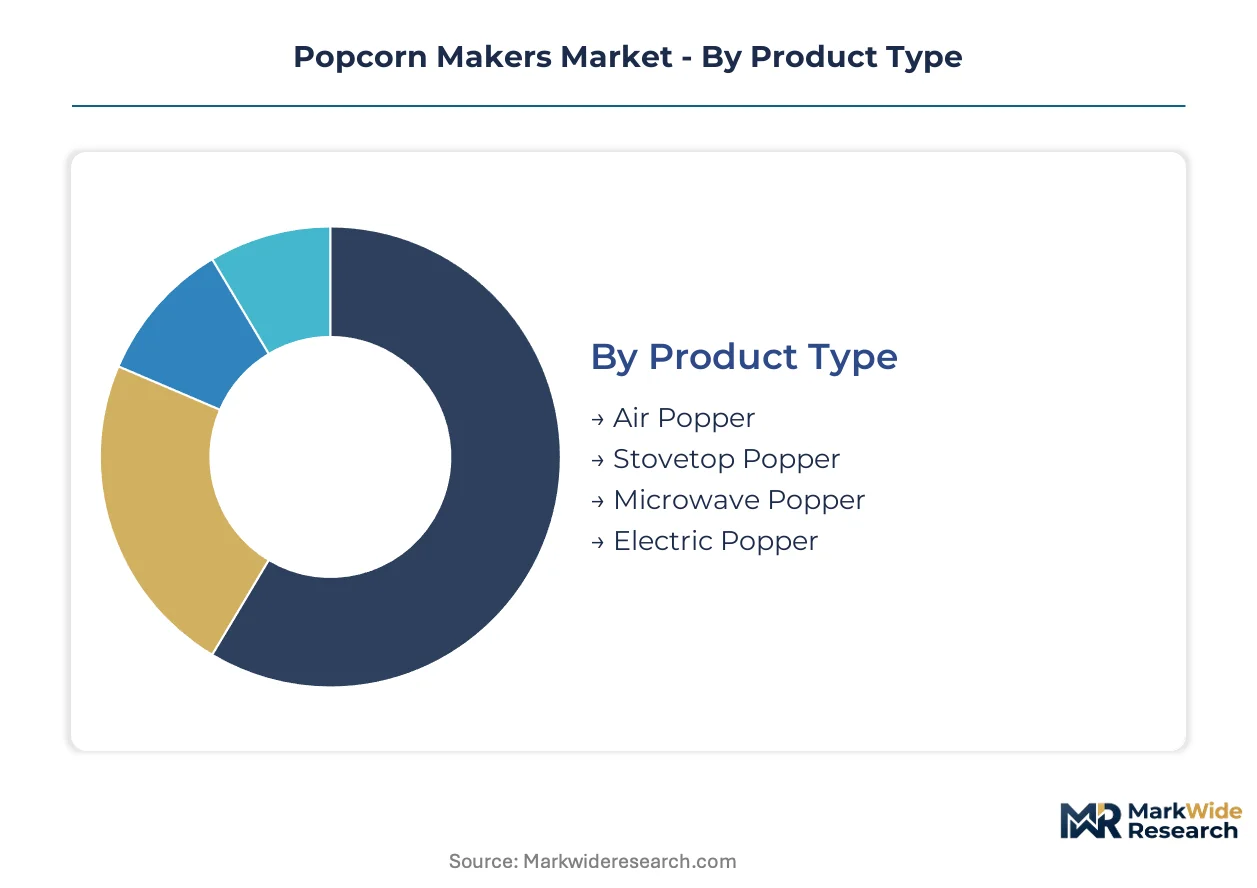
Popcorn maker purchasing patterns diverge sharply between impulse retail buyers seeking countertop convenience and institutional operators optimizing throughput per square foot. Segment boundaries increasingly blur as manufacturers deploy modular platforms spanning residential and light commercial duty cycles.
Product Type:
Standalone countertop units dominate household penetration, while embedded or built-in configurations serve commercial retrofit projects and custom kitchen installations.
- Air Popper:Forced convection systems operating at approximately 180°C eliminate oil requirements through calibrated airflow velocity. Demand clusters in Germany and the Pacific Northwest among health-positioned buyers seeking fat-free preparation methods. The EU's Ecodesign Directive wattage caps are compressing heating element specifications in this segment.
- Electric Popper:Integrated stirring mechanisms with oil-distribution ports sustain the highest household sales volumes across mass retail channels. US Consumer Product Safety Commission cord and heating-element standards shape liability exposure for manufacturers sourcing stamped housings from Asian metalworking zones.
- Stovetop Popper:Manual agitation over external heat sources appeals to outdoor enthusiasts and off-grid users prioritizing portability over automation.
- Microwave Popper:Silicone or collapsible polymer vessels target dormitory and office environments where electrical outlet access is limited.
Volume placements concentrate in Electric Popper configurations; the faster expansion belongs to Air Popper variants as streaming subscription density pulls health-positioned appliances into living rooms.
End User:
Cost tier stratification separates price-sensitive residential purchasers from commercial operators amortizing equipment across high-throughput concession rushes.
- Household:Individual and family units purchasing through appliance retail corridors and e-commerce platforms represent the baseline demand pool for compact countertop designs.
- Commercial:Multi-location operators and institutional foodservice buyers specify NSF-certified kettles with field-serviceable components to minimize downtime across distributed sites.
- Movie Theaters:Cinema circuits negotiate direct service contracts with manufacturers for large-batch kettle systems featuring calibrated thermostat feedback loops. Ohio foundry clusters supply cast aluminum and stainless steel kettle assemblies sustaining North American theater infrastructure.
- Snack Shops:Independent concession operators favor medium-batch electric units balancing throughput against footprint constraints in limited retail spaces.
Margin capture peaks in Movie Theater supply relationships; the steepest expansion trajectory is emerging in Snack Shops as street food and specialty retail formats proliferate.
Technology:
Maturity gradients separate established heating modalities from precision induction systems commanding premium positioning.
- Hot Air:Forced convection without conductive surface contact dominates health-positioned segments. REACH Annex XVII solder restrictions are accelerating laser-welded joint migration in Guangdong assembly lines producing these units.
- Electric Heating:Resistive coil elements with integrated stirring define the mass-market standard. China's GB standard thermal cutoff requirements impose four-to-six-month retesting cycles that delay product launches for export-manufactured units.
- Induction:Precision temperature calibration eliminates hot-spot scorching in premium residential units. Scandinavian buyers specify these systems to reduce unpopped kernel waste.
- Manual:Unpowered agitation over external heat sources serves camping and emergency preparedness applications with minimal component complexity.
Production volumes anchor in Electric Heating platforms; Induction configurations are climbing the fastest as smart home integration converges with kitchen appliance ecosystems.
Capacity:
Customer type determines batch size specifications, with volume buyers optimizing units per hour and residential users prioritizing storage footprint.
- Small Batch:One-to-four-serving capacities target single-person households and dormitory environments. France's repairability index mandates are creating differentiation for modular, field-serviceable designs in this tier.
- Medium Batch:Four-to-eight-serving outputs balance family use against countertop space constraints. These units dominate German appliance retail corridor placements.
- Large Batch:Eight-to-sixteen-serving capacities serve light commercial duty in office break rooms and small concession operations.
- Extra Large Batch:Theater-grade kettles sustain throughput during peak concession rushes through continuous feed mechanisms and rapid recovery heating elements.
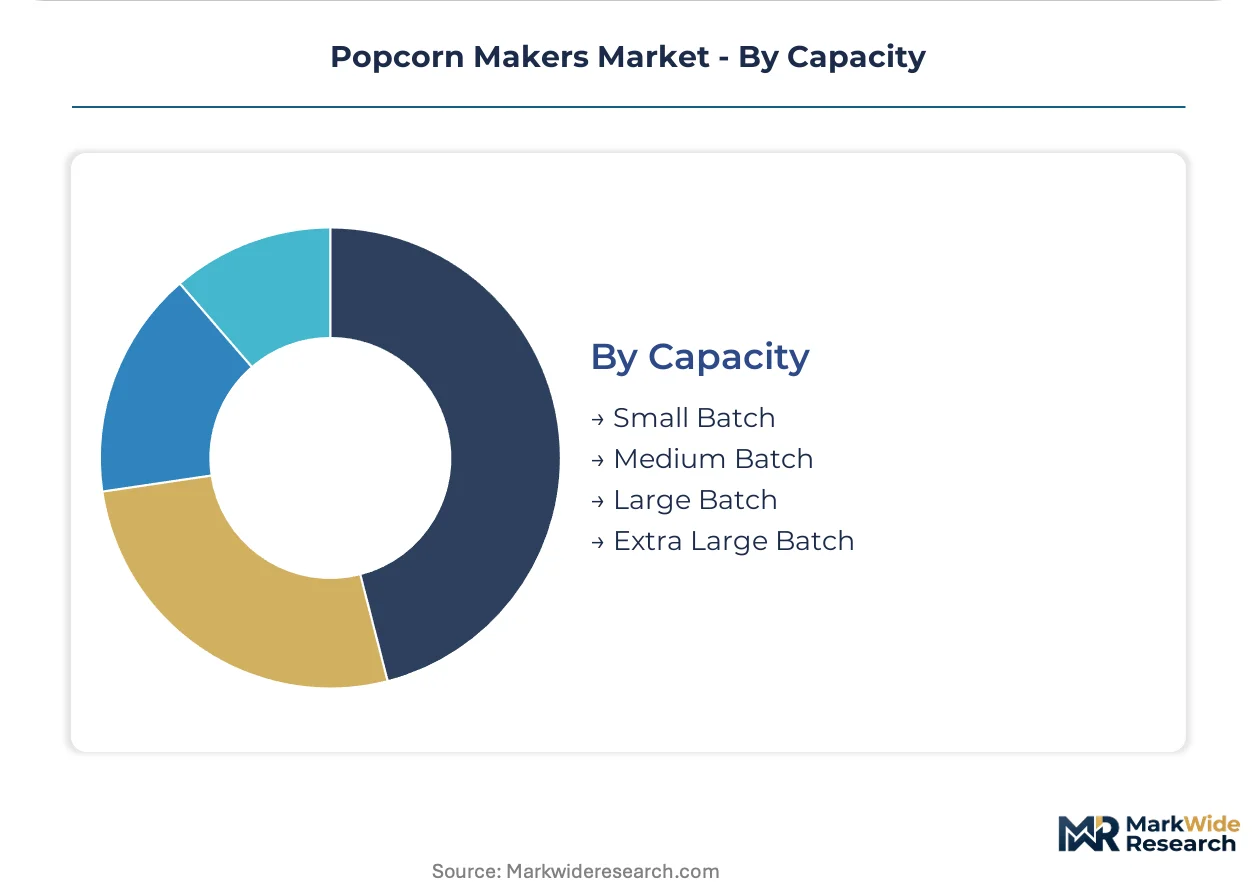
Shipment volumes concentrate in Medium Batch specifications; Large Batch units are gaining share fastest as hybrid home-entertainment and light-commercial use cases proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ohio Enterprise Zone program and similar state-level incentives have concentrated commercial kettle foundries in the Midwestern United States, while Germany's appliance retail corridors and China's export manufacturing zones anchor distinct regional supply configurations.
United States
Streaming subscription density and home theater investment are pulling air poppers into suburban households across the Pacific Northwest and Texas metros. The US Consumer Product Safety Commission enforces electrical cord and heating-element safety standards that shape product liability exposure for domestic manufacturers. Ohio's foundry cluster supplies cast aluminum and stainless steel kettle assemblies sustaining North American theater infrastructure through direct service contracts.
Germany
Health-positioned buyers in Bavaria and North Rhine-Westphalia are specifying fat-free air poppers as streaming penetration replicates theater-style snacking environments in living rooms. The EU's Ecodesign Directive is pressing manufacturers toward lower-wattage heating elements with mandatory energy-label placement. Appliance retail corridors in Munich and Cologne concentrate demand for mid-tier electric units with integrated stirring mechanisms.
China
Contract manufacturers in Guangdong and Zhejiang provinces are retooling assembly lines for laser-welded stainless steel joints to meet REACH Annex XVII solder restrictions. China's GB standards for household electrical appliances impose thermal cutoff requirements that delay export product launches by four-to-six months. Shenzhen and Dongguan metalworking zones supply stamped housings for mass-market electric poppers bound for North American and European distribution.
India
Organized retail corridors in Mumbai and Bangalore remain underpenetrated for electric poppers relative to microwave penetration rates, creating whitespace for appliance brands. The Bureau of Indian Standards sets baseline electrical safety requirements for imported household appliances. Maharashtra and Karnataka state industrial policies are attracting component assembly operations to serve domestic demand growth.
France
Repairability index mandates under extended producer responsibility schemes are creating competitive differentiation for modular, field-serviceable popcorn maker designs. ANSM and CNIL oversight extends to connected appliance data handling as smart home integration converges with kitchen ecosystems. The Île-de-France region concentrates premium residential demand for precision induction heating systems that eliminate hot-spot scorching.
Popcorn Makers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with household appliance brands dominating retail shelf space while foundry-integrated producers capture commercial theater supply relationships. The vendor base organizes into three tiers: premium residential specialists, mass-market volume players, and commercial-grade kettle fabricators. Dominant competitive moves include backward integration into foundry operations to control casting costs and geographic expansion through direct service contracts with cinema circuits.
Among Ohio-based foundry-integrated producers, Gold Medal Products and Cretors exemplify the commercial-grade archetype through captive kettle-casting capacity and theater circuit relationships. Presto occupies a position within the mass-market tier, competing on price through Asian metalworking zone sourcing for stamped housings. These three anchors illustrate how supply chain configuration and end-use specialization stratify competitive positioning across residential and commercial duty cycles.
| Leading Market Players |
|---|
| Gold Medal Products |
| Cretors |
| Nostalgia Electrics |
| Great Northern Popcorn |
| Presto |
| Paragon-Manufactured Fun |
| West Bend |
| Hamilton Beach Brands |
| Jarden Consumer Solutions |
| Others |
Value Network & Pricing Analysis
Stainless steel feedstock costs originating from Indonesian nickel ore processing cascade through Guangdong assembly lines into three-tier pricing structures across premium, standard, and economy levels of popcorn maker tiers. Contract manufacturers absorbing REACH Annex XVII compliance burdens pass laser-welding conversion costs downstream, compressing margins on mid-tier electric units while Ohio foundry-integrated producers maintain pricing power through captive kettle-casting capacity.
Pricing Analysis
Short lead-time premiums attach to theater-grade kettle assemblies sourced from Ohio foundries serving cinema circuits with calibrated thermostat requirements. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with NSF-certified commercial units commanding substantial premiums over stamped-housing residential models. Pricing pressure stems from nickel price volatility tied to Indonesian ore export policies, squeezing mid-tier stainless steel configurations. Household buyers through mass retail channels exhibit highest price sensitivity, while institutional operators prioritize throughput reliability over unit cost.
Supply Chain Analysis
Skilled metalworker availability in Shenzhen and Dongguan zones sustains stamped housing production for mass-market electric poppers bound for North American distribution. Manufacturing concentrates in China, the United States, and Germany, with raw material dependencies spanning Indonesian nickel ore, Midwestern aluminum casting feedstock, and German thermostat component assemblies. Single-source vulnerability concentrates in calibrated heating element supply from two German component suppliers. Distribution runs through appliance retail corridors in Munich and Cologne, direct service contracts with cinema circuits, and e-commerce platforms penetrating suburban US households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Ecodesign Directive wattage caps function as a cost-of-compliance barrier that favors incumbent manufacturers with established thermal architecture redesign capabilities and foundry retooling relationships. Compliant players capture extended warranty terms and energy-label placement advantages that emerging entrants struggle to replicate without capital-intensive platform redevelopment.
For Market Incumbents: To counter nickel price volatility compressing mid-tier margins, pursue backward integration into Ohio foundry relationships or captive stainless steel sourcing agreements with Indonesian ore processors. Prioritize modular platform designs spanning regulatory zones to amortize die-casting tooling costs across unified production runs rather than fragmenting across region-specific specifications. For New Entrants and Emerging Players: Health-positioned buyers in Germany's appliance retail corridors represent an underserved archetype seeking fat-free air popper configurations with integrated smart home compatibility. White-space targets include India's underpenetrated organized retail corridors in Mumbai and Bangalore relative to microwave penetration rates, and Scandinavian demand for precision induction heating systems. A direct-to-consumer refurbishment channel strategy bypasses established retail slotting fees while capturing aftermarket revenue concentration. For Investors and Strategic Acquirers: Theater operators shifting expectations toward manufacturer-managed parts availability rather than third-party repair networks is the leading indicator that aftermarket revenue concentration with original equipment makers will deepen. Long-term viability favors foundry-integrated producers with direct cinema circuit service contracts over stamped-housing assemblers dependent on Asian metalworking zone sourcing. Monitor REACH Annex XVII expansion scope as the inflection signal for accelerated assembly line conversion requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive kettle-casting capacity insulates Gold Medal Products and Cretors from nickel price volatility and secures theater supply relationships. |
| Modular Platform Standardization | Unified thermal architectures spanning EU Ecodesign wattage caps and US CPSC standards reduce per-unit fixed costs from fragmented tooling. |
| Smart Home Integration Partnership | Voice-activation modules converging with kitchen appliance ecosystems capture premium positioning among health-positioned Scandinavian buyers. |
| Direct-to-Consumer Refurbishment Channel | Manufacturer-managed parts availability concentrates aftermarket revenue and compresses independent service organization margins in theater operator relationships. |
| Laser-Welding Assembly Line Conversion | REACH Annex XVII solder restriction compliance in Guangdong and Zhejiang contract manufacturers accelerates joint migration and extends warranty terms. |
Research Methodology
Independent corroboration across primary interviews with appliance brand managers, foundry operations directors, cinema circuit procurement officers, and retail category buyers, combined with secondary validation through US CPSC safety filings, EU Ecodesign Directive implementation documents, and customs trade data, underwrites the qualitative findings. Bottom-up demand modeling from household penetration rates and theater concession equipment replacement cycles triangulates against top-down market sizing from manufacturer shipment disclosures and foundry capacity utilization reports.
Historical reference periods anchoring the projection horizon include pre-pandemic baseline theater attendance patterns, streaming subscription density inflection points, and REACH regulatory phase-in timelines. The analytical framework segments by product type, end user, technology, and capacity tier across the modeling period, with CAGRs derived from regression analysis of correlated demand drivers including home entertainment investment and health-positioned food preparation trends. Industry-specific inputs incorporate nickel price volatility indices and German thermostat component supplier concentration metrics.
Revisions become necessary when Indonesian ore export policy shifts, EU Ecodesign Directive expansion to additional appliance categories, or theater circuit consolidation altering direct service contract structures materialize. Forecasts reflect documented assumptions regarding streaming penetration saturation levels and REACH Annex XVII enforcement consistency. Material deviation in named triggers warrants pause and re-evaluation of thermal architecture investment timelines and foundry capacity allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market