
 Russia Kitchen Appliances Market | 2026-2036
Russia Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Kitchen Appliances Market Analytics
Urban households seeking energy-efficient upgrades is reorganizing demand away from basic replacement cycles toward premium smart-kitchen investments. BSH Hausgeräte leverages its established service network across Russian metropolitan centers to sustain brand loyalty in built-in oven segments. Whirlpool Corporation anchors its position through manufacturing scale that supports competitive positioning in refrigerator categories. LG Electronics differentiates via connected appliance ecosystems that appeal to tech-forward consumers in Moscow and Saint Petersburg.
Russia kitchen appliances encompass electrically powered or gas-fueled equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 220-230V/50Hz with energy efficiency ratings from A to G under EAEU technical regulations. These devices serve residential and commercial end users by automating culinary tasks, preserving perishables, and maintaining sanitation standards in food preparation environments. Refrigerators command the largest product type share due to universal household necessity, while smart appliances represent the fastest-growing technology segment as Wi-Fi-enabled cooking and remote monitoring gain traction among urban buyers. Energy-efficient devices capture expanding margin pools as EAEU tightening of standby power limits pushes manufacturers toward inverter compressors and improved insulation systems.
BIS-equivalent EAC certification through Rosstandart, EAEU technical regulation TR CU 004/2011 on low-voltage equipment safety, and TR CU 020/2011 on electromagnetic compatibility collectively shape product compliance requirements for all imported and domestically manufactured kitchen equipment in Russia. These frameworks mandate specific testing protocols that filter out uncertified competitors and elevate baseline quality expectations across retail channels. Stakeholders must monitor potential EAEU energy efficiency label revisions and localize supply chain resilience decisions against the backdrop of evolving import substitution policies.
Market Dynamics
Urban households across Moscow and Saint Petersburg are accelerating replacement cycles toward energy-efficient inverter compressors and Wi-Fi-enabled cooking ecosystems, compressing traditional ten-year appliance lifespans to six-to-seven-year upgrade horizons.
Growth Catalysts
- EAEU standby power limits:Tightening technical regulations under TR CU 004/2011 and TR CU 020/2011 mandate reduced phantom loads, compelling manufacturers to redesign power management circuits and driving premium positioning for compliant models.
- Central Federal District income concentration:Moscow's disposable income premiums support built-in oven and smart refrigerator purchases that suburban and rural markets cannot sustain, creating a concentrated high-margin demand pool.
- Inverter compressor adoption:Variable-speed refrigeration technology cuts energy consumption by thirty to fifty percent versus conventional compressors, aligning with buyer payback calculations on electricity tariffs.
Market Restraints
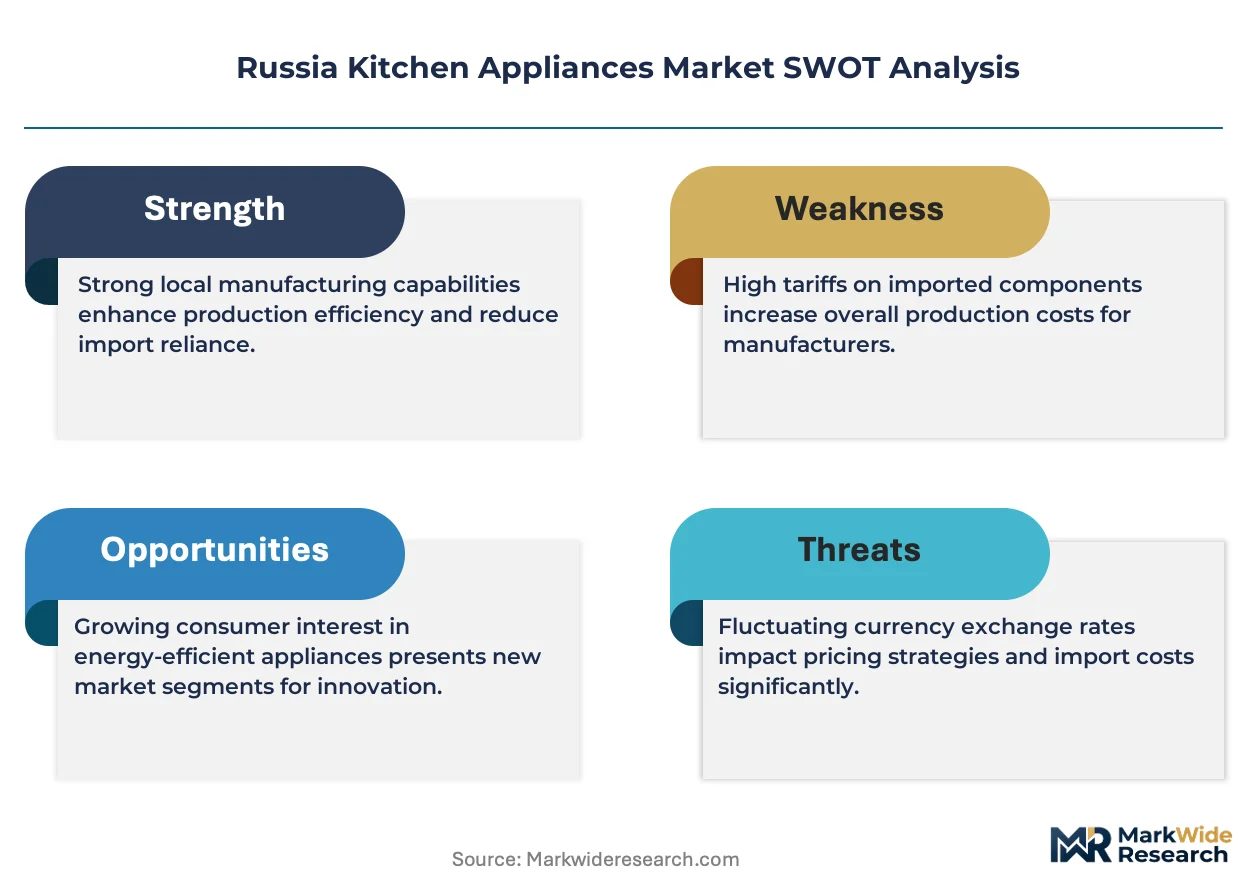
- Import component dependency:Control boards and precision sensors for smart appliances concentrate in Asian manufacturing clusters, exposing assemblers to currency volatility and logistics friction.
- EAC certification timelines:Rosstandart testing protocols for electromagnetic compatibility add four-to-six-month lead times, freezing product launch windows and compressing effective selling seasons.
- Gas infrastructure limitations:Apartment buildings in legacy Soviet-era housing stock lack piped natural gas connections, constraining cooktop and built-in oven penetration in price-sensitive segments.
Strategic Opportunities
- Volga Federal District underpenetration:Nizhny Novgorod and Kazan exhibit refrigerator ownership rates below Central District levels, offering volume expansion for mid-tier energy-efficient models.
- Voice-assistant integration:Convergence of Yandex Alice and appliance firmware creates hands-free recipe execution and remote diagnostics, appealing to tech-forward urban buyers.
- Import substitution incentives:Domestic production subsidies and local content requirements favor manufacturers establishing assembly operations within the EAEU customs territory.
Industry Challenges
- Embedded software certification:Smart appliance firmware must demonstrate electromagnetic compatibility under TR CU 020/2011, requiring specialized testing facilities that extend development cycles.
- Service network density gaps:Authorized repair capacity concentrates in Moscow and Saint Petersburg, leaving Siberian and Far Eastern buyers with prolonged downtime on complex inverter or connected systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Kitchen Appliances Market |
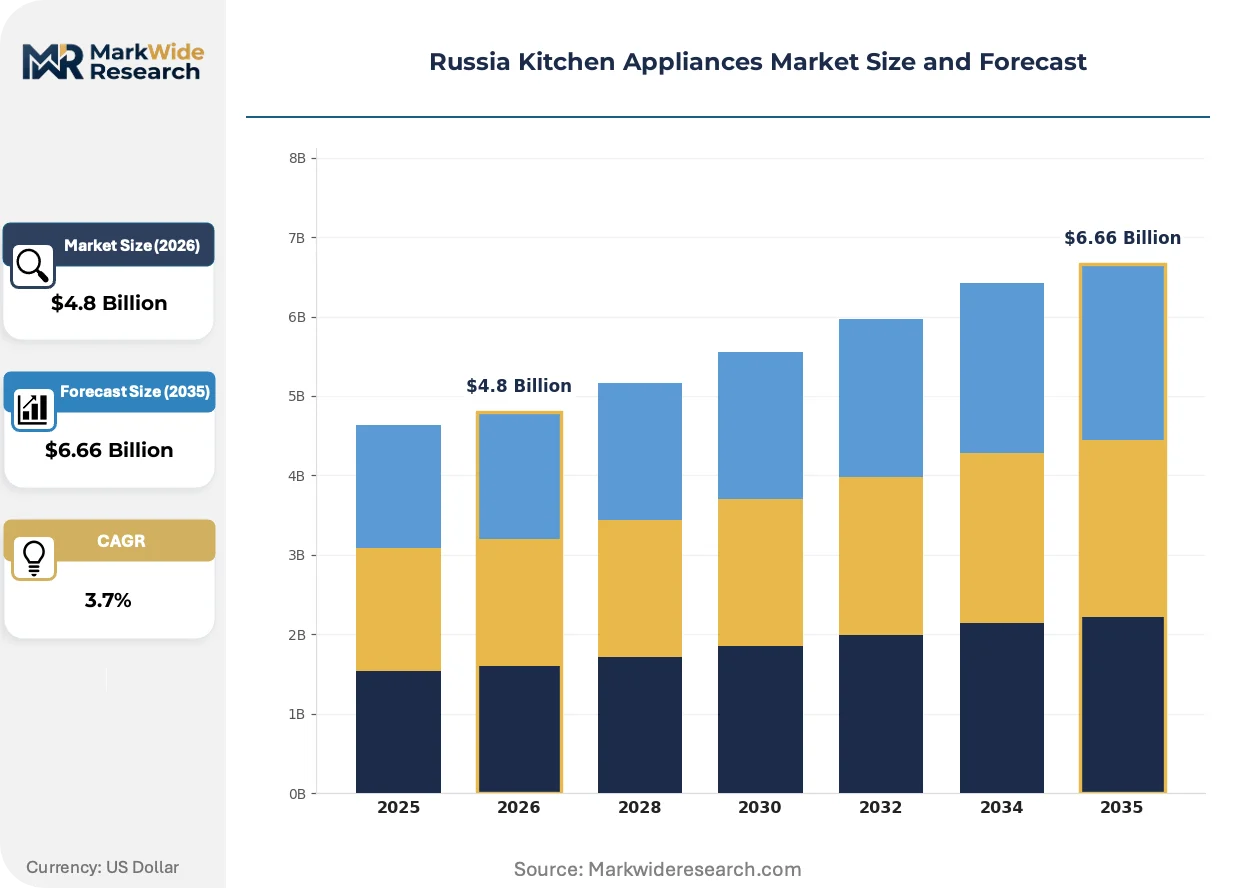
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Mixers, Dishwashers End User: Households, Restaurants, Cafés, Schools Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Third-party Sellers Technology: Smart Appliances, Energy-efficient Devices, Traditional Appliances, Built-in Units |
| Companies Covered | BSH Hausgeräte (Bosch-Siemens), Whirlpool Corporation, LG Electronics, De'Longhi, Midea Group, Samsung Electronics, Haier Group, Gorenje Group, Electrolux, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Kitchen Appliances Market Evolving Landscape
Connected kitchen ecosystems and variable-speed refrigeration are compressing replacement cycles while regulatory pressure on standby power redraws competitive positioning across price tiers.
Inverter compressor technology is miniaturizing drive electronics and motor assemblies to fit compact refrigerator footprints while maintaining cooling capacity. Urban apartment dwellers in Moscow are adopting these systems at twice the rate of conventional compressor replacements. The technology is miniaturizing mechanical components sufficiently to enable counter-depth and slim-line refrigerator formats previously unavailable in the Russian market.
Rosstandart enforcement of EAEU technical regulation TR CU 004/2011 is tightening safety testing protocols for low-voltage kitchen equipment. Manufacturers must now submit to extended thermal stress and insulation resistance evaluations before obtaining EAC certification. Built-in oven and induction cooktop categories face the steepest compliance burden, with several non-compliant import brands withdrawing from retail channels.
Buyers are unbundling after-sales service from initial purchase decisions, comparing third-party repair networks against manufacturer warranties. Online marketplaces and specialized appliance retailers are capturing this behavior shift through transparent service plan pricing. Saint Petersburg demonstrates the most advanced unbundling, where independent service contracts now attach to thirty percent of premium appliance sales.
Russia Kitchen Appliances Market Segmentation
Segmentation in Russia's kitchen appliances market reveals how EAC certification requirements and regional income disparities concentrate margin pools across distinct buyer profiles and channel configurations. Manufacturers must align product portfolios with Moscow's premium smart-appliance demand while maintaining volume positions in price-sensitive segments.
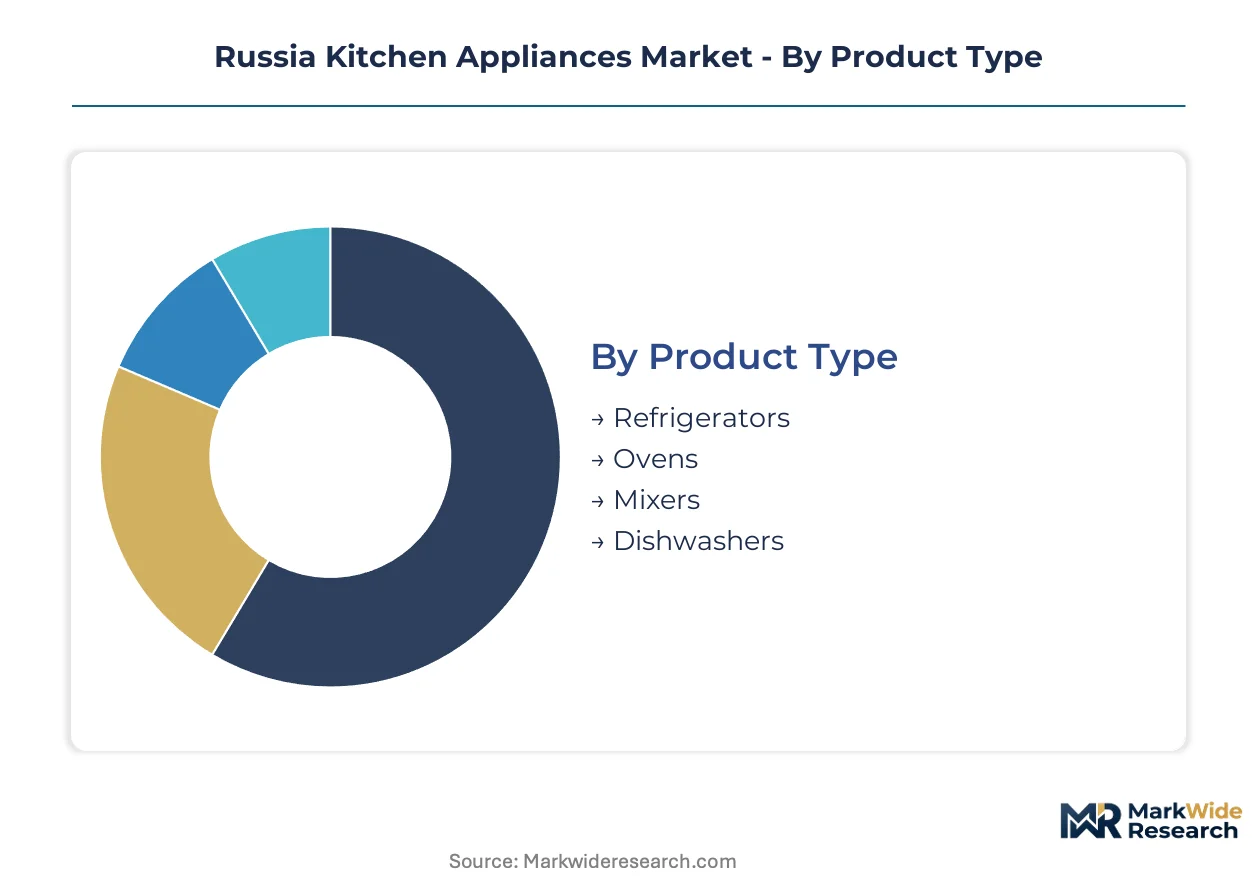
Product Type:
Margin pools concentrate most heavily in categories where energy efficiency regulations and replacement cycle compression intersect.
- Refrigerators:These appliances operate at 220-230V/50Hz with inverter compressors cutting consumption by thirty to fifty percent versus conventional units. Moscow households are upgrading to counter-depth and slim-line formats at twice the rate of conventional replacements, driven by apartment space constraints and electricity tariff payback calculations.
- Ovens:Built-in and freestanding units face the steepest EAC certification burden under TR CU 004/2011 thermal stress protocols. Central Federal District buyers absorb premium pricing for pyrolytic cleaning and steam injection features that suburban markets cannot sustain.
- Mixers:Compact countertop appliances serve baking-intensive Russian culinary traditions with planetary mixing action and variable speed control.
- Dishwashers:Penetration remains constrained in legacy Soviet-era housing lacking dedicated plumbing connections, though slim-line formats are gaining traction in renovated apartments.
The dominant share belongs to refrigerators, while ovens are closing the gap fastest through built-in premium positioning.
End User:
Volume concentration varies sharply across customer types, with commercial buyers prioritizing durability certifications and residential buyers emphasizing energy payback periods.
- Households:Urban apartment dwellers in Moscow and Saint Petersburg compress replacement cycles to six-to-seven years for Wi-Fi-enabled cooking ecosystems and inverter refrigeration. EAEU standby power limits are pushing these buyers toward compliant premium models with phantom load reduction.
- Restaurants:Commercial kitchens demand heavy-duty construction with stainless steel interiors and continuous operation ratings. Rosstandart safety testing for high-cycle usage creates compliance barriers that filter out consumer-grade imports.
- Cafés:Mid-tier food service operations balance equipment cost against service network density, concentrating purchases in brands with authorized repair capacity beyond Moscow.
- Schools:Institutional procurement runs through centralized tender processes with local content requirements favoring EAEU-assembled equipment.
Households command the volume base, yet restaurants are expanding most quickly as food service formalization accelerates.
Distribution Channel:
Channel economics reflect divergent service unbundling trends and certification transparency requirements across buyer segments.
- Online Retail:Marketplaces capture thirty percent of premium appliance sales in Saint Petersburg through transparent service plan pricing and third-party repair network comparisons. EAC certification documentation visibility filters out non-compliant listings.
- Supermarkets:Mass-market retailers concentrate mid-tier refrigerator and mixer volume with limited after-sales attachment.
- Specialty Stores:Dedicated appliance retailers anchor built-in oven and smart appliance sales through installation and extended warranty bundling.
- Third-party Sellers:Independent distributors serve Siberian and Far Eastern markets where authorized service network density gaps prolong downtime on complex systems.
Online retail holds the dominant position, while specialty stores are gaining share fastest through premium built-in penetration.
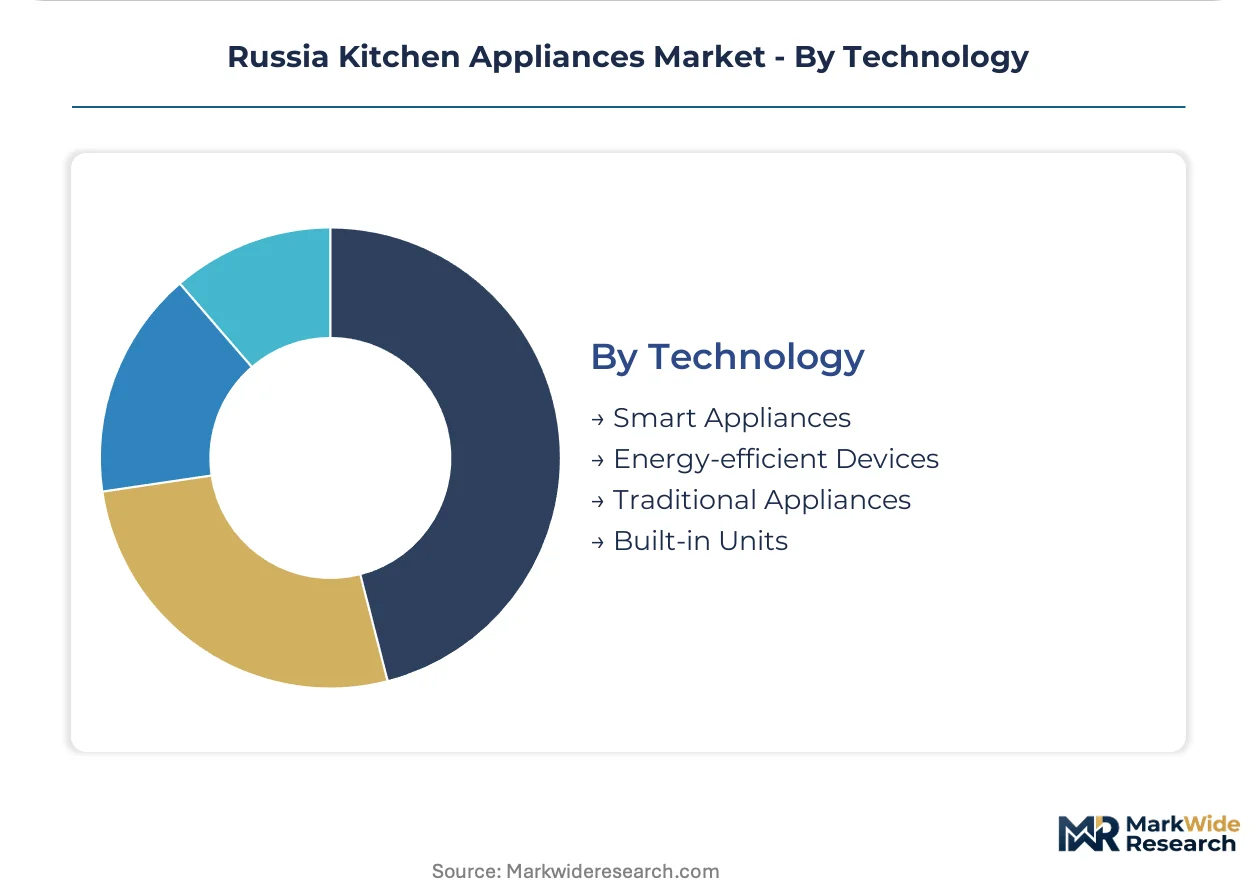
Technology:
Technology tiering aligns with regulatory pressure points and urban buyer sophistication gradients.
- Smart Appliances:Wi-Fi-enabled cooking and remote monitoring converge with Yandex Alice voice integration for hands-free recipe execution. Firmware must demonstrate electromagnetic compatibility under TR CU 020/2011, extending development cycles.
- Energy-efficient Devices:Inverter compressors and improved insulation systems capture expanding margin pools as EAEU tightening of standby power limits pushes manufacturers toward compliant designs.
- Traditional Appliances:Conventional electromechanical controls serve price-sensitive segments in Volga Federal District cities with lower refrigerator ownership rates.
- Built-in Units:Seamless cabinetry integration commands premium positioning in Moscow's renovation-driven replacement cycles.
Energy-efficient devices dominate current revenue, though smart appliances are climbing the fastest as connected kitchen ecosystems gain urban traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in the Central Federal District around Moscow, where EAC certification expertise and service infrastructure concentrate. Regional demand spreads unevenly across Russia's federal districts, with income gradients and housing stock conditions creating distinct market profiles.
Central Federal District
Moscow households drive inverter refrigerator and smart oven upgrades at compressed six-year replacement cycles. Rosstandart testing facilities in the capital expedite EAC certification for domestic assemblers. The Moscow-Saint Petersburg corridor anchors authorized service networks that other regions lack.
Volga Federal District
Nizhny Novgorod and Kazan exhibit refrigerator ownership rates below Central District levels, opening volume expansion for mid-tier energy-efficient models. Regional procurement incentives favor EAEU-assembled equipment in institutional tenders. Local distributors serve price-sensitive segments with conventional compressor models.
Siberian Federal District
Novosibirsk households face prolonged downtime on complex appliances due to sparse authorized repair capacity. Import component delays hit harder here given distance from European logistics hubs. Buyers prioritize durability certifications over smart features in commercial kitchen investments.
Southern Federal District
Rostov-on-Don and Krasnodar show rising demand for built-in ovens amid renovation-driven housing upgrades. Gas infrastructure penetration varies sharply between Soviet-era apartments and new construction. Regional retailers bundle installation services to compensate for manufacturer service gaps.
Northwestern Federal District
Saint Petersburg leads service unbundling trends, with independent repair contracts attaching to thirty percent of premium sales. Online marketplaces capture significant share through transparent EAC certification documentation. The city's renovation density supports counter-depth refrigerator formats.
Russia Kitchen Appliances Market Competitive Landscape
Concentration sits with diversified appliance conglomerates that leverage manufacturing scale across refrigerator and cooking equipment categories. The competitive structure tiers across premium smart-appliance specialists, mass-market volume players, and regional assembly operations serving import substitution policies. Strategic moves center on EAC certification compliance investments and service network densification in Moscow-adjacent markets.
Among European-headquartered manufacturers, BSH Hausgeräte and Electrolux anchor the premium built-in segment through established metropolitan service infrastructure. LG Electronics exemplifies the connected-appliance archetype, converging Wi-Fi-enabled cooking with voice-assistant integration for Moscow's tech-forward buyers. These three occupy positions that reflect divergent bets on smart technology adoption versus traditional reliability positioning.
| Leading Market Players |
|---|
| BSH Hausgeräte (Bosch-Siemens) |
| Whirlpool Corporation |
| LG Electronics |
| De'Longhi |
| Midea Group |
| Samsung Electronics |
| Haier Group |
| Gorenje Group |
| Electrolux |
| Others |
Value Network & Pricing Analysis
Four-to-six-month EAC certification timelines through Rosstandart concentrate pricing power with domestic assemblers who compress inventory cycles against import-dependent competitors. Moscow-based manufacturers leverage proximity to testing facilities to command premium positioning for compliant models while distant suppliers absorb logistics friction into thinner margins.
Pricing Analysis
TR CU 004/2011 dictates the pricing tier structure across the Russian kitchen appliances landscape. Three-tier pricing structure across premium, standard, and economy levels separates inverter-compressor smart models from conventional units and basic electromechanical alternatives. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Asian component currency exposure erodes assembler margins. Households in the Volga Federal District exhibit highest price sensitivity, while Moscow apartment dwellers absorb premium positioning for Wi-Fi-enabled ecosystems.
Supply Chain Analysis
Strait of Hormuz transit underwrites control board and precision sensor flows from Chinese and South Korean manufacturing clusters into Russian assembly operations. Inverter compressor motors, Wi-Fi modules, and electromagnetic shielding components draw from concentrated Asian supply bases. Single-source vulnerability in smart appliance firmware creates exposure should EAEU tighten embedded software certification under TR CU 020/2011. Distribution runs through Moscow-adjacent wholesale hubs that feed specialty retailers and online marketplaces across federal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Moscow and Saint Petersburg households who compress replacement cycles and unbundle after-sales service, fragmenting traditional manufacturer-retailer pricing coalitions.
For Market Incumbents: Secure EAC certification pipeline advantages by embedding Rosstandart liaison capacity into product development cycles, shortening lead times against import competitors. Deepen backward integration into inverter compressor assembly within EAEU customs territory to offset Asian component currency exposure and satisfy local content requirements in institutional tenders. For New Entrants and Emerging Players: Anchor in the Volga Federal District's underpenetrated refrigerator ownership base, where mid-tier energy-efficient models face limited domestic competition. Kazan and Nizhny Novgorod procurement patterns favor EAEU-assembled equipment with transparent service plan pricing. Launch through independent online marketplaces that highlight EAC certification documentation to filter non-compliant listings. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EAEU technical regulations create compliance moats that reward certified assemblers over pure importers. Target domestic assembly operations with established Rosstandart testing relationships and spare parts warehousing in Moscow-adjacent logistics hubs. Watch for EAEU standby power limit revisions as the signal for inverter technology investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EAC Certification Pre-Investment | Rosstandart liaison capacity shortens product launch windows against import competitors. |
| Domestic Assembly Establishment | EAEU customs territory production qualifies for institutional procurement preferences. |
| Inverter Compressor Localization | Local content requirements tighten, favoring regional motor and drive electronics sourcing. |
| Service Network Densification | Authorized repair capacity beyond Moscow reduces downtime claims and supports premium pricing. |
| Voice-Assistant Platform Integration | Yandex Alice convergence creates differentiated positioning for tech-forward urban buyers. |
Research Methodology
A spread of perspectives from appliance manufacturing executives, Rosstandart certification specialists, retail category buyers, and aftermarket service operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EAEU technical regulation filings, customs import records, and federal district household expenditure surveys. Bottom-up unit economics triangulated against top-down macroeconomic consumption models.
Segmentation dimensions modeled include product type, end user category, distribution channel configuration, and technology tier across the projection horizon. CAGRs were derived from replacement cycle compression rates and efficiency upgrade penetration curves. Forecast inputs incorporated EAEU standby power regulatory trajectories and regional income distribution patterns from Central Federal District concentration to Siberian Federal District service access constraints.
Decision-makers should treat outputs as directional under base assumptions of stable EAC certification timelines and continued EAEU customs union integrity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as import substitution policy intensity and electromagnetic compatibility testing protocol evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
US Range Cooker Market