
 Cotton Candy Maker Market | 2026-2036
Cotton Candy Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Candy Maker Market Outlook
Chinese OEM production clusters is restructuring global supply availability for cotton candy makers, shifting component sourcing toward consolidated metal fabrication hubs. Gold Medal Products Co. leverages its century-long brand equity to dominate the North American carnival and concession channel. Nostalgia anchors the home-use segment through nostalgic design aesthetics and broad retail distribution. Paragon competes on commercial-grade durability, sustaining placement in high-throughput amusement park environments.
A cotton candy maker is an electromechanical or gas-powered food preparation device that heats and centrifugally extrudes granulated sugar through a perforated spinning head, typically operating at rotational speeds between 3,000 and 3,600 RPM to produce fine sugar filaments. The machine's primary commercial purpose is enabling on-demand confection production for concession stands, entertainment venues, and rental event services. Commercial machines command the largest installed base due to continuous duty cycles and stainless steel construction, while portable battery-operated units represent the fastest-growing configuration as outdoor event planners seek untethered operation. Electric power sources dominate volume shipments, though gas-powered models retain share in remote fairground settings lacking reliable grid access.
The US FDA governs food contact surfaces and material safety for sugar-processing equipment, while OSHA standards address thermal hazard exposure in commercial kitchen environments; both frameworks elevate compliance costs for entry-tier manufacturers. CE marking requirements under EU machinery directives constrain European market access for uncertified imports, filtering the competitive landscape toward established exporters. Stakeholders must monitor evolving energy efficiency regulations and battery safety certifications as electrification trends reshape product development priorities across all price tiers.
Market Dynamics
Electrification of commercial food service equipment is compressing replacement cycles for gas-powered cotton candy makers, as concessionaires face stricter energy efficiency mandates and rising fuel cost volatility. This structural pivot toward electric-powered stainless steel units is reshaping procurement patterns across carnival circuits and amusement park operators.
Growth Catalysts
- State Fair Circuit Expansion:Seasonal event density in the United States sustains replacement demand for high-throughput commercial units, with regional fair associations standardizing on electric-powered equipment to meet municipal emissions guidelines.
- REACH Compliance Tiering:European food contact material standards under ECHA frameworks are filtering uncertified imports, creating protected market access for CE-marked manufacturers with validated stainless steel formulations.
- Battery Chemistry Advances:Lithium-ion power systems are enabling untethered operation for outdoor event planners, eliminating generator dependency for remote fairground deployments lacking grid infrastructure.
Market Restraints
- Granulated Sugar Price Volatility:Input cost swings for refined sucrose compress concessionaire margins, forcing equipment amortization periods to stretch beyond typical depreciation schedules.
- Guangdong Fabrication Cluster Concentration:Component sourcing dependence on consolidated Chinese metalworking hubs exposes lead time vulnerability during regional logistics disruptions.
- Thermal Efficiency Ceilings:Centrifugal heating mechanisms face fundamental energy conversion limits that constrain further operational cost reductions for high-duty-cycle commercial users.
Strategic Opportunities
- India Untapped Event Infrastructure:Urban festival culture expansion in Mumbai and Delhi creates first-mover positioning for portable electric units compliant with BIS electrical safety certifications.
- IRA Clean Energy Credits:US commercial kitchen electrification incentives subsidize electric cotton candy maker procurement for concession operators upgrading from propane-powered legacy equipment.
- Direct-to-Venue Distribution:Bypassing traditional rental intermediaries, manufacturers are establishing direct service contracts with regional amusement park chains for integrated maintenance and consumable supply.
Industry Challenges
- Certification Timeline Compression:CE marking and FDA food contact surface approvals require 8-14 month validation cycles that delay product launches for modified heating element designs.
- Electromechanical Technician Scarcity:Maintenance networks for high-RPM centrifugal motors remain thin outside major US metropolitan corridors, extending equipment downtime for remote fairground operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Candy Maker Market |
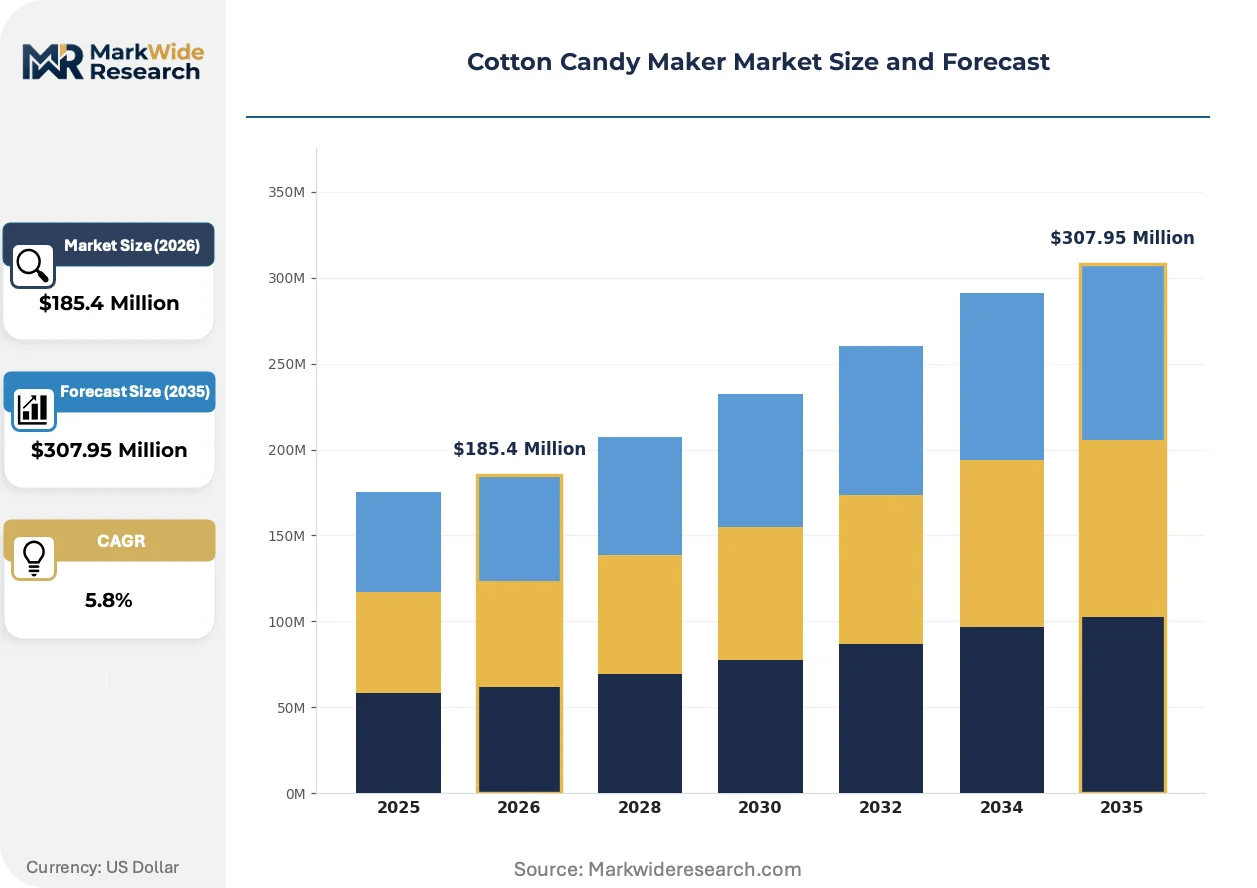
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Machines, Commercial Machines, Portable Machines, Industrial Machines End User: Households, Event Planners, Amusement Parks, Food Vendors Power Source: Electric, Manual, Battery-operated, Gas-powered Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Gold Medal Products Co., Nostalgia, Great Northern Popcorn Company, Paragon, Cretors, Vivo, Clevr, Olde Midway, Bella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Candy Maker Market Strategic Shifts
Operational autonomy and regulatory compliance are converging to reshape cotton candy maker design priorities, with manufacturers racing to integrate portable power systems while satisfying tightening food safety and energy efficiency frameworks across multiple jurisdictions.
Brushless DC motor technology is decentralizing equipment placement possibilities for outdoor event specialists. These compact drive systems enable battery-powered operation at rotational speeds matching commercial grid-tied units. Festival operators in Texas and Florida are adopting cordless configurations for parade routes and temporary midway setups where generator noise restrictions apply.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free cooling system adoption for integrated candy floss storage compartments. This industrial consequence eliminates compressor maintenance burdens while reducing equipment weight for mobile concessionaires. German and French rental fleet operators are retrofitting existing carts with thermoelectric cooling modules to maintain compliance without full equipment replacement.
Rental model unbundling is fragmenting traditional equipment procurement patterns. Amusement venues are shifting from capital purchase toward short-term lease arrangements with bundled consumable supply and technical support. This behavioral pivot is most visible in California and Florida theme park clusters, where seasonal staffing variability favors operational expense classification over fixed asset ownership.
Cotton Candy Maker Market Segmentation
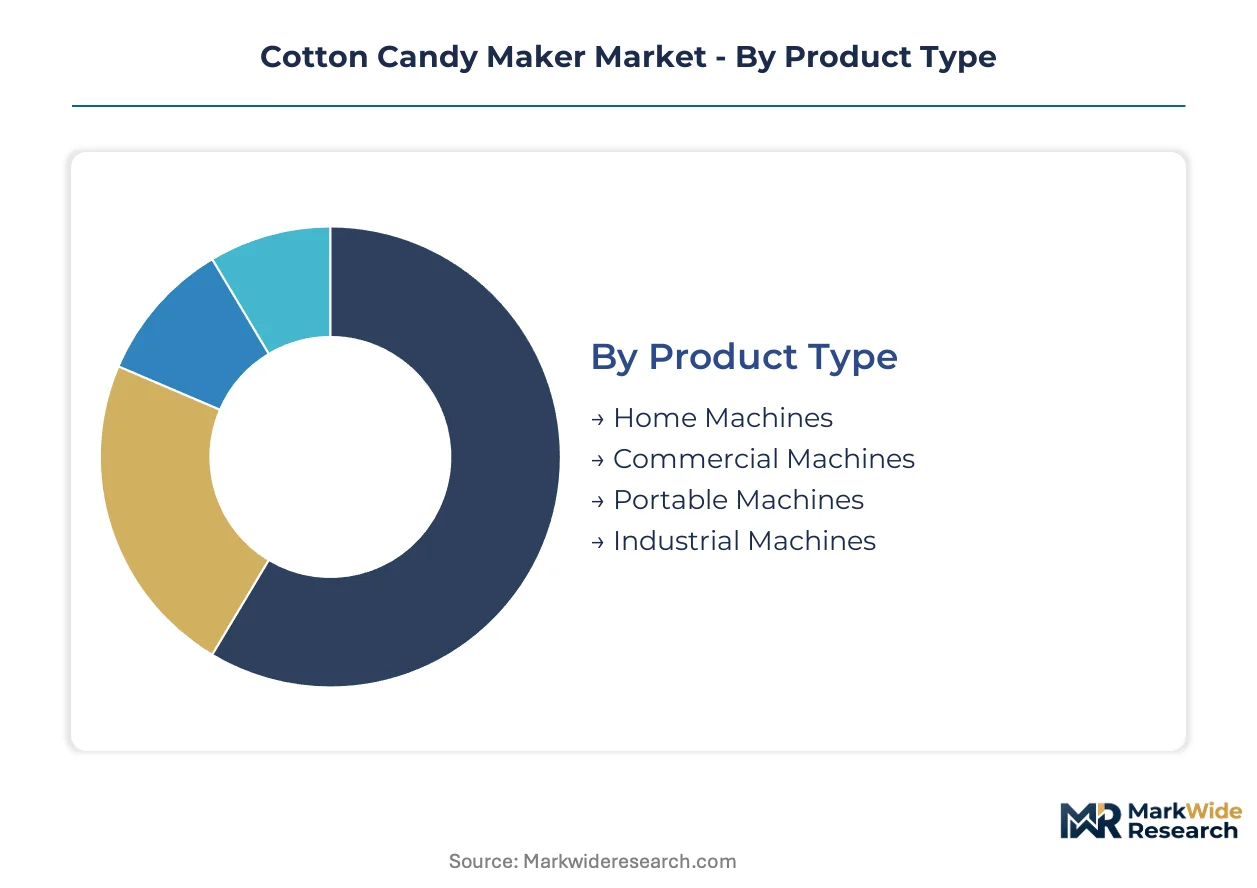
Segmentation in cotton candy equipment reveals divergent engineering priorities between intermittent home use and continuous commercial duty cycles. Procurement patterns split sharply across power source preferences and venue-specific durability requirements.
Product Type:
Rotational speed tolerance and heating element wattage define the technical axis separating product tiers.
- Commercial Machines:Stainless steel construction supports 3,000-3,600 RPM operation with continuous duty cycles. Amusement parks in Texas and Florida drive replacement demand for electric-powered units meeting municipal emissions guidelines.
- Portable Machines:Lithium-ion battery systems enable untethered operation at rotational speeds matching grid-tied equivalents. Outdoor event planners in California and Florida adopt cordless configurations for parade routes where generator noise restrictions apply.
- Home Machines:Compact plastic housings with intermittent-duty motors target countertop use.
- Industrial Machines:High-throughput units with reinforced spinning heads serve centralized production facilities.
Commercial machines lead on scale; portable machines lead on momentum.
End User:
Volume throughput requirements and operating environment harshness shape customer procurement behavior.
- Amusement Parks:Seasonal high-throughput operations demand corrosion-resistant construction and rapid sugar filament production. Regional fair circuits in the United States sustain replacement cycles as associations standardize on electric equipment.
- Event Planners:Mobile deployment needs prioritize lightweight transport and quick setup protocols. Rental fleet operators in Germany and France retrofit carts with thermoelectric cooling modules to maintain EU F-Gas Regulation compliance.
- Food Vendors:Concession stand operators balance equipment durability against capital constraints.
- Households:Occasional use patterns favor lower price points and nostalgic design aesthetics.
Amusement parks dominate installed base; event planners show steepest expansion trajectory.
Power Source:
Energy infrastructure availability and regulatory compliance costs determine power selection across deployment contexts.
- Electric:Brushless DC motor technology delivers grid-comparable performance with lower maintenance burdens. Stricter energy efficiency mandates in US food service equipment compress replacement cycles for legacy gas-powered units.
- Battery-operated:Advanced lithium-ion chemistry eliminates generator dependency for remote fairground deployments lacking grid infrastructure.
- Gas-powered:Propane units retain share in rural carnival settings with unreliable electrical access.
- Manual:Hand-cranked mechanisms serve educational demonstrations and emergency backup scenarios.
Electric systems command volume leadership; battery-operated configurations gain share fastest.
Distribution Channel:
Customer technical support needs and purchase urgency dictate channel preference patterns.
- Online Retail:Direct-to-consumer platforms enable specification comparison and rapid delivery for replacement parts. Home-use segment concentration drives platform investment in nostalgic product presentation.
- Specialty Stores:Concession equipment dealers provide hands-on demonstration and maintenance training. Commercial buyers in Texas and Florida prioritize local service networks for high-RPM motor repair.
- Wholesale:Volume pricing supports rental fleet operators and regional amusement park chains.
- Supermarkets:Seasonal placement captures impulse purchases in home-use segment.
Online retail leads on transaction velocity; specialty stores lead on commercial account retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cotton candy maker production toward jurisdictions with streamlined certification pathways, while demand clusters persist in markets with entrenched carnival traditions and tightening energy efficiency mandates.
United States
State fair circuits in Texas and Florida sustain replacement demand for high-throughput electric units. OSHA thermal hazard standards and municipal emissions guidelines compress procurement timelines for gas-to-electric conversions. Regional fabrication hubs in the Midwest serve domestic concession equipment channels with shortened lead times.
Germany
Rental fleet operators retrofit existing carts with thermoelectric cooling modules to maintain EU F-Gas Regulation compliance. CE marking requirements under EU machinery directives filter uncertified imports, protecting domestic fabricators. Industrial clusters in North Rhine-Westphalia concentrate stainless steel component sourcing for European carnival supply chains.
China
Guangdong fabrication clusters dominate global component supply for cotton candy maker metal housings and spinning heads. GB standards and MIIT energy efficiency frameworks shape export-oriented production specifications. Shenzhen and Dongguan hubs are consolidating upstream metalworking capacity to capture economies of scale.
India
Urban festival expansion in Mumbai and Delhi creates positioning opportunities for portable electric units compliant with BIS electrical safety certifications. FSSAI food contact material standards are elevating compliance barriers for uncertified imports. Manufacturing activity concentrates in Gujarat and Maharashtra for domestic carnival and event rental channels.
France
Provence-Alpes-Côte d'Azur event planners adopt battery-operated configurations for outdoor deployments where generator noise restrictions apply. ECHA REACH compliance tiering filters non-validated stainless steel formulations from import channels. Lyon-based metal fabrication specialists serve regional concession equipment distributors with CE-marked assemblies.
Cotton Candy Maker Market Competitive Environment
United States producers anchor the premium-tier concession channel; Chinese fabricators hold volume leadership in component supply and entry-level equipment. The vendor base splits between century-established carnival specialists and agile OEM exporters. Two strategic archetypes dominate: brand-equity incumbents leveraging distribution lock-in, and scale-driven manufacturers capturing rental fleet procurement. Competitive moves center on direct-to-venue service contracting and backward integration into stainless steel component production.
Among North American incumbents, Gold Medal Products Co. exemplifies brand-equity consolidation through century-long carnival channel presence. Paragon occupies a position within the commercial-grade durability tier, anchoring high-throughput amusement park placements. Nostalgia represents the nostalgia-driven home-use archetype, capturing countertop segment demand through retail distribution density. These three companies collectively illustrate the market's tripartite segmentation across commercial, rental, and consumer tiers.
| Leading Market Players |
|---|
| Gold Medal Products Co. |
| Nostalgia |
| Great Northern Popcorn Company |
| Paragon |
| Cretors |
| Vivo |
| Clevr |
| Olde Midway |
| Bella |
| Others |
Value Chain & Pricing Dynamics
Metal fabrication specialists in Guangdong and Zhejiang provinces anchor global component supply, with labor-cost differentials stretching pricing-tier spreads between CE-certified premium units and uncertified economy imports.
Pricing Analysis
Distributor margin layers compress as rental fleet operators in Germany and France negotiate direct service contracts with manufacturers, bypassing traditional concession equipment dealers. Pricing stratifies across FDA-validated stainless steel formulations, CE-marked commercial units, and entry-level aluminum constructions lacking certification. Cost compression in the battery-operated portable tier is intensifying because lithium-ion cell procurement faces commodity volatility. Event planners and mobile concessionaires exhibit highest price sensitivity, while amusement park chains with standardized procurement protocols absorb premium tiering for durability guarantees.
Supply Chain Analysis
Dual-sourcing requirements from major US carnival operators mandate multi-supplier qualification for spinning head assemblies and heating elements, forcing diversification beyond single Guangdong hubs. Component supply concentrates in China, India, and Germany, with stainless steel housings drawing from consolidated metalworking clusters and brushless DC motors sourcing from Shenzhen electronics corridors. Sucrose supply volatility and regional logistics disruptions present persistent vulnerability. Distribution runs through specialty concession equipment dealers for commercial accounts, while online retail platforms serve home-use replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with US IRA clean energy credits and EU F-Gas Regulation phase-downs accelerating equipment replacement cycles across concession channels.
For Market Incumbents: Deploy backward integration into stainless steel spinning head production to capture margin compression from Guangdong fabrication cluster concentration. Deepen direct-to-venue service contracts with regional amusement park chains to lock out rental intermediaries. Counter battery-operated portable entrants by anchoring high-throughput electric units in municipal emissions-compliant fair circuits. For New Entrants and Emerging Players: Mobile event planners in India's urban festival corridors represent the most penetrable buyer archetype, with BIS certification gaps creating first-mover positioning for compliant portable electric units. Target California and Florida theme park clusters with short-term lease arrangements bundling consumable supply. Pursue rental model unbundling as the primary go-to-market angle, converting capital-averse seasonal operators from purchase to operational expense classification. For Investors and Strategic Acquirers: Concession equipment distributors with captive service networks are the most active acquirer in this space, consolidating regional maintenance capabilities. Five-to-ten year viability hinges on electrification compliance positioning rather than gas-powered legacy exposure. Acquisition target archetype: mid-scale manufacturers with validated CE marking and FDA food contact surface approvals. Monitor municipal emissions guideline adoption velocity across US state fair circuits as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Component Production | Captures margin from Guangdong cluster concentration while securing FDA-validated material traceability. |
| Direct-to-Venue Service Contracting | Bypasses rental intermediaries in Texas and Florida amusement park clusters with bundled maintenance. |
| Battery Chemistry Platform Development | Enables lithium-ion configurations for California parade routes facing generator noise restrictions. |
| CE Marking and FDA Dual Certification Investment | Unlocks protected market access under ECHA REACH and OSHA thermal hazard frameworks. |
| Rental Model Unbundling | Converts seasonal California and Florida operators from capital purchase to operational expense classification. |
Study Parameters
Direct dialogue with concession equipment procurement managers, carnival association technical directors, amusement park maintenance heads, and rental fleet operators in Germany and France grounded qualitative assessment. Secondary validation drew from FDA food contact surface filings, ECHA REACH substance databases, US state fair association equipment standards, and customs trade records for stainless steel component flows. Bottom-up equipment shipment tallies triangulated against top-down carnival and amusement venue expenditure estimates.
Bottom-up modeling segmented volume and value across product type, end user, power source, and distribution channel dimensions, with municipal emissions compliance tiering as an industry-specific overlay. CAGRs derived from replacement cycle analysis for gas-to-electric conversions and penetration trajectory for battery-operated configurations across the projection horizon. Forecast inputs incorporated IRA credit uptake assumptions and EU F-Gas Regulation retrofit timelines.
Underlying measurement precision varies by segment; commercial machine replacement cycles carry tighter precision than nascent battery-operated portable adoption curves. Forecasts reflect assumptions on electrification subsidy continuity and certification timeline compression. Deviation in Guangdong logistics reliability or lithium-ion cell supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market