
 South Korea Kitchen Appliances Market | 2026-2036
South Korea Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Kitchen Appliances Market Analytics
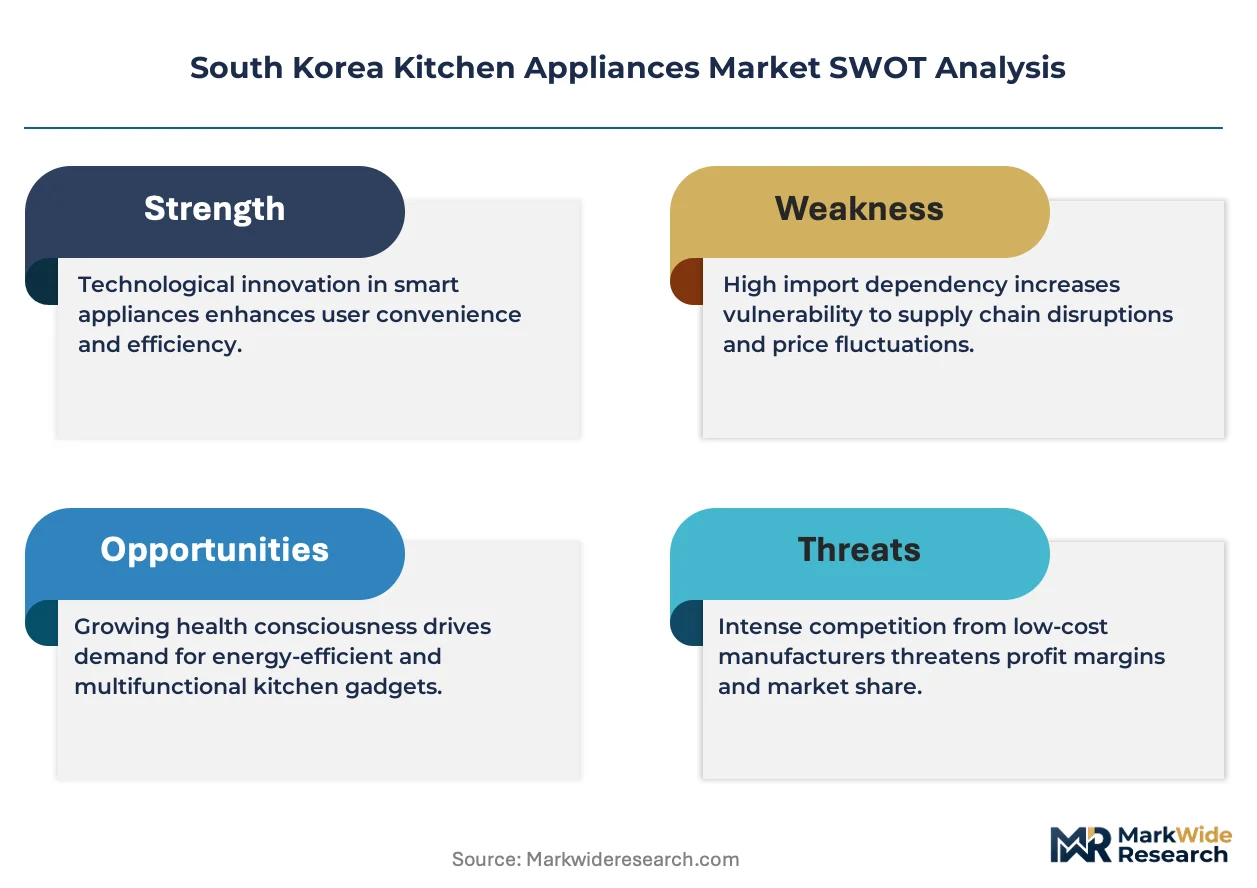
KC certification compliance is unwinding competitive access as smaller import brands face retesting costs. Samsung Electronics dominates domestic smart refrigerator development through in-house semiconductor production. LG Electronics leverages its Home Appliance & Air Solution division to sustain premium positioning in energy-efficient cooktops. Coway specializes in compact water and air purification adjacent kitchen systems, occupying a defensible niche in Seoul apartments.
South Korea kitchen appliances encompass electrically powered food preparation, preservation, and cooking equipment designed for residential and commercial environments, typically operating at 220V/60Hz with mandatory standby power limits below 1W for certified models. These systems serve primary functions of thermal processing, cold storage, and automated meal preparation across Korean culinary traditions. Smart Appliances technology leads value generation as IoT-enabled inventory management and voice-integrated cooking commands attract premium buyers, while Energy-Efficient Devices segment growth accelerates under tightening MEPS standards and consumer electricity cost sensitivity. Conventional Technology retains volume dominance in rural Gyeongsang and Jeolla provinces where replacement cycles extend beyond metropolitan patterns.
MFDS oversees food-contact material safety in appliance interiors, while KTL and KTC laboratories execute KC mark testing for electromagnetic compatibility and electrical safety. The Korea Energy Agency administers standby power regulations that disqualify non-compliant imports from e-commerce platforms. Stakeholders must monitor pending revisions to smart appliance cybersecurity standards and position procurement around modular component architectures that simplify certification updates.
Market Dynamics
Seoul's single-person household density is compressing appliance form factors while MFDS energy-efficiency mandates force semiconductor redesigns across refrigeration and induction cooktop categories.
Growth Catalysts
- MFDS standby power limits:Sub-1W certification requirements filter low-efficiency imports, creating protected shelf space for domestic OEMs with captive power management IC design.
- Busan high-rise residential pipeline:New construction permits in Haeundae and Marine City clusters specify built-in smart kitchen packages, pulling premium compact refrigeration and IoT-enabled cooktops.
- Induction coil miniaturization:Advanced ferrite core geometries enable 200mm-wide single-burner cooktops that fit Seoul studio apartment counter depths without ventilation duct retrofit.
Market Restraints
- Neodymium magnet cost volatility:Compressor motor permanent magnet pricing fluctuates with Chinese rare earth export quotas, squeezing margin on entry-tier refrigerator models.
- KC certification retesting burden:Electromagnetic compatibility laboratory capacity concentrates in KTL and KTC facilities, creating 8-12 week queue delays for import brands seeking mark renewal.
- Gas infrastructure persistence:Legacy LPG distribution networks in Gyeongsang rural municipalities slow induction cooktop substitution despite efficiency advantages.
Strategic Opportunities
- Jeolla province replacement wave:Aging refrigerator stock in Gwangju and Jeonju metropolitan zones exceeds 12-year average replacement cycles, creating volume pull for mid-tier energy-efficient models.
- Voice-integrated cooking commands:Naver Clova and Kakao i platform APIs enable hands-free recipe navigation, differentiating premium SKUs for Seoul's time-constrained professional demographic.
- Modular water purification attachments:Under-sink filtration modules that dock with refrigerator icemaker lines capture adjacent spending from Coway's established air purifier customer base.
Industry Challenges
- Embedded software cybersecurity certification:Pending KISA IoT security standards require firmware audit trails and over-the-air update architectures that legacy 8-bit microcontroller designs cannot accommodate.
- Appliance-as-a-service billing integration:Subscription revenue recognition systems demand ERP reconfiguration that mid-tier distributors lack technical staffing to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Kitchen Appliances Market |
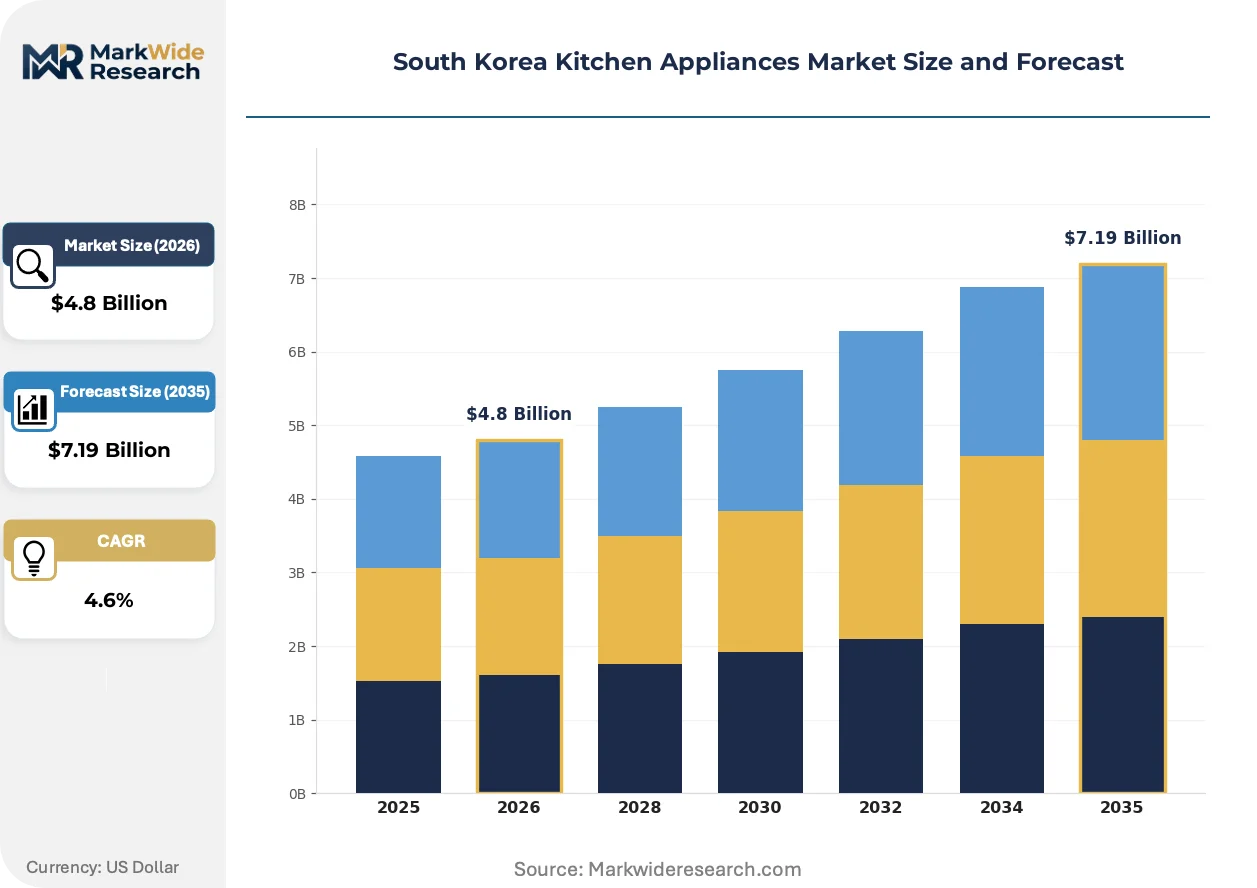
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Cooktops Technology: Smart Appliances, Energy-Efficient Devices, Induction Heating, Conventional Technology End User: Households, Restaurants, Cafes, Catering Services Sales Channel: Online Retail, Specialty Stores, Hypermarkets, Wholesale Distributors |
| Companies Covered | Cuckoo Electronics Co., Ltd., Panasonic Corp., LG Electronics Inc., Haier Group Corp., Whirlpool Corp., Samsung Electronics Co., Ltd., Coway Co., Ltd., Koninklijke Philips N.V., WINIA Electronics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Kitchen Appliances Market Evolving Landscape
IoT-enabled inventory management and voice-integrated cooking interfaces are compressing replacement cycles in Seoul's premium residential segment while forcing semiconductor architecture redesigns across the supplier base.
Inverter-driven linear compressors are supplanting conventional reciprocating designs in mid-tier and above refrigerator segments. Seoul's single-person households prioritize noise reduction and temperature stability for fermented food storage. The technology is compressing warranty claim rates and enabling 10-year compressor guarantees that lock in brand loyalty.
KC certification requirements for electromagnetic compatibility are tightening test protocols for Wi-Fi-enabled appliances. KTL laboratories now mandate conducted emissions testing across 2.4GHz and 5GHz bands for all smart kitchen devices. The regulation is forcing import brands to redesign antenna placement or exit the e-commerce channel entirely.
Direct-to-consumer online configuration tools are displacing traditional retail showroom selection for built-in appliance packages. Younger buyers in Busan and Incheon metropolitan zones customize finish materials and handle styles through brand apps before single-visit showroom confirmation. The channel shift is concentrating marketing spend on Naver and Kakao display advertising rather than distributor co-op programs.
South Korea Kitchen Appliances Market Segmentation
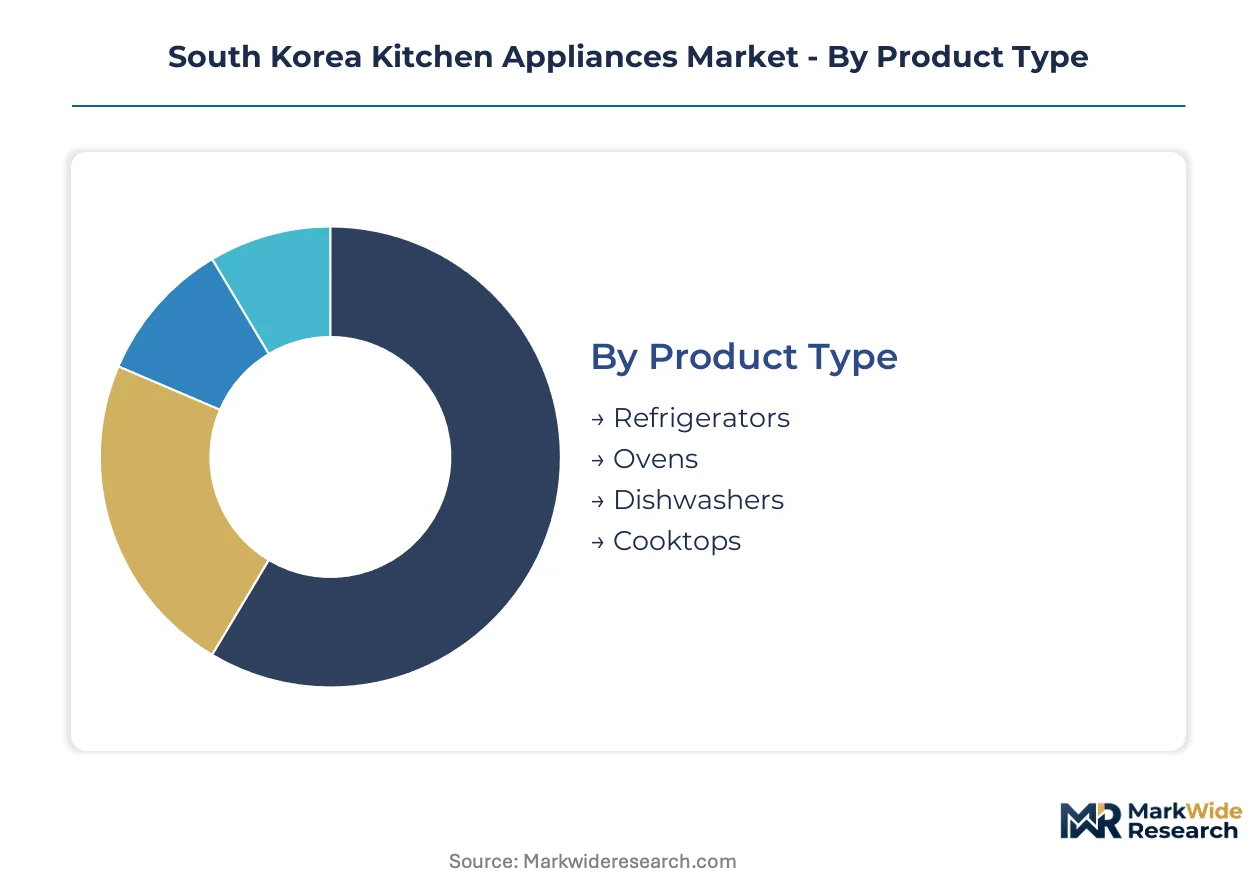
Segmentation in the South Korea kitchen appliances market reveals how MFDS certification tiers and Seoul's spatial constraints reshape competitive access. Each dimension exposes different pressure points: technology segments face substitution from adjacent categories, while channel dynamics reflect e-commerce platform consolidation under tightened standby power enforcement.
Product Type:
Induction cooktops exert substitution pressure on gas ranges as Seoul apartment ventilation standards tighten, compressing demand for traditional burner configurations across all segments.
- Refrigerators:Linear compressor systems with inverter-driven temperature zones address kimchi fermentation storage requirements. Seoul's single-person households pull compact 200-300L units into studio apartments, displacing full-size models. MFDS standby power limits below 1W filter non-compliant imports from Coupang and Naver Shopping channels.
- Cooktops:Induction coil designs with ferrite core miniaturization fit 600mm counter depths without duct retrofit. Busan high-rise specifications in Haeundae and Marine City clusters mandate built-in smart packages, accelerating induction substitution for legacy LPG infrastructure.
- Ovens:Convection and steam-combination units serve Korean baking trends and multi-function meal preparation.
- Dishwashers:Compact 6-8 place setting countertop models address Seoul's space-constrained kitchens where plumbing retrofit costs deter full-size installation.
Refrigerators anchor the volume base while cooktops gain share at the steepest rate.
Technology:
Cost tier stratification separates semiconductor-intensive designs from commodity electromechanical platforms, with premium tiers capturing Seoul's professional demographic.
- Smart Appliances:IoT-enabled inventory management and voice-integrated cooking commands through Naver Clova and Kakao i APIs attract premium buyers. KTL electromagnetic compatibility testing across 2.4GHz and 5GHz bands creates 8-12 week certification queues for Wi-Fi-enabled designs.
- Energy-Efficient Devices:MEPS-compliant refrigeration and induction systems qualify for Korea Energy Agency rebates. Semiconductor redesigns for sub-1W standby power favor domestic OEMs with captive power management IC production.
- Induction Heating:Advanced ferrite geometries enable single-burner 200mm widths for studio apartment deployment.
- Conventional Technology:Electromechanical controls and reciprocating compressors retain dominance in rural Gyeongsang and Jeolla provinces where replacement cycles exceed metropolitan patterns.
Conventional Technology retains volume leadership while Smart Appliances expand most quickly in Seoul and Busan premium residential segments.
End User:
Application concentration in high-rise residential shapes product specifications, with commercial segments demanding durability certifications absent from household tiers.
- Households:Single-person units in Seoul Capital Area drive compact form factors and noise-reduction priorities for fermented food storage. Direct-to-consumer online configuration tools displace showroom selection for built-in packages.
- Restaurants:High-duty-cycle induction and refrigeration systems require reinforced chassis designs for continuous operation.
- Cafes:Beverage-focused equipment configurations prioritize under-counter refrigeration and rapid-heating water systems.
- Catering Services:Mobile and event-deployable appliances demand 220V/60Hz compatibility with generator power sources.
Households dominate unit volume while Restaurants show the steepest specification upgrade trajectory.
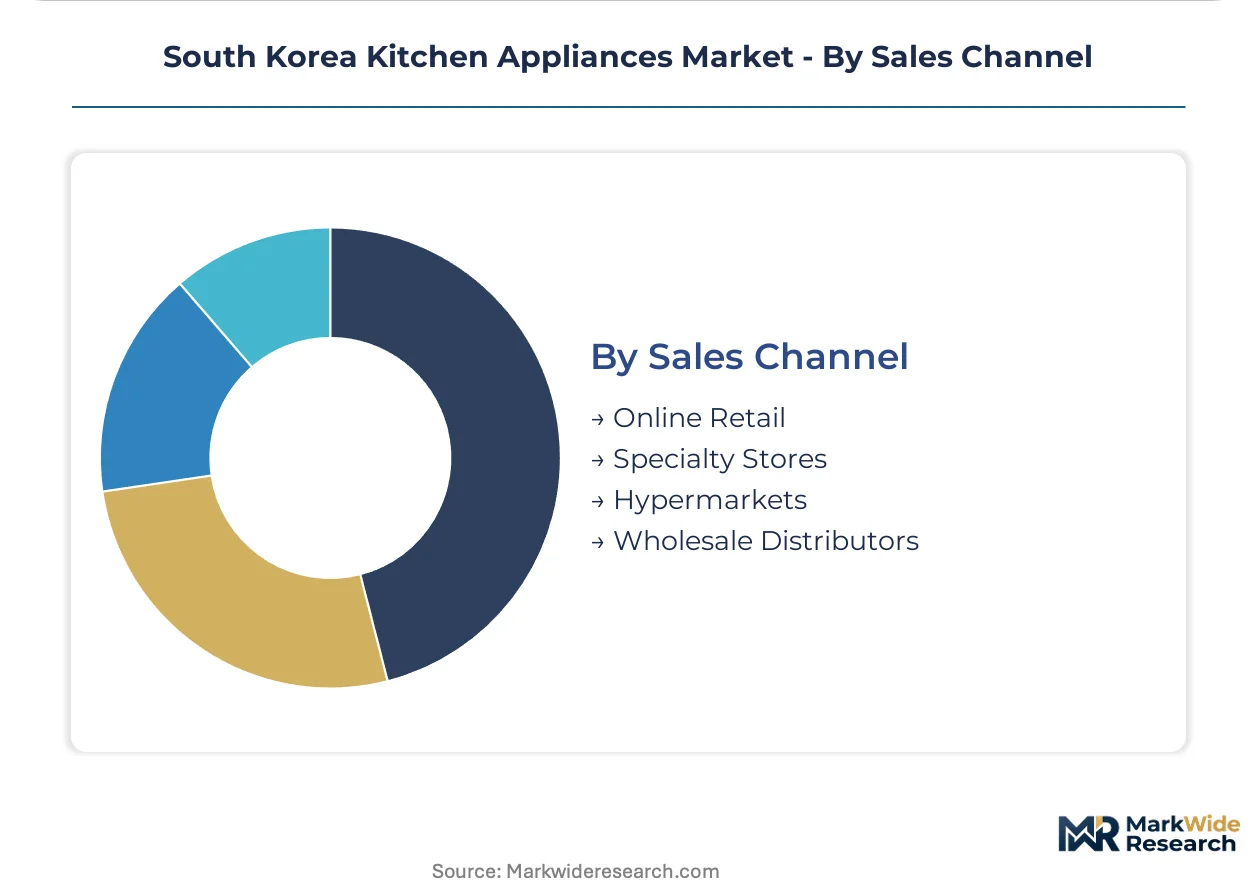
Sales Channel:
Geography-based channel concentration in Seoul metropolitan logistics hubs favors platforms with same-day delivery infrastructure for bulky appliance categories.
- Online Retail:Naver and Kakao display advertising concentrates marketing spend previously allocated to distributor co-op programs. Younger buyers in Busan and Incheon customize finishes through brand apps before single-visit showroom confirmation. KC certification documentation must display on product pages to avoid platform delisting.
- Specialty Stores:Built-in appliance package consultation and installation coordination services capture premium Seoul renovation projects.
- Hypermarkets:E-mart and Lotte Mart locations stock mid-tier replacement inventory for Jeolla province aging refrigerator stock.
- Wholesale Distributors:Regional logistics networks serve Gyeongsang rural municipalities where gas infrastructure persistence slows induction substitution.
Online Retail captures the steepest share expansion while Specialty Stores defend margin position in premium built-in segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-person professional households concentrate appliance demand in Seoul's high-rise residential clusters, while Busan's coastal development pipeline pulls premium built-in kitchen packages. Provincial replacement cycles in Jeolla and Gyeongsang regions lag metropolitan adoption patterns by four to six years.
Seoul Capital Area
Studio apartment proliferation in Gangnam and Mapo districts compresses refrigerator form factors below 300L. MFDS standby power regulations below 1W filter non-compliant imports from Coupang and Naver Shopping platforms. Samsung Electronics and LG Electronics anchor smart appliance development in Suwon and Seoul R&D clusters.
Busan-Ulsan
Haeundae and Marine City high-rise permits specify built-in smart kitchen packages with IoT-enabled cooktops. Korea Energy Agency rebates accelerate induction substitution for legacy LPG infrastructure in new construction. Coway maintains water purification system dominance through Ulsan manufacturing proximity.
Daegu-Gyeongbuk
Rural Gyeongsang municipalities retain gas range infrastructure that slows induction cooktop penetration despite efficiency advantages. KC certification laboratory capacity concentrates in KTL and KTC facilities, creating certification queue delays for import brands. Aging refrigerator stock exceeds twelve-year replacement cycles in Daegu metropolitan zones.
Daejeon-Sejong
Government complex relocation drives dual-income household formation with premium appliance purchasing power. Korea Energy Agency headquarters proximity accelerates MEPS rebate program administration for energy-efficient models. Compact dishwasher demand rises in Sejong apartment complexes with standardized kitchen dimensions.
Gwangju-Honam
Jeolla province refrigerator replacement wave targets mid-tier energy-efficient models as aging stock exceeds metropolitan replacement cycles. E-mart and Lotte Mart hypermarket channels serve volume demand outside Seoul logistics networks. Conventional electromechanical controls retain share in rural Honam districts where smart appliance connectivity infrastructure remains underdeveloped.
South Korea Kitchen Appliances Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive semiconductor production and specialized water purification specialists. Market structure concentrates around three archetypes: integrated appliance-electronics conglomerates with in-house power management IC design, compact system specialists occupying defensible urban niches, and import brands navigating KC certification bottlenecks. Dominant competitive moves include backward integration into compressor motor production and modular platform architectures that simplify firmware recertification.
Among integrated electronics conglomerates, Samsung Electronics Co., Ltd. and LG Electronics Inc. anchor premium smart appliance development through captive semiconductor supply chains. Coway Co., Ltd. exemplifies the compact system specialist archetype, occupying defensible positioning in Seoul apartment water and air purification adjacencies. Cuckoo Electronics Co., Ltd. sits within the domestic pressure-cooker and rice-cooking equipment tier, representing localized product-market fit expertise.
| Leading Market Players |
|---|
| Cuckoo Electronics Co., Ltd. |
| Panasonic Corp. |
| LG Electronics Inc. |
| Haier Group Corp. |
| Whirlpool Corp. |
| Samsung Electronics Co., Ltd. |
| Coway Co., Ltd. |
| Koninklijke Philips N.V. |
| WINIA Electronics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
KC certification requirements gate both supplier qualification and price stratification simultaneously, as electromagnetic compatibility testing concentrates in KTL and KTC laboratories while standby power compliance separates premium domestic OEMs from import brands facing retesting costs. This regulatory architecture compresses margins at the entry tier while insulating integrated conglomerates with captive semiconductor production.
Pricing Analysis
Cost-plus contracts with neodymium magnet indexation anchor compressor motor procurement, exposing refrigerator OEMs to Chinese rare earth export quota volatility. Three-tier pricing structure across premium smart appliances, MEPS-compliant mid-tier models, and conventional electromechanical units reflects certification grade and volume scale differentiation. Pricing pressure stems from KISA cybersecurity standards forcing firmware architecture redesigns. Rural Gyeongsang households exhibit highest price sensitivity, while Seoul single-person professionals absorb premium voice-integrated SKUs.
Supply Chain Analysis
KTL and KTC laboratory capacity chokepoints in Seoul and Busan metropolitan zones create 8-12 week certification queues that filter import brand market access. Semiconductor fabrication concentrates in South Korea and Taiwan, with power management ICs and inverter-driven linear compressor components drawing from captive domestic foundries. Single-source vulnerability runs through Chinese rare earth processing for permanent magnet motors. Distribution runs through Naver and Kakao platform logistics with same-day delivery infrastructure for bulky categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house power management IC design capability separates viable competitors from margin-compressed assemblers, with firmware audit trail architecture emerging as the critical skill gap as KISA standards tighten.
For Market Incumbents: Shield premium positioning by deepening backward integration into linear compressor motor production and accelerating modular platform architectures that simplify recertification cycles. Defend against Coway's adjacent water purification expansion by locking in refrigerator icemaker line docking standards. Channel control through direct-to-consumer configuration tools preserves margin against hypermarket price competition. For New Entrants and Emerging Players: Anchor in Jeolla province's aging refrigerator replacement wave, where twelve-year replacement cycles and E-mart hypermarket channel concentration create volume entry points without Seoul logistics infrastructure requirements. Target mid-tier energy-efficient models with MEPS rebate qualification. Pursue voice-integrated cooking command differentiation through Naver Clova API partnerships rather than proprietary platform builds. For Investors and Strategic Acquirers: Pending KISA IoT security standard implementation reshapes the acquisition landscape toward firmware audit-capable targets with over-the-air update architectures. Long-term viability favors modular component specialists over legacy 8-bit microcontroller assemblers. Watch KC certification queue duration as inflection indicator for import brand exit acceleration and domestic OEM share consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Firmware Architecture Investment | Enables rapid KISA cybersecurity recertification without full platform redesign. |
| Linear Compressor Backward Integration | Captures neodymium cost volatility margin while supporting ten-year warranty positioning. |
| Voice Platform API Partnership | Leverages Naver Clova and Kakao i installed base for hands-free recipe navigation differentiation. |
| Direct-to-Consumer Configuration Tool Launch | Displaces showroom-dependent selection with app-based customization and single-visit confirmation. |
| Under-Sink Purification Module Docking | Captures adjacent Coway customer spending through refrigerator icemaker line integration. |
Research Methodology
Cross-validation between primary interviews with appliance R&D directors, KC certification laboratory managers, and Korea Energy Agency rebate administrators anchors the qualitative findings against secondary validation from MFDS regulatory filings, Korea Energy Agency MEPS compliance databases, and Naver Shopping platform delisting records. Bottom-up shipment estimates from compressor motor suppliers and top-down household penetration models triangulate volume figures. Customs records trace neodymium magnet import flows and rare earth cost pass-through timing.
Sensitivity analysis across neodymium price volatility scenarios, KC certification queue duration assumptions, and KISA standard implementation timelines informs projection robustness. Segmentation modeling spans product type, technology tier, end-use application, and sales channel dimensions with regional granularity across Seoul Capital Area, Busan-Ulsan, and provincial clusters. CAGRs derive from replacement cycle compression in metropolitan zones and MEPS-driven substitution elasticity. Voice platform API adoption curves and smart appliance connectivity penetration anchor technology segment trajectories.
Decision-makers should treat outputs as directional under stable rare earth export quota and KISA standard implementation assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as cybersecurity certification timelines and induction infrastructure substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market