
 South Africa Kitchen Appliances Market | 2026-2036
South Africa Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Kitchen Appliances Market Analytics
Specialty retail and direct-to-consumer platforms is reshaping how kitchen appliances reach South African buyers. Defy Appliances leverages its domestic manufacturing footprint to sustain price competitiveness against imports. Samsung Electronics anchors premium positioning through smart connectivity features in its cooking product lines. Hisense South Africa competes aggressively on value-tier refrigeration and small appliance bundles.
South Africa kitchen appliances encompass electrically or manually powered devices designed for food preparation, cooking, storage, and cleaning, typically operating at 220-240V/50Hz with energy efficiency ratings measured in kilowatt-hours per cycle. These products serve residential households, commercial foodservice operations, and institutional catering facilities across formal and informal economic channels. The product type dimension shows ovens and microwaves capturing disproportionate margin pools as consumers prioritize built-in kitchen aesthetics in new housing developments. Technology segmentation reveals induction systems gaining share from traditional electric coils as load-shedding resilience becomes a decisive purchase criterion for South African buyers.
The National Regulator for Compulsory Specifications (NRCS) enforces safety and energy performance standards for electrical appliances sold in South Africa, while SABS certification marks remain prerequisites for retail listing at major chains. Municipal electricity tariff structures and Eskom's grid reliability challenges directly shape demand timing and product feature prioritization across all buyer segments. Stakeholders must monitor how distributed solar generation adoption alters the viable technology mix for cooking appliances in suburban and peri-urban installations.
Market Dynamics
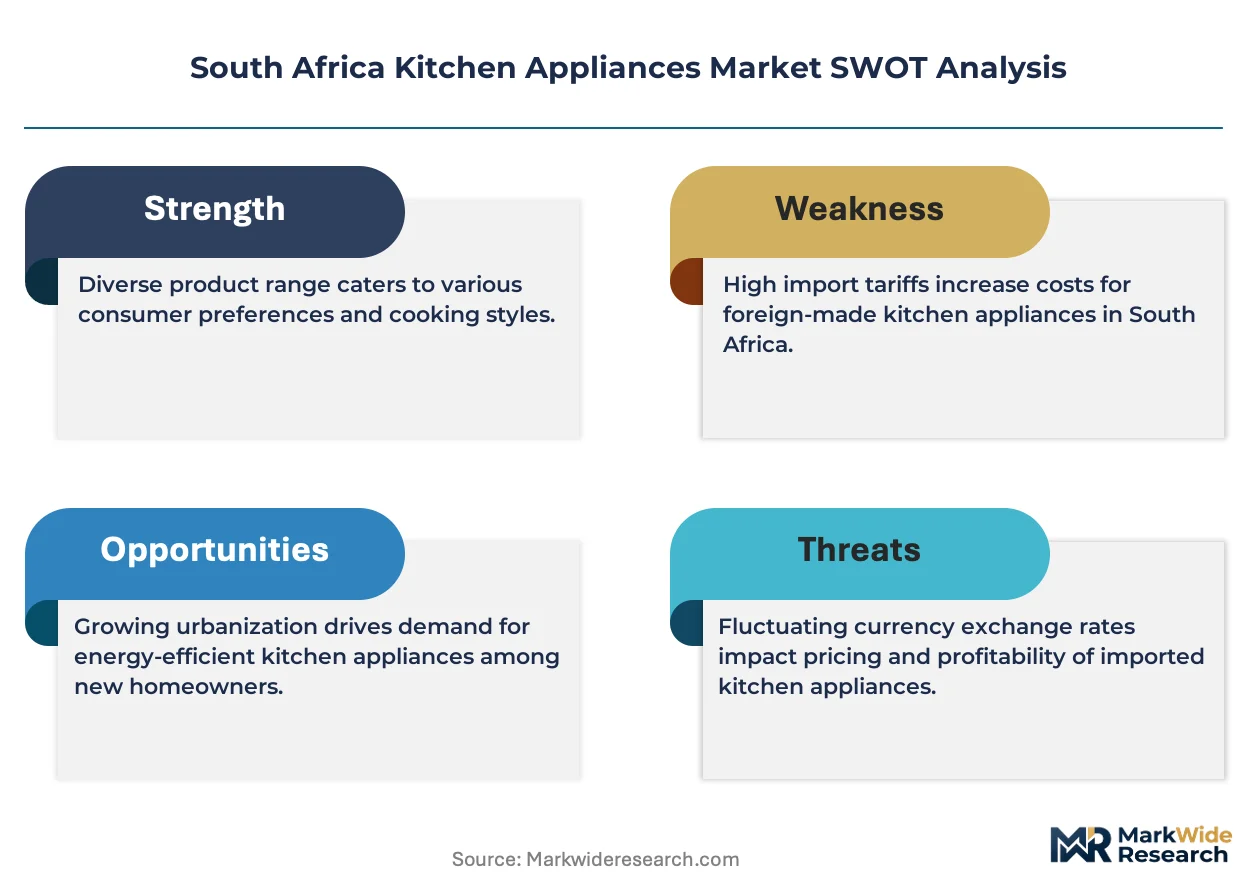
Load-shedding frequency is restructuring South African kitchen appliance demand, as Eskom's grid instability forces households toward induction and gas-hybrid systems that minimize cooking-time electricity draw. Municipal tariff escalation and SABS energy labeling mandates compound this technology pivot.
Growth Catalysts
- SABS Energy Efficiency Labeling:Mandatory kilowatt-hour disclosure at retail channels redirects consumer preference toward A-rated electric ovens and induction cooktops. Retail chains now prioritize certified inventory.
- Solar-Plus-Storage Adoption:Suburban households pairing rooftop PV with lithium battery banks expand viable addressable market for high-wattage electric cooking appliances previously incompatible with load-shedding schedules.
- Gauteng Housing Stock Expansion:Middle-income residential developments in Johannesburg and Pretoria prioritize built-in kitchen aesthetics, pulling premium appliance specifications into standard developer fit-outs.
Market Restraints
- Import Tariff Volatility:Rand depreciation against dollar-denominated component sourcing raises landed cost for semiconductor controllers and compressor motors, compressing distributor margins.
- Single-Grid Dependency:Eskom's centralized generation monopoly creates demand timing unpredictability, forcing inventory holding patterns that tie up working capital across wholesale channels.
- LPG Substitution Threat:Informal settlements and peri-urban households bypass electric infrastructure entirely, installing bottled gas cookers that eliminate grid-dependent appliance demand.
Strategic Opportunities
- Western Cape Solar Corridors:Stellenbosch and Paarl municipalities with highest residential PV penetration rates present concentrated demand for induction-compatible cookware bundles and smart load-management systems.
- Direct-to-Installer Channels:Solar EPC contractors represent underutilized appliance distribution path, capturing replacement-cycle decisions during home energy retrofits before retail consideration.
- NRCS Pre-Certification Streamlining:Expedited safety approval pathways for products already holding EU CE marks reduce time-to-market for import-dependent brands, compressing competitive response windows.
Industry Challenges
- Field Service Technician Scarcity:Induction inverter and smart connectivity repair capabilities concentrate in Johannesburg and Cape Town, leaving secondary cities with 14-day-plus resolution timelines that erode brand equity.
- Legacy Stock Clearance Friction:Traditional electric coil inventory accumulated pre-2023 resists price-clearing as consumer education around induction efficiency accelerates, straining distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Kitchen Appliances Market |
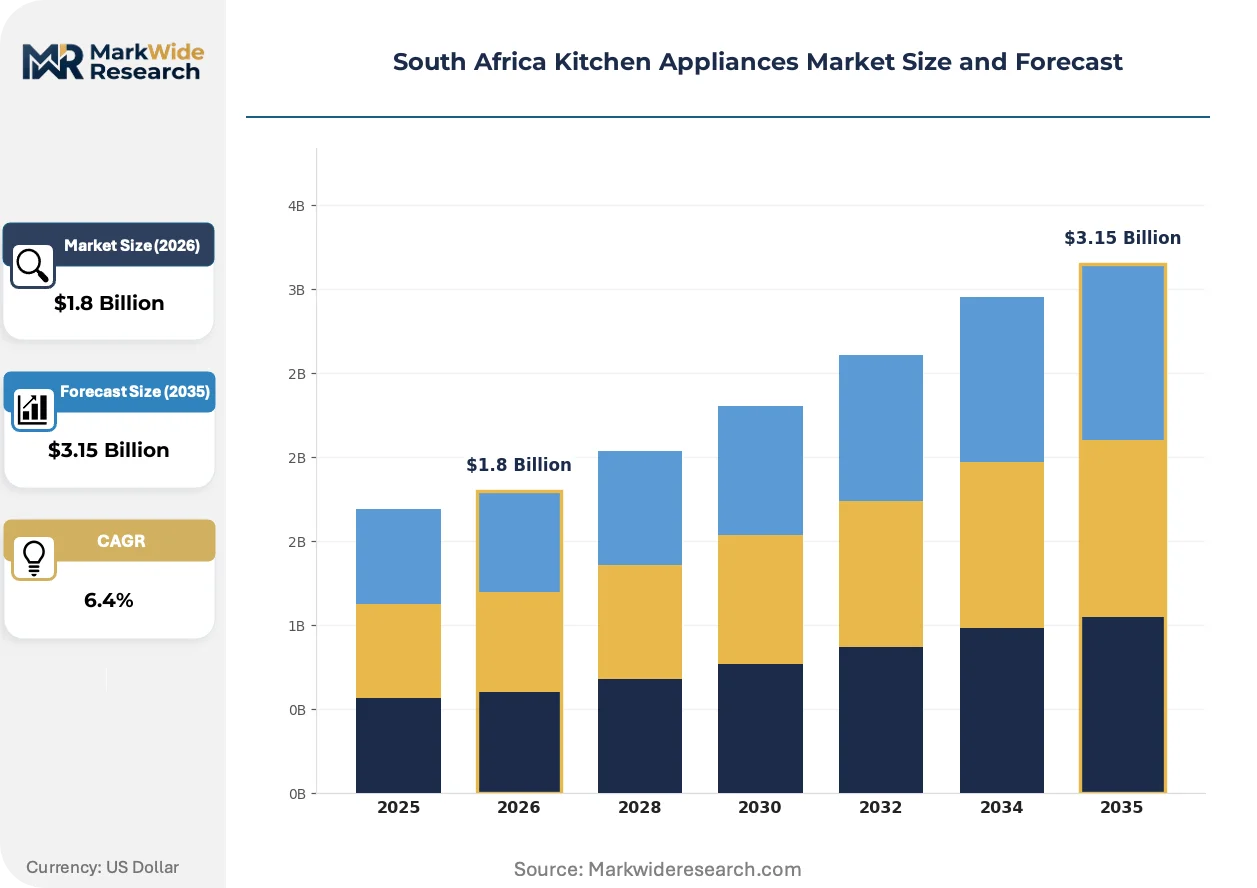
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microwave, Blender, Toaster, Oven Technology: Convection, Induction, Electric, Manual End User: Household, Restaurants, Catering Services, Hotels Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Defy Appliances, Samsung Electronics, LG Electronics, Hisense South Africa, Bosch Home Appliances SA, Haier, Siemens, Electrolux, Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Kitchen Appliances Market Evolving Landscape
Smart connectivity and distributed energy compatibility are redefining product specifications across South Africa's appliance channels. Manufacturers now engineer for off-grid resilience alongside conventional performance metrics.
Induction cooking technology is migrating from niche premium positioning toward mass-market standard equipment in new housing developments. Johannesburg-based developers now specify induction hobs as baseline in mid-market apartments, compressing electric coil market presence to replacement-only demand. This technology shift enables appliance-as-a-service financing models where energy savings offset monthly payments.
SABS certification alignment with IEC 60335 safety standards is tightening compliance timelines for imported cooking appliances. The National Regulator for Compulsory Specifications now mandates local electrical safety testing even for products holding EU CE marks, extending product registration cycles by eight to twelve weeks. Premium brands with established Johannesburg testing partnerships capture shelf space faster than direct-import competitors.
Buyer concentration in retail chains is fragmenting toward specialty kitchen studios and solar installer networks. Cape Town's southern suburbs exhibit strongest channel shift, where kitchen designers specify appliance packages before housing completion rather than post-occupancy retail selection. This pattern compresses traditional big-box retail influence in high-value postcodes.
South Africa Kitchen Appliances Market Segmentation
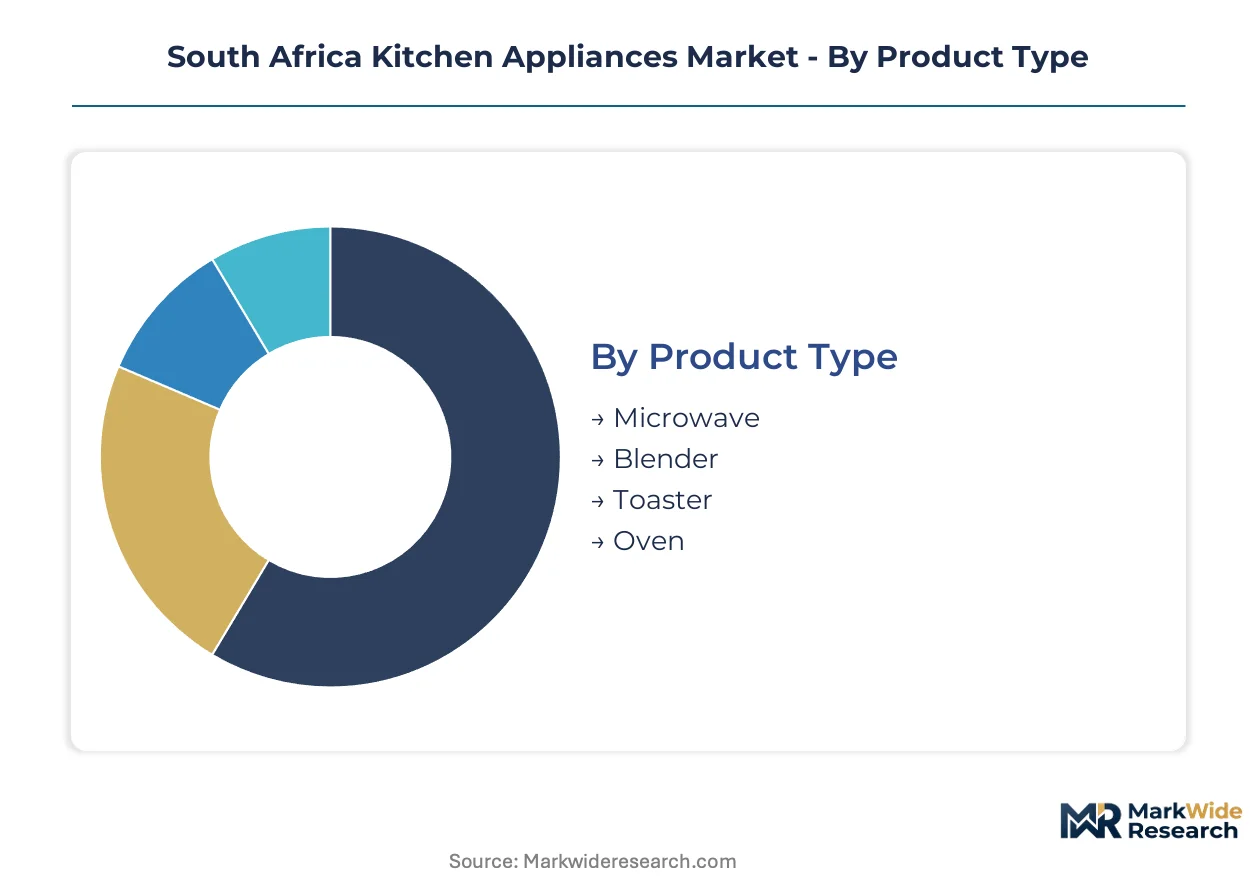
South Africa's kitchen appliance segmentation reflects divergent resilience strategies across buyer types. Product specifications now prioritize load-shedding compatibility and solar integration as primary purchase filters.
Product Type:
Mature categories dominate replacement cycles while emerging formats reshape new-build specifications across Gauteng and Western Cape developments.
- Microwave:Countertop and built-in variants operating at 700-1000W dominate urban household penetration. Demand concentrates in Johannesburg apartment complexes where space constraints and rapid reheating needs override full-kitchen investments.
- Oven:Built-in electric and convection systems anchor premium kitchen fit-outs in Pretoria and Cape Town middle-income housing. Developers specify these as standard in new residential stock, pulling replacement demand forward into initial purchase decisions.
- Blender:Personal and commercial-grade units serve smoothie preparation and small-batch food processing needs across household and informal catering channels.
- Toaster:Entry-level two-slice and premium four-slice configurations represent low-involvement purchases with minimal technology differentiation across retail channels.
Oven handles the majority of throughput; microwave is the fastest mover on share.
Technology:
Cost tier stratification separates premium induction from mass-market electric coil positioning, with manual alternatives serving grid-unreliable peri-urban settlements.
- Induction:Electromagnetic heating systems deliver 90% energy efficiency with instantaneous temperature control. Stellenbosch and Paarl solar corridor households drive adoption as battery-backed PV installations enable high-wattage cooking without grid dependency.
- Convection:Fan-assisted thermal circulation reduces cooking times by 25% versus conventional radiant heat. Cape Town kitchen studios specify these for coastal humidity environments where moisture control affects baking outcomes.
- Electric:Traditional coil and ceramic glass cooktops retain volume leadership through lower upfront cost and established repair infrastructure.
- Manual:Hand-powered and gas-hybrid systems serve informal settlements and rural Eastern Cape households beyond reliable grid reach.
Electric maintains volume dominance; induction is expanding most quickly in new housing specifications.
End User:
Application intensity varies sharply between residential convenience cooking and commercial throughput requirements.
- Household:Primary demand channel spanning entry-level to premium segments across all nine provinces.
- Restaurants:High-duty-cycle equipment requiring SABS certification and rapid service response capabilities concentrated in Johannesburg and Durban foodservice clusters.
- Catering Services:Mobile and event-based operations prioritizing portable induction and convection equipment for off-grid venue service.
- Hotels:Procurement through hospitality supply chains with extended warranty and bulk replacement scheduling.
Household absorbs the dominant share; catering services are climbing the fastest as event-based dining expands.
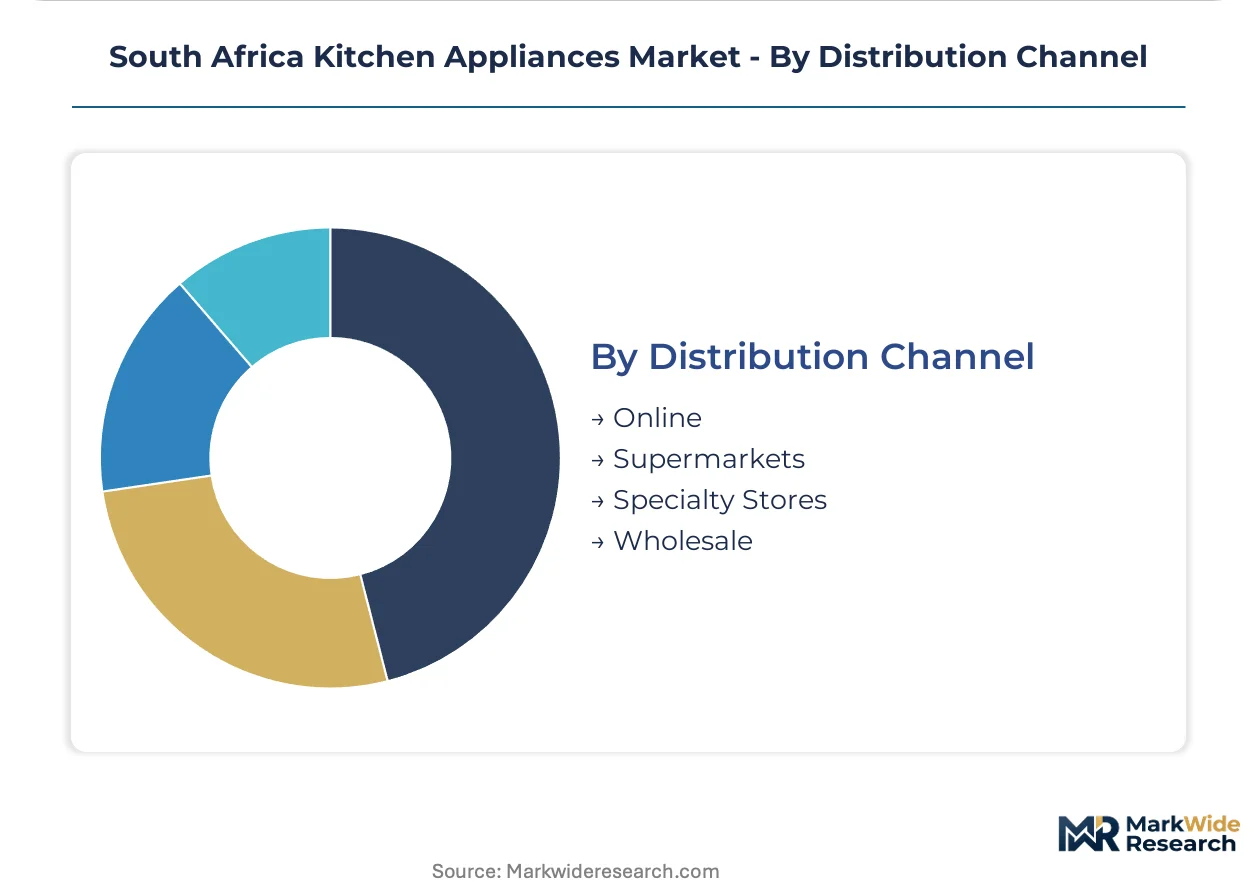
Distribution Channel:
Customer type and purchase timing reshape channel selection between planned specification and emergency replacement scenarios.
- Specialty Stores:Cape Town kitchen designers and Johannesburg appliance studios capture pre-construction specification decisions.
- Online:Direct-to-consumer platforms accelerate in secondary cities where physical retail coverage gaps persist.
- Supermarkets:Mass-market small appliances and entry-level refrigeration serve immediate replacement needs.
- Wholesale:Bulk procurement for property developers and hospitality groups with standardized fit-out requirements.
Supermarkets move the highest unit volumes; specialty stores are gaining share fastest in premium postcodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Richards Bay Coal Terminal and Cape Town Container Terminal anchor South Africa's appliance import infrastructure, channeling Asian-manufactured components through Durban and Cape Town ports into Gauteng distribution networks.
Gauteng
Johannesburg and Pretoria middle-income housing developments specify built-in ovens and induction hobs as baseline fit-outs. The National Regulator for Compulsory Specifications enforces SABS certification for all electrical appliances sold through formal retail channels. Centurion and Midrand appliance studios capture pre-construction specification decisions before retail consideration.
Western Cape
Stellenbosch and Paarl solar corridor households drive premium induction adoption through battery-backed PV installations. Cape Town's municipal electricity tariff escalation redirects buyer preference toward A-rated energy efficiency appliances. Southern suburbs kitchen designers now specify appliance packages during housing construction rather than post-occupancy retail selection.
KwaZulu-Natal
Durban foodservice clusters demand high-duty-cycle equipment with rapid service response capabilities. The province's humidity levels accelerate convection oven specification for moisture-sensitive baking applications. Umhlanga and Ballito hospitality developments pull commercial-grade appliance procurement through specialized supply chains.
Eastern Cape
Peri-urban settlements beyond reliable grid reach sustain manual and LPG-hybrid cooking system demand. Port Elizabeth retail infrastructure serves replacement-cycle purchases for traditional electric coil inventory. East London's lower middle-income housing stock prioritizes upfront cost minimization over energy efficiency ratings.
South Africa Kitchen Appliances Market Competitive Landscape
On the supply side, the industry is structured around three distinct competitive tiers anchored by domestic manufacturing, multinational electronics conglomerates, and import-dependent specialists. Domestic producers leverage local assembly footprints to bypass currency volatility on finished goods. Multinational electronics groups compete through smart connectivity integration and extended warranty infrastructure. Import specialists concentrate on value-tier positioning through volume-driven distribution partnerships. The dominant competitive moves involve direct-to-installer channel development and solar-plus-storage compatibility certification.
Within the domestic manufacturing tier, Defy Appliances anchors price-competitive positioning through its South African production base. Among multinational electronics conglomerates, Samsung Electronics and LG Electronics exemplify premium-tier competition through connected appliance ecosystems and established service networks. Hisense South Africa occupies a position within the value-import segment, competing through bundled refrigeration and small appliance offerings. Bosch Home Appliances SA represents European-origin specialist positioning in the premium built-in category.
| Leading Market Players |
|---|
| Defy Appliances |
| Samsung Electronics |
| LG Electronics |
| Hisense South Africa |
| Bosch Home Appliances SA |
| Haier |
| Siemens |
| Electrolux |
| Philips |
| Others |
Value Network & Pricing Analysis
Rand depreciation against dollar-denominated component sourcing compresses distributor margins and forces three-tier pricing stratification across import-dependent inventory. This currency exposure simultaneously widens premium-to-economy tier spreads and concentrates supply chain control among Johannesburg-based wholesalers with forward-contract hedging capabilities.
Pricing Analysis
Volume-discount tiering separates developer bulk procurement from retail single-unit purchases and installer channel bundles. Pricing stratifies across premium smart-connected, standard energy-efficient, and economy manual-operation tiers, with SABS certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying because LPG substitution threatens electric appliance demand in peri-urban settlements. Developer procurement teams show lowest price sensitivity; informal settlement households exhibit highest.
Supply Chain Analysis
Export-control scrutiny on semiconductor controllers and inverter-grade silicon limits component flows from China and Taiwan into South African assembly channels. Manufacturing draws from Chinese finished goods, Turkish white-goods components, and German precision electronics, with lithium battery cells and induction inverter modules as critical dependencies. Single-source vulnerability concentrates in Johannesburg port clearance bottlenecks. Distribution runs through Durban and Cape Town container terminals into Gauteng wholesale networks serving formal retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for induction inverter repair creates defensive moats for incumbents with established service infrastructure, while solar-plus-storage integration expertise remains underdeveloped across all competitive tiers.
For Market Incumbents: Harden service network coverage in secondary cities where 14-day resolution timelines erode brand equity, and secure backward integration into induction inverter module sourcing to offset rand volatility. LPG substitution in peri-urban Eastern Cape threatens volume; vertical control over repair technician training programs locks in replacement-cycle loyalty. For New Entrants and Emerging Players: Establish a beachhead in Western Cape solar corridor installer channels before retail consideration, where Stellenbosch and Paarl households prioritize battery-compatible induction bundles. Direct-to-solar-EPC distribution bypasses big-box retail gatekeepers. NRCS pre-certification streamlining for EU CE-marked products compresses competitive response windows against import-dependent specialists. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors service-capable incumbents over pure-import distributors. Long-term viability hinges on solar-integration engineering depth and Western Cape geographic presence. Acquisition targets should demonstrate certified technician networks and NRCS testing partnerships. Watch distributed PV adoption rates in Gauteng middle-income housing as inflection indicator for induction demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Plus-Storage Compatibility Certification | NRCS alignment with IEC 60335 standards enables premium positioning in Stellenbosch and Paarl corridors. |
| Direct-to-Installer Channel Development | Solar EPC contractor partnerships capture replacement-cycle decisions before retail consideration in Cape Town. |
| Backward Integration into Induction Inverter Sourcing | Captive supply of semiconductor controllers insulates margins from rand-dollar volatility. |
| Certified Technician Network Expansion | Johannesburg and Cape Town repair capabilities extend to secondary cities, compressing resolution timelines. |
| LPG-Hybrid Product Line Introduction | Dual-fuel systems address peri-urban grid unreliability in Eastern Cape informal settlements. |
Research Methodology
The analysis maps induction technology migration, solar-plus-storage adoption patterns, and load-shedding resilience specifications, each validated through appliance studio designers, solar EPC contractors, and retail category buyers. Primary fieldwork with NRCS certification specialists, Eskom grid planning officers, and Gauteng property developer procurement teams combined with SABS regulatory filings, Eskom tariff schedules, and municipal housing permit data. Bottom-up channel volume estimates and top-down macroeconomic scaling provided triangulation across the analysis window.
Assumptions held fixed include SABS energy labeling mandate enforcement and Eskom grid reliability profiles; variables tested included solar PV adoption rates and rand depreciation scenarios. Segmentation dimensions modeled encompass product type, technology tier, end-use application, and distribution channel, with provincial housing stock expansion and municipal electricity tariff escalation as industry-specific demand drivers. CAGRs derived from installed base replacement cycles and new-build specification trends.
Macroeconomic conditions sit as an overlay; deviation in rand exchange rates, lithium battery import costs, or Eskom load-shedding intensity would shift the trajectory. Material shifts in NRCS certification timelines or Western Cape solar corridor penetration rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Smart Induction Cooktop Market