
 North America Glassware Market | 2026-2036
North America Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glassware Market Analytics
Market Context with Strategic Players
California's SB 54 extended producer responsibility mandate is restructuring procurement priorities across foodservice channels. Libbey Inc leverages its Toledo, Ohio manufacturing base to sustain institutional contracts with national restaurant chains. Oneida competes through specialty store partnerships that emphasize American-made origin claims. Arc International anchors North American supply with Mexican production facilities serving US retail and hospitality buyers.
Technical Definition and Structural Segments
Glassware encompasses vessels and containers fabricated from silica-based melts, with borosilicate formulations tolerating thermal shock differentials exceeding 150°C and soda-lime variants dominating cost-sensitive volume production. The category serves food preparation, beverage service, and storage functions across residential and commercial environments. Drinkware leads material throughput in the North American market, while borosilicate glass captures premium margin pools in specialty retail and professional kitchen channels. Online retail is displacing supermarket dominance in household procurement, though direct sales sustain pricing power for crystal serveware among catering services.
Regulatory Frame and Forward-Looking Close
US FDA food-contact regulations, California Proposition 65 labeling requirements, and OSHA workplace safety standards collectively shape product composition, warning labels, and manufacturing facility compliance burdens across the value chain. The EPA's advancing rules on recycled content thresholds will force reformulation timelines for soda-lime producers. Stakeholders must monitor how state-level extended producer responsibility legislation fragments compliance obligations across the US-Canada-Mexico trade corridor.
Market Dynamics
California's SB 54 extended producer responsibility mandate is forcing glassware manufacturers to restructure material sourcing and end-of-life collection systems across the US-Canada-Mexico trade corridor.
Growth Catalysts
- Tempered glass durability standards:Restaurants and cafés in Texas and Arizona are expanding front-of-house procurement as hospitality construction accelerates. The material withstands thermal shock differentials exceeding 150°C.
- EPA recycled-content thresholds:The US EPA's advancing rules on sustainable packaging are redirecting manufacturer investment toward borosilicate and recycled-content production lines.
- Southwest demand concentration:Texas and Arizona hospitality construction is outpacing other US sub-regions, pulling serveware volumes toward desert climate markets.
Market Restraints
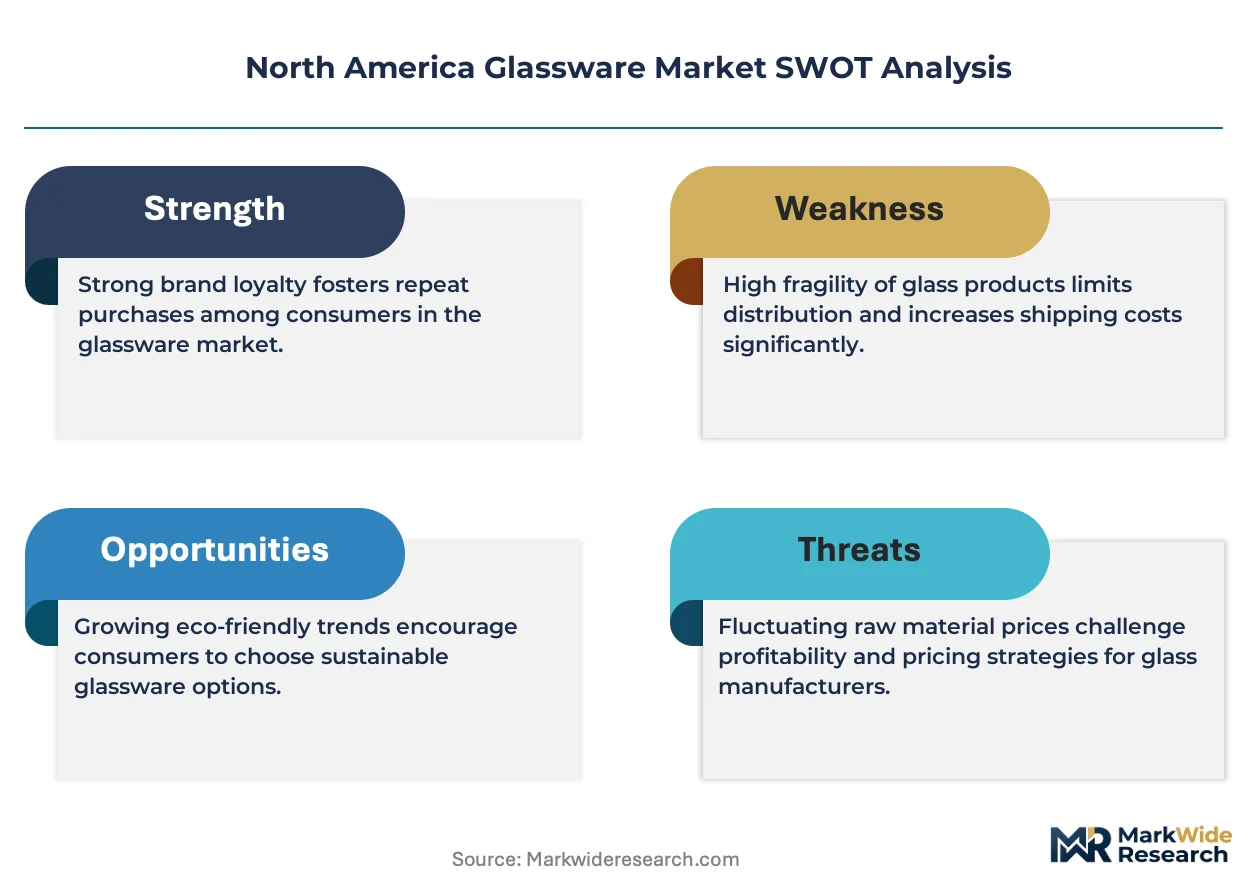
- Natural gas price volatility:Soda-lime glass production depends on natural gas-fired furnaces. Input cost swings compress margin pools for volume producers operating continuous melt operations.
- Mexican supply concentration:Arc International's Mexican production facilities anchor North American supply. Single-source dependency creates vulnerability to cross-border logistics friction.
- Thermal shock limitations:Standard soda-lime formulations cannot tolerate rapid temperature shifts. This technical ceiling restricts penetration into professional kitchen channels demanding borosilicate performance.
Strategic Opportunities
- Canadian EPR expansion:Ontario and British Columbia are implementing extended producer responsibility frameworks. These policies create first-mover advantage for manufacturers with closed-loop collection infrastructure.
- Online retail channel growth:E-commerce platforms are displacing supermarket dominance in household glassware procurement. Direct-to-consumer models sustain pricing power for specialty serveware.
- Borosilicate-crystal convergence:Premium retail channels are blending laboratory-grade thermal performance with aesthetic crystal clarity. This hybrid positioning captures margin pools above commodity drinkware.
Industry Challenges
- Prop 65 compliance timelines:California's labeling requirements for lead and cadmium content force reformulation sprints. Manufacturers face compressed certification windows ahead of enforcement dates.
- OSHA silica exposure standards:Workplace safety regulations mandate capital-intensive ventilation and monitoring systems at manufacturing facilities. Smaller producers struggle with capex intensity for compliance upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glassware Market |
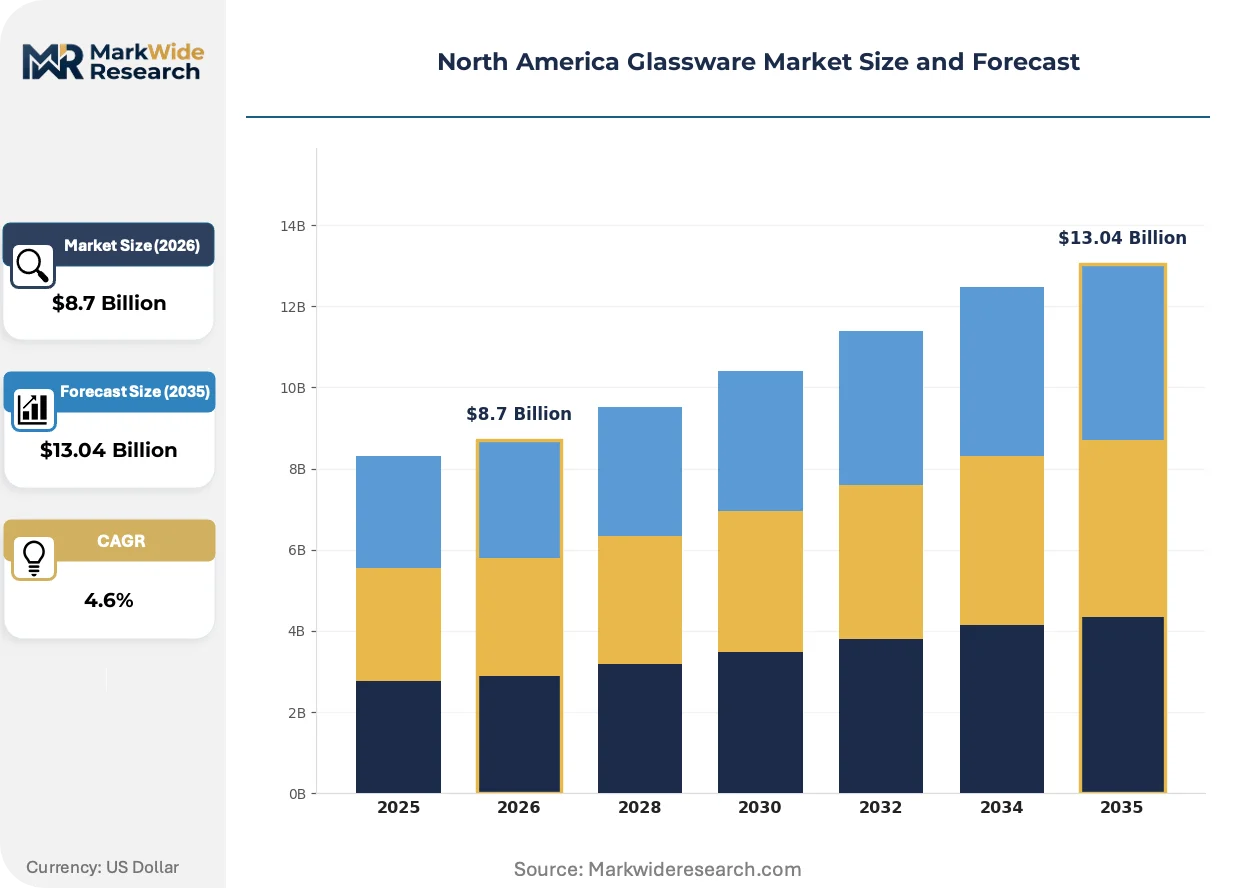
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware, Drinkware, Serveware, Storage Containers Material: Tempered Glass, Borosilicate Glass, Crystal, Soda-Lime Glass End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Libbey Inc, Oneida, Lenox Corporation, Noritake, Arc International, Fortessa Tablewear Solutions, Bormioli Rocco, Stoelzle Glass Group, Anchor Hocking, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glassware Market Evolving Landscape
Active reshaping in North American glassware centers on material science advancement, regulatory-driven circularity mandates, and channel architecture disruption that fragments traditional wholesale dominance.
Post-consumer recycled cullet is integrating into furnace feeds at ratios previously technically unfeasible. Major foodservice distributors are specifying minimum recycled-content thresholds in national chain contracts. The technology is integrating closed-loop material flows into cost-competitive soda-lime production, compressing virgin silica demand.
The US EPA's recycled-content thresholds are advancing through rulemaking phases. These standards will force reformulation timelines for producers dependent on virgin batch materials. Soda-lime manufacturers serving institutional channels face the steepest compliance curves.
Foodservice buyers are consolidating procurement through direct manufacturer relationships, bypassing traditional restaurant supply distributors. National chains in the US Southwest are negotiating volume commitments with Toledo and Mexican production facilities. This pattern is most visible in Texas and Arizona hospitality construction markets where durability specifications tighten fastest.
North America Glassware Market Segmentation
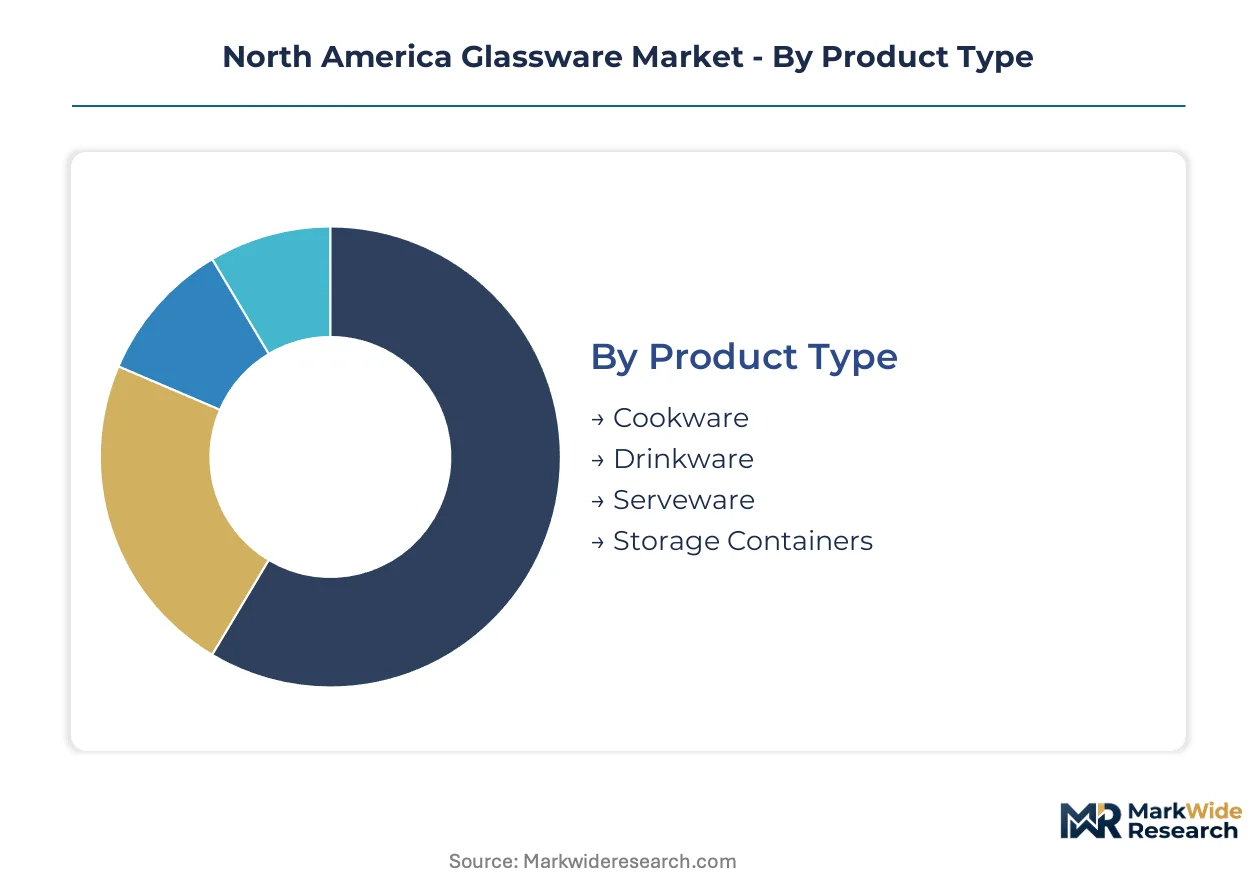
Material composition and thermal performance specifications drive procurement decisions across foodservice and residential channels in the North America glassware market. Segmentation reveals how durability standards, regulatory compliance, and channel economics fragment demand patterns between commodity volume and premium specialty tiers.
Product Type:
Application environment dictates durability requirements and replacement frequency across commercial and residential settings.
- Cookware:Borosilicate formulations tolerate thermal shock differentials exceeding 150°C, enabling stovetop-to-oven transitions. Demand concentrates in Texas and Arizona residential markets where open-concept kitchen renovations prioritize thermal performance.
- Drinkware:Soda-lime glass dominates volume production for cost-sensitive household procurement. Texas and Arizona hospitality construction is outpacing other US sub-regions, pulling tempered glass drinkware volumes toward desert climate markets with tightened front-of-house durability standards.
- Serveware:Tempered glass withstands mechanical stress for high-traffic restaurant applications. California's SB 54 extended producer responsibility mandate is restructuring procurement priorities across foodservice channels.
- Storage Containers:Borosilicate and tempered variants serve meal-prep and commercial kitchen organization functions. The US EPA's advancing rules on recycled content thresholds will force reformulation timelines for soda-lime producers serving this segment.
Drinkware leads on scale; cookware leads on momentum as thermal performance specifications tighten fastest.
Material:
Cost-positioning against performance requirements determines channel access and margin capture.
- Tempered Glass:Heat-treated soda-lime variants deliver 4-5x mechanical strength improvement. Restaurants and cafés in the US Southwest are expanding front-of-house procurement as hospitality construction accelerates.
- Borosilicate Glass:Laboratory-grade thermal shock resistance commands premium positioning in specialty retail and professional kitchen channels. The US EPA's growing focus on sustainable packaging is redirecting manufacturer investment toward borosilicate production lines.
- Crystal:Leaded and lead-free formulations serve ceremonial and luxury hospitality applications. Direct sales sustain pricing power for crystal serveware among catering services.
- Soda-Lime Glass:Virgin and recycled-content batches dominate cost-competitive volume production. Natural gas-fired furnace operations face margin compression from input cost volatility.
Soda-lime glass leads on scale; borosilicate glass leads on momentum as regulatory thresholds advance.
End User:
Procurement consolidation patterns and durability specifications differentiate commercial from residential demand.
- Households:Online retail is displacing supermarket dominance in household glassware procurement. E-commerce platforms fragment traditional wholesale channel control.
- Restaurants:National chains are negotiating volume commitments directly with Toledo and Mexican production facilities. Foodservice buyers are consolidating procurement through direct manufacturer relationships, bypassing traditional restaurant supply distributors.
- Cafés:Front-of-house aesthetic requirements combine with durability specifications for high-turnover service environments. Tempered glass serveware procurement is expanding as durability standards tighten.
- Catering Services:Event-based volume demand prioritizes stackability, transport resilience, and replacement cost economics. Direct sales relationships sustain pricing power for premium serveware tiers.
Households lead on scale; restaurants lead on momentum as procurement consolidation accelerates.
Distribution Channel:
Channel economics determine pricing power and customer relationship depth across fragmented retail architectures.
- Online Retail:E-commerce platforms are displacing supermarket dominance in household glassware procurement. Direct-to-consumer models sustain pricing power for specialty serveware.
- Supermarkets:Mass-market volume placement depends on slotting fees and promotional calendar alignment. Channel share is compressing as digital procurement patterns mature.
- Specialty Stores:Curated assortments emphasize American-made origin claims and thermal performance storytelling. Oneida competes through specialty store partnerships.
- Direct Sales:Manufacturer-to-institutional relationships bypass distributor markups for national chain accounts. National chains in the US Southwest are negotiating volume commitments with production facilities.
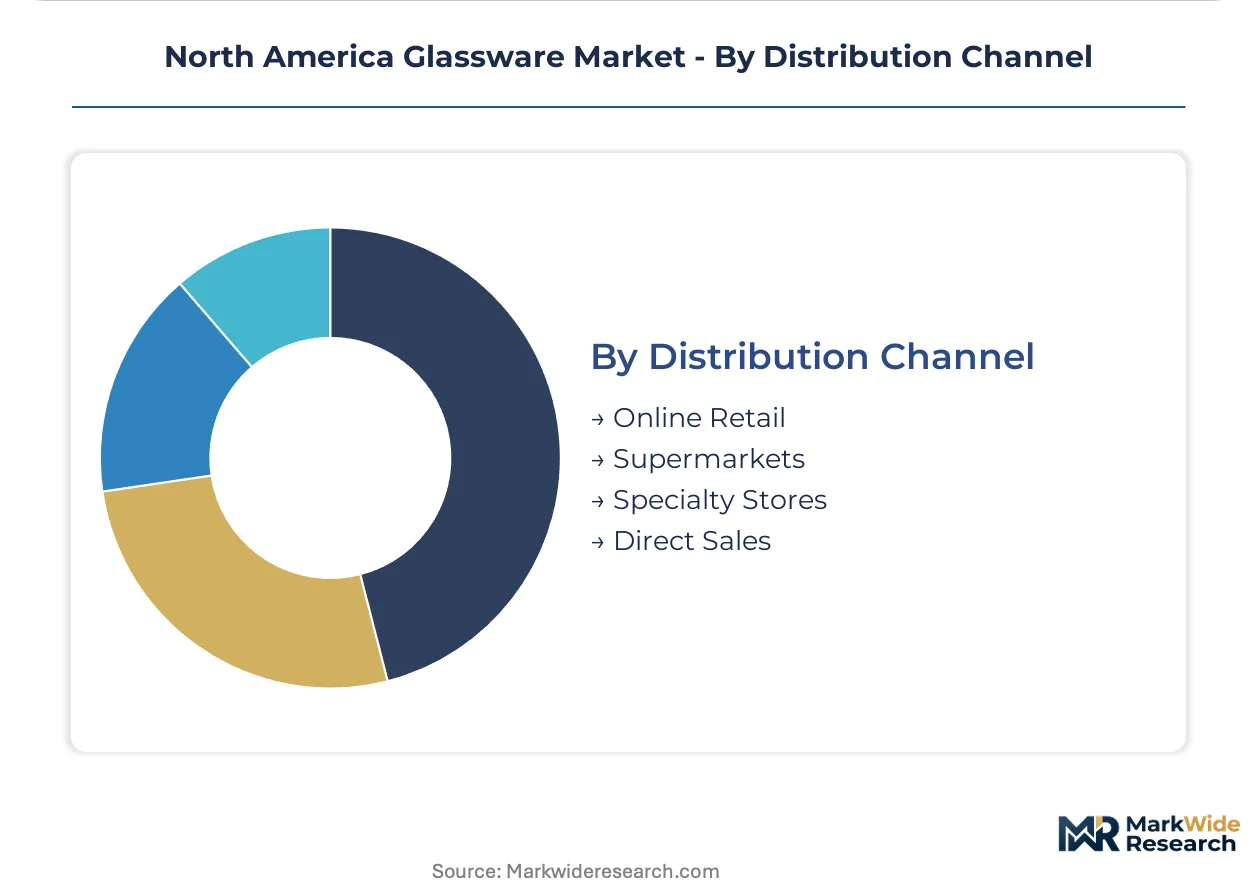
Supermarkets lead on scale; online retail leads on momentum as channel architecture disruption fragments traditional wholesale dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glassware manufacturing in North America traces its industrial roots to Ohio's silica-rich river valleys and Mexico's colonial glassmaking traditions, with modern production clustering around natural gas corridors and cross-border logistics hubs that serve integrated US-Canada-Mexico supply chains.
United States
Texas and Arizona hospitality construction is outpacing other sub-regions, pulling tempered glass serveware volumes toward desert climate markets. The US EPA's advancing rules on recycled-content thresholds are redirecting manufacturer investment toward borosilicate production lines. Toledo, Ohio retains institutional contract density with national restaurant chains leveraging its historical manufacturing base.
Canada
Ontario and British Columbia are implementing extended producer responsibility frameworks that create first-mover advantage for manufacturers with closed-loop collection infrastructure. Health Canada's food-contact regulations align with FDA standards while maintaining distinct labeling requirements. Quebec's industrial glass sector serves specialty retail channels emphasizing thermal performance specifications.
Mexico
Arc International's production facilities anchor North American supply from Mexican manufacturing bases serving US retail and hospitality buyers. Cross-border logistics friction creates vulnerability in single-source dependency patterns. The country's glassmaking heritage in Jalisco and Nuevo León supports both artisanal crystal and industrial soda-lime volume production.
Southwest US Sub-region
Texas and Arizona front-of-house durability standards are tightening fastest, consolidating procurement through direct manufacturer relationships. California's SB 54 extended producer responsibility mandate spills across state lines as national chains harmonize sourcing policies. Phoenix and Dallas-Fort Worth hospitality construction clusters concentrate demand for thermal-shock-resistant serveware.
North America Glassware Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that fragments between integrated manufacturers with captive furnace operations and brand-focused distributors outsourcing production. The vendor base separates into three strategic archetypes: legacy manufacturers with Toledo or Mexican production bases, specialty retailers emphasizing American-made origin claims, and European-headquartered multinationals leveraging North American distribution networks. Dominant competitive moves include direct procurement consolidation by national restaurant chains and portfolio diversification into borosilicate-crystal hybrid positioning.
Within the legacy manufacturer tier, Libbey Inc and Anchor Hocking represent capital-intensive furnace operators with historical Ohio manufacturing footprints. Arc International occupies a position as the European-headquartered multinational anchoring North American supply through Mexican production facilities. Oneida exemplifies the brand-focused distributor archetype competing through specialty store partnerships rather than captive manufacturing.
| Leading Market Players |
|---|
| Libbey Inc |
| Oneida |
| Lenox Corporation |
| Noritake |
| Arc International |
| Fortessa Tablewear Solutions |
| Bormioli Rocco |
| Stoelzle Glass Group |
| Anchor Hocking |
| Others |
Value Network & Pricing Analysis
Natural gas-fired furnace operations in Ohio and Mexico draw from regional pipeline networks to feed continuous melt production, with thermal energy costs cascading through soda-lime volume tiers into borosilicate premium positioning. Input cost volatility at the furnace level compresses margin pools for commodity producers while reinforcing pricing power for thermal-performance specialists serving institutional buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates borosilicate laboratory-grade formulations from tempered glass foodservice tiers and virgin soda-lime household volumes. Price differentiation rests on thermal shock certification thresholds and American-made origin claims in specialty retail channels. Cost compression in standard-tier soda-lime production is intensifying because natural gas price swings erode continuous-melt economics. Quick-service restaurant chains exhibit highest price sensitivity, while catering services purchasing crystal serveware through direct sales show least.
Supply Chain Analysis
Single-source vulnerability sits with Mexican production facilities anchoring North American supply for Arc International's cross-border logistics network. Geographic concentration spans Mexico, Ohio, and Quebec, with silica sand deposits in the Great Lakes region feeding furnace operations. Raw material dependencies include natural gas for melting energy, soda ash for chemical formulation, and post-consumer cullet for recycled-content batches. Tariff exposure at the US-Mexico border creates structural risk for just-in-time hospitality procurement. Distribution runs through direct manufacturer relationships with national chains alongside traditional foodservice distributors serving fragmented café accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America glassware market reads as a late-cycle quality story, with procurement consolidation by restaurant chains pulling volumes toward thermal-performance specifications that command sustainable margin capture.
For Market Incumbents: Anchor institutional contract density through captive furnace investments in Toledo and cross-border Mexican facilities. Defend against direct procurement consolidation by national chains through backward integration into post-consumer cullet collection infrastructure. Prioritize borosilicate-crystal hybrid R&D to capture premium positioning above commodity drinkware tiers. For New Entrants and Emerging Players: Specialty retailers emphasizing American-made origin claims offer the most penetrable channel for asset-light designers without captive manufacturing. Target Canadian EPR expansion in Ontario and British Columbia where closed-loop collection infrastructure creates first-mover advantage. Pursue white-label partnerships with e-commerce platforms displacing supermarket dominance in household procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where natural gas price volatility compresses margin pools for continuous-melt soda-lime operators. Long-term viability favors vertically integrated producers with captive furnace operations and diversified thermal-performance portfolios. Watch EPA recycled-content threshold advancement as inflection indicator for reformulation capex cycles and M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Collection | Closed-loop material flows satisfy California SB 54 extended producer responsibility mandates ahead of compliance deadlines. |
| Borosilicate Production Line Expansion | Thermal shock resistance exceeding 150°C captures premium positioning in Texas and Arizona hospitality construction markets. |
| Direct-to-Consumer Channel Launch | E-commerce platforms fragment traditional wholesale control while sustaining pricing power for specialty serveware tiers. |
| Canadian EPR Infrastructure Buildout | Ontario and British Columbia frameworks reward first-movers with closed-loop collection systems and preferential procurement status. |
| Natural Gas Hedging Program | Input cost stabilization protects continuous-melt soda-lime margins against volatility in regional pipeline pricing. |
Research Methodology
Multiple input streams — primary interviews with glassware manufacturing executives, foodservice procurement directors, and specialty retail buyers; secondary validation through US EPA rulemaking dockets, FDA food-contact guidance documents, and customs trade flow records; plus industry association production surveys — were reconciled through bottom-up volume modeling and top-down value triangulation. Plant managers at Ohio and Mexican furnace operations provided operational cost structures, while national chain purchasing committees detailed procurement consolidation patterns. SEC filings from publicly traded manufacturers and state-level EPR implementation timelines supplied secondary anchor points.
Data-stream reconciliation applied across the modeling period segmented demand by material composition, thermal performance tier, end-user procurement consolidation level, and distribution channel control. CAGRs were derived from installed base replacement cycles, hospitality construction permit flows in Texas and Arizona, and regulatory-driven reformulation timelines. Forecast inputs incorporated natural gas price trajectory assumptions, post-consumer cullet availability curves, and cross-border logistics friction indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA recycled-content rulemaking pace, California Proposition 65 enforcement intensity, and OSHA silica exposure standard revision timing. Forecasts reflect documented assumptions about furnace energy economics, EPR policy diffusion across the US-Canada-Mexico corridor, and channel architecture evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Germany Induction Hobs Market
Household Items
GCC Gas Hobs Market
Household Items
India Air Purifier Market
Household Items
Household Scales Market
Household Items
Steam Cleaners Market
Household Items
Tiki Torch Market
Household Items
Infrared Sauna Heaters Market
Household Items
Smart Connected Water Purifier Market
Household Items
Drain Cleaners Market
Household Items
Smart Toilet Market
Household Items
Shower Caddies Market
Household Items
Global Humidifier Market
Household Items
Commercial Lawnmower Market
Household Items
Global Rimless Toilets Market
Household Items
Kuwait Gas Hobs Market
Household Items
Electric Clothes Drying Hanger Market