
 Commercial Hovercraft Market | 2026-2036
Commercial Hovercraft Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Hovercraft Market Analysis
Buyer concentration in the commercial hovercraft sector is pivoting toward government agencies and coast guard services as defense budgets expand across littoral nations. Griffon Hoverwork Ltd. anchors British manufacturing through its long-standing Ministry of Defence contracts. Textron Systems Corporation leverages its defense-industrial base to compete for naval procurement programs. Neoteric Hovercraft Inc. specializes in compact designs for private operators and research institutions.
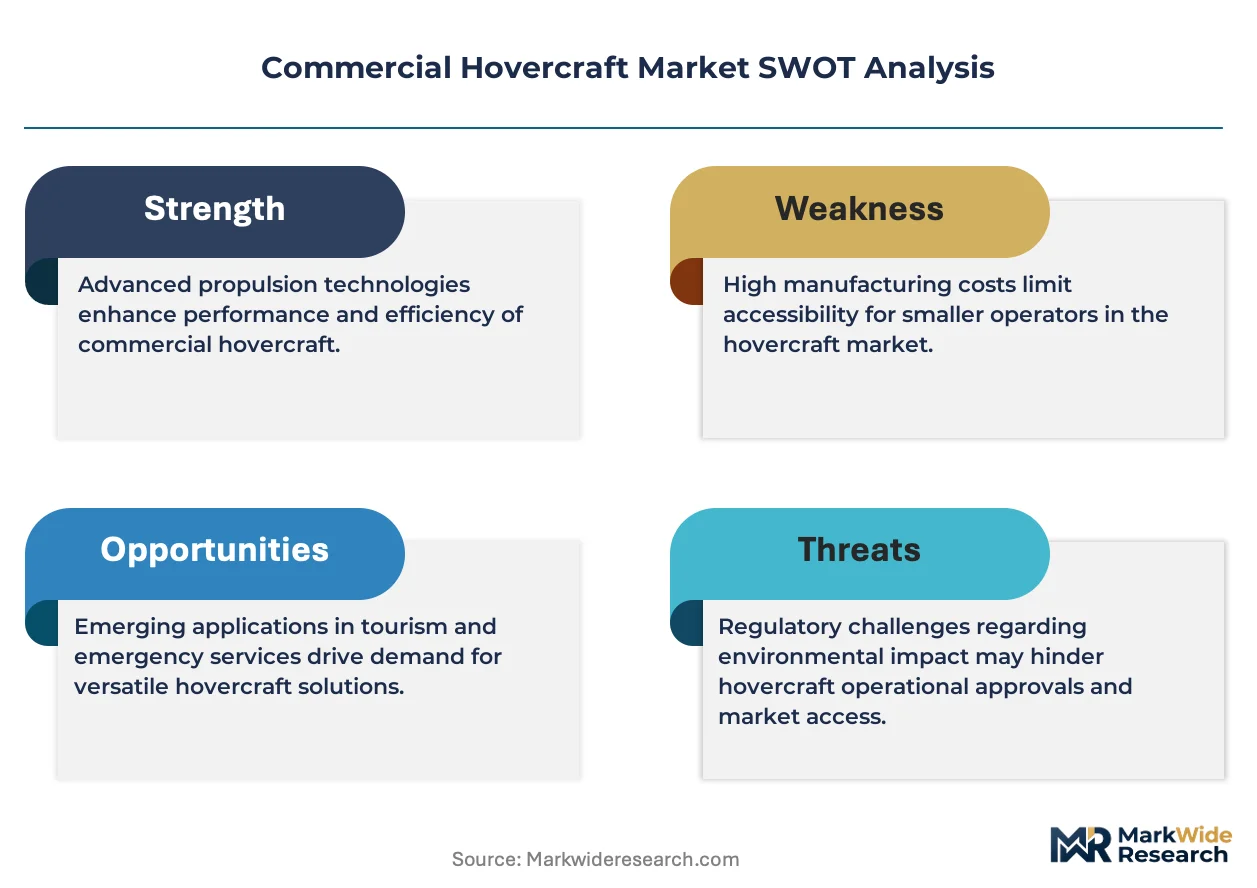
A commercial hovercraft is a vessel that rides on a pressurized cushion of air contained within a flexible skirt, enabling operation over water, ice, mud, and marsh terrain where conventional boats or vehicles cannot function. Lift fans typically generate cushion pressures of 500-2,500 pascals, allowing payloads from 380 kilograms to over 70 tonnes depending on hull configuration. The passenger product type dominates current fleet deployments, particularly in tourism corridors and inter-island transport routes, while emergency response applications command premium pricing due to specialized equipment requirements. Diesel technology retains the largest installed base, though hybrid systems are gaining traction in environmentally sensitive operating zones.
The U.S. Coast Guard and FAA jointly govern hovercraft certification and operational safety standards, while the EU Green Deal and REACH frameworks constrain material selection and emissions profiles for European builders. Military end users increasingly require interoperability with NATO logistics standards, reshaping procurement specifications. Stakeholders must monitor evolving coastal state sovereignty claims and their impact on patrol vessel demand.
Market Dynamics
The EU Green Deal's emissions mandates are compressing diesel propulsion timelines while hybrid architectures gain engineering priority across European yards. Defense procurement cycles in littoral nations now dominate order books, redirecting manufacturer capacity from commercial tourism toward naval specifications.
Growth Catalysts
- Coastal Tourism Expansion:Southeast Asian operators are commissioning larger-capacity craft to serve remote archipelago routes unreachable by conventional ferry services.
- REACH Material Standards:European builders are reformulating skirt fabrics and hull composites to meet ECHA restrictions on fluorinated compounds, opening supplier diversification.
- Hybrid Propulsion Maturation:Battery-electric auxiliary systems are reducing fuel consumption in environmentally sensitive operating zones without sacrificing payload range.
Market Restraints
- Specialized Powertrain Concentration:Marine diesel engine supply concentrates among a handful of European and Japanese suppliers, exposing builders to allocation delays.
- Skirt Replacement Economics:Flexible skirt systems require replacement every 500-1,500 operating hours, creating recurring cost burdens for high-utilization fleets.
- Amphibious Vehicle Substitution:Shallow-draft landing craft and air-cushion catamarans are capturing certain intertidal transport applications at lower capital cost.
Strategic Opportunities
- Arctic Patrol Demand:Canadian and Norwegian coast guard requirements for ice-capable craft are creating specification openings for cold-weather hull designs.
- Emergency Response Unbundling:Fire suppression and medical evacuation modules are enabling rental fleet operators to serve multiple agency contracts with reconfigurable platforms.
- PLI Scheme Alignment:India's production-linked incentive framework for marine manufacturing is attracting component localization investments from European system integrators.
Industry Challenges
- Multicraft Certification Complexity:Dual FAA and US Coast Guard approval pathways for commercial hovercraft extend type certification timelines by 18-24 months versus conventional vessels.
- Skirt Fabrication Skill Scarcity:Pattern cutting and RF welding of elastomeric skirt segments requires specialized technician training unavailable in standard marine curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Hovercraft Market |
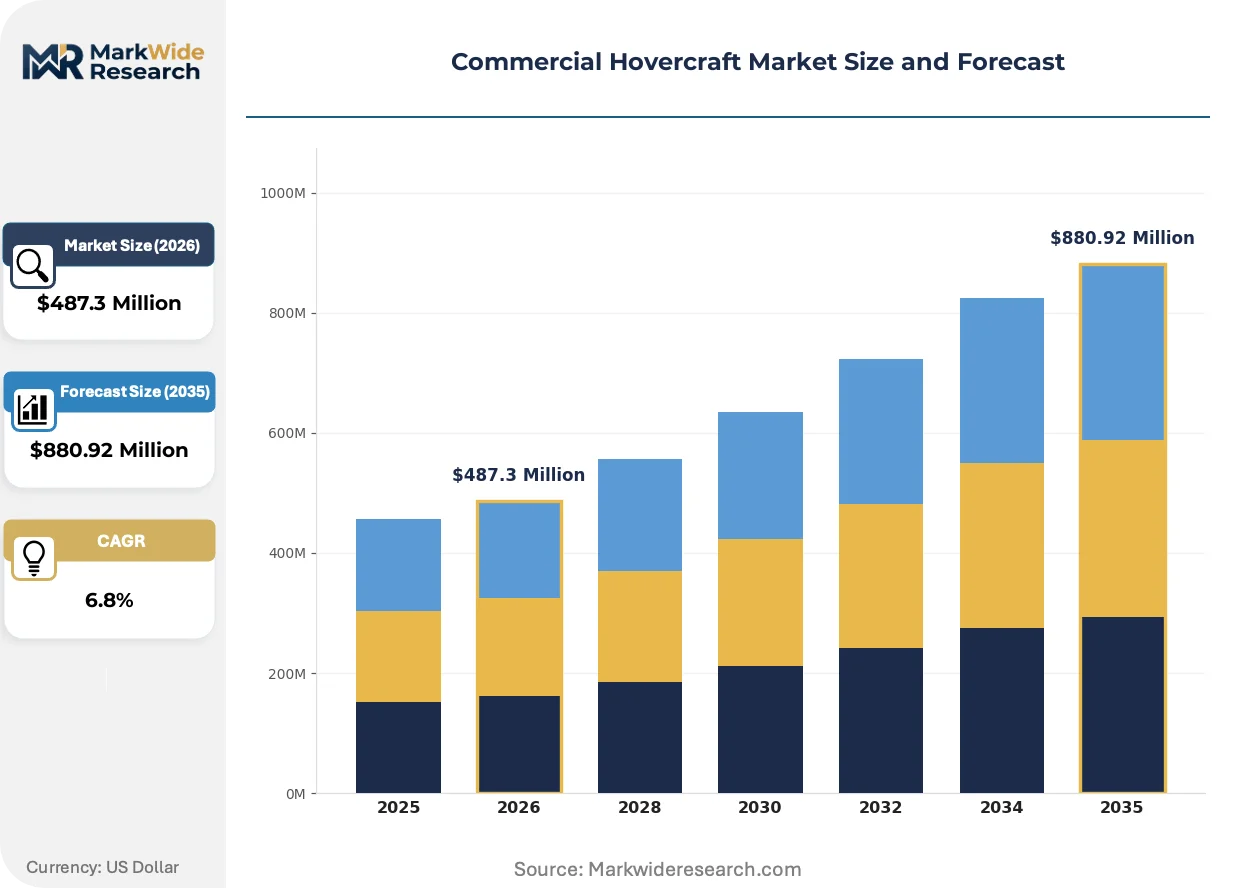
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger, Cargo, Emergency Response, Military Application: Transport, Tourism, Rescue Operations, Surveillance End User: Government Agencies, Private Operators, Tourist Companies, Research Institutions Technology: Air Cushion, Electric, Hybrid, Diesel |
| Companies Covered | Griffon Hoverwork Ltd., Neoteric Hovercraft Inc., The British Hovercraft Company Ltd., Textron Systems Corporation, Airlift Hovercraft Pty Ltd., Christy Hovercraft, Universal Hovercraft, Hovertechnics LLC, Ivanoff Hovercraft AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Hovercraft Market Emerging Trajectories
Propulsion architecture and procurement contracting are undergoing parallel transformation. Manufacturers are rebalancing engineering resources between emission compliance and mission flexibility while buyers restructure acquisition models.
Modular battery-electric auxiliary systems are decentralizing power distribution across lift and propulsion functions. Coast guard operators in the United Kingdom and Japan are piloting split-architecture designs that isolate propulsion battery banks from lift fan circuits. This topology is decentralizing maintenance scheduling and reducing single-point failure risks in extended patrol missions.
The EU Green Deal's F-Gas Regulation is phasing out hydrofluorocarbon-based fire suppression agents in marine applications. European builders are retrofitting detection systems with inert gas alternatives, compressing equipment bay volumes and altering weight distribution calculations. Passenger ferry configurations face the steepest redesign burden due to dense cabin layouts.
Outcome-based availability contracts are displacing conventional unit sales in defense procurement. Australian and British naval programs now specify operational hours rather than hull counts, transferring maintenance liability to manufacturers. This restructuring concentrates revenue recognition over longer periods and favors established service networks over pure-build specialists.
Commercial Hovercraft Market Segmentation
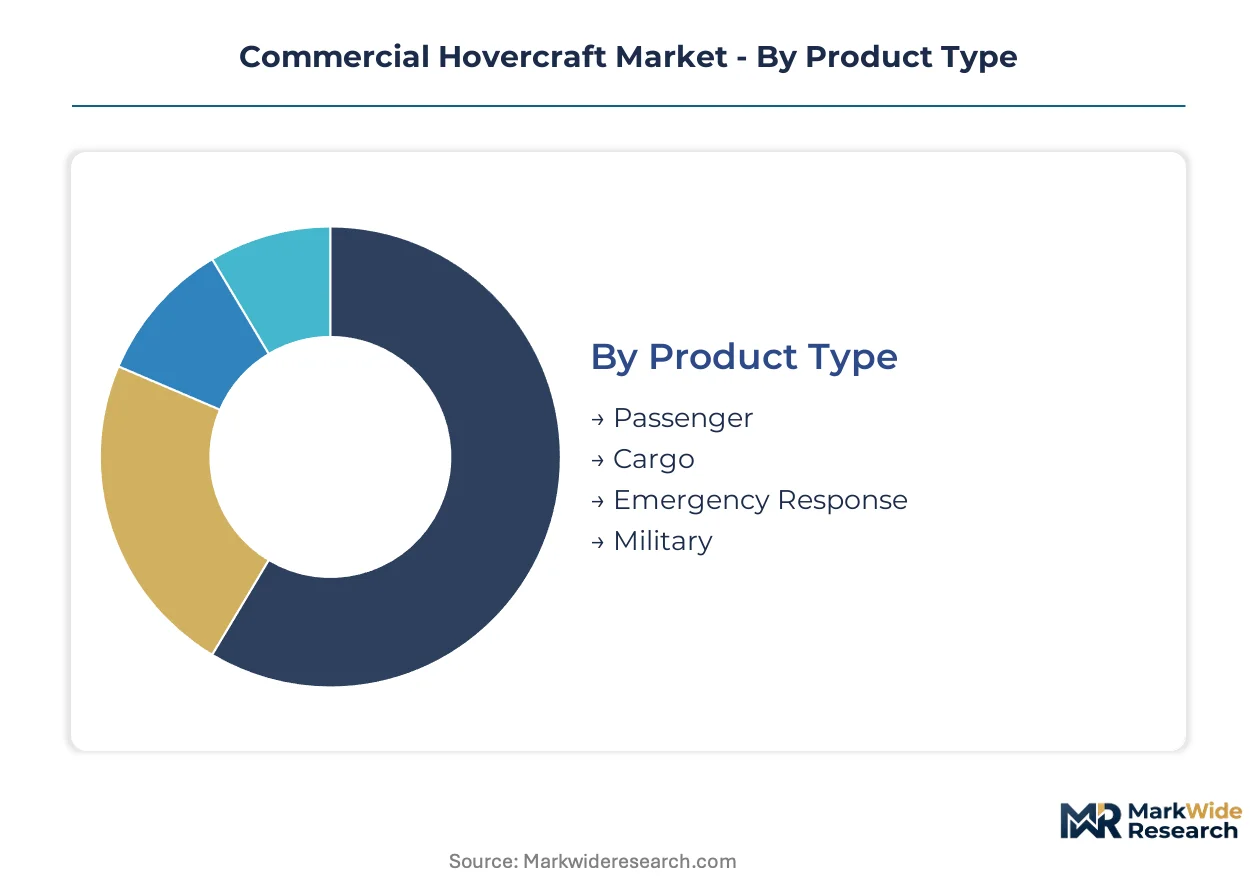
Commercial hovercraft segmentation reveals distinct operational envelopes where air-cushion physics, payload requirements, and regulatory constraints create non-overlapping procurement clusters. Each dimension governs different stages of the acquisition cycle, from hull specification through powertrain selection.
Product Type:
Standalone craft dominate fleet deployments where mission profiles remain fixed, while modular platforms serve operators rotating across multiple contract types.
- Passenger:Configurations seat 12 to 180 occupants with cabin pressurization systems rated for 500-2,500 pascal cushion pressures. Southeast Asian tourism corridors commission the largest-capacity variants for archipelago routes unreachable by conventional ferry networks. Volume placements concentrate in Passenger; the faster expansion belongs to Emergency Response.
- Emergency Response:Platforms integrate fire suppression booms, medical evacuation litters, and hazardous material containment systems within reinforced hull structures. British and Australian coast guard services specify these craft for rapid deployment in tidal zones where conventional vessels founder. Steepest expansion trajectory here reflects unbundling of single-purpose fleets into reconfigurable multi-agency assets.
- Cargo:Payload ratings span 2 to 70 tonnes with roll-on/roll-off deck configurations for intertidal logistics. Arctic supply operations in Canada and Norway drive specification demand for ice-reinforced skirt geometries.
- Military:NATO interoperability standards govern communications suites, logistics tie-down points, and defensive countermeasure mounting rails. Procurement concentrates in littoral nations expanding patrol capabilities under contested sovereignty claims.
Passenger hulls anchor current fleet totals; Emergency Response configurations climb fastest as agencies consolidate multi-mission platforms.
Application:
Commercial returns vary sharply by mission predictability, with scheduled routes supporting financing structures unavailable to contingency-dependent operations.
- Transport:Fixed-schedule inter-island services in Indonesia, the Philippines, and Scotland generate utilization rates exceeding 2,000 annual operating hours. Operators amortize skirt replacement cycles against ticket revenue rather than per-mission contracting.
- Tourism:Sightseeing circuits in Southeast Asian archipelagos and Scottish loch systems emphasize panoramic cabin glazing and reduced noise signatures. Environmental certification requirements under the EU Green Deal reshape propulsion specifications for European operators.
- Rescue Operations:Search-and-recovery missions over mudflats, ice fields, and flood zones exploit hovercraft's pressure-cushion mobility where rotary-wing assets face ceiling restrictions or fuel limitations.
- Surveillance:Coast guard and customs enforcement deployments prioritize radar integration, extended endurance, and interoperability with shore-based command networks.
Transport applications generate the densest order flow; Rescue Operations segments widen fastest as climate-related flooding expands addressable mission sets.
End User:
Procurement authority and maintenance infrastructure availability segment buyer behavior more sharply than vessel size or application type.
- Government Agencies:Defense and coast guard services specify availability-based contracting with manufacturer-retained maintenance liability, extending revenue recognition over operational-hour commitments rather than hull delivery.
- Private Operators:Independent ferry and logistics companies face capital constraints that favor smaller diesel-powered craft with established parts networks over developmental hybrid systems.
- Tourist Companies:Seasonal revenue concentration in Southeast Asian and Mediterranean markets drives leasing preferences over ownership, with skirt replacement costs borne by lessors.
- Research Institutions:Arctic and wetland ecology programs commission compact craft with minimal environmental disturbance signatures for sampling access.
Government Agencies command the largest unit volumes; Research Institutions expand most quickly as climate science funding redirects toward field-based data collection.
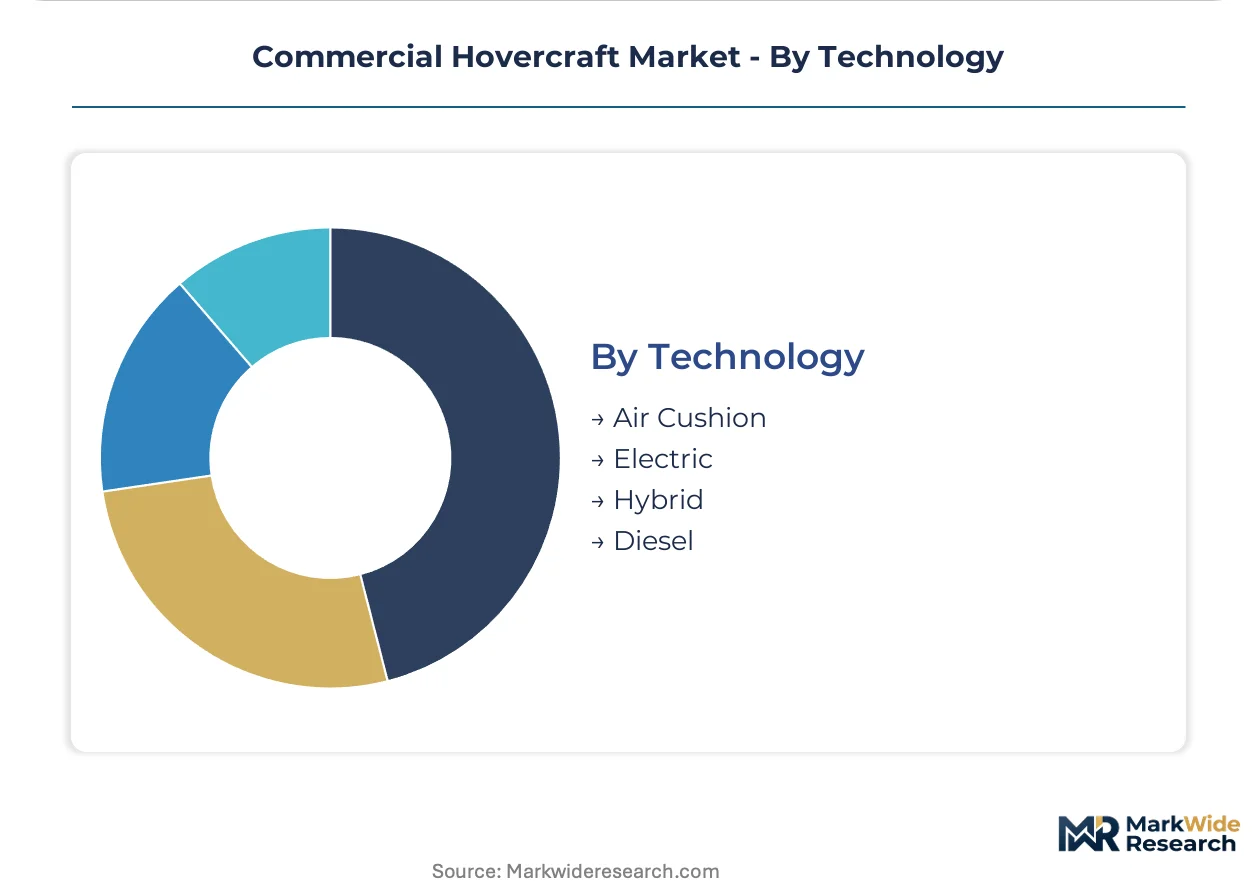
Technology:
Powertrain selection now follows regulatory geography more closely than operational requirements, with emission standards compressing diesel timelines in European markets.
- Diesel:Marine compression-ignition engines from European and Japanese suppliers retain the largest installed base despite allocation bottlenecks affecting high-horsepower variants. Supply concentration among limited engine builders exposes procurement timelines to capacity constraints.
- Hybrid:Split-architecture designs isolate battery-electric auxiliary systems for lift fans from main propulsion circuits, enabling coast guard operators in the United Kingdom and Japan to reduce fuel consumption without sacrificing patrol range. EU Green Deal mandates accelerate engineering priority for this topology.
- Air Cushion:Conventional skirt-and-fan configurations remain dominant in cost-sensitive markets where emission regulations remain unenforced or fuel subsidies persist.
- Electric:Fully battery-powered systems serve short-route tourism circuits with predictable duty cycles and shore-based charging infrastructure.
Diesel systems retain volume leadership; Hybrid architectures gain share fastest as ECHA restrictions and EU Green Deal timelines constrain conventional powertrain deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom defense procurement sustains the largest concentration of commercial hovercraft manufacturing capacity. Coast guard services across littoral nations are redirecting fleet investment toward ice-capable and hybrid-propulsion variants.
United Kingdom
Ministry of Defence contracts anchor domestic production through long-standing availability-based agreements. EU Green Deal emissions mandates pressure yards to accelerate hybrid architecture development. Griffon Hoverwork and British Hovercraft Company operations concentrate along the Solent and South Coast maritime corridor.
United States
Coast Guard and Navy procurement programs drive specification demand for NATO-interoperable patrol craft. FAA and US Coast Guard joint certification requirements extend type approval timelines. Textron Systems leverages its defense-industrial base from facilities in Louisiana and Rhode Island for naval program competition.
Canada
Arctic sovereignty patrol requirements generate demand for ice-reinforced skirt geometries and cold-weather hull designs. Canadian Coast Guard procurement aligns with NATO logistics standards for northern operations. Vancouver Island and Newfoundland shipyards specialize in seasonal ice-capable craft modification.
Australia
Outcome-based availability contracts displace conventional unit sales in naval procurement programs. Australian Border Force and maritime rescue services specify operational hours rather than hull counts. Queensland and Western Australian facilities cluster around coast guard maintenance infrastructure.
Japan
Coast Guard expansion across contested maritime zones drives patrol vessel demand. METI efficiency standards accelerate hybrid propulsion adoption in domestic yards. Nagasaki and Hiroshima prefectures concentrate manufacturing for split-architecture battery-electric auxiliary systems.
Commercial Hovercraft Market Vendor Landscape
British producers anchor the defense-contract tier; American specialists hold naval procurement positions. The vendor base splits between established defense contractors with integrated service networks and compact-craft fabricators serving private operators. Two strategic archetypes dominate: availability-contract incumbents with manufacturer-retained maintenance liability, and modular-platform specialists enabling rental fleet reconfiguration. Competitive moves concentrate on geographic licensing arrangements and hybrid propulsion technology partnerships.
Within the British defense-contract tier, Griffon Hoverwork Ltd. and The British Hovercraft Company Ltd. represent established Ministry of Defence suppliers with long-standing availability agreements. Textron Systems Corporation exemplifies the American defense-industrial archetype competing for naval procurement programs. Neoteric Hovercraft Inc. occupies a position among compact-craft specialists serving private operators and research institutions with smaller-displacement platforms.
| Leading Market Players |
|---|
| Griffon Hoverwork Ltd. |
| Neoteric Hovercraft Inc. |
| The British Hovercraft Company Ltd. |
| Textron Systems Corporation |
| Airlift Hovercraft Pty Ltd. |
| Christy Hovercraft |
| Universal Hovercraft |
| Hovertechnics LLC |
| Ivanoff Hovercraft AB |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of skirt fabrics and hull composites anchors pricing power for established British and European yards, insulating them from volatile elastomer spot markets while compressing margins for modular-component assemblers dependent on external pattern-cutting specialists. This integration choice concentrates margin capture upstream with hull fabricators and fragments profitability across downstream rental fleet operators facing recurring skirt replacement cycles.
Pricing Analysis
High-volume passenger ferry contracts trade margin for utilization certainty, while emergency response configurations sustain premium pricing through mission-critical equipment bundling and coast guard availability commitments. Three-tier pricing structure across NATO-interoperable military specifications, commercial tourism standards, and compact research-grade platforms reflects certification complexity and after-sales service depth. Cost compression in the private operator tier intensifies as shallow-draft landing craft capture intertidal transport bids at lower capital outlay. Government agencies exhibit lowest price sensitivity due to outcome-based contracting structures; tourist companies face acute sensitivity from seasonal revenue concentration.
Supply Chain Analysis
Dual-sourcing requirements from NATO procurement programs mandate qualified second sources for marine diesel engines and fire suppression systems, extending component qualification timelines. Supply concentration clusters in the United Kingdom for hull fabrication, Japan for high-horsepower compression-ignition powertrains, and Germany for elastomeric skirt compounds. Raw material dependencies center on aramid fiber reinforcements, marine-grade aluminum alloys, and hydrofluorocarbon-free fire suppression agents. Single-source vulnerability concentrates in specialized RF welding equipment for skirt segment fabrication. Distribution runs through manufacturer-direct availability contracts for defense buyers and regional leasing networks for Southeast Asian tourism operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized skirt fabrication skill scarcity props pricing for integrated hull builders while constraining capacity expansion across the sector. This bottleneck sustains margin premiums for established yards with captive technician training pipelines.
For Market Incumbents: Anticipate hybrid propulsion certification delays by pre-qualifying split-architecture battery systems with FAA and US Coast Guard joint review panels. Lock in long-term elastomer supply agreements before ECHA fluorinated compound restrictions tighten further. Vertical integration into pattern-cutting and RF welding training programs defends against technician scarcity eroding production schedules.
For New Entrants and Emerging Players: Direct-to-government digital procurement portals offer bypass routes around incumbent defense-contractor relationships for compact emergency response platforms. Arctic patrol specifications in Canada and Norway present the most penetrable geography given ice-reinforced hull demand exceeding domestic yard capacity. Target research institution leasing channels with minimal environmental disturbance signatures as a low-competition entry wedge.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense-industrial consolidators seeking availability-contract service networks. Long-term viability favors manufacturers with NATO interoperability credentials and hybrid architecture engineering depth. Watch Canadian Coast Guard procurement award timing as an inflection indicator for ice-capable craft demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Certification | FAA and US Coast Guard joint approval compresses diesel transition timelines for European builders under EU Green Deal mandates. |
| Arctic Hull Design Specialization | Canadian and Norwegian coast guard ice-reinforced specifications open premium procurement segments unavailable to temperate-climate fabricators. |
| Skirt Fabrication Training Pipeline | Captive technician development insulates production schedules from RF welding skill scarcity constraining competitor capacity. |
| Availability-Based Contracting | Outcome-based operational hour commitments transfer maintenance liability to manufacturers and concentrate revenue recognition over extended periods. |
| Emergency Response Module Unbundling | Reconfigurable fire suppression and medical evacuation systems enable rental fleet operators to serve multiple agency contracts with single platforms. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coast guard procurement officers, hovercraft fleet maintenance directors, marine diesel engine supply managers, and elastomeric fabric technical directors. Secondary sources included EU ECHA restriction dossiers, FAA type certification databases, NATO logistics standardization agreements, and British Maritime and Coastguard Agency operational records. Bottom-up hull delivery tallies by configuration type were cross-validated against top-down defense budget appropriation tracking across littoral nations.
Granularity-level modeling distinguished passenger, emergency response, cargo, and military product types; transport, tourism, rescue, and surveillance applications; and diesel, hybrid, air cushion, and electric technology segments across the analysis window. CAGRs were derived from segment-level volume trajectories weighted by end-user procurement authority and regulatory compliance timelines. Forecast inputs incorporated EU Green Deal implementation pacing, Arctic sovereignty patrol budget allocations, and Southeast Asian tourism infrastructure investment flows.
Inputs from defense procurement disclosures and coast guard fleet modernization plans were available through the study window; gaps in private operator leasing contract terms introduce uncertainty bands around commercial tourism segment projections. Deviation in NATO interoperability specification adoption timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Hydrogen Ships Market
Marine
Marine Fuel Injector Market
Marine
Ship Heat Exchanger Market
Marine
Marine Asset Integrity Services Market
Marine
Autonomous Ships Market
Marine
Electric Outboard Engines Market
Marine
Jack-Up Vessels Market
Marine
Europe ROV Market
Marine
Marine Bearings Market
Marine
Hydraulic Marine Cranes Market
Marine
Boat Ladder Market
Marine
Trim Tabs Market
Marine
Rescue Boats Market
Marine
Military Marine Engine Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Marine Auxiliary Engine Market