
 Philippines Car Rental Market | 2026-2036
Philippines Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Car Rental Market Analytics
LTFRB franchise certification is rotating the competitive landscape by filtering out unregistered operators and elevating compliance costs for new entrants. Hertz Global Holdings leverages its airport counter network to dominate Ninoy Aquino International Terminal traffic. Avis sustains brand recognition among business travelers through corporate account structures. GrabRent competes by embedding rental services within its super-app ecosystem, capturing on-demand mobility demand.
Car rental denotes the short-term commercial provision of motorized passenger vehicles, typically governed by daily or weekly rate structures and mileage allowances, for temporary transportation without ownership transfer. The fleet comprises sedans, SUVs, vans, and pickups maintained through standardized preventive maintenance cycles to ensure roadworthiness and insurance compliance. Self-drive rentals anchor volume in Metro Manila and Cebu, while chauffeur-driven services command premium pricing from corporate and diplomatic clients. Online platforms are displacing phone reservations as the dominant booking channel, driven by real-time availability dashboards and integrated payment gateways.
LTFRB franchise rules, BIR tax reporting mandates, and LTO vehicle inspection protocols collectively shape fleet renewal cycles and operator eligibility in the Philippines. These frameworks elevate capital requirements and compress margins for non-compliant independents. Stakeholders must monitor LTFRB policy shifts on ride-hailing and rental convergence, as regulatory ambiguity here will determine whether platform-integrated models gain formal operating status or face exclusion.
Market Dynamics
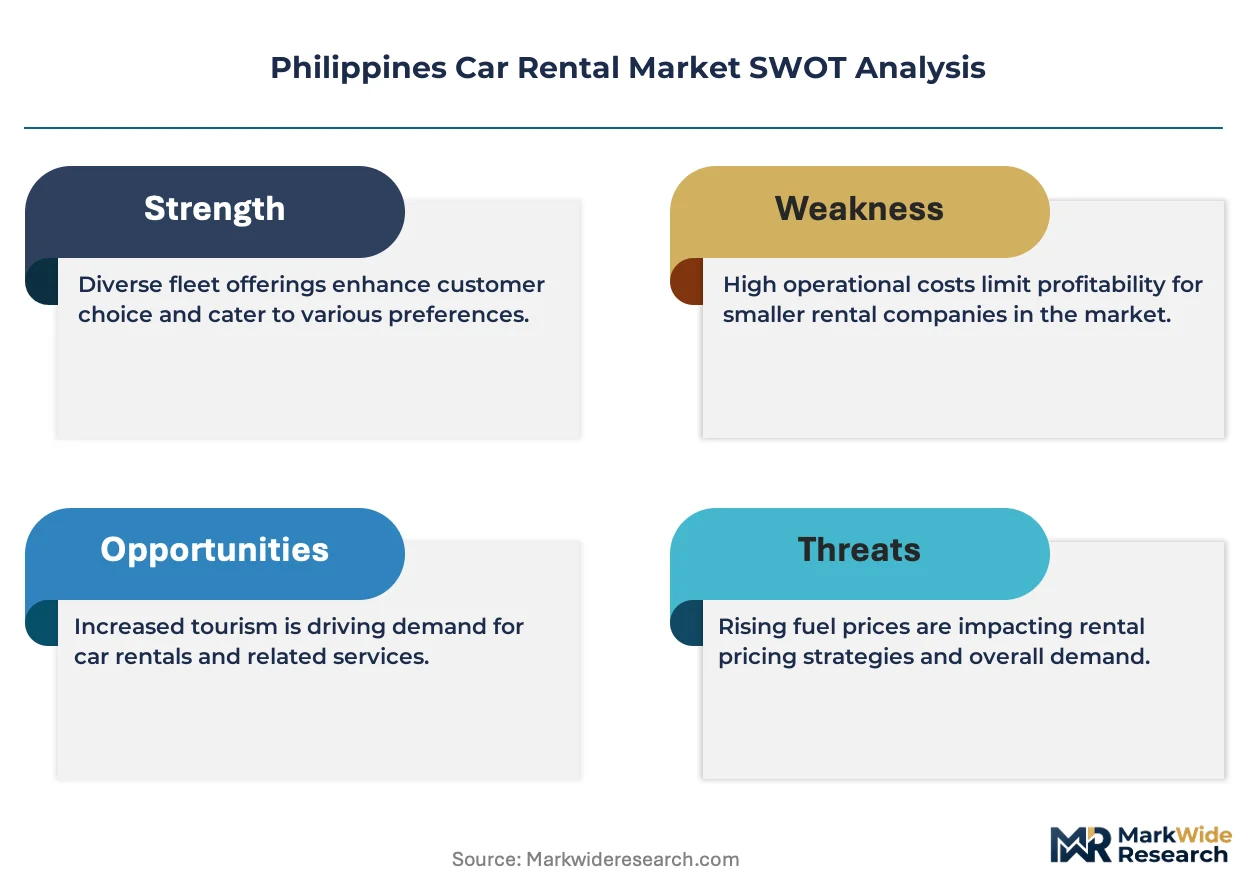
LTFRB franchise certification is compressing the independent operator base while channeling fleet investment toward compliant, newer vehicles. This regulatory tightening is simultaneously elevating barriers for marginal players and consolidating booking volume around certified networks with airport counter presence.
Growth Catalysts
- International Visitor Surge:Tourism boards in Cebu and Boracay are expanding fleet partnerships to accommodate rising foreign arrivals. These destination-specific arrangements lock in guaranteed utilization rates for certified operators.
- LTFRB Compliance Mandate:The franchising board's stricter commercial vehicle rules are filtering out unregistered competitors. Surviving operators capture displaced demand while benefiting from reduced price undercutting.
- Super-App Integration:On-demand mobility platforms are embedding rental modules within existing ride-hailing interfaces. This convergence captures impulse bookings from users already authenticated for transport services.
Market Restraints
- Vehicle Import Cost Volatility:Fleet acquisition costs fluctuate with peso-dollar exchange rates and import tariff schedules. Operators face compressed margins when replenishing units during currency weakness.
- Insurance Premium Escalation:Comprehensive commercial coverage for self-drive rentals carries steep deductibles and exclusion clauses. Underwriters price aggressively given traffic density and accident frequency in Metro Manila.
- Ride-Hailing Substitution:Point-to-point app-based transport reduces multi-day rental necessity for short-stay visitors. Tourists increasingly combine airport transfers with daily ride-hailing rather than committing to fixed rental periods.
Strategic Opportunities
- Davao Corporate Expansion:Mindanao's emerging business district generates underserved long-term lease demand. Operators establishing satellite offices there capture government and extractive industry contracts ahead of national chain penetration.
- Electric Fleet Transition:The LTO's vehicle inspection protocols are beginning to accommodate battery-electric powertrains. Early adopters positioning EV units gain preferential airport slotting and corporate sustainability credentials.
- Inter-Island Logistics Integration:Ferry-connected island-hopping itineraries create multi-leg rental requirements. Partnerships with roll-on/roll-off operators enable seamless vehicle transfer between Cebu, Bohol, and Leyte.
Industry Challenges
- LTFRB Certification Backlogs:Franchise application processing creates multi-month delays between fleet acquisition and revenue generation. Operators must carry capitalized vehicles without corresponding booking authorization.
- Technical Workforce Scarcity:Diagnostic expertise for modern engine management and telematics systems concentrates in Metro Manila. Provincial maintenance facilities struggle to perform warranty-compliant repairs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Car Rental Market |
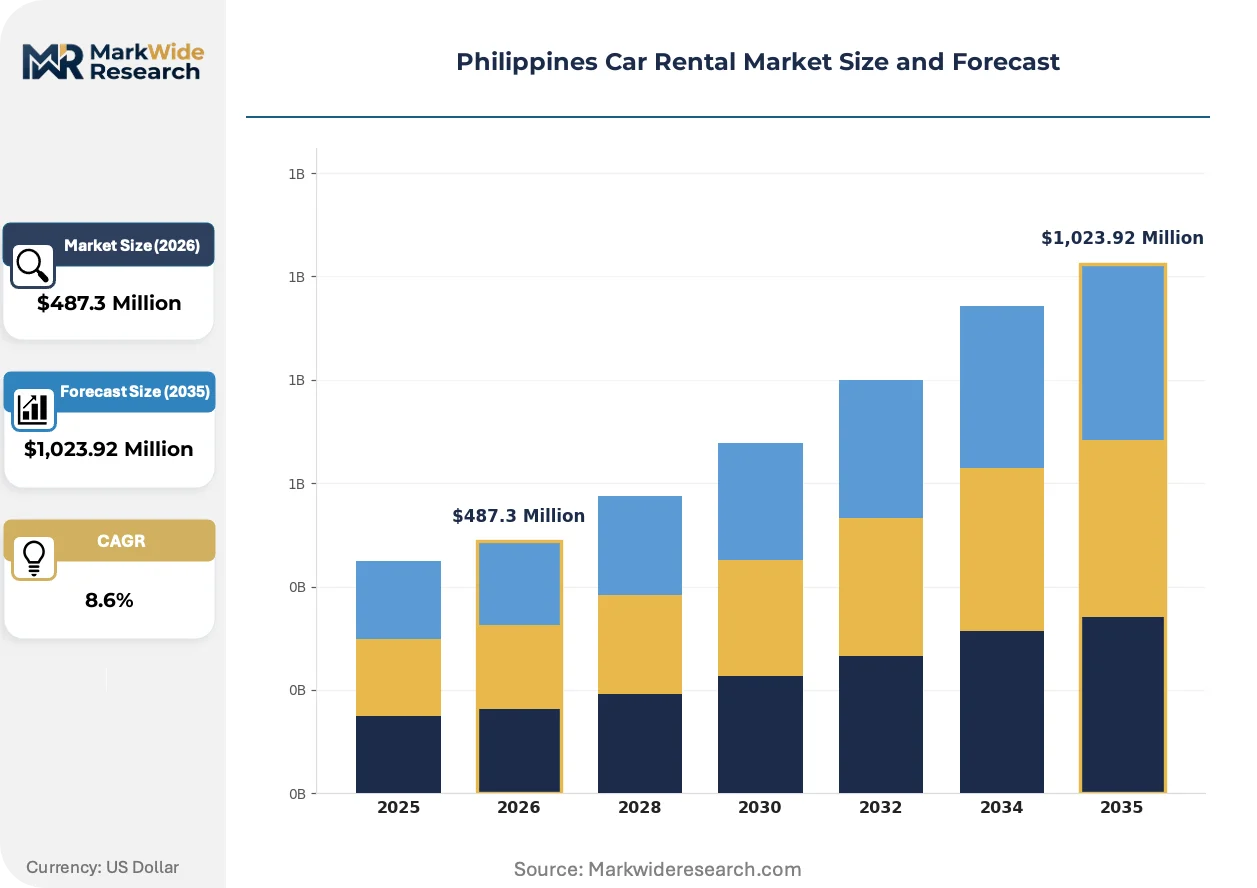
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Chauffeur-Driven, Luxury Rentals, Corporate Rentals Vehicle Type: Sedan, SUV, Van, Pickup Booking Channel: Online Platforms, Travel Agencies, Direct Rental, Phone Reservations Customer Type: Tourists, Business Travelers, Local Residents, Event Organizers |
| Companies Covered | Hertz Global Holdings, Sixt, Avis, GrabRent, Diamond Car Rental, Enterprise Holdings, Budget, National Car Rental, Europcar Mobility Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Car Rental Market Evolving Landscape
Digital booking infrastructure is displacing voice reservations as the dominant customer interface. Real-time availability dashboards and integrated payment gateways are compressing the path from search to confirmation.
Telematics hardware is miniaturizing to plug-and-play OBD-II dongles that eliminate professional installation costs. Budget rental fleets are adopting these self-installed units to track location, fuel levels, and driving behavior without vehicle downtime. This capability is miniaturizing the operational gap between large networked operators and independent single-location competitors.
LTFRB policy development is converging ride-hailing and rental regulations into unified commercial transport frameworks. The franchising board's draft guidelines create ambiguity around whether platform-integrated rental models require separate certification or fall under existing ride-hailing permits. Metro Manila operators with established airport counter infrastructure are most exposed to potential reclassification requirements.
Corporate procurement departments are consolidating travel spend under managed service contracts with preferred rental suppliers. Fixed monthly rates and consolidated billing replace transaction-by-transaction booking for frequent business travelers. This concentration is most visible among business process outsourcing firms with large expatriate workforces in Cebu and Clark Freeport Zone.
Philippines Car Rental Market Segmentation
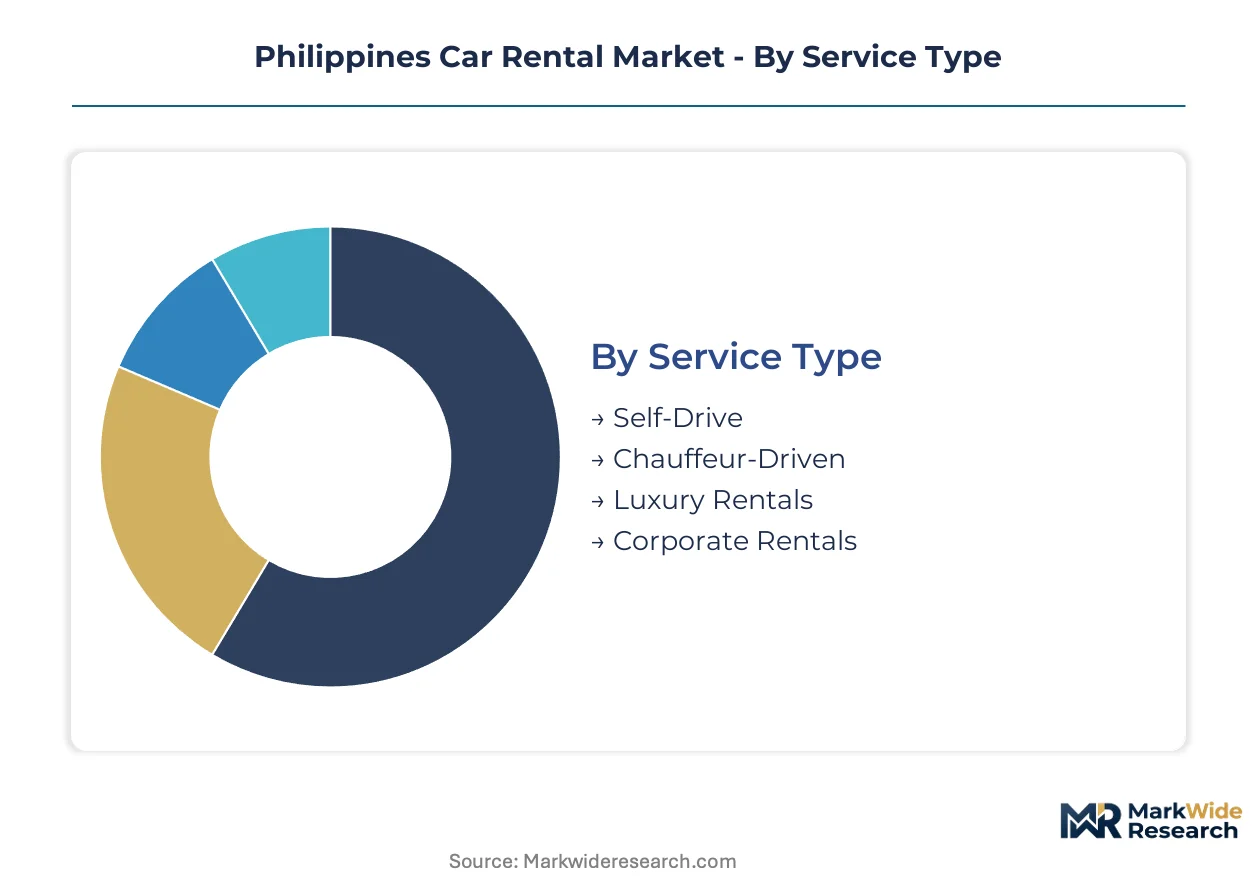
Segmentation in the Philippines car rental market reveals how LTFRB compliance requirements and digital platform penetration reshape channel economics across service tiers. Understanding these splits helps operators allocate fleet capital toward certified segments with sustainable margin structures.
Service Type:
Self-drive bookings flow predominantly through online platforms and airport counters, while chauffeur-driven services concentrate around corporate procurement desks and diplomatic channels.
- Self-Drive:Customers retain full vehicle control under standardized insurance frameworks with mileage ceilings. Demand clusters in Metro Manila and Cebu among domestic tourists and business travelers seeking multi-day flexibility without driver costs.
- Chauffeur-Driven:Professional drivers handle navigation and parking in dense urban corridors. Corporate accounts in Makati and Bonifacio Global City drive volume for executive transport and client entertainment.
- Luxury Rentals:Premium vehicles with enhanced concierge support serve wedding planners and high-net-worth visitors in Boracay and Palawan.
- Corporate Rentals:Long-term fixed-rate contracts with consolidated billing support BPO expatriate mobility in Clark Freeport Zone and Cebu IT Park.
By volume, Self-Drive leads. By growth pace, Corporate Rentals is climbing the fastest as outsourcing firms expand provincial operations.
Vehicle Type:
Fleet composition tracks terrain diversity across the Philippine archipelago, with operators balancing highway efficiency against island-hopping durability requirements.
- Sedan:Compact and mid-size passenger cars optimize fuel economy for urban corridors and paved intercity routes. Metro Manila self-drive bookings favor this segment for parking maneuverability in congested CBD districts.
- SUV:Elevated ground clearance and all-weather capability address provincial road conditions. Mindanao corporate contracts and Cebu family tourism generate disproportionate SUV demand.
- Van:Multi-passenger configurations serve group travelers and event logistics across ferry-connected islands.
- Pickup:Dual-cab utility vehicles support construction and extractive industry site access in Davao and Cagayan de Oro.
Sedan fleets carry the largest unit counts. SUV deployment is expanding most quickly as operators upgrade to LTFRB-compliant vehicles with enhanced safety ratings.
Booking Channel:
Channel mix reflects generational divides in payment behavior and authentication comfort, with super-app ecosystems capturing authenticated users from adjacent mobility services.
- Online Platforms:Real-time availability dashboards with integrated GCash and Maya payment rails dominate Metro Manila and Cebu bookings. GrabRent and similar super-apps leverage existing user verification to compress booking friction.
- Travel Agencies:Package tour operators in Boracay and Palawan bundle ground transport with accommodation, guaranteeing fleet utilization during peak seasons.
- Direct Rental:Walk-in counter traffic persists at Ninoy Aquino International Terminal and Mactan-Cebu International Airport for unplanned extensions.
- Phone Reservations:Voice booking retains share among corporate travel coordinators managing complex multi-city itineraries.
Online Platforms command the transaction volume lead. Direct Rental at airport counters maintains the steepest expansion trajectory as international visitor arrivals recover.
Customer Type:
Customer segments diverge sharply in booking lead time, insurance requirements, and price sensitivity, forcing operators to maintain parallel reservation systems.
- Tourists:Foreign visitors from East Asian and Western markets combine short-term rentals with domestic flight connections. Cebu and Boracay tourism boards channel these bookings through certified operator partnerships.
- Business Travelers:Frequent flyers with managed travel policies prioritize airport counter proximity and express checkout. Makati and Ortigas CBD concentrations drive weekday demand patterns.
- Local Residents:Filipinos seeking temporary vehicles for family events or vehicle maintenance periods. Price sensitivity pushes this segment toward independent operators with lighter compliance burdens.
- Event Organizers:Wedding planners and conference coordinators in Tagaytay and Batangas require coordinated multi-vehicle logistics with uniform branding.
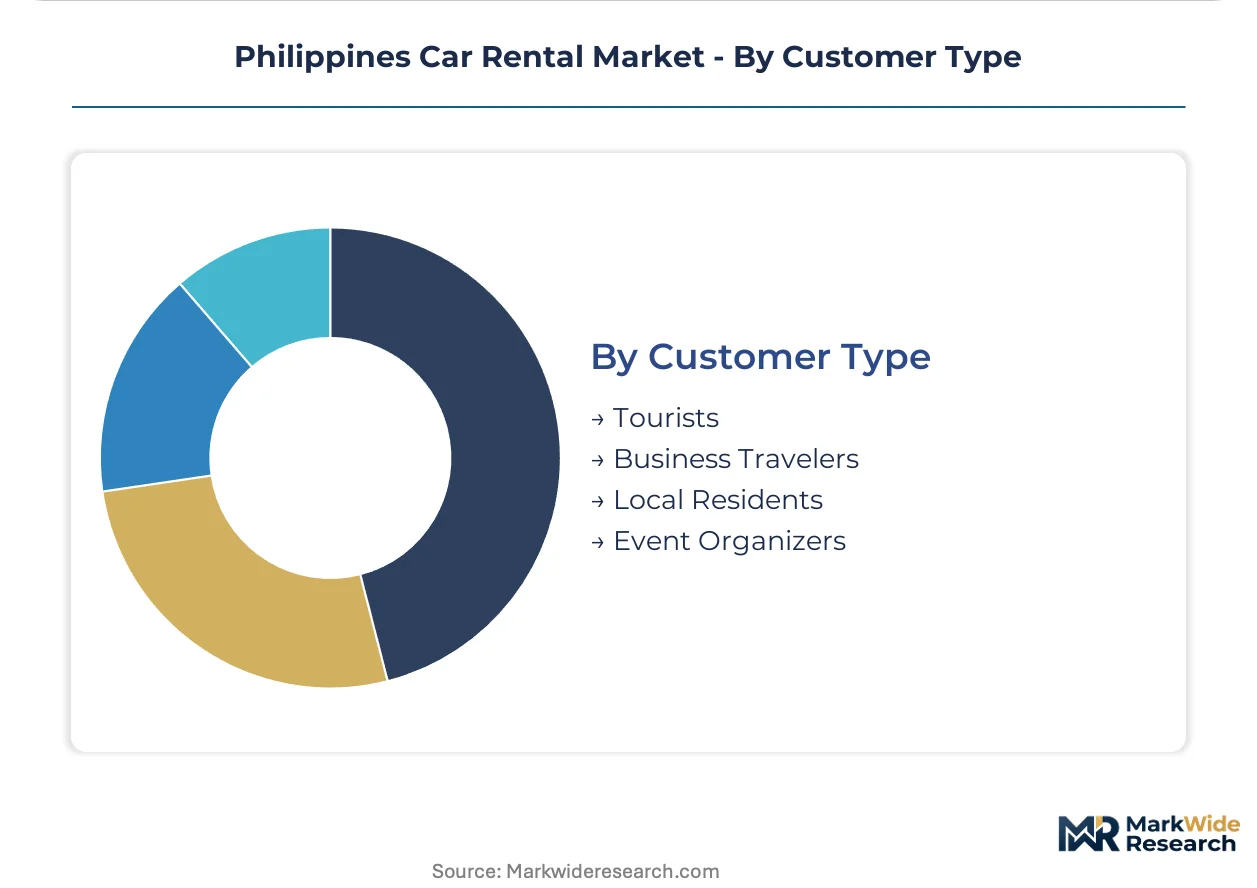
Tourists generate the highest transaction frequency. Local Residents represent the segment gaining share fastest as ride-hailing substitution pushes multi-day rental consideration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement desks and tourism boards concentrate fleet demand in three distinct Philippine sub-markets. Each geography exhibits unique booking patterns shaped by local infrastructure and LTFRB enforcement intensity.
Metro Manila
Business travelers from Makati and Ortigas CBDs drive weekday self-drive volume. LTFRB franchise certification requirements filter out unregistered operators in Quezon City and Pasay. Ninoy Aquino International Terminal anchors airport counter traffic for international arrivals seeking immediate vehicle access.
Cebu
Family tourism and IT Park expatriate mobility generate dual demand streams for SUVs and sedans. The provincial government partners with certified operators to guarantee fleet availability during Sinulog Festival peaks. Mactan-Cebu International Airport serves as the primary booking origination point for island-hopping itineraries.
Davao
Mindanao's emerging business district creates underserved long-term lease demand from government and extractive industry contractors. LTFRB processing backlogs delay franchise authorization for new entrants. Davao City operators capture provincial corporate accounts ahead of national chain satellite office deployment.
Clark Freeport Zone
BPO expatriate workforces require coordinated multi-vehicle logistics under managed service contracts. The national government's infrastructure investment elevates road connectivity to Subic and Manila. Angeles City-based fleet operators specialize in corporate sustainability credentials and consolidated billing structures.
Philippines Car Rental Market Competitive Landscape
Player mix skews toward international airport-counter networks and platform-integrated super-apps. The competitive structure stratifies across three tiers: global brands with physical counter presence, domestic independents with lighter compliance burdens, and technology platforms embedding rental modules within existing mobility ecosystems. Consolidation pressure intensifies as LTFRB certification costs rise. Dominant competitive moves include airport slot acquisition and super-app partnership negotiations.
Within the global brand tier, Hertz Global Holdings and Avis exemplify airport-counter dominance through Ninoy Aquino and Mactan-Cebu International Terminal positioning. GrabRent occupies the platform-integrated archetype, leveraging existing user authentication from ride-hailing services to compress booking friction. Diamond Car Rental represents domestic specialist positioning with lighter LTFRB compliance structures serving provincial price-sensitive segments.
| Leading Market Players |
|---|
| Hertz Global Holdings |
| Sixt |
| Avis |
| GrabRent |
| Diamond Car Rental |
| Enterprise Holdings |
| Budget |
| National Car Rental |
| Europcar Mobility Group |
| Others |
Value Network & Pricing Analysis
Telematics-enabled fleet management systems are displacing traditional manual tracking infrastructure across Philippine rental operations, simultaneously concentrating supply relationships with hardware-software integrated vendors and compressing per-unit operational costs that feed into rate competitiveness.
Pricing Analysis
Cost-plus contracts with fuel indexation dominate long-term corporate lease arrangements, insulating operators from peso-dollar volatility while passing through commodity swings to enterprise clients. Price differentiation hinges on LTFRB certification tier and airport counter proximity, with Ninoy Aquino Terminal operators commanding sustained premiums over street-location independents. Cost compression in the self-drive segment is intensifying because super-app platforms aggregate demand and standardize rate transparency. Local residents exhibit the highest price sensitivity, filtering toward unregistered provincial operators, while diplomatic and corporate accounts show minimal elasticity due to compliance requirements and consolidated billing convenience.
Supply Chain Analysis
Japan and South Korea anchor the upstream production of compact sedans and SUVs entering Philippine rental fleets, with Thailand serving as the regional assembly hub for ASEAN-market vehicles. Fleet acquisition draws from knock-down kit imports, complete built-up units, and domestic reconditioning facilities. Single-source vulnerability concentrates around Japanese OEM distribution networks for spare parts and warranty-compliant components. Distribution runs through franchised dealer networks for new vehicle procurement, supplemented by secondary auction channels for fleet refresh cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines car rental market sits at a regulatory inflection where LTFRB certification convergence with ride-hailing frameworks threatens to reclassify platform-integrated operators overnight. This disruption elevates strategic urgency for position-taking ahead of formal rule issuance.
For Market Incumbents: Fortify airport counter infrastructure at Ninoy Aquino and Mactan-Cebu International Terminal to lock in arrival-channel dominance before super-app reclassification uncertainty resolves. Deepen backward integration into in-house preventive maintenance facilities to reduce provincial technical workforce dependency and compress warranty compliance costs. The priority lever rests on securing LTFRB franchise fast-track relationships that accelerate fleet authorization timelines relative to capital carrying periods. For New Entrants and Emerging Players: LTFRB certification fast-tracks through provincial satellite offices in Davao and Cagayan de Oro present the most penetrable pathway, exploiting multi-month processing backlogs that delay national chain expansion. Target Mindanao government and extractive industry corporate accounts ahead of established Metro Manila operator satellite deployment. The optimal go-to-market angle combines chauffeur-driven service entry with super-app partnership negotiations that secure provisional operating status under existing ride-hailing permits. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated regional specialists with established LTFRB compliance and airport slot control. Long-term viability over the medium horizon hinges on positioning ahead of formal ride-hailing rental convergence rules. Acquisition targets should prioritize operators with certified fleet scale in Cebu and Clark Freeport Zone. The signal to watch is LTFRB draft guideline publication timing on platform-integrated model classification.| Strategic Initiative | Industry Significance |
|---|---|
| Airport Counter Slot Acquisition | Secures Ninoy Aquino and Mactan-Cebu arrival-channel dominance against super-app displacement. |
| LTFRB Certification Fast-Track Investment | Compresses franchise authorization timelines and reduces capitalized vehicle carrying periods. |
| Super-App Partnership Negotiation | Positions rental modules within GrabRent authentication flows for impulse booking capture. |
| Electric Fleet Pilot Deployment | Gains preferential airport slotting and corporate sustainability credentials under LTO protocols. |
| Provincial Maintenance Facility Buildout | Reduces Metro Manila diagnostic expertise dependency for warranty-compliant repairs. |
Research Methodology
A spread of perspectives from fleet operations managers, LTFRB regulatory affairs officers, airport concession administrators, and corporate travel procurement leads converged on the working assumptions underlying this study. Primary field engagement combined structured interviews with secondary validation through LTFRB franchise registry data, Bureau of Customs import records, and Ninoy Aquino International Terminal concession disclosures. Bottom-up fleet counts and top-down tourism arrival projections were triangulated against operator revenue benchmarks.
Segmentation dimensions modeled span service type, vehicle class, booking channel, customer archetype, and regional regulatory enforcement intensity across the projection horizon. CAGRs were derived from historical fleet expansion trajectories, visitor arrival elasticity coefficients, and LTFRB compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated super-app penetration rates and electric vehicle inspection protocol adoption curves.
Decision-makers should treat outputs as directional under stable LTFRB policy and peso-dollar exchange assumptions; material deviation in ride-hailing rental convergence rules or currency volatility would warrant model refresh. Recalibration cycles align with material shifts in franchise processing timelines, international visitor arrival patterns, and platform-integrated operating status determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
India Car Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Truck Rental Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Ship Management Software Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Spain Car Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Russia Car Rental Market
Transportation Services
Germany Car Rental Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Full-Service Carrier Market