
 North America Hovercraft Market | 2026-2036
North America Hovercraft Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hovercraft Market Insights
Aftermarket service revenue is tilting toward military platform sustainment as defense operators extend fleet lifecycles rather than replace aging air-cushion vehicles. Textron Systems leverages its integrated logistics support contracts to capture recurring maintenance streams across Marine Corps and Coast Guard programs. Neoteric Hovercraft anchors the commercial segment with specialized designs for shallow-water patrol and ice rescue missions.
A hovercraft generates lift by forcing air beneath a flexible skirt, creating a pressurized cushion that reduces friction and enables travel over water, ice, mud, and uneven terrain at speeds typically ranging from 35 to 70 knots. The technology serves critical functions where conventional vessels or land vehicles cannot operate, including flood rescue, amphibious assault, and remote cargo delivery to unprepared shorelines. Military applications dominate current procurement volumes, while electric and hybrid propulsion systems represent the fastest-growing technology segment as operators seek to comply with tightening emissions rules. Cargo configurations command premium pricing due to specialized hull reinforcement requirements and limited supplier competition.
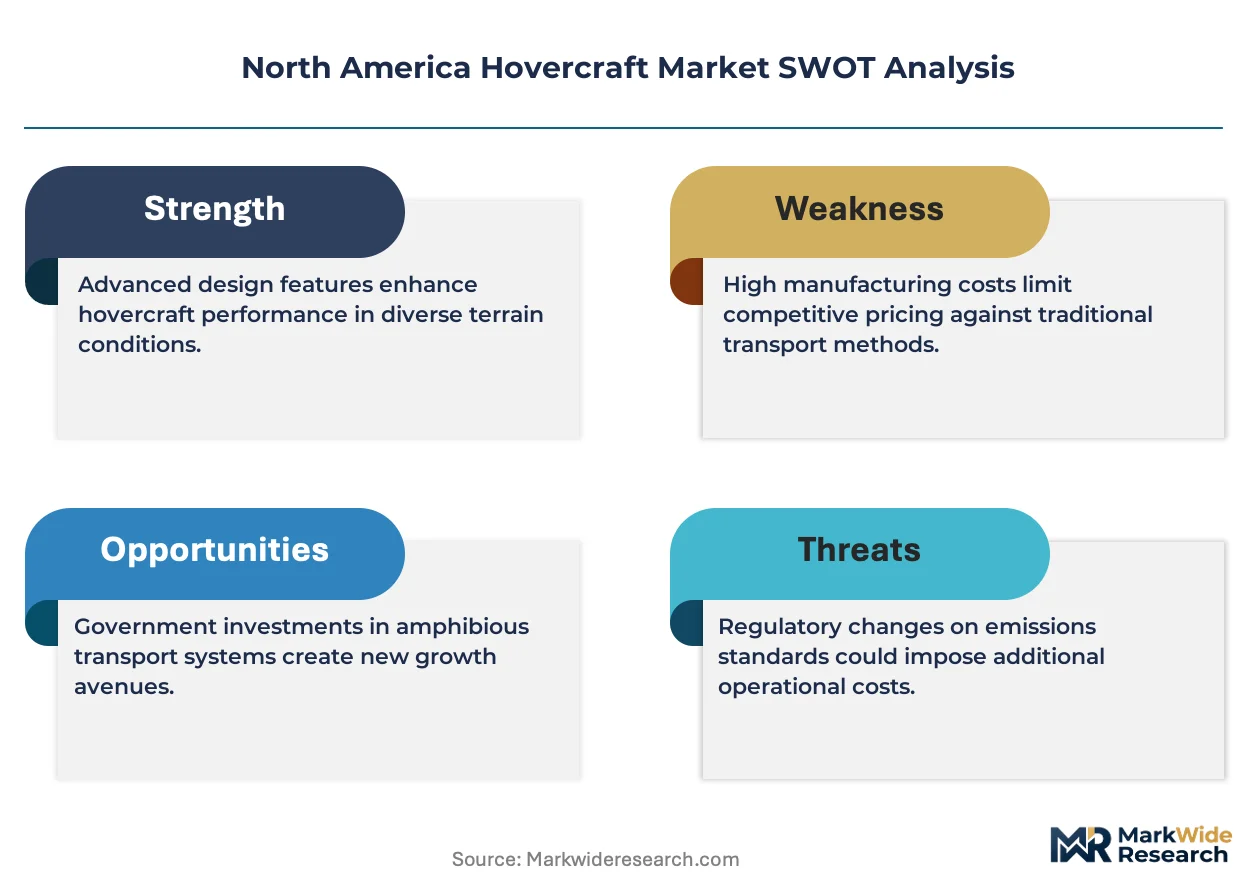
The U.S. Coast Guard enforces structural fire-safety and stability standards that shape hull material selection and skirt durability specifications for commercial operators. EPA Tier 4 marine engine regulations and Transport Canada equivalent standards are forcing propulsion system redesigns across the installed base. Stakeholders must monitor evolving zero-emission mandates in California and British Columbia, as these jurisdictions often prefigure broader North American regulatory shifts that could accelerate electric hovercraft adoption timelines.
Market Dynamics
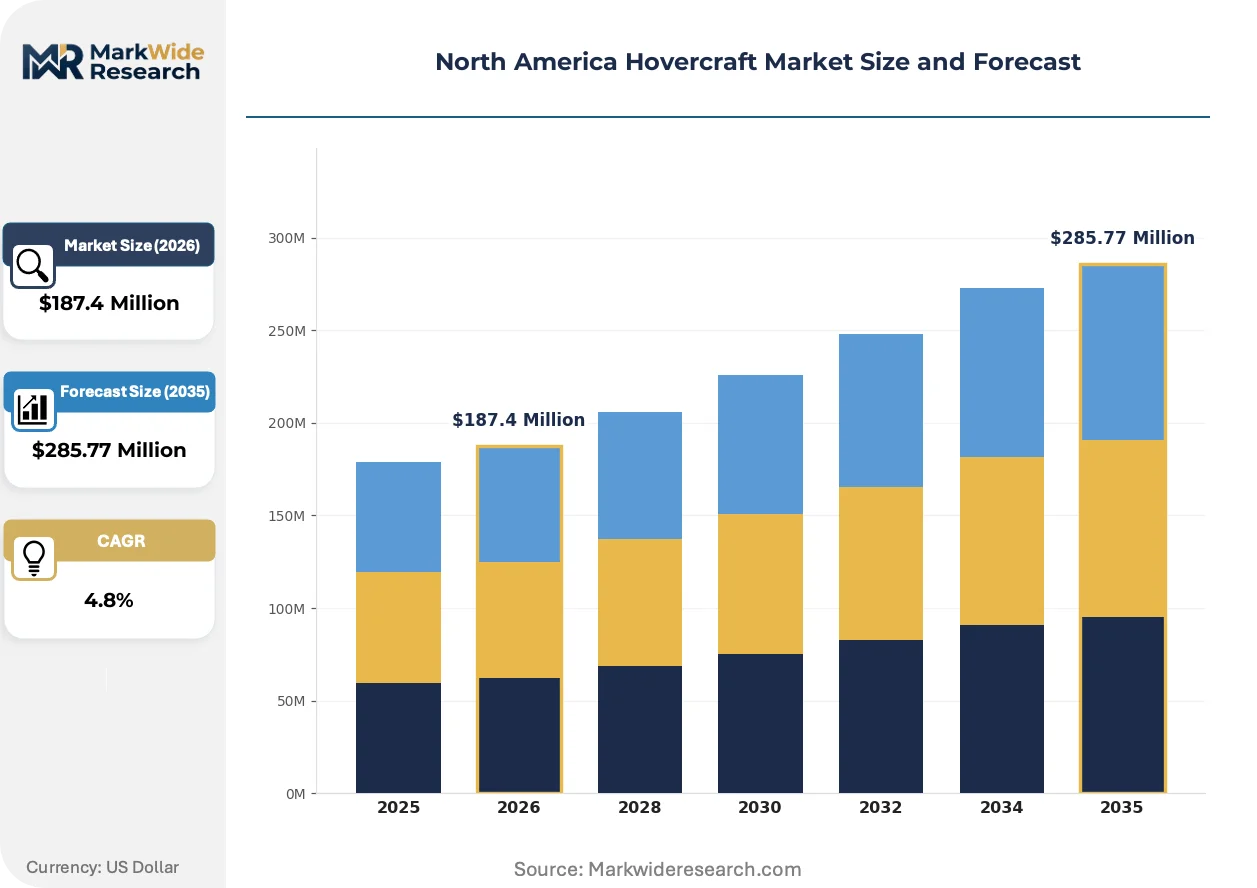
The North America hovercraft market is pivoting around the collision between tightening EPA Tier 4 marine emissions mandates and the operational necessity of air-cushion mobility in littoral and marshland environments where conventional vessels cannot function.
Growth Catalysts
- Amphibious assault modernization:The United States Marine Corps is accelerating procurement of next-generation landing craft to replace aging LCAC fleets, creating sustained demand for heavy-lift air-cushion platforms with hardened hull configurations.
- Offshore energy logistics:Gulf Coast operators deploy hovercraft for crew transport across marshland terrain inaccessible to conventional boats, driven by deepwater drilling expansion in Louisiana and Texas coastal zones.
- Electric propulsion maturation:Battery energy density improvements and modular electric drivetrains are enabling zero-emission variants that satisfy emerging state-level zero-emission mandates in California and British Columbia.
Market Restraints
- Skirt material cost volatility:Reinforced neoprene and hypalon fabrics face petroleum-derived input price swings, compressing margins for commercial operators who cannot pass costs to fixed-price military contracts.
- Canadian procurement concentration:Canadian Coast Guard and Department of National Defense represent the dominant public-sector demand pool north of the border, creating single-buyer dependency risk for suppliers without US diversification.
- Diesel outboard substitution:Shallow-draft aluminum airboats with surface-piercing propellers offer comparable marshland access at lower capital cost, capturing price-sensitive search-and-rescue and survey applications.
Strategic Opportunities
- Arctic domain awareness gaps:Canadian Northern territories and Alaska require ice-capable patrol platforms for sovereignty enforcement where seasonal ice breakup prevents conventional vessel operations eight months annually.
- Hybrid-electric retrofit kits:Converging battery storage and range-extender generator technologies enable mid-life propulsion upgrades for installed military fleets, extending platform relevance under tightening emissions rules.
- FEMA disaster response prepositioning:Emergency management agencies in hurricane-prone US Southeast states are establishing hovercraft rapid-response units for flood rescue in urban environments where road infrastructure fails.
Industry Challenges
- Marine engineer specialization scarcity:Air-cushion vehicle design requires hybrid expertise in naval architecture, aerospace structures, and skirt aerodynamics that conventional marine engineering programs do not produce.
- Coast Guard certification timelines:Subchapter T small passenger vessel approvals and structural fire-safety compliance reviews extend commercial product launch cycles by 18-24 months versus comparable military programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hovercraft Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger, Cargo, Military, Emergency Application: Transportation, Rescue Operations, Tourism, Research End User: Government Agencies, Commercial Operators, Private Owners, Research Institutions Technology: Hydrofoil, Air Cushion, Electric, Hybrid |
| Companies Covered | Textron Systems, Neoteric Hovercraft, Universal Hovercraft of America, Airlift Hovercraft, Vanair Hovercraft, Hovertechnics, Christy Hovercraft, The British Hovercraft Company, Griffon Hoverwork, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hovercraft Market Trends and Innovations
Propulsion electrification and skirt material advances are compressing the performance gap between military and commercial platforms, while regulatory pressure on emissions is forcing redesign cycles that favor modular, upgradeable architectures over purpose-built legacy systems.
Hybrid-electric drivetrains combining lithium-ion battery packs with downsized diesel range extenders are rendering obsolete pure mechanical transmission systems in medium-lift hovercraft categories. US Coast Guard search-and-rescue operators and Canadian Coast Guard ice patrol units are piloting these configurations for reduced acoustic signature and fuel consumption. The technology is rendering obsolete the traditional trade-off between endurance and emissions compliance that constrained operational profiles in environmentally sensitive waterways.
EPA Tier 4 Final marine engine standards and Transport Canada equivalent regulations are compelling propulsion system redesigns across the installed base. Manufacturers must integrate selective catalytic reduction or exhaust gas recirculation into compact marine diesel packages without compromising power-to-weight ratios critical to air-cushion lift generation. Cargo and heavy-lift military segments face the steepest compliance costs, accelerating interest in battery-electric alternatives for shorter-range missions.
Service contracting is displacing platform ownership in commercial segments where capital constraints limit fleet expansion. Offshore logistics operators in the US Gulf Coast and environmental survey contractors in the Canadian Arctic are migrating toward availability-based agreements where maintenance, spare skirt inventory, and crew training bundle into per-hour operating fees. This shift concentrates most visible in Louisiana marshland transport and British Columbia coastal access contracts where operational predictability outweighs asset control preferences.
North America Hovercraft Market Segmentation
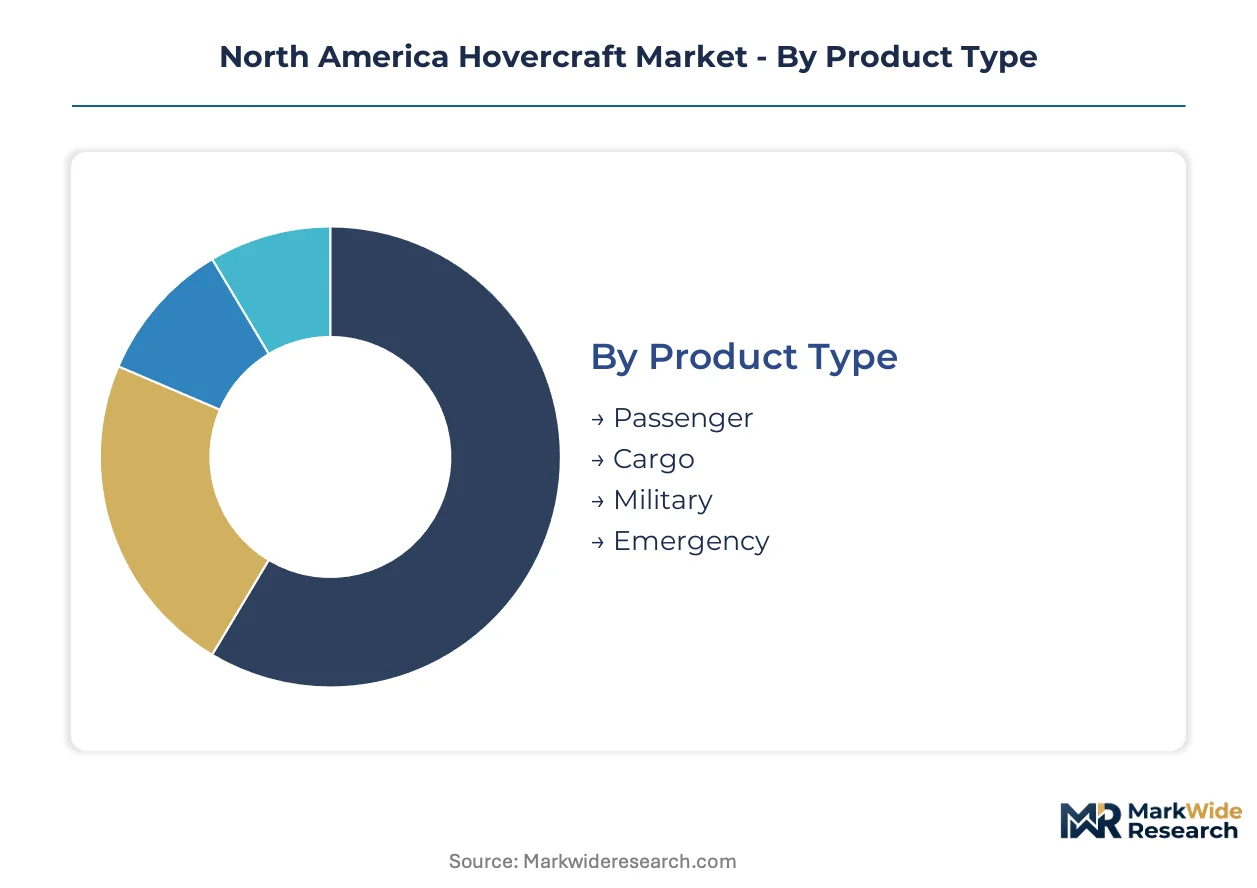
Hovercraft segmentation reveals divergent service intensity patterns across product categories. Military platforms demand integrated logistics support contracts spanning decades, while commercial segments favor availability-based fee structures that bundle maintenance with operational hours.
Product Type:
After-sales service intensity varies dramatically across product categories, with military platforms requiring decades of sustainment engineering versus commercial units needing rapid skirt replacement turnaround.
- Military:Heavy-lift amphibious landing craft with hardened hull configurations support Marine Corps expeditionary operations. Procurement concentrates through US Navy and Canadian Department of National Defense programs, where fleet lifecycle extensions drive aftermarket revenue concentration.
- Cargo:Reinforced hull structures accommodate remote logistics to unprepared shorelines across Louisiana marshlands and Arctic coastal zones. Gulf Coast offshore operators deploy these for crew transport where conventional vessels cannot navigate, though petroleum-derived skirt material costs compress margins.
- Passenger:US Coast Guard Subchapter T certified vessels serve small-capacity transport routes.
- Emergency:Rapid-response configurations support FEMA flood rescue operations in hurricane-prone Southeast states.
Military holds the largest share; momentum sits with Cargo as offshore energy logistics expand.
Application:
Cost tier stratification separates mission-critical defense applications from price-sensitive commercial deployments.
- Rescue Operations:Ice rescue and flood response platforms operate in environments where seasonal conditions preclude conventional vessel access eight months annually. Canadian Coast Guard and US Coast Guard units prioritize reduced acoustic signature through hybrid-electric configurations.
- Transportation:Marshland crew movement across Texas and Louisiana coastal zones demands shallow-draft capability that diesel outboard airboats cannot match for heavy payloads.
- Tourism:Sightseeing operations concentrate in British Columbia coastal access corridors.
- Research:Environmental survey contractors in the Canadian Arctic deploy availability-based service contracts rather than platform ownership.
Transportation holds the largest share; Rescue Operations are gaining share fastest through federal emergency preparedness funding.
End User:
Customer type determines procurement modality, with government agencies favoring multi-year platform acquisitions and commercial operators migrating toward service-based agreements.
- Government Agencies:US Marine Corps, US Coast Guard, and Canadian Coast Guard dominate public-sector demand through structured procurement programs with embedded logistics support. EPA Tier 4 and Transport Canada emissions standards shape technical specifications.
- Commercial Operators:Offshore logistics providers in the Gulf Coast and environmental survey firms in the Canadian Arctic favor per-hour operating fees that bundle maintenance and crew training.
- Private Owners:Limited to specialized recreational and private security applications.
- Research Institutions:Arctic domain awareness programs require ice-capable patrol platforms for sovereignty enforcement.
Government Agencies hold the largest share; Commercial Operators show the steepest expansion trajectory as service contracting displaces ownership.
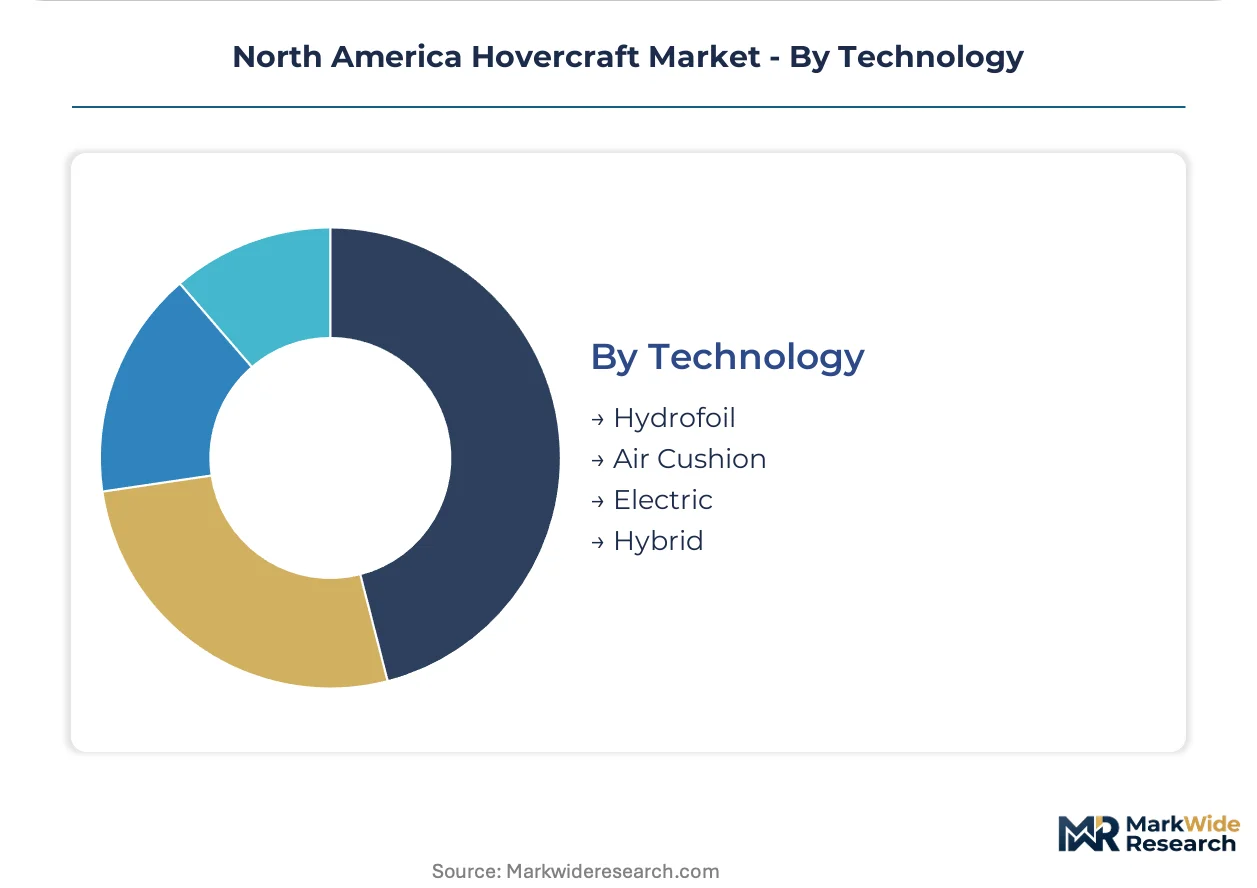
Technology:
Technology maturity curves separate proven air-cushion architectures from emerging electric configurations facing certification timeline extensions.
- Hybrid:Lithium-ion battery packs combined with downsized diesel range extenders enable zero-emission operation during sensitive missions while preserving endurance. US and Canadian Coast Guard pilot programs validate reduced fuel consumption and acoustic signature for search-and-rescue and ice patrol.
- Electric:Battery energy density improvements support short-range missions in California and British Columbia waterways where state-level zero-emission mandates apply. Cargo and heavy-lift segments face power-to-weight constraints that slow adoption.
- Air Cushion:Conventional diesel-mechanical systems remain dominant in heavy-lift military categories despite emissions compliance costs.
- Hydrofoil:Hybrid surface-piercing configurations serve niche high-speed transport applications.
Air Cushion holds the largest share; Hybrid is climbing the fastest as emissions regulations tighten across the installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes hovercraft primarily for military expeditionary operations and Gulf Coast offshore logistics, while Canada deploys them for Arctic sovereignty patrol and ice rescue missions where seasonal ice prevents conventional vessel access.
United States
The US Marine Corps drives demand through next-generation landing craft procurement to replace aging LCAC fleets, while Gulf Coast operators deploy units for Louisiana marshland crew transport. EPA Tier 4 marine engine regulations force propulsion system redesigns across military and commercial fleets. Deepwater drilling expansion in Texas and Louisiana coastal zones concentrates operational deployment.
Canada
Canadian Coast Guard and Department of National Defense represent the dominant public-sector demand pool for ice-capable patrol platforms. Transport Canada emissions standards equivalent to EPA Tier 4 shape technical specifications for new procurements. Northern territories require sovereignty enforcement capabilities where seasonal ice breakup blocks conventional vessels eight months annually.
Mexico
Limited hovercraft deployment concentrates on coastal surveillance and limited offshore logistics support. The country's national maritime regulator oversees safety certifications for commercial operations. Gulf of Mexico energy infrastructure near Veracruz and Tabasco states generates nascent demand for marshland access capabilities.
North America Hovercraft Market Competitive Landscape
Capability concentration sits with defense-integrated tier; scale advantage sits with specialized commercial fabricators. The market structure divides between military platform sustainment contractors and commercial segment specialists serving rescue and transport applications. Three archetypes dominate: integrated defense logistics providers, commercial specialty builders, and regional service contractors. Competitive moves center on fleet lifecycle extension contracts and hybrid-electric propulsion partnerships.
Among defense-integrated contractors, Textron Systems anchors military platform sustainment through embedded logistics support agreements. Neoteric Hovercraft and Universal Hovercraft of America exemplify the commercial specialty tier, occupying positions in shallow-water patrol and ice rescue mission sets. These named entities represent the capability-scale divide without exhaustive market coverage.
| Leading Market Players |
|---|
| Textron Systems |
| Neoteric Hovercraft |
| Universal Hovercraft of America |
| Airlift Hovercraft |
| Vanair Hovercraft |
| Hovertechnics |
| Christy Hovercraft |
| The British Hovercraft Company |
| Griffon Hoverwork |
| Others |
Pricing and Supply Chain Analysis
Petroleum-derived skirt material volatility compresses margins unevenly across pricing tiers while forcing supply chain consolidation toward vertically integrated fabricators with captive neoprene and hypalon sourcing. EPA Tier 4 compliance costs propagate differently through military offtake agreements versus commercial spot procurement, widening the spread between fixed-contract and availability-based pricing structures.
Pricing Analysis
Long-term integrated logistics support contracts dominate military procurement, insulating Textron Systems and defense-integrated tier suppliers from spot market fluctuations while commercial operators face project-based pricing exposed to petroleum input swings. Three-tier pricing structure across premium, standard, and economy levels separates Coast Guard-certified passenger vessels from uncertified commercial transport units and surplus military conversions. Cost compression in the commercial tier is intensifying because Gulf Coast logistics operators cannot pass skirt replacement costs through fixed-rate crew transport agreements. Government agencies exhibit lowest price sensitivity due to embedded sustainment budgets, while environmental survey contractors in the Canadian Arctic show highest sensitivity as they migrate toward per-hour service contracts to avoid capital ownership.
Supply Chain Analysis
Extended payment terms from defense primes to sub-tier skirt fabricators are compressing working capital availability for specialized neoprene processors in the United States and Canada. Manufacturing concentration rests on domestic hull fabricators in Louisiana and Texas, Canadian Arctic-capable assemblers in British Columbia, and specialty propulsion integrators in Michigan. Reinforced skirt fabrics, marine diesel powerpacks, and lithium-ion battery modules constitute critical input dependencies. Single-source vulnerability sits with EPA-certified engine suppliers capable of Tier 4 Final integration without power-to-weight degradation. Distribution runs through direct military procurement channels for defense segments and regional service contractors for commercial availability-based agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hovercraft incumbents must defend against diesel outboard airboat substitution in price-sensitive marshland applications where aluminum hulls and surface-piercing propellers undercut air-cushion capital costs.
For Market Incumbents: Harden fleet lifecycle extension capabilities through hybrid-electric retrofit kit development, converting installed military LCAC platforms to range-extender configurations before pure battery alternatives mature. Deepen backward integration into skirt material production to neutralize petroleum volatility exposure that erodes commercial margins. EPA Tier 4 compliance timelines represent the critical chokepoint; accelerate certification engineering to capture Coast Guard search-and-resure modernization programs ahead of competitors. For New Entrants and Emerging Players: Establish a beachhead in FEMA disaster response prepositioning contracts across hurricane-prone Southeast states where federal emergency funding is displacing municipal capital budgets. Arctic domain awareness gaps in Canadian Northern territories and Alaska offer the most penetrable geography, with ice-capable patrol demand exceeding incumbent capacity during seasonal breakup periods. Pursue availability-based service contracting rather than platform sales to bypass capital constraints limiting commercial operator expansion. For Investors and Strategic Acquirers: EPA Tier 4 Final marine engine standards reshape the acquisition landscape by devaluing pure diesel-mechanical platform portfolios and privileging hybrid-electric technology holdings. Long-term viability centers on suppliers with modular propulsion architectures capable of mid-life upgrade pathways across the installed base. Watch California and British Columbia zero-emission mandate enforcement velocity as the signal indicating accelerated electric hovercraft adoption timelines versus extended hybrid transition periods.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Partnership | Combines lithium-ion battery packs with diesel range extenders for Coast Guard pilot programs. |
| Integrated Logistics Support Contract | Captures decades of military sustainment revenue through embedded fleet lifecycle services. |
| Arctic Service Capability Buildout | Positions operators for Canadian Coast Guard ice patrol and sovereignty enforcement demand. |
| Skirt Material Backward Integration | Neutralizes petroleum-derived neoprene and hypalon price volatility compressing commercial margins. |
| FEMA Rapid-Response Unit Prepositioning | Secures federal emergency preparedness funding for flood rescue deployment in hurricane zones. |
Research Methodology
Cross-validation between defense procurement databases and commercial operator fleet registries anchors the qualitative findings across the North America hovercraft market. Primary interviews with Marine Corps program officers, Coast Guard acquisition leads, Gulf Coast logistics fleet managers, and Arctic survey contractors combined with secondary validation from EPA certification records, Transport Canada vessel registries, and FEMA disaster equipment inventories. Bottom-up unit deployment tracking and top-down defense budget appropriation analysis provided triangulation across segmentation dimensions.
Calibration against historical LCAC replacement cycles and offshore energy capex patterns shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type, application mission profile, end-user procurement modality, and technology propulsion architecture. CAGRs derived from weighted average of defense program acceleration curves and commercial service contract expansion rates. Industry-specific inputs included EPA Tier 4 compliance cost trajectories and battery energy density improvement curves from marine electric drivetrain pilots.
Stress conditions across petroleum input price bands, defense budget sequestration scenarios, and zero-emission mandate acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hybrid-electric technology maturation and Coast Guard certification timeline stability. Macroeconomic contraction affecting offshore drilling activity, regulatory deviation from EPA Tier 4 enforcement schedules, or breakthrough battery density improvements enabling pure electric heavy-lift platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Segway Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market