
 Rescue Boats Market | 2026-2036
Rescue Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Rescue Boats Market Analytics
The split between custom-built aluminum-hull craft for offshore oil platforms and standardized PVC inflatable units for inland rescue is realigning procurement budgets across emergency fleets. Fassmer leverages its German shipyard heritage to dominate complex naval contracts. Norsafe anchors Arctic-capable freefall lifeboat production with integrated davit systems. Zodiac Milpro competes through military-grade Hypalon construction and special-operations deployment expertise.
Rescue boats are purpose-built watercraft engineered for rapid deployment in search-and-recovery, mass-evacuation, and emergency medical transport, typically constructed from marine-grade aluminum or reinforced composite laminates with self-righting hull geometry and integrated survivor-recovery platforms. Rigid Inflatable Boats command the premium tier due to their versatility across coastal and offshore deployment modes. Folding Boats occupy a niche growth corridor where rapid air-transportability drives NGO and alpine lake demand. Jet Boats lead in shallow-water inland configurations where propeller damage risk excludes conventional drivetrains.
IMO SOLAS Chapter III life-saving appliance codes, EU MDR certification requirements for marine equipment, and national coast guard procurement specifications collectively dictate hull integrity testing, stability criteria, and equipment interoperability standards that manufacturers must satisfy for market access. The US Coast Guard's supplemental NVIC guidance further shapes domestic builder compliance pathways. Stakeholders must monitor evolving green-propulsion mandates and evaluate electrification readiness against current diesel-outboard supply commitments.
Market Dynamics
Arctic-capable hull engineering is concentrating procurement authority among specialized shipbuilders as offshore energy operators and coast guard fleets modernize simultaneously. SOLAS Chapter III amendments and national ice-class certification requirements are compressing supplier qualification timelines while elevating technical barriers to entry.
Growth Catalysts
- IMO SOLAS Life-Saving Appliance Codes:Mandatory freefall lifeboat deployment systems on cargo vessels above 85 meters are mandating replacement cycles across commercial fleets.
- Offshore Wind Installation Vessels:North Sea and Baltic Sea turbine construction is generating demand for daughter craft with integrated motion-compensated davits.
- Hypalon-Neoprene Composite Fabrication:Military special operations units are specifying reinforced inflatable collars for rapid-deployment scenarios in littoral zones.
Market Restraints
- Marine-Grade Aluminum Sheet Volatility:5083-H116 alloy pricing fluctuates with primary aluminum LME contracts, compressing builder margins on fixed-price naval contracts.
- Arctic Hull Certification Concentration:Only Norwegian and Finnish classification societies currently issue full ice-class rescue boat approvals, creating bottlenecked access to polar markets.
- Diesel Outboard Supply Commitments:Long-term engine procurement agreements with Mercury Marine and Volvo Penta lock builders into combustion architectures despite electrification pressures.
Strategic Opportunities
- Indonesia Archipelagic Coast Guard Modernization:The Maritime Security Agency is tendering for 400+ fast rescue craft to patrol the Natuna Sea and Malacca Strait chokepoints.
- Battery-Electric Shallow-Water Configurations:Jet drive systems paired with lithium-ferro-phosphate packs are opening municipal fire department contracts previously closed to combustion engines.
- EU Green Deal Maritime Decarbonization Incentives:Innovation Fund grants for zero-emission vessel development are redirecting R&D budgets toward hydrogen fuel cell lifeboat prototypes.
Industry Challenges
- Composite Laminate Technician Scarcity:Vacuum infusion and resin transfer molding expertise concentrates in Germany's northern shipbuilding corridor, limiting production scaling elsewhere.
- Multi-Agency Certification Parallel Processing:Simultaneous USCG NVIC, Lloyd's Register, and Bureau Veritas approvals extend delivery timelines by 8-14 months for international buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rescue Boats Market |
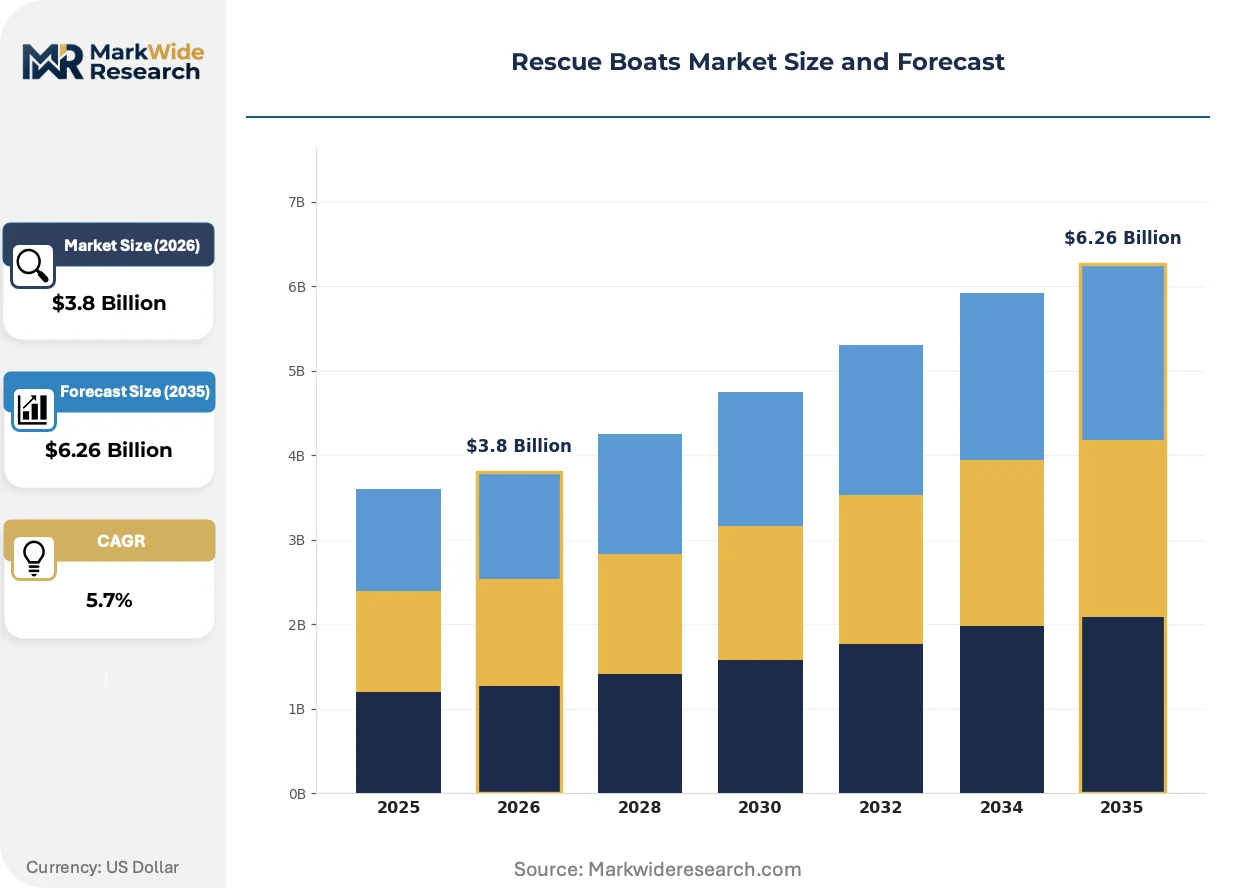
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Inflatable Boats, Folding Boats, Jet Boats, Canoes End User: Government Agencies, NGOs, Private Organizations, Maritime Security Deployment Mode: Onshore, Offshore, Inland, Coastal Material: Aluminum, Fiberglass, Hypalon, PVC |
| Companies Covered | Fassmer, Norsafe, Zodiac Milpro, Maritime Partner, Willard Marine, Palfinger Marine, New Marine, VIKING Life-Saving Equipment, Survitec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rescue Boats Market Evolving Landscape
Propulsion architecture decisions now precede hull design in rescue boat development cycles. Electrification roadmaps, autonomous navigation integration, and modular payload systems are resequencing engineering priorities across the supplier base.
Hybrid-electric drivetrain development is electrifying coastal patrol specifications as harbor authorities and environmental response fleets confront emissions restrictions. Danish and Swedish pilot programs are validating 150-kW permanent magnet motor configurations for 12-meter aluminum hulls. Battery energy density limitations are compressing operational range expectations and forcing tender-based recharging infrastructure investments.
EU MDR certification requirements for marine equipment are tightening documentation burdens on inflatable component suppliers. Technical file compilation and notified body engagement now consume 18-24 months for new Hypalon formulations. German and Dutch builders are responding by consolidating textile supply chains under captive quality management systems.
Performance-based contracting is displacing traditional unit purchase models among oil major procurement teams. Total availability agreements covering 15-year service life are transferring maintenance liability to original equipment manufacturers. Norway's Equinor and Aker BP are pioneering this structure in North Sea platform support vessel fleets.
Rescue Boats Market Segmentation
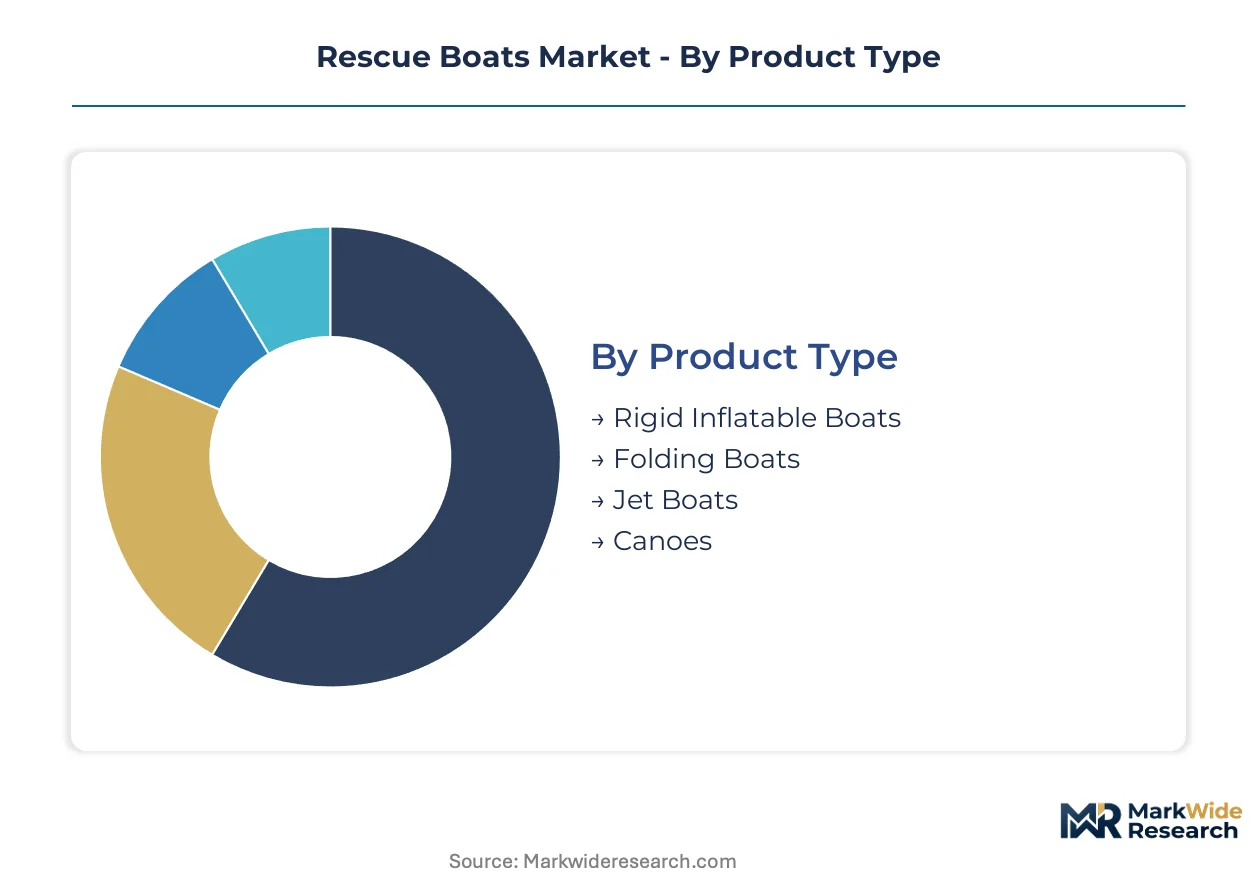
Segmentation in rescue boats reveals how certification requirements fragment procurement across operational environments. SOLAS compliance, ice-class ratings, and military specifications create distinct technical silos that manufacturers must navigate simultaneously.
Product Type:
IMO SOLAS Chapter III mandates freefall deployment certification for cargo vessel lifeboats, while EU MDR governs inflatable collar integrity for commercial rescue craft. Military specifications from NATO STANAG frameworks add a third compliance layer for special operations variants.
- Rigid Inflatable Boats:Aluminum or fiberglass hulls bonded to Hypalon or PVC inflatable tubes deliver self-righting stability in Beaufort Force 8 conditions. Norwegian coast guard fleets and North Sea offshore operators specify integrated davit systems for 12-meter variants, driving premium procurement budgets. SOLAS freefall certification extends manufacturer qualification timelines to 18-24 months.
- Folding Boats:Collapsible aluminum or polymer hulls compress to pallet dimensions for helicopter sling-load transport. Alpine rescue services in Switzerland and Austria specify these for high-altitude lake access where road infrastructure terminates. EU MDR documentation burdens concentrate among German textile suppliers for inflatable collar variants.
- Jet Boats:Shallow-draft aluminum hulls with waterjet propulsion eliminate propeller damage risk in debris-choked inland waterways. Municipal fire departments in the Netherlands specify 8-meter configurations for canal network emergency response.
- Canoes:Traditional paddle-craft configurations persist in wilderness search-and-rescue protocols where engine noise compromises acoustic detection. Canadian and Finnish volunteer rescue associations maintain fleet contracts for silent approach operations.
Leading the category by volume: Rigid Inflatable Boats. Growing fastest: Folding Boats.
End User:
Procurement authority concentrates differently across buyer types, with government tenders demanding 15-year total availability agreements while NGO purchases prioritize air-transportable unit cost.
- Government Agencies:National coast guards and maritime safety authorities issue multi-hundred-unit tenders with integrated through-life maintenance. Indonesia's Maritime Security Agency and Vietnam's Coast Guard are expanding fleet modernization with Arctic-capable specifications.
- Maritime Security:Naval and special operations commands specify military-grade Hypalon construction with ballistic protection integration. Procurement runs through defense ministry channels with NATO STANAG interoperability requirements.
- NGOs:International relief organizations prioritize rapid deployment logistics over endurance specifications. Médecins Sans Frontières and similar operators source folding configurations for airbridge disaster response.
- Private Organizations:Offshore energy operators and private maritime security firms negotiate performance-based contracting with availability guarantees. Equinor and Aker BP in Norway pioneered 15-year service life agreements transferring maintenance liability to builders.
Dominating procurement value: Government Agencies. Expanding most quickly: Maritime Security.
Deployment Mode:
Operational environment dictates hull geometry, propulsion selection, and survivor recovery platform configuration more than any other variable.
- Offshore:Self-righting freefall lifeboats with enclosed cabins withstand 6-meter significant wave heights. Norwegian and UK North Sea platforms mandate these for 100+ person evacuation capacity with integrated davit launch systems.
- Coastal:Semi-rigid inflatable configurations balance speed and stability for surf zone operations. French and Irish national lifeboat institutions specify 10-meter aluminum-hull RIBs with waterjet or outboard propulsion flexibility.
- Inland:Jet drive shallow-water craft navigate debris and variable depth without propeller damage. German and Austrian inland waterway fire departments specify lithium-ferro-phosphate electric variants for zero-emission harbor operations.
- Onshore:Trailer-launched rapid response units deploy from land-based stations to littoral zones. Spanish and Portuguese maritime rescue coordinate these with helicopter winch-capable configurations for cliff rescue integration.
Highest specification intensity: Offshore. Gaining share fastest: Inland.
Material:
Raw material selection locks manufacturers into specific supply chain geographies and certification pathways that resist rapid substitution.
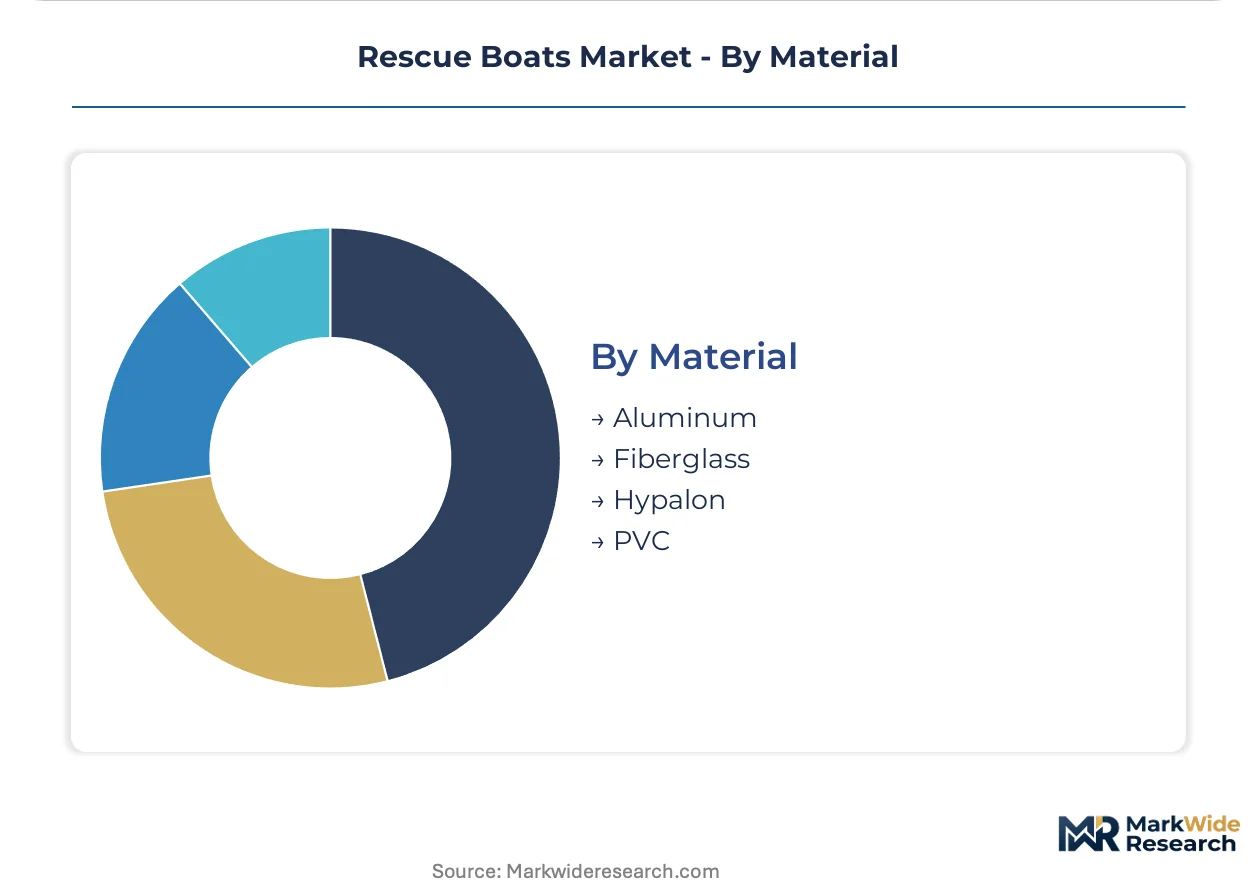
- Aluminum:Marine-grade 5083-H116 alloy dominates 12-meter-plus hull construction for ice-class certification. Norwegian and Finnish classification societies approve only specific temper specifications for polar operations, concentrating supply relationships with Nordic smelters.
- Hypalon:Chlorosulfonated polyethylene synthetic rubber delivers UV resistance and chemical tolerance for inflatable collars. EU MDR technical file compilation now consumes 18-24 months for new formulations, consolidating supply among German and Dutch captive textile operations.
- Fiberglass:Glass-reinforced polymer laminates compete in cost-sensitive coastal patrol segments where ice-class ratings are unnecessary. Vacuum infusion expertise concentrates in Germany's northern shipbuilding corridor, limiting production scaling.
- PVC:Polyvinyl chloride inflatable constructions serve inland recreational and light rescue applications where Hypalon cost premiums are unjustified. Chinese and Turkish manufacturers dominate this commoditized tier with limited regulatory documentation burdens.
Commanding premium pricing: Aluminum. Steepest expansion trajectory: Hypalon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stavanger anchors the global rescue boat manufacturing corridor, with Norwegian shipyards clustering around North Sea offshore energy demand and Arctic-capable hull certification authority.
Norway
Equinor and Aker BP drive 15-year total availability agreements for platform support fleets. The Norwegian Maritime Authority enforces ice-class certification standards that only domestic classification societies currently administer. Bergen and Ålesund yards specialize in integrated davit systems for freefall lifeboat deployment.
Germany
Federal police and maritime emergency response units procure rigid inflatable boats for North Sea and Baltic patrols. The KBA and BSH coordinate vessel type-approval with EU MDR documentation requirements for inflatable components. Northern shipbuilding corridors concentrate vacuum infusion expertise for composite laminate production.
United States
The US Coast Guard modernizes inland and coastal fleets under supplemental NVIC guidance for small boat construction. DHS procurement channels specify integrated survivor recovery platforms for search-and-rescue operations. Pacific Northwest and Gulf Coast fabricators supply municipal fire departments with shallow-water jet configurations.
Indonesia
The Maritime Security Agency tenders for 400-plus fast rescue craft to secure Natuna Sea and Malacca Strait chokepoints. BAKAMLA fleet specifications emphasize rapid deployment from land-based stations. Surabaya and Batam shipyards compete for domestic assembly contracts with imported hull kits.
United Kingdom
RNLI specifications influence global standards for surf zone self-righting stability. The Maritime and Coastguard Agency enforces SOLAS Chapter III compliance for commercial fleet certification. Southampton and Plymouth clusters develop motion-compensated davit systems for offshore wind installation vessels.
Rescue Boats Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent certification pathways. The market structures around three tiers: integrated naval shipyards, specialized lifeboat manufacturers, and inflatable component suppliers. Strategic moves concentrate on captive textile supply consolidation and 15-year service life contracting structures that transfer maintenance liability downstream.
Among Norwegian and German integrated producers, Fassmer GmbH & Co. KG and Norsafe AS exemplify the naval shipyard archetype with Arctic certification authority. Zodiac Milpro represents the military-grade inflatable specialist tier, with company naming conventions indicating French composite fabrication heritage. These three anchors demonstrate how geographic concentration around classification society headquarters shapes competitive positioning.
| Leading Market Players |
|---|
| Fassmer |
| Norsafe |
| Zodiac Milpro |
| Maritime Partner |
| Willard Marine |
| Palfinger Marine |
| New Marine |
| VIKING Life-Saving Equipment |
| Survitec Group |
| Others |
Value Network & Pricing Analysis
Total availability agreements transferring 15-year maintenance liability to manufacturers are compressing upfront margins while extending revenue recognition timelines across Norwegian and German yards. Builders must absorb lifecycle service costs into initial quotations, forcing selective bidding on contracts where captive supply chains permit margin defense.
Pricing Analysis
Performance-based contracting anchored to platform evacuation throughput and vessel availability uptime now dominates North Sea procurement. Pricing stratifies across SOLAS-certified premium tiers, ice-class Arctic specifications, and standard coastal patrol configurations, with certification grade commanding the widest spreads. Cost compression in aluminum-hull segments intensifies as LME-linked 5083-H116 alloy pricing erodes fixed-quote profitability. Government agencies exhibit lowest price sensitivity due to mandated safety budgets, while municipal fire departments in inland markets prioritize capital expenditure minimization.
Supply Chain Analysis
Container freight volatility from Nordic smelters to German shipbuilding corridors adds cost unpredictability to hull fabrication timelines. Supply concentrates in Norway, Germany, and Finland, with marine-grade aluminum extrusion, Hypalon textile formulations, and integrated davit systems as critical inputs. Single-source vulnerability runs through Norwegian classification societies' ice-class certification authority, which bottleneck polar market access. Distribution runs through defense ministry procurement channels, coast guard tender processes, and oil major fleet management teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IMO SOLAS Chapter III amendment cycles erect a cost-of-compliance barrier that favors incumbent builders with established notified body relationships and amortized certification infrastructure.
For Market Incumbents: Anchor market position through backward integration into Hypalon textile production and captive vacuum infusion capacity for composite laminates. Consolidate around Norwegian Maritime Authority certification relationships to defend against emerging Finnish classification society competition. Prioritize capacity addition in Bergen and Ålesund clusters to capture Equinor and Aker BP fleet renewal cycles. For New Entrants and Emerging Players: Municipal fire departments in German and Austrian inland waterway networks present the most penetrable entry corridor. Battery-electric jet boat configurations for zero-emission harbor operations offer white-space positioning outside diesel-outboard supply lock-ins. Pursue technology licensing partnerships with established davit system integrators to bypass 18-24 month SOLAS qualification timelines. For Investors and Strategic Acquirers: The window for entry favors specialist manufacturers with Arctic hull certification authority and existing IMO notified body engagements. Acquisition targets should demonstrate captive supply chain control over 5083-H116 alloy sourcing or integrated textile operations. Monitor EU Green Deal Maritime Decarbonization Fund disbursement velocity as inflection signal for hydrogen fuel cell lifeboat prototype viability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Hypalon Textile Integration | EU MDR documentation burdens consolidate supply among German and Dutch captive operations. |
| Arctic Hull Certification Investment | Norwegian Maritime Authority ice-class standards bottleneck polar market access for non-compliant builders. |
| Battery-Electric Propulsion Development | Danish and Swedish pilot programs validate 150-kW permanent magnet motor configurations for harbor fleets. |
| Total Availability Contracting | Equinor and Aker BP transfer 15-year maintenance liability to manufacturers in North Sea platform support. |
| Indonesian Coast Guard Partnership | BAKAMLA tenders for 400-plus fast rescue craft secure Natuna Sea and Malacca Strait deployment channels. |
Research Methodology
Independent corroboration across coast guard procurement officers, shipyard engineering directors, and offshore energy fleet managers underwrites the qualitative findings in this study. Primary field engagement with davit system integrators, classification society surveyors, and marine equipment procurement specialists combined with secondary validation from Lloyd's Register certification databases, IMO SOLAS amendment documentation, and EU MDR technical file registries. Bottom-up vessel delivery tracking and top-down fleet modernization budget analysis provided triangulation across the analysis window.
Rate-of-change decomposition across product type, deployment mode, end-user category, and material specification dimensions structured the analytical framework. CAGRs derived from segmented volume builds and value-per-unit trajectories across rigid inflatable, folding, jet boat, and canoe configurations. Forecast inputs incorporated offshore wind installation vessel daughter craft demand curves and Indonesian Maritime Security Agency fleet expansion timelines.
Caveats apply where aluminum LME pricing volatility, Arctic certification authority concentration, or electrification mandate acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Hydraulic Marine Cranes Market
Marine
Marine Glass Market
Marine
Deep-V Boat Market
Marine
Global Maritime Information Market
Marine
GCC ROV Market
Marine
Marine Spreader Lights Market
Marine
Marine Growth Removal Tool Market
Marine
Japan Marine Composites Market
Marine
Global Discount-Marine Trenchers Market
Marine
Marine Trenchers Market
Marine
Electric Ship Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
North America Naval Vessels Market
Marine
Global Foldable Inflatable Boats Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Electric Ferry Market