
 Hydrogen Ships Market | 2026-2036
Hydrogen Ships Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Ships Market Foresight
A capital-intensity divergence between integrated fuel cell developers and regional shipyard operators is bifurcating competitive dynamics in hydrogen marine propulsion. Ballard Power Systems leverages its proton exchange membrane stack manufacturing depth to anchor long-term supply agreements with European ferry operators. Siemens Energy sustains electrolyzer-to-propulsion system integration that differentiates its offering from component-only rivals. Viking Cruises competes on passenger vessel retrofit expertise, positioning its fleet decarbonization program as a reference architecture for competitors.
Hydrogen ships are vessels powered by hydrogen fuel cells or hydrogen combustion engines that convert stored hydrogen into electrical or mechanical propulsion, typically operating at system pressures of 350–700 bar for compressed hydrogen or cryogenic temperatures near minus 253 degrees Celsius for liquid hydrogen storage. The primary industrial purpose is eliminating carbon dioxide and sulfur oxide emissions from maritime transport to comply with tightening environmental mandates. Ferries dominate current deployment because short, fixed routes simplify shoreside refueling infrastructure and allow predictable duty cycles. Cargo ships represent the fastest-expanding segment as container lines pilot hydrogen retrofit programs on deep-sea routes. Proton exchange membrane technology leads installed capacity due to its operational maturity in marine environments, while solid oxide systems attract R&D investment for higher efficiency at scale.
The International Maritime Organization enforces carbon intensity indicators that ratchet downward annually, forcing shipowners to abandon conventional bunker fuels or face operational penalties. DNV classification rules for hydrogen-fueled vessels, alongside EU Green Deal fuel standards under the FuelEU Maritime initiative, shape product certification requirements and market access conditions for builders and operators. Classification societies in Germany, Norway, and France are developing harmonized safety protocols for hydrogen storage and bunkering that will determine which shipyards qualify for construction contracts. Stakeholders must monitor which regulatory jurisdiction certifies the first large-scale liquid hydrogen carrier, as that precedent will cascade through insurance, port access, and financing standards worldwide.
Market Dynamics
Proton exchange membrane fuel cell technology is consolidating its position as the dominant marine propulsion architecture, compressing development timelines for competing solid oxide systems and forcing shipyards to specialize around cryogenic hydrogen storage integration or exit the segment entirely.
Growth Catalysts
- FuelEU Maritime mandate:The EU Green Deal's binding carbon intensity targets for vessels calling at European ports are compelling ferry operators to accelerate hydrogen retrofit programs ahead of 2025 enforcement deadlines.
- Norwegian coastal corridor electrification:The country's fjord access regulations now require zero-emission operation in designated heritage waterways, creating captive demand for hydrogen-powered passenger vessels on fixed routes.
- 350-bar compressed hydrogen bunkering:Standardized shoreside refueling protocols developed by classification societies in Germany and France are reducing port entry barriers for early-adopter fleets.
Market Restraints
- Liquid hydrogen boil-off rates:Cryogenic storage systems lose approximately one percent of stored hydrogen daily at minus 253 degrees Celsius, compressing viable voyage duration for deep-sea cargo applications.
- Electrolyzer supply concentration:European alkaline and PEM electrolyzer manufacturing capacity remains concentrated among German and Norwegian suppliers, creating procurement bottlenecks for Asian shipyards seeking fuel cell integration.
- DNV certification timelines:Hydrogen vessel classification rules require extensive safety case documentation for storage tank placement and venting systems, extending newbuild delivery schedules by eight to fourteen months relative to conventional vessels.
Strategic Opportunities
- Japanese deep-sea container pilots:Nippon Foundation-funded demonstration projects on transpacific routes are validating liquid hydrogen carrier designs for 8,000+ TEU vessels, opening a pathway for scale deployment beyond coastal ferries.
- Solid oxide fuel cell convergence:Integration of high-temperature fuel cells with onboard carbon capture systems offers potential efficiency advantages for cruise operators seeking combined heat and power architectures.
- Port authority green corridor incentives:Rotterdam and Singapore port authorities are offering priority berth access and reduced harbor fees for hydrogen-fueled vessels, creating operational cost advantages for compliant operators.
Industry Challenges
- Cryogenic systems engineering talent:Shipyards report acute shortages of naval architects experienced in minus 253-degree Celsius tank design and vacuum insulation integration, forcing reliance on aerospace industry contractors.
- Retrofit certification complexity:Converting existing diesel-electric ferries to hydrogen propulsion requires complete electrical system recertification under IEC 60092 marine electrical standards, compressing project economics.
- Harmonized bunkering protocols:Absence of unified ISO standards for hydrogen transfer rates and coupling interfaces is forcing operators to maintain vessel-specific shore connection configurations at each port of call.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Ships Market |
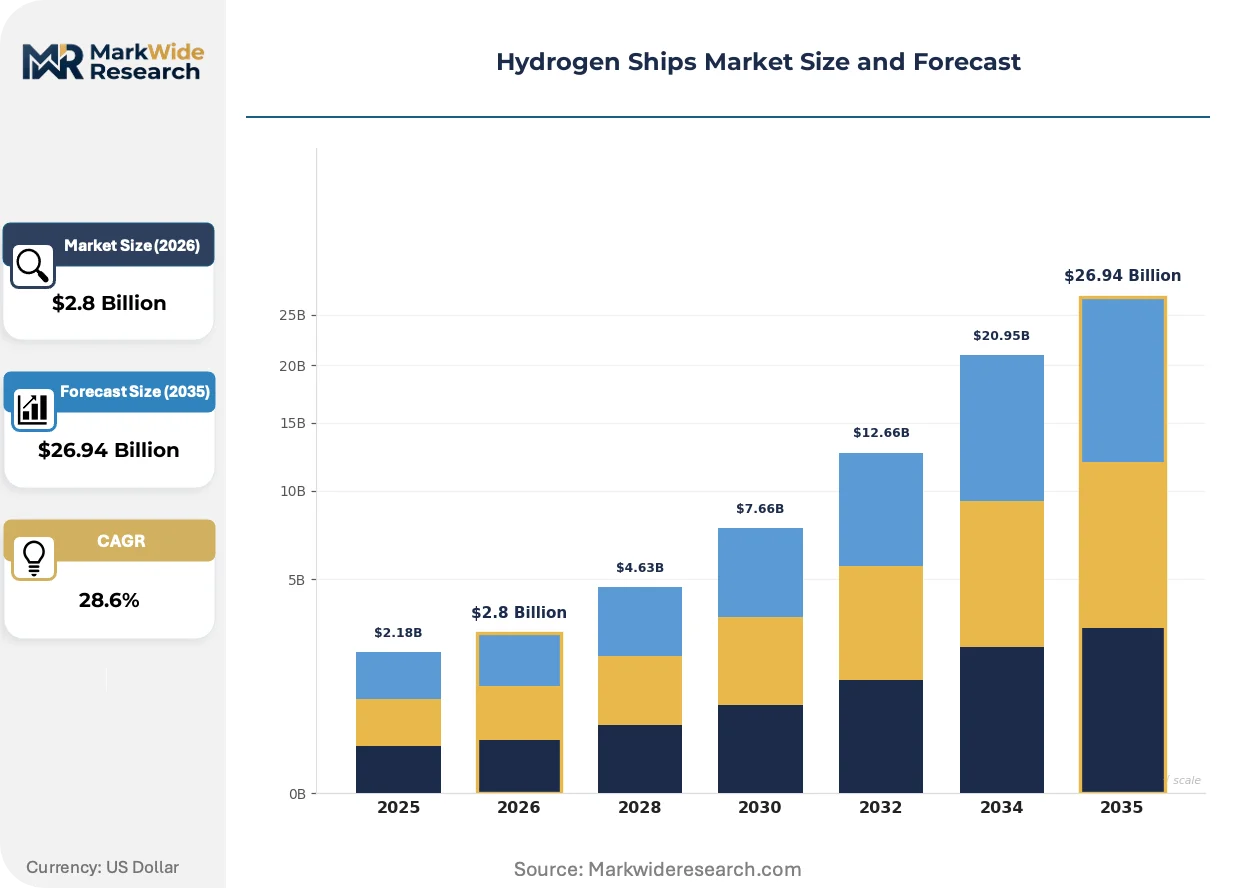
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Cargo Ships, Ferries, Tankers, Research Vessels Fuel Cell Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Direct Methanol End User: Shipping Companies, Government Agencies, Research Institutions, Private Sector Power Output: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Ballard Power Systems, Siemens Energy, Viking Cruises, Torghatten Nord, Myklebust Verft, Fincantieri, Glosten, DNV, Isotta Fraschini Motori, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Ships Market Shifts & Advancements
Maritime hydrogen adoption is accelerating through three interconnected developments: fuel cell stack power density improvements, regulatory harmonization across Northern European jurisdictions, and the emergence of dedicated green hydrogen supply contracts tied to specific vessel routes.
Liquid hydrogen storage systems are displacing compressed gas architectures in vessel designs above two megawatts of installed propulsion power. Japanese shipyards are adopting cryogenic tank configurations for deep-sea cargo pilots, while Norwegian ferry operators retain compressed hydrogen for sub-megawatt coastal routes. This technology divergence is bifurcating shipyard specialization and compressing the addressable market for component suppliers unable to serve both storage modalities.
The EU Green Deal's FuelEU Maritime regulation is mandating annual carbon intensity reductions for vessels trading with European ports. Shipowners face escalating penalties for non-compliance from 2025 onward, forcing container lines to accelerate hydrogen pilot programs on Asia-Europe strings. Classification societies in France and Germany are responding with streamlined approval pathways for dual-fuel hydrogen-diesel configurations.
Charter-party contracting is incorporating emissions performance clauses that transfer fuel technology risk from shipowners to cargo interests. Major European retailers now specify zero-emission vessel requirements for supply chain contracts, compelling container operators to secure hydrogen supply agreements before vessel delivery. This demand-side pressure concentrates most intensely on North Sea and Baltic Sea feeder services.
Hydrogen Ships Market Segmentation
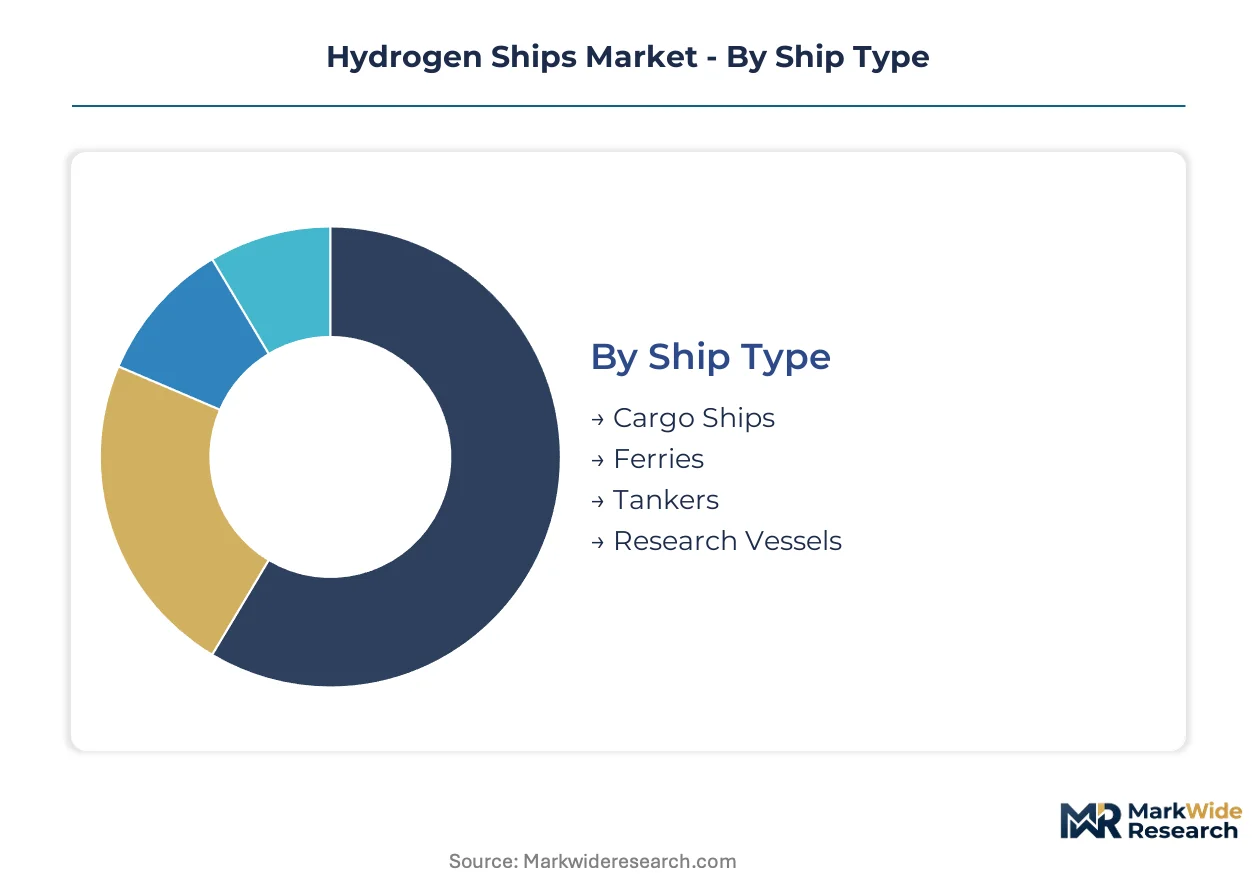
Hydrogen ship procurement channels diverge sharply by vessel scale and operational profile. Coastal ferry operators favor integrated fuel cell packages through regional shipyard consortia, while deep-sea cargo lines negotiate directly with fuel cell developers for custom propulsion architectures.
Ship Type:
Cargo operators and passenger ferry companies source through distinct commercial channels, with ferries clustering around Norwegian and German coastal shipyards and cargo vessels routing through Japanese and South Korean newbuild programs.
- Cargo Ships:Container carriers and bulk operators are piloting liquid hydrogen storage systems for transpacific routes. Japanese deep-sea demonstration projects validate 8,000+ TEU vessel designs, driven by Nippon Foundation funding and charter-party emissions clauses from European retailers.
- Ferries:Short-haul passenger vessels dominate current deployment volume. Norwegian fjord access regulations mandate zero-emission operation in designated waterways, compressing procurement timelines for fixed-route operators.
- Tankers:Specialized hydrogen carriers and chemical tankers require cryogenic cargo containment systems. Demand concentrates among energy majors seeking dedicated ammonia and liquid hydrogen transport vessels.
- Research Vessels:Government-funded oceanographic platforms test dual-fuel configurations. Procurement flows through national research councils in Norway, Japan, and Germany.
Ferries dominate installed base. Cargo ships are where expansion concentrates.
Fuel Cell Technology:
Technology selection tracks vessel power requirements and voyage duration, with coastal operators accepting lower efficiency for faster startup times and deep-sea operators prioritizing thermal efficiency at scale.
- Proton Exchange Membrane:Low-temperature operation at 60-80°C enables rapid load response for ferry duty cycles. Norwegian operators anchor demand through coastal corridor electrification programs.
- Solid Oxide:High-temperature ceramic electrolyte systems achieve 60% electrical efficiency. Japanese container pilots and cruise operators evaluate combined heat and power architectures for auxiliary loads.
- Alkaline:Mature electrolyte-based systems compete on capital cost for sub-megawatt installations. Emerging demand from inland waterway operators in Germany and the Netherlands.
- Direct Methanol:Liquid fuel compatibility simplifies bunkering logistics. Research vessel and small craft applications where hydrogen infrastructure remains undeveloped.
Proton exchange membrane anchors near-term revenue. Solid oxide is climbing the fastest among emerging alternatives.
End User:
Procurement authority fragments across commercial, sovereign, and institutional buyers with divergent risk tolerances and certification requirements.
- Shipping Companies:Container lines and ferry operators drive volume procurement. EU Green Deal compliance deadlines force accelerated retrofit and newbuild programs.
- Government Agencies:Naval architects and coast guard administrations specify reference designs. Norwegian Maritime Authority and Japan's Ministry of Land, Infrastructure, Transport and Tourism shape safety protocols.
- Research Institutions:Universities and oceanographic institutes validate operational data. Funding flows through Horizon Europe and national innovation agencies.
- Private Sector:Energy majors and logistics operators pilot captive fleets. Demand clusters around green corridor commitments from Rotterdam and Singapore port authorities.
Shipping companies command procurement volume. Government agencies control certification pathways.
Power Output:
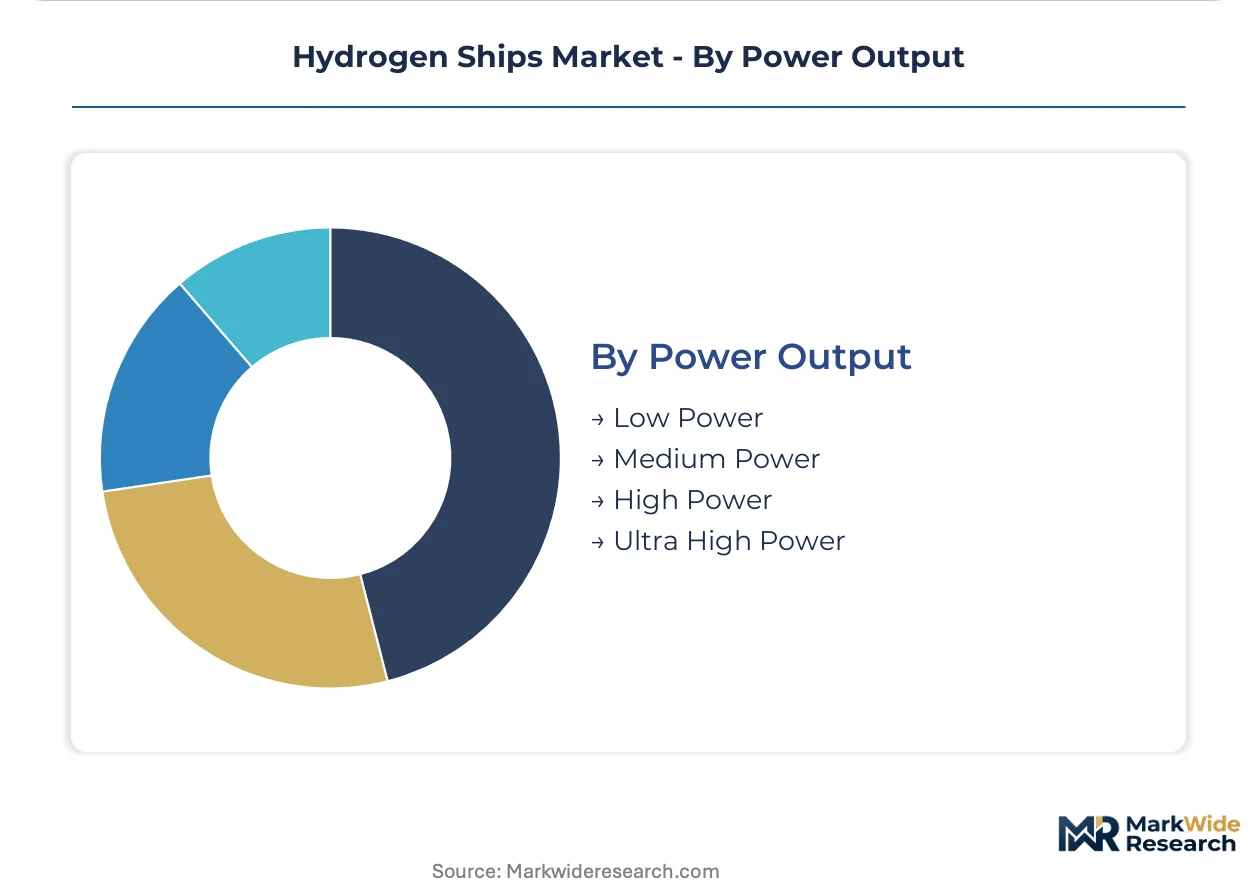
System scale determines fuel storage modality and shipyard specialization, compressing the vendor landscape at upper power bands.
- Low Power:Sub-500 kW systems serve harbor craft and inland ferries. Compressed hydrogen architectures dominate Norwegian coastal routes.
- Medium Power:500 kW to 2 MW installations cover regional ferries and offshore support vessels. German and French classification societies streamline approval pathways.
- High Power:2-10 MW systems target deep-sea cargo and cruise applications. Liquid hydrogen storage becomes mandatory above two megawatts.
- Ultra High Power:Above 10 MW propulsion for large container vessels remains pre-commercial. Japanese shipyards advance cryogenic tank integration for 8,000+ TEU designs.
Medium power systems dominate current orderbooks. Ultra high power is gaining share fastest as container lines advance pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands pricing power on coastal ferry specifications while Japanese shipyards absorb cost premiums for deep-sea liquid hydrogen architectures. This asymmetry concentrates procurement authority in Northern European corridors and East Asian newbuild programs.
Norway
Fjord access regulations mandate zero-emission operation in designated heritage waterways, compressing procurement timelines for fixed-route ferry operators. The Norwegian Maritime Authority enforces strict electrification deadlines under coastal corridor decarbonization programs. Bergen and Stavanger anchor hydrogen bunkering infrastructure development along the western fjord network.
Germany
Classification society leadership from DNV and Germanischer Lloyd shapes harmonized safety protocols for hydrogen storage and bunkering systems. The EU Green Deal's FuelEU Maritime initiative tightens carbon intensity standards for vessels calling at Hamburg and Bremerhaven. Shipyards in Mecklenburg-Western Pomerania specialize in cryogenic tank integration for medium-power ferry retrofits.
Japan
Nippon Foundation funding validates liquid hydrogen carrier designs for 8,000+ TEU container vessels on transpacific routes. METI coordinates demonstration projects linking shipbuilders with electrolyzer manufacturers under national hydrogen strategy mandates. Nagoya and Kobe cluster deep-sea pilot programs with charter-party emissions clauses from European retailers.
Singapore
Port authority green corridor incentives offer priority berth access and reduced harbor fees for hydrogen-fueled vessels calling at Southeast Asian hubs. The Maritime and Port Authority coordinates bunkering standardization with Rotterdam and Antwerp counterparts. Tuas Port development incorporates dedicated hydrogen refueling infrastructure for feeder services.
France
Classification society Bureau Veritas advances streamlined approval pathways for dual-fuel hydrogen-diesel configurations in regional ferry applications. ANSM safety protocols influence cryogenic system certification standards adopted across EU member states. Marseille and Le Havre concentrate shoreside electrolyzer deployment for Mediterranean short-sea shipping.
Hydrogen Ships Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in hydrogen marine propulsion. Integrated fuel cell developers command premium positioning through proprietary stack manufacturing depth, while regional shipyard operators compete on retrofit execution speed and local regulatory relationships. Three archetypes dominate: membrane technology specialists, electrolyzer-to-propulsion integrators, and passenger vessel retrofit experts. Competitive dynamics center on long-term supply agreement anchoring and certification pathway control rather than price-based rivalry.
Among North American fuel cell developers, Ballard Power Systems anchors the membrane technology specialist archetype through its proton exchange membrane manufacturing depth. Siemens Energy exemplifies the electrolyzer-to-propulsion integrator model with its bundled system offerings. Viking Cruises occupies a distinct position as the passenger vessel retrofit specialist, leveraging fleet decarbonization program expertise. These three companies represent divergent competitive vectors—component depth, system integration, and operational execution—that collectively define market structure.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Siemens Energy |
| Viking Cruises |
| Torghatten Nord |
| Myklebust Verft |
| Fincantieri |
| Glosten |
| DNV |
| Isotta Fraschini Motori |
| Others |
Supply & Pricing Matrix
Electrolyzer manufacturing scale economies in Germany and Norway compress fuel cell stack costs while elevating price floors for Asian shipyards lacking captive supply. This capacity concentration concentrates pricing power among integrated propulsion developers and forces regional operators to absorb premiums for DNV-certified storage systems or exit the segment.
Pricing Analysis
Configured-to-order pricing for cryogenic liquid hydrogen systems commands a 40-60% premium over compressed hydrogen architectures for coastal ferry retrofits. Project-based contract structures dominate, with price differentiation tracking DNV certification tier and electrolyzer integration depth. Cost compression in proton exchange membrane stacks is intensifying because Ballard and Siemens Energy are expanding manufacturing footprints in Northern Europe. Charter-party operators exhibit highest price sensitivity, while government-funded research vessels accept premium pricing for solid oxide fuel cell configurations.
Supply Chain Analysis
Inventory lead times for cryogenic tank vacuum insulation systems extend 14-22 months, forcing shipyards to pre-position materials before contract award. Manufacturing concentrates in Germany, Norway, and Japan, with each hub specializing in distinct power-output tiers. Raw material dependencies center on platinum-group catalysts, carbon-fiber pressure vessels, and specialized ceramic electrolytes. Single-source vulnerability runs through German alkaline electrolyzer suppliers, where capacity constraints are creating procurement bottlenecks for Asian newbuild programs. Distribution runs through regional shipyard consortia for ferries and direct OEM relationships for deep-sea cargo pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen marine propulsion represents a service-attach opportunity where lifecycle maintenance contracts and fuel supply agreements expand faster than vessel hardware sales. Recurring revenue from electrolyzer servicing and stack refurbishment is capturing margin pools that hardware-only vendors cannot access.
For Market Incumbents: Compound defensive positioning through backward integration into cryogenic tank manufacturing and exclusive bunkering infrastructure at Rotterdam and Singapore. Lock in long-term supply agreements with Norwegian ferry operators before FuelEU Maritime enforcement tightens. Anchor certification pathway control by deepening DNV relationship management and pre-positioning safety case documentation for dual-fuel retrofits.
For New Entrants and Emerging Players: Differentiate on solid oxide fuel cell efficiency for cruise and auxiliary power applications where incumbent PEM dominance is weakest. Target Japanese deep-sea container pilots as the most penetrable segment, where Nippon Foundation funding reduces customer acquisition costs. Pursue a go-to-market angle through port authority green corridor partnerships that bundle vessel conversion with shoreside hydrogen supply.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrolyzer-to-propulsion integrators over component-only suppliers as the market transitions from pilot to scale deployment. Five-to-ten-year viability hinges on liquid hydrogen carrier certification precedents and harmonized bunkering standard adoption. Signal to monitor: first large-scale liquid hydrogen carrier DNV classification, which will cascade through insurance, port access, and financing standards worldwide.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Manufacturing | Captures margin from German and Norwegian supply bottlenecks while securing stack availability for shipyard orderbooks. |
| DNV Certification Pre-Positioning | Accelerates newbuild delivery timelines by 8-14 months versus competitors pursuing concurrent safety case development. |
| Port Authority Green Corridor Partnership | Locks in priority berth access at Rotterdam and Singapore while securing reduced harbor fee structures for compliant fleets. |
| Liquid Hydrogen Storage System Development | Opens addressable market beyond coastal ferries into 8,000+ TEU container segments where compressed architectures fail. |
| Lifecycle Service Contract Anchoring | Converts one-time vessel sales into recurring stack refurbishment and electrolyzer maintenance revenue streams. |
Research Methodology
The analysis maps fuel cell technology tiers, vessel power-output bands, and regional regulatory clusters, each validated through shipyard procurement directors, ferry operator fleet managers, and classification society technical leads. Primary interviews with DNV and Bureau Veritas certification engineers, combined with electrolyzer manufacturer sales executives, were cross-referenced against secondary sources including IMO carbon intensity filings, EU Green Deal regulatory texts, and Nippon Foundation demonstration project disclosures. Bottom-up vessel orderbook aggregation and top-down maritime decarbonization spending estimates were triangulated to constrain forecast variance.
Consistency checks against external benchmarks validated projections against historical fuel cell deployment curves in adjacent transportation sectors. The analytical framework models ship type, fuel cell technology, power output tier, and end-user procurement authority across the projection horizon. CAGRs were derived from segmented adoption curves weighted by regulatory enforcement timelines and bunkering infrastructure buildout schedules. Key inputs include electrolyzer manufacturing capacity expansion announcements and port authority green corridor commitment tracking.
Decision-makers should treat outputs as directional under assumptions of sustained FuelEU Maritime enforcement and liquid hydrogen carrier certification progress; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sailboat Market
Marine
Marine Asset Integrity Services Market
Marine
Mooring Ropes Market
Marine
Ship Searchlight Market
Marine
Boat Control Lever Market
Marine
Marine Diesel Engine Market
Marine
Singapore Container Transshipment Market
Marine
Europe Marine Communication Systems Market
Marine
Deep-V Boat Market
Marine
Hydrofoil Market
Marine
Unmanned Marine Vehicles Market
Marine
Marine Winch Motors Market
Marine
Marine Auxiliary Engine Market
Marine
Ship Rudders Market
Marine
Flap Rudder Market
Marine
Marine Fin Stabilizer Market