
 Brazil Energy Sector Market | 2026-2036
Brazil Energy Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Energy Sector Market Insights
Brazilian offshore pre-salt operators are rebalancing output portfolios toward higher-margin crude streams. Petróleo Brasileiro S.A. - Petrobras dominates deepwater extraction through proprietary floating production systems. Eletrobras sustains the country's largest transmission backbone across multiple voltage classes. Neoenergia positions its renewable platform to capture grid parity dynamics in Northeast wind zones.
The Brazil Energy Sector encompasses the full chain of energy resource extraction, conversion, transmission, and distribution serving national economic activity. Thermal efficiency ratings, reservoir recovery factors, and grid interconnection standards determine asset valuations and dispatch priority across the system. Renewable type capacity led by hydro and wind commands the largest installed base, while solar technology segments exhibit the fastest capacity addition rates. Application in power generation concentrates the deepest margin pools due to long-term purchase agreements, whereas oil and gas application segments retain substantial capital intensity from upstream development cycles.
ANP licensing rules shape upstream access, while ANEEL tariff methodologies determine distribution utility revenue ceilings and investment recovery timelines. Brazil's central bank and BNDES financing directives steer capital toward decarbonization projects through concessional lending rates. Stakeholders must weigh pre-salt depletion curves against renewable integration costs when committing capital to generation portfolios.
Market Dynamics
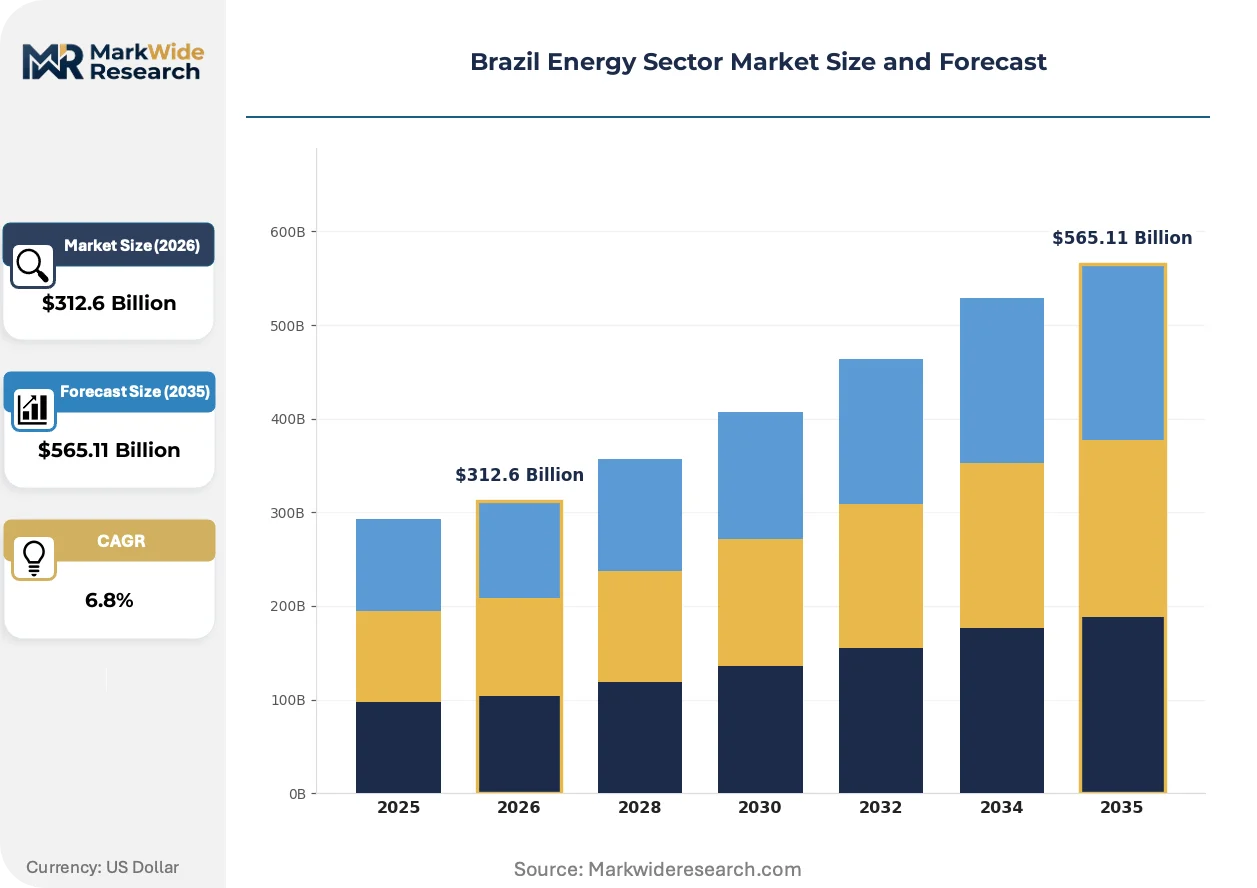
Pre-salt depletion curves and Northeast wind grid parity are compressing capital allocation timelines across Brazilian generation portfolios. ANEEL tariff methodologies and BNDES concessional lending rates now determine project viability more than reservoir geology alone.
Growth Catalysts
- RenovaBio carbon intensity targets:ANP mandates redirect fuel distributor obligations toward ethanol and biomethane infrastructure investments. Heavy transport fleets in São Paulo state are retrofitting for hydrous ethanol blends.
- Industrial corridor electrification:Manufacturing procurement from São Paulo-Rio de Janeiro heavy industry is expanding transmission access requests. Steel and cement producers are signing long-term purchase agreements with renewable generators.
- Floating production system deployment:Proprietary deepwater extraction technology is unlocking pre-salt reserves previously classified as non-commercial. Santos Basin operators are rebalancing output toward higher-margin crude streams.
Market Restraints
- Upstream licensing friction:ANP concession rounds face bid-floor disputes that delay acreage release schedules. International operators are reallocating exploration capital to Guyana-Suriname plays.
- Transmission bottleneck concentration:Eletrobras backbone saturation in Southeast load centers limits renewable dispatch from Northeast wind zones. Grid interconnection queues now extend beyond three years for new projects.
- Biomethane feedstock competition:Sugarcane bagasse diversion to power generation constrains anaerobic digester input supply. São Paulo ethanol mills are prioritizing electricity sales over biogas upgrading.
Strategic Opportunities
- Green hydrogen export corridors:Port of Pecém infrastructure and Ceará wind resource density position Brazil for European offtake contracts. Electrolyzer deployment is attracting separate BNDES credit lines from power generation.
- Distributed generation regulatory tailwind:ANEEL net metering expansion for commercial consumers below seventy-five kilowatts unlocks rooftop solar in Minas Gerais industrial zones. Billing credits now transfer across multiple consumer units.
- Offshore wind technology convergence:Floating foundation designs adapted from oil and gas mooring systems are reducing levelized costs for deepwater sites. Rio Grande do Sul and Santa Catarina seabed conditions favor early pilot arrays.
Industry Challenges
- Subsea engineering talent scarcity:Petrobras workforce transition to renewable units is depleting deepwater project management capacity. Training pipelines for floating production specialists require eighteen-month certification cycles.
- Legacy hydro dispatch integration:Run-of-river plant coordination with intermittent wind and solar is forcing algorithmic trading system overhauls. ANEEL is revising spot price formation rules to accommodate storage arbitrage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Energy Sector Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional, Renewable, Nuclear, Hybrid Application: Power Generation, Oil & Gas, Manufacturing, Transportation End User: Industrial, Commercial, Residential, Government Technology: Solar, Wind, Hydro, Biomass |
| Companies Covered | Petróleo Brasileiro S.A. - Petrobras, Petro Rio SA, Ultrapar Participações SA, Cosan SA, 3R Petroleum Óleo e Gás SA, Enauta Participacoes SA, Petroreconcavo SA, Eletrobras, Neoenergia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Energy Sector Market Trends and Innovations
Digital twin deployment and modular electrolyzer scaling are compressing project development cycles across Brazilian energy infrastructure. These shifts are reconfiguring how operators manage asset lifecycles and offtake negotiations.
Battery energy storage systems paired with Northeast wind farms are decentralizing grid balancing authority away from centralized hydro dispatch. Neoenergia and other renewable platforms are installing lithium-ion arrays at substation level. This architecture is reducing frequency regulation dependence on thermal peakers and enabling merchant revenue streams from ancillary services.
ANEEL's updated distributed generation regulatory framework is mandating smart inverter standards for all new solar connections above ten kilowatts. Industrial consumers in Campinas and Sorocaba industrial parks are installing grid-forming inverters to maintain power quality during utility disturbances. The standard is accelerating microgrid controller adoption across São Paulo state's manufacturing belt.
Corporate renewable energy procurement through bilateral contracts is displacing traditional utility tariff structures for large consumers. Mining operations in Pará and iron ore processors in Minas Gerais are negotiating direct supply agreements with wind and solar developers. This behavior is most visible in the Southeast region where grid access constraints have created premium pricing for firm renewable supply.
Brazil Energy Sector Market Segmentation
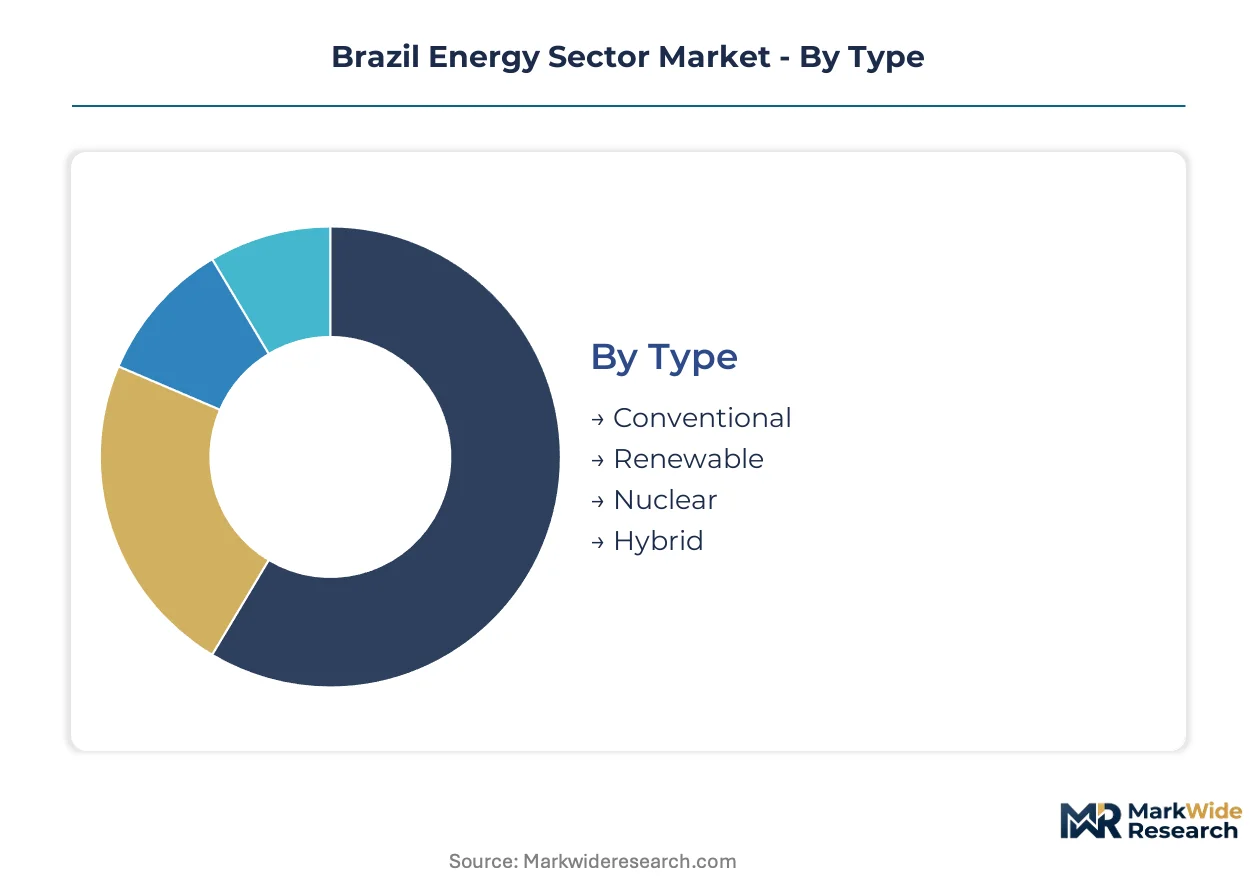
ANEEL licensing requirements and ANP operational permits create distinct compliance burdens across Brazil's energy segments. Certification pathways determine capital recovery timelines and dispatch priority for asset owners operating within national regulatory frameworks.
Type:
ANEEL generation licensing distinguishes conventional thermal assets from renewable dispatch priority tiers. ANP upstream concessions impose separate environmental licensing through IBAMA for offshore extraction.
- Conventional:Thermal plants burning natural gas, coal, or fuel oil require ANEEL thermal efficiency certifications and IBAMA atmospheric emissions licenses. Demand concentrates in São Paulo industrial corridors where grid stability requirements override carbon intensity concerns. Petrobras thermal dispatch contracts with Eletrobras transmission access dominate procurement.
- Renewable:Hydro, wind, solar, and biomass installations qualify for ANEEL priority dispatch certificates and BNDES concessional financing. Northeast wind zones and Minas Gerais solar belts concentrate developer activity. RenovaBio carbon intensity targets redirect ethanol and biomethane infrastructure investments toward this segment.
- Nuclear:Angra reactors operate under CNEN operational licenses with IAEA safeguard protocols. Eletrobras Eletronuclear maintains exclusive generation rights through constitutional energy charter provisions.
- Hybrid:Combined cycle and co-generation facilities blend thermal baseload with renewable peaking capacity. São Paulo sugarcane mills integrate bagasse power with grid-tied solar arrays.
Leading the category by volume: Renewable. Growing fastest: Hybrid.
Application:
Margin structures diverge sharply between long-term contracted power generation and volatile oil and gas upstream cycles.
- Power Generation:ANEEL regulated auctions and bilateral PPAs provide revenue certainty for hydro, wind, and solar assets. Eletrobras transmission backbone access determines project bankability across voltage classes. Northeast wind farms and pre-salt thermal backup dominate capacity additions.
- Oil & Gas:ANP concession rounds and production sharing contracts govern upstream economics. Santos Basin pre-salt operators deploy proprietary floating production systems. Higher-margin crude stream rebalancing compresses capital allocation timelines.
- Manufacturing:Steel and cement producers in Minas Gerais sign direct renewable supply agreements bypassing utility tariffs. Campinas and Sorocaba industrial parks install grid-forming inverters for power quality assurance.
- Transportation:Heavy transport fleets in São Paulo retrofit for hydrous ethanol blends under RenovaBio mandates. Port of Pecém infrastructure positions Ceará for green hydrogen export corridors.
Power Generation commands the deepest margin pools. Oil & Gas retains the steepest expansion trajectory in absolute capital deployment.
End User:
Procurement scale and contracting flexibility separate large industrial offtakers from fragmented residential demand.
- Industrial:Mining operations in Pará and iron ore processors negotiate firm renewable supply directly with developers. Grid access constraints in Southeast load centers create premium pricing for guaranteed dispatch.
- Commercial:ANEEL net metering expansion unlocks rooftop solar for consumers below seventy-five kilowatts. Billing credits transfer across multiple consumer units in Minas Gerais industrial zones.
- Residential:Distributed generation regulatory tailwinds accelerate microinverter adoption in urban centers. Smart inverter standards above ten kilowatts mandate grid-forming capabilities.
- Government:Federal procurement through BNDES credit lines steers capital toward decarbonization projects. State-level renewable mandates in São Paulo and Ceará anchor public sector demand.
Industrial offtakers lead procurement volume. Commercial segment expands most quickly behind regulatory net metering reforms.
Technology:
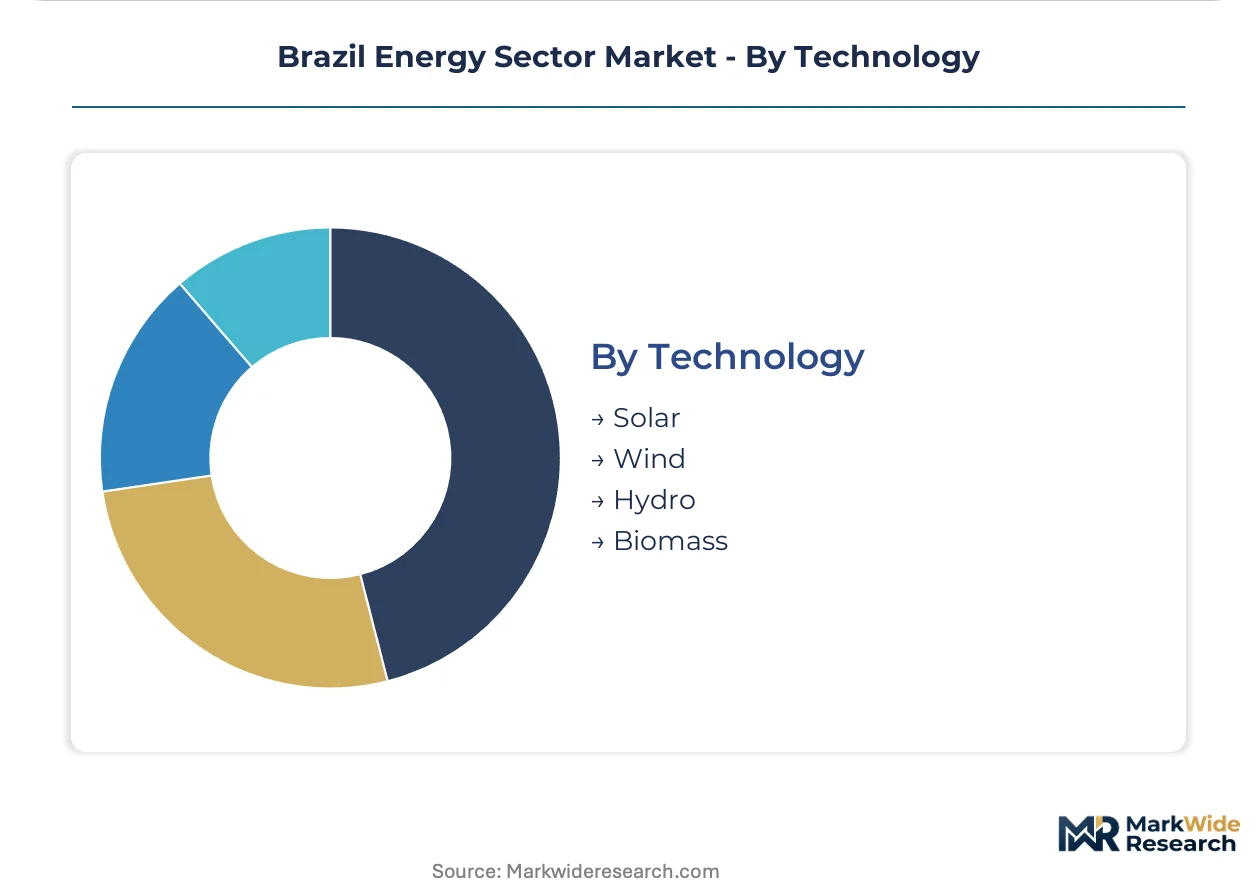
Grid parity dynamics and equipment import dependencies differentiate technology cost structures across Brazilian zones.
- Solar:Photovoltaic module deployment accelerates in Minas Gerais and São Paulo industrial belts. ANEEL smart inverter standards and distributed generation frameworks reduce soft costs. Module supply chains concentrate Asian manufacturing links.
- Wind:Northeast onshore zones achieve grid parity through Eletrobras transmission access negotiations. Rio Grande do Sul and Santa Catarina seabed conditions favor floating offshore pilot arrays adapted from oil and gas mooring systems.
- Hydro:Run-of-river plants require algorithmic trading system overhauls to coordinate with intermittent renewable dispatch. ANEEL spot price formation revisions accommodate storage arbitrage opportunities.
- Biomass:Sugarcane bagasse diversion to power generation constrains anaerobic digester feedstock for biomethane upgrading. São Paulo ethanol mills prioritize electricity sales over biogas production.
Hydro maintains installed base leadership. Solar gains share fastest behind distributed generation regulatory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-salt petroleum reservoirs in the Santos Basin anchor Brazil's upstream capital deployment. Industrial electricity demand concentrates in Southeast state manufacturing corridors where transmission access constraints shape procurement behavior.
São Paulo
Heavy manufacturing operations in steel and cement drive electricity procurement expansion. ANEEL net metering reforms unlock rooftop solar for commercial consumers below seventy-five kilowatts. Campinas and Sorocaba industrial parks install grid-forming inverters to maintain power quality during utility disturbances.
Minas Gerais
Iron ore processors negotiate direct renewable supply agreements bypassing traditional utility tariffs. Billing credits now transfer across multiple consumer units under expanded distributed generation frameworks. Solar deployment accelerates in industrial zones seeking to capture regulatory tailwinds.
Rio de Janeiro
The São Paulo-Rio de Janeiro industrial corridor concentrates transmission access requests from expanding manufacturing bases. ANEEL tariff methodologies determine distribution utility revenue ceilings and investment recovery timelines. Port infrastructure supports offshore supply chain logistics for floating production system deployment.
Rio Grande do Sul
Seabed conditions favor early pilot arrays for floating offshore wind technology adapted from oil and gas mooring systems. Grid interconnection standards determine asset valuations for renewable developers seeking Northeast wind zone parity. Manufacturing clusters evaluate bilateral renewable procurement contracts.
Bahia
Northeast wind resource density positions the region for grid parity dynamics through Eletrobras transmission access negotiations. RenovaBio carbon intensity targets redirect ethanol infrastructure investments toward low-carbon fuel pathways. Heavy transport fleets evaluate hydrous ethanol blend retrofits under ANP mandates.
Brazil Energy Sector Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue distributed generation and biomethane infrastructure positions. The market exhibits tiered concentration with state-controlled entities dominating upstream extraction and transmission backbones while private platforms capture renewable growth vectors. Three archetypes define competitive positioning: integrated oil majors with pre-salt extraction capabilities, state-backed transmission and generation utilities, and specialized renewable developers targeting grid parity zones. Capacity expansion in floating production systems and strategic partnerships for green hydrogen export corridors represent dominant competitive moves.
Among Brazil-based energy conglomerates, Petróleo Brasileiro S.A. - Petrobras exemplifies the integrated oil major archetype through its dominance of deepwater extraction activities. Eletrobras occupies a position representing state-backed transmission and generation utility structures. Neoenergia sits within the specialized renewable developer tier targeting Northeast wind zone opportunities. These three entities anchor the competitive landscape across upstream, midstream, and clean energy transition vectors without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Petróleo Brasileiro S.A. - Petrobras |
| Petro Rio SA |
| Ultrapar Participações SA |
| Cosan SA |
| 3R Petroleum Óleo e Gás SA |
| Enauta Participacoes SA |
| Petroreconcavo SA |
| Eletrobras |
| Neoenergia |
| Others |
Pricing and Supply Chain Analysis
Backward integration into ethanol milling and floating production system fabrication anchors supply positioning and pricing power for Brazilian energy conglomerates. Petrobras captive control over deepwater extraction technology and Eletrobras in-house transmission backbone ownership insulate cost structures from imported equipment volatility.
Pricing Analysis
Long-term offtake contract bundling with grid interconnection priority distinguishes premium renewable supply from spot-exposed thermal dispatch. Pricing stratifies across firm renewable supply, regulated utility tariffs, and merchant market exposure based on ANEEL dispatch certification tiers. Cost compression in thermal generation is intensifying because international operators reallocate exploration capital to Guyana-Suriname plays. Industrial offtakers in Minas Gerais steel and cement sectors exhibit lowest price sensitivity due to grid access constraints, while commercial rooftop solar consumers below seventy-five kilowatts show highest sensitivity to financing spreads.
Supply Chain Analysis
Single-source vulnerability sits with Chinese photovoltaic module manufacturing for Minas Gerais solar deployment. Equipment sourcing draws from China, South Korea, and Germany for wind turbine nacelles, solar inverters, and high-voltage transformers. Logistics chokepoint risk concentrates at Port of Pecém for green hydrogen export infrastructure and Santos Basin offshore supply bases. Distribution runs through Eletrobras transmission backbone access negotiations, with substation-level battery storage decentralizing final delivery architecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian energy markets function as a vertical-integration race where upstream control over pre-salt extraction technology and downstream grid interconnection priority determine competitive viability. Players pursue captive ethanol milling capacity and proprietary floating production system fabrication as decisive levers.
For Market Incumbents: To counter international operator capital flight to Guyana-Suriname acreage, Petrobras must deepen proprietary floating production system deployment in Santos Basin higher-margin crude streams. Eletrobras should accelerate transmission backbone expansion in Southeast load centers to defend renewable dispatch priority against Northeast wind zone grid parity challengers. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in firm renewable supply for industrial offtakers create entry windows for specialized developers. White-space targets concentrate in Minas Gerais distributed generation below seventy-five kilowatts and Ceará green hydrogen export corridor infrastructure. Direct bilateral PPA negotiation with iron ore processors offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated oil majors seeking renewable platform diversification. Long-term viability across the analysis window hinges on ANEEL regulatory tailwinds for distributed generation and BNDES concessional financing access. The signal to watch is ANP concession round bid-floor dispute resolution timelines as inflection indicator for upstream capital allocation sentiment.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Production System Deployment | Proprietary deepwater technology unlocks pre-salt reserves previously classified as non-commercial in Santos Basin. |
| Transmission Backbone Expansion | Eletrobras voltage-class additions reduce Northeast wind zone dispatch bottlenecks and grid interconnection queues. |
| Green Hydrogen Export Corridor Development | Port of Pecém electrolyzer infrastructure positions Brazil for European offtake contract capture. |
| Distributed Generation Platform Buildout | ANEEL net metering expansion unlocks rooftop solar billing credit transfer across multiple consumer units. |
| Biomethane Infrastructure Investment | RenovaBio carbon intensity targets redirect fuel distributor obligations toward anaerobic digester upgrading capacity. |
Research Methodology
Multi-period observation of ANEEL licensing queues, ANP concession round participation rates, and BNDES credit line disbursement patterns anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA data, IEA reports, ANEEL regulatory filings, and project development databases. Bottom-up capacity addition tracking and top-down macroeconomic scenario modeling enabled triangulation across data sources.
Input-output matrix framing connected fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type segmentation dimensions across the modeling period. CAGRs were derived through regression-based trajectory fitting against historical capacity deployment curves and policy scenario weighting. Forecast inputs incorporated ANEEL tariff methodology revision schedules and Petrobras pre-salt depletion curve assumptions.
Underlying measurement precision varies by segment; renewable capacity additions carry tighter precision than upstream reserve estimates due to disclosed project-level data availability. Forecasts reflect documented assumptions regarding ANEEL regulatory continuity and BNDES lending rate stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Industrial Energy Management System Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Thermostat Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Global Energy Consumption Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Microgrid Control System Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Smart Power Management Market
Energy Management
Connected Energy Market
Energy Management
Energy Harvesting System Market