
 UAV Lithium Battery Market | 2026-2036
UAV Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Lithium Battery Market Insights
Defense procurement is collapsing the historical dominance of commercial cinematography buyers in the UAV lithium battery space. EaglePicher Technologies anchors military-grade solid-state programs with decades of aerospace heritage. Amperex Technology Limited leverages its cylindrical cell expertise to supply high-rate discharge formats for tactical rotary-wing platforms. Shenzhen Grepow Battery competes aggressively on energy density customizations for racing and industrial UAV niches.
UAV lithium batteries are rechargeable electrochemical cells engineered to deliver high specific energy, typically 150-300 Wh/kg, under variable load profiles demanded by unmanned aerial propulsion, avionics, and payload systems. Lithium polymer dominates current deployments due to flexible form factors that conform to tight airframe geometries, while lithium iron phosphate gains structural share in agricultural and inspection drones where cycle life and thermal stability outweigh raw energy density. Delivery drone applications concentrate margin pools because last-mile logistics operators specify certified packs with integrated battery management systems and rapid-swap architectures.
FAA Part 107 commercial drone rules and the EU AI Act's autonomous system classifications shape product certification pathways, with the former governing flight operations and the latter imposing algorithmic transparency requirements on battery-integrated power management. China's GB standards and MIIT drone regulations enforce domestic cell sourcing quotas that redirect supply chain configurations. Stakeholders must monitor evolving thermal runaway test protocols from EASA and the FAA, as these will determine which chemistries and pack designs qualify for beyond-visual-line-of-sight operations.
Market Dynamics
Defense procurement budgets are redirecting cell manufacturing capacity toward military-grade solid-state formats, compressing commercial availability and forcing industrial buyers into longer qualification cycles.
Growth Catalysts
- FAA Part 107 commercial integration:Expanded beyond-visual-line-of-sight permissions in the United States are accelerating certified pack orders for logistics operators.
- China's dual carbon goals:Domestic NMPA certification requirements and production incentives are scaling local lithium-ion cell capacity for tactical drone fleets.
- High-discharge cylindrical formats:Rotary-wing tactical platforms are specifying 15C+ rate cells for rapid ascent maneuvers in contested airspace.
Market Restraints
- Cobalt and lithium carbonate volatility:Cathode material costs swing 40-60% annually, compressing pack margins for non-vertically integrated assemblers.
- Cell production concentration in China:Over 70% of global lithium polymer cell capacity sits in Guangdong and Jiangsu provinces, exposing supply chains to single-point geopolitical risk.
- Thermal runaway propagation limits:Current liquid electrolyte chemistries face hard caps on energy density before safety margins degrade, blocking next-generation endurance targets.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Subsidized domestic manufacturing is opening import-substitution plays for regional UAV assemblers.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separators paired with silicon anodes are enabling 400+ Wh/kg prototypes for long-endurance surveillance missions.
- Rapid-swap architecture penetration:Last-mile delivery operators in Germany and the Netherlands are specifying modular pack standards that decouple vehicle from battery ownership.
Industry Challenges
- EASA thermal runaway test protocol uncertainty:Pending beyond-visual-line-of-sight certification standards are freezing pack design lock-downs until 2025-2026 guidance clarifies.
- Electrolyte formulation talent scarcity:Solid-state ceramic processing expertise concentrates in Japanese and South Korean materials labs, limiting Western cell development velocity.
- Legacy avionics voltage incompatibility:New 48V and 800V pack architectures require complete power distribution redesigns for existing tactical airframes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Lithium Battery Market |
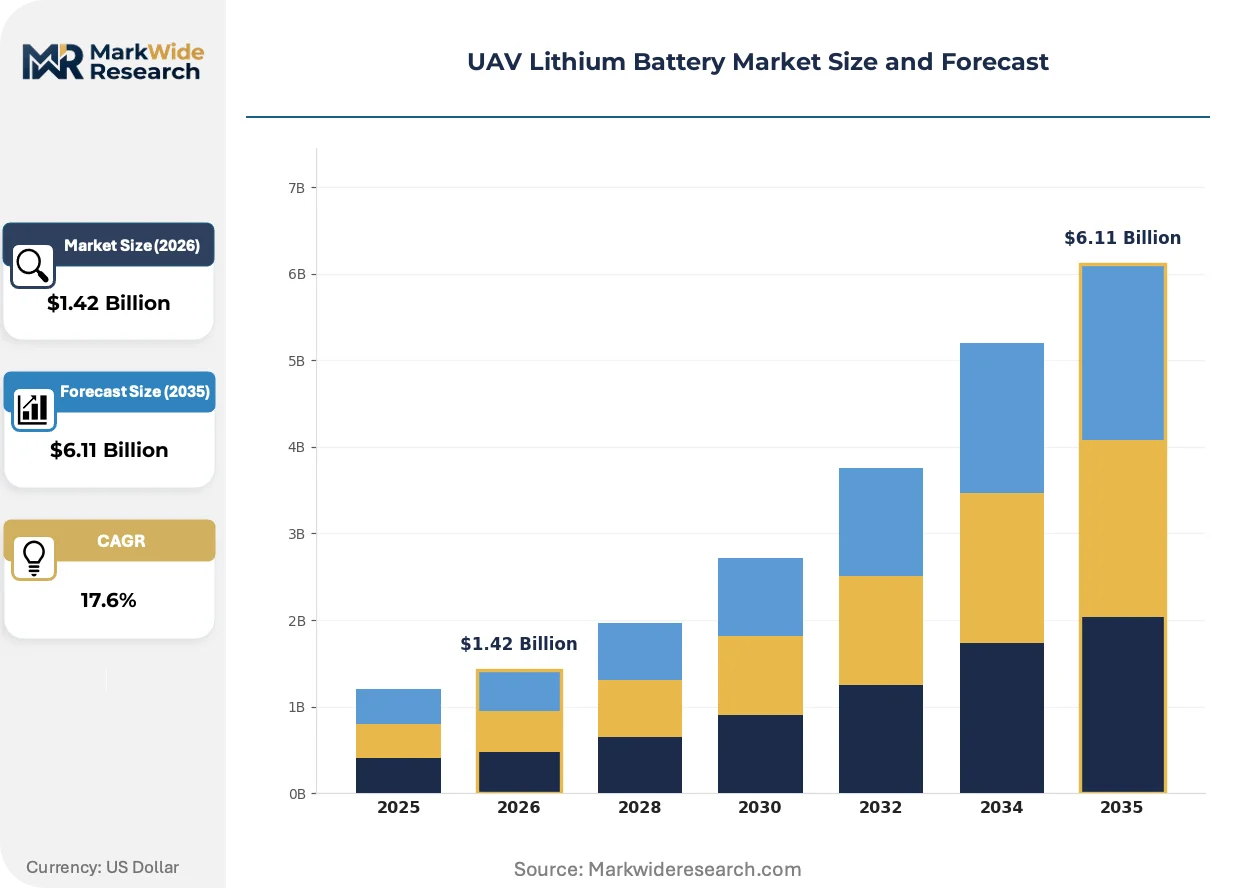
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Polymer, Lithium Iron Phosphate, Lithium Cobalt Oxide, Lithium Manganese Oxide, Lithium Nickel Cobalt Aluminum Application: Agricultural Drones, Surveillance Systems, Mapping & Survey, Delivery Drones, Search & Rescue, Cinematography End User: Defense & Security, Commercial Enterprises, Research Institutes, Energy Inspection Providers, Disaster Management Agencies Deployment Type: Fixed Wing UAVs, Rotary Wing UAVs, Hybrid UAVs, Tethered UAVs, Nano & Micro UAVs |
| Companies Covered | EaglePicher Technologies, Amicell, Amperex Technology Limited, Venom Power, COSMX, Shenzhen Grepow Battery, RRC Power Solutions GmbH, Tadiran Batteries, Sion Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Lithium Battery Market Trends and Innovations
Cell chemistry evolution and autonomous flight certification are compressing product development cycles while fragmenting buyer specifications across defense, logistics, and industrial inspection verticals.
Solid-state battery technology is miniaturizing pack volumes while maintaining thermal stability margins. Defense procurement offices in the United States and United Kingdom are piloting sulfide-electrolyte prototypes for micro-UAV swarms. This compression is enabling airframe designers to reclaim 15-20% of internal volume for sensor payloads without sacrificing endurance.
EU AI Act algorithmic transparency mandates are forcing battery management system firmware disclosures for autonomous flight platforms. Pack integrators must now document power prediction algorithms and thermal state estimation logic. Agricultural drone operators in France and Spain face the steepest compliance ramps as their fleets transition to unsupervised spraying missions.
Last-mile logistics buyers are consolidating procurement around certified pack-as-a-service contracts rather than capital purchases. German and Dutch delivery operators now specify per-flight-hour pricing with guaranteed swap-station availability. This shift concentrates margin pools with integrators who control both cell supply and ground infrastructure deployment.
UAV Lithium Battery Market Segmentation
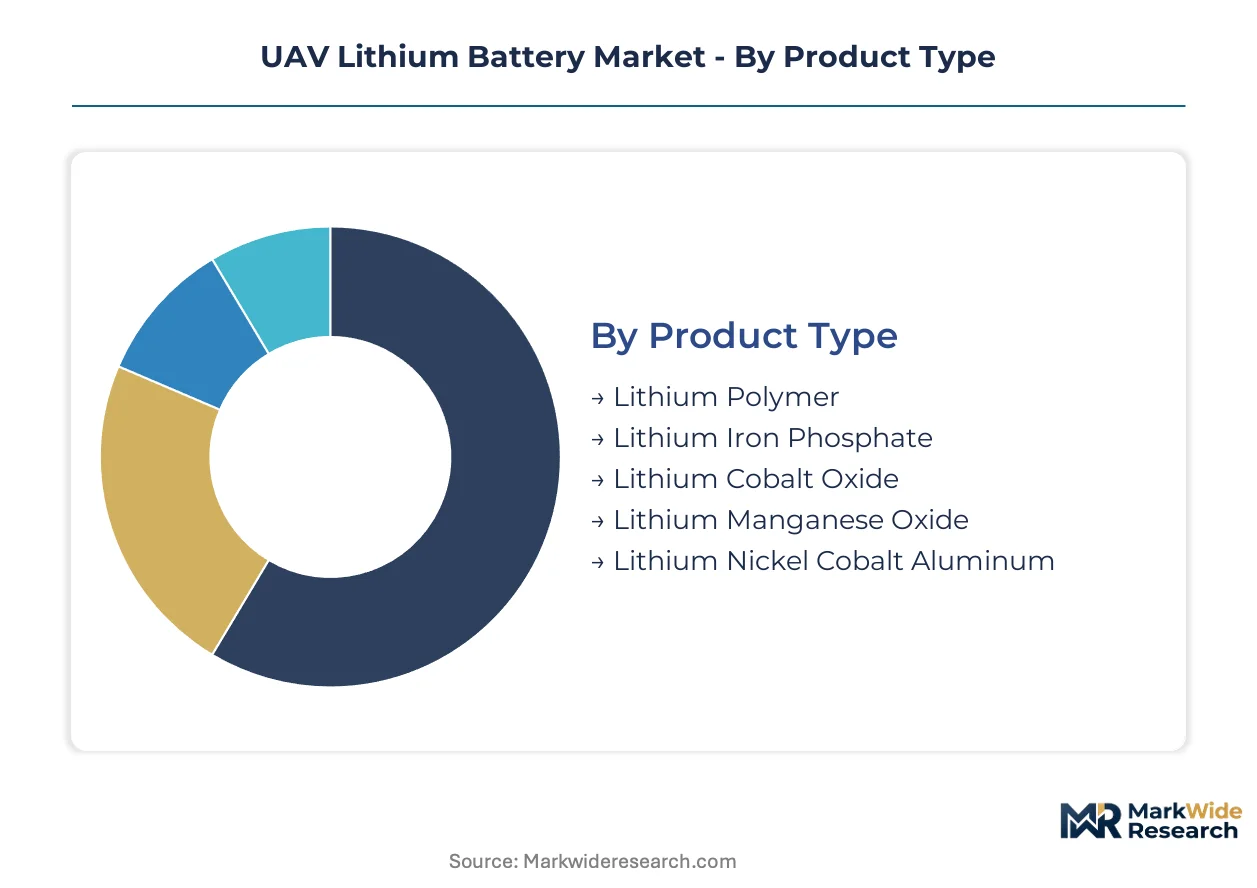
UAV lithium battery segmentation reveals divergent channel economics across chemistry formats and deployment architectures. Defense procurement offices, commercial logistics operators, and industrial service providers each route orders through distinct qualification pathways and pricing mechanisms.
Product Type:
Channel flow splits between certified military supply chains and spot-market commercial procurement, with chemistry selection determining which path dominates.
- Lithium Polymer:Flexible pouch cells dominate commercial cinematography and racing drone channels due to conformable form factors. Chinese cell manufacturers in Guangdong and Jiangsu provinces capture the bulk of spot-market volume for industrial inspection buyers.
- Lithium Iron Phosphate:Prismatic and cylindrical formats route through agricultural equipment dealers and energy inspection service providers. The chemistry's thermal stability satisfies FAA Part 107 requirements for extended-duration spraying missions in Florida and California agricultural corridors.
- Lithium Cobalt Oxide:High-energy density cylindrical cells feed defense procurement channels for micro-UAV swarms requiring minimal pack volume.
- Lithium Manganese Oxide:Moderate-cost cylindrical formats serve commercial mapping contractors through regional distributor networks in Germany and Japan.
- Lithium Nickel Cobalt Aluminum:Premium cylindrical cells concentrate in delivery drone programs with rapid-swap architectures specified by Dutch and German logistics operators.
By volume, lithium polymer leads. By growth pace, lithium iron phosphate is climbing the fastest as agricultural drone fleets expand.
Application:
Margin concentration varies sharply across use cases, with certification requirements and flight-hour intensity determining profitability tiers.
- Agricultural Drones:Spray platforms demand 500+ cycle life specifications under humid, dusty field conditions. Brazilian soybean operators and Californian vineyard managers drive replacement battery demand through seasonal intensity patterns.
- Surveillance Systems:Border patrol and infrastructure monitoring programs specify military-grade solid-state prototypes for 12+ hour endurance missions. UK and US defense procurement offices anchor this segment's technology roadmap.
- Mapping & Survey:Geospatial contractors prioritize weight reduction over cycle life, accepting 200-cycle packs for single-mission density advantages.
- Delivery Drones:Last-mile logistics operators in Germany and the Netherlands specify certified pack-as-a-service contracts with guaranteed swap-station density.
- Search & Rescue:Emergency response agencies in Alpine regions and coastal Japan require cold-weather discharge performance down to -20°C.
- Cinematography:Racing drone enthusiasts and commercial film operators drive demand for 15C+ discharge rates in compact formats.
Delivery drones command premium pricing per watt-hour. Agricultural drones generate the highest absolute cell volume through fleet scale.
End User:
Procurement sophistication separates defense buyers with multi-year qualification cycles from commercial operators seeking immediate availability.
- Defense & Security:US Army and UK Ministry of Defence programs mandate solid-state electrolyte roadmaps with decade-long development horizons. Tactical rotary-wing platforms specify 15C+ cylindrical formats for contested airspace maneuvers.
- Commercial Enterprises:Logistics operators and agricultural service providers purchase through regional distributors with 4-6 week lead times. Pricing sensitivity concentrates buying power with vertically integrated pack assemblers.
- Research Institutes:University labs and national research centers in Japan and South Korea prototype next-generation silicon anode configurations.
- Energy Inspection Providers:Wind turbine and solar farm operators in Texas and Rajasthan specify rapid-swap packs for minimal downtime during blade and panel surveys.
- Disaster Management Agencies:FEMA and Japan's Fire and Disaster Management Agency maintain strategic battery reserves with 10-year shelf life requirements.
Defense contracts carry the longest sales cycles. Commercial enterprises deliver the steadiest recurring revenue through fleet replacement schedules.
Deployment Type:
Airframe architecture dictates voltage, thermal management, and form factor requirements with minimal cross-compatibility.
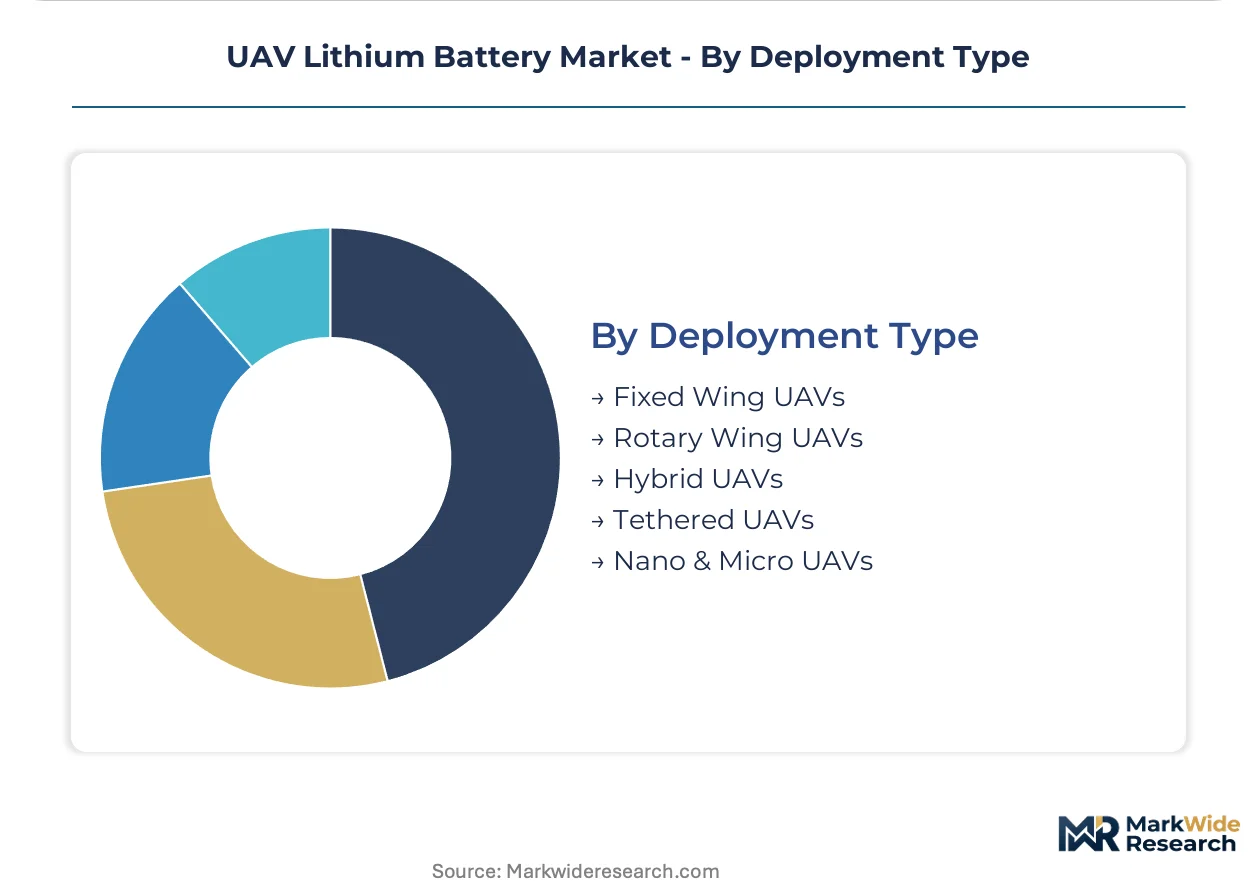
- Fixed Wing UAVs:High-aspect-ratio platforms for long-endurance surveillance specify 48V and 800V pack architectures. New voltage standards require complete power distribution redesigns for legacy tactical airframes.
- Rotary Wing UAVs:Multirotor configurations dominate commercial cinematography and agricultural spraying with 6S-12S lithium polymer configurations. Rapid ascent maneuvers in tactical applications drive 15C+ discharge rate specifications.
- Hybrid UAVs:Vertical-takeoff-and-landing fixed-wing designs combine cruise efficiency with hover capability, demanding dual-mode power management firmware.
- Tethered UAVs:Persistent surveillance platforms use onboard batteries as backup power only, reducing energy density requirements while emphasizing cycle stability.
- Nano & Micro UAVs:Swarm-capable platforms under 250 grams drive miniaturization of solid-state prototypes for US Army and UK Defence Science and Technology Laboratory programs.
Rotary wing platforms generate the highest cell volume through commercial fleet scale. Nano and micro UAVs are expanding most quickly as defense swarm programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific lithium cell flows into North American UAV assembly lines. German rail corridors through the Rhine-Alpine network distribute high-rate cylindrical formats to Dutch and Polish drone integrators. China's Ningbo-Zhoushan port complex handles cathode precursor shipments feeding Guangdong polymer cell plants.
United States
Defense procurement offices in Arlington and Dayton drive solid-state battery qualification programs for tactical drone swarms. FAA Part 107 beyond-visual-line-of-sight rulemaking accelerates certified pack orders from logistics operators. The Dallas-Fort Worth metroplex clusters battery management system firmware developers serving agricultural spraying fleets across the Great Plains.
China
NMPA certification requirements and MIIT drone regulations enforce domestic cell sourcing quotas for tactical fleets. Dual carbon goals accelerate lithium iron phosphate capacity expansion in Jiangsu and Guangdong provinces. Shenzhen's Bao'an district concentrates polymer cell manufacturing for racing and cinematography drone exporters.
Germany
Last-mile logistics operators in Berlin and Hamburg specify rapid-swap pack standards with guaranteed station density. EU AI Act algorithmic transparency mandates force battery management system disclosures for autonomous flight platforms. Bavaria's Munich aerospace corridor hosts power electronics specialists designing 48V architectures for fixed-wing surveillance platforms.
Japan
METI funding programs support solid-state electrolyte prototyping for long-endurance micro-UAV applications. JIS standards govern thermal runaway test protocols shaping pack designs for domestic disaster response agencies. Nagoya's Chubu region concentrates ceramic separator processing expertise for next-generation silicon anode configurations.
India
PLI scheme subsidies for advanced chemistry cells attract regional UAV assemblers seeking import substitution. DGFT tariff structures redirect supply chains toward domestic cylindrical cell production. Karnataka's Bangalore-Tumkur corridor clusters drone OEMs qualifying locally assembled lithium polymer packs for agricultural spraying contracts.
UAV Lithium Battery Market Competitive Landscape
Concentration sits with defense-aerospace heritage specialists and high-volume cylindrical cell manufacturers. The vendor base splits between military qualification holders with decade-long development horizons and commercial spot-market suppliers serving industrial inspection buyers. Two archetypes dominate: vertically integrated pack assemblers controlling cell supply and ground infrastructure, and chemistry-focused cell specialists licensing formats to third-party integrators. Competitive moves center on capacity expansion in solid-state electrolyte processing and strategic partnerships around rapid-swap architecture standards.
Among defense-aerospace specialists, EaglePicher Technologies and Tadiran Batteries occupy positions anchored by military program heritage. Amperex Technology Limited exemplifies the high-rate cylindrical cell archetype supplying rotary-wing tactical platforms. Shenzhen Grepow Battery sits within the commercial customization tier, serving racing and industrial UAV niches with energy density variants. RRC Power Solutions GmbH represents European pack integration capabilities aligned with German logistics operator specifications.
| Leading Market Players |
|---|
| EaglePicher Technologies |
| Amicell |
| Amperex Technology Limited |
| Venom Power |
| COSMX |
| Shenzhen Grepow Battery |
| RRC Power Solutions GmbH |
| Tadiran Batteries |
| Sion Power |
| Others |
Pricing and Supply Chain Analysis
FAA Part 107 certification requirements and EASA thermal runaway protocols gate both supplier qualification and price tiering simultaneously, forcing pack integrators to absorb compliance costs into premium-tier offerings while spot-market buyers face extended lead times for uncertified alternatives.
Pricing Analysis
Volume-discount tiering separates defense procurement contracts from commercial spot purchases, with military buyers locking decade-long offtake agreements at fixed rates while agricultural operators face quarterly repricing based on lithium carbonate spot movements. Price differentiation hinges on certification grade—FAA Part 107 and EASA BVLOS compliance adds substantial premiums—and vertical integration depth, with cell manufacturers controlling cathode precursor supply commanding margin advantages. Cost compression in commercial cinematography packs is intensifying because Chinese polymer cell oversupply forces racing drone specialists into 15C+ rate wars. Defense buyers exhibit the lowest price sensitivity due to mission-critical specifications, while Brazilian agricultural cooperatives drive hardest bargain negotiations through seasonal volume consolidation.
Supply Chain Analysis
Inventory buffers at Ningbo-Zhoushan port complex and Guangdong polymer plants have compressed from eight weeks to three weeks as defense procurement redirects cell capacity toward solid-state qualification batches. Manufacturing concentrates in China, South Korea, and Japan, with Jiangsu and Guangdong provinces hosting over seventy percent of global lithium polymer pouch capacity. Cathode precursor supply draws from Indonesian nickel processing and Chilean lithium brine operations, tethering pack assemblers to commodity volatility. Single-source vulnerability sits with ceramic separator processing expertise concentrated in Nagoya's Chubu region. Distribution runs through defense-aerospace prime contractors for military channels and regional drone OEM distributors for commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around German and Dutch logistics operators specifying pack-as-a-service contracts, fragmenting pricing leverage among smaller agricultural and cinematography fleet operators.
For Market Incumbents: Fortify solid-state electrolyte roadmaps through captive sulfide ceramic processing partnerships in Japan or South Korea, as defense procurement offices freeze design lock-downs pending EASA thermal runaway guidance. Deepen backward integration into silicon anode precursor supply to offset cobalt and lithium carbonate volatility compressing commercial pack margins. Channel control through rapid-swap station infrastructure deployment secures recurring revenue against spot-market price erosion. For New Entrants and Emerging Players: Lead with India's PLI-subsidized cylindrical cell assembly for agricultural drone OEMs in Karnataka's Bangalore-Tumkur corridor, where import substitution demand outpaces domestic supply qualification. White-space concentration sits with cold-weather discharge packs for Alpine search-and-rescue agencies and Japanese disaster management reserves, segments underserved by tropical-optimized Chinese suppliers. Go-to-market positioning as certified rapid-swap architecture specialists bypasses direct cell manufacturing capital intensity. For Investors and Strategic Acquirers: EASA beyond-visual-line-of-sight certification standard finalization reshapes the acquisition landscape toward pack integrators with pre-qualified thermal runaway test data and firmware transparency documentation. Long-term viability over a five-to-ten year window favors vertically integrated specialists controlling both cell chemistry and battery management system algorithm development. Acquisition target archetype: mid-cap pack assemblers with defense program heritage and commercial logistics operator contracts. Signal to watch: solid-state prototype flight-hour accumulation in US Army and UK Ministry of Defence micro-UAV swarm programs.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Scale-Up | Sulfide ceramic processing capacity expansion enables 400+ Wh/kg prototypes for surveillance missions. |
| Rapid-Swap Infrastructure Deployment | Modular pack standardization captures German and Dutch logistics operator recurring revenue pools. |
| Defense-Aerospace Certification Investment | FAA and EASA thermal runaway pre-qualification secures BVLOS program design lock-downs. |
| Backward Integration into Cathode Supply | Captive lithium iron phosphate precursor production insulates margins from carbonate volatility. |
| Solid-State Talent Acquisition | Japanese and South Korean ceramic separator expertise recruitment accelerates Western development velocity. |
Research Methodology
Desk research of customs trade databases, FAA regulatory filings, and EASA safety directives preceded structured interviews with defense procurement officers, commercial logistics fleet managers, agricultural drone OEM technical leads, and polymer cell manufacturing executives. Primary fieldwork across Shenzhen's Bao'an district, Dallas-Fort Worth metroplex, and Bavaria's Munich aerospace corridor validated secondary estimates of capacity expansion timelines and certification pathway durations. Bottom-up cell shipment tracking and top-down defense budget allocation analysis were triangulated against pack assembler revenue disclosures.
Variance decomposition across chemistry format, deployment architecture, and end-user procurement sophistication drove segment-level growth attribution throughout the projection horizon. The analytical framework modeled lithium polymer, lithium iron phosphate, and emerging solid-state formats separately, with rotary-wing versus fixed-wing voltage standards and defense versus commercial qualification cycles as cross-cutting dimensions. CAGRs were derived from installed fleet replacement schedules and beyond-visual-line-of-sight regulatory enablement curves. Forecast inputs incorporated cathode material cost indices and solid-state prototype flight-hour accumulation rates from US Army and UK Defence Science and Technology Laboratory programs.
Forecasts assume regulatory continuity in FAA Part 107 rulemaking and EASA thermal runaway protocols; material policy shifts or accelerated solid-state commercialization timelines would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market