
 Cogeneration System Market | 2026-2036
Cogeneration System Market Size, Share, and Industry Trends Forecast 2026-2036
Cogeneration System Market Analytics
Turbine engineering talent scarcity is bifurcating the competitive landscape between integrated OEMs and specialized service providers. Siemens Energy leverages its gas turbine manufacturing depth to anchor European district energy contracts. Mitsubishi Heavy Industries dominates large-scale industrial installations across Asia-Pacific through captive supply of heavy rotating equipment. Clarke Energy specializes in reciprocating engine packages for biogas applications, competing on fuel flexibility rather than unit scale.
A cogeneration system simultaneously produces electricity and useful thermal energy from a single fuel source, typically achieving total fuel efficiency of 75-90 percent through heat recovery steam generators or absorption chillers. The technology serves industrial facilities, hospitals, and district heating networks requiring steady baseload power with process steam or space conditioning. Gas turbine deployments lead in utility-scale applications where high exhaust temperatures enable combined-cycle augmentation, while reciprocating engines capture margin pools in sub-20 MW commercial and biogas projects. Microturbine adoption accelerates in urban commercial buildings constrained by emissions ordinances and limited mechanical footprints.
The EPA regulates stationary source emissions under the Clean Air Act, compelling operators to evaluate best available control technology for NOx and CO output. FERC Order 2222 facilitates distributed energy resource participation in wholesale markets, reshaping revenue stacking for behind-the-meter cogeneration assets. ISO 50001 energy management standards and EU ETS carbon pricing create compliance-driven replacement cycles for aging coal-fired cogeneration plants. Stakeholders must weigh fuel price volatility against regulatory certainty when committing to twenty-year asset lifecycles.
Market Dynamics
Data center operators are accelerating on-site power procurement as EPA emissions rules tighten for distributed generation assets, compressing project timelines and favoring modular equipment configurations over custom-engineered installations.
Growth Catalysts
- FERC Order 2222:Distributed energy resource participation in wholesale markets is reshaping revenue stacking for behind-the-meter cogeneration assets, enabling new monetization pathways for industrial facilities.
- Industrial boiler retrofits:Aging coal-fired infrastructure in Germany, China, and the United States is driving replacement demand for gas turbine and reciprocating engine packages with integrated heat recovery.
- Heat recovery steam generators:Combined-cycle augmentation capabilities are expanding addressable market size for utility-scale installations seeking total fuel efficiency above 75 percent.
Market Restraints
- Natural gas price volatility:Twenty-year asset lifecycles expose operators to fuel cost uncertainty that undermines project finance certainty and return thresholds.
- Turbine engineering talent scarcity:Specialized rotating equipment expertise concentrates at integrated OEMs, limiting service provider capacity and extending commissioning timelines.
- NOx control technology costs:EPA Clean Air Act best available control technology mandates add capital intensity to projects in non-attainment zones.
Strategic Opportunities
- Biogas-to-power projects:Agricultural and wastewater treatment facilities in rural Germany and the United States present underpenetrated demand for reciprocating engine packages with fuel flexibility.
- EU ETS carbon pricing:Compliance-driven replacement cycles for coal-fired district heating plants in Eastern Europe create equipment procurement windows for low-carbon gas turbine solutions.
- Microturbine-thermal storage convergence:Urban commercial buildings constrained by emissions ordinances and limited mechanical footprints are adopting sub-1 MW configurations with absorption chiller integration.
Industry Challenges
- Commissioning engineer shortage:Specialized expertise in gas turbine alignment and heat recovery steam generator integration extends project handover timelines and inflates EPC contractor premiums.
- ISO 50001 certification complexity:Energy management system documentation requirements impose administrative burden on mid-sized industrial facilities lacking dedicated sustainability personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cogeneration System Market |
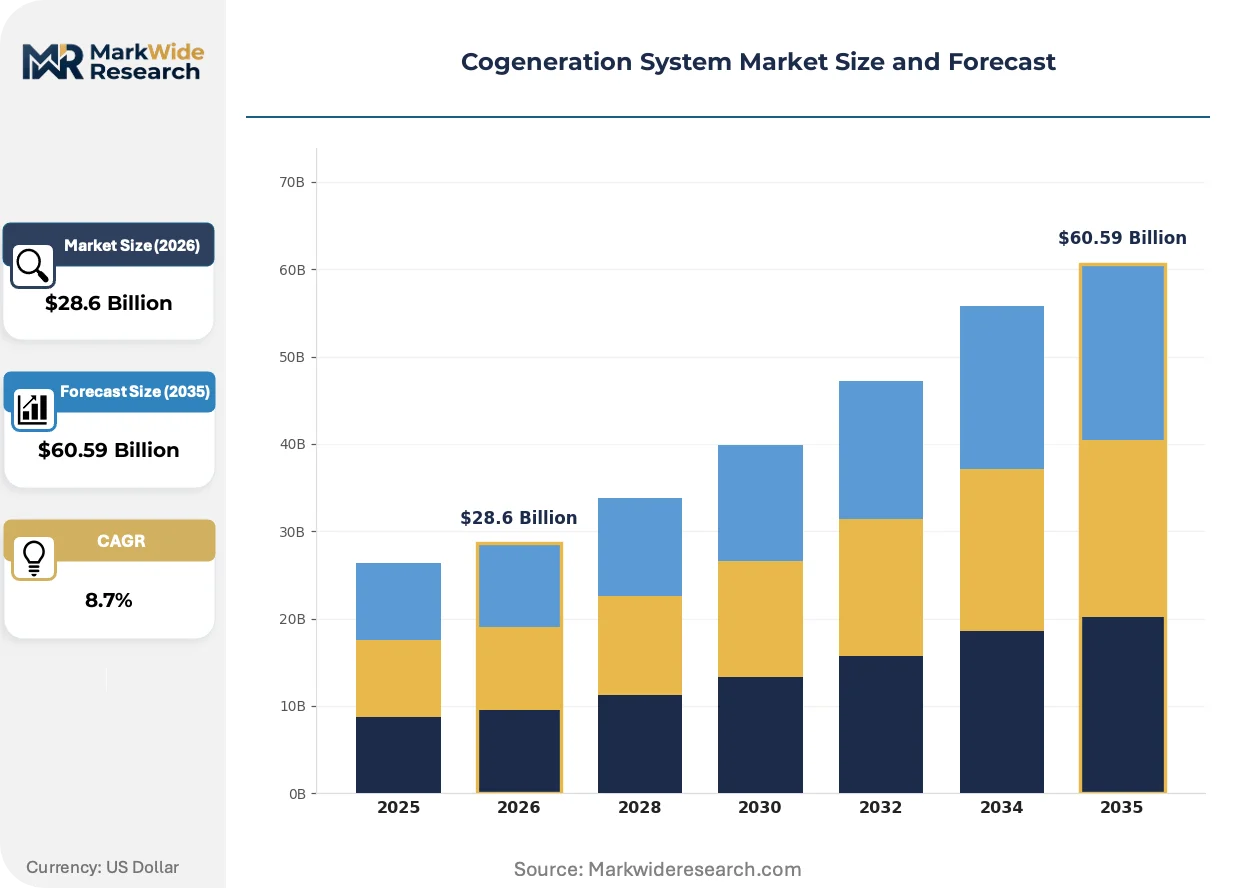
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbine, Gas Turbine, Reciprocating Engine, Microturbine End User: Industrial, Commercial, Residential, Healthcare Fuel Type: Natural Gas, Biomass, Coal, Oil Deployment: On-site, Off-site, District Energy, Hybrid |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, 2G Energy, Kawasaki Heavy Industries, ABB, Clarke Energy, Rolls-Royce, Andritz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cogeneration System Market Evolving Landscape
Equipment architectures are converging around modular, factory-integrated packages that compress field assembly timelines and reduce site-specific engineering dependencies. This standardization push is redistributing value capture between OEMs and EPC contractors.
Absorption chiller integration with microturbine exhaust heat is supplanting conventional electric vapor compression in urban hospital and university district cooling networks. Facility managers in emissions-constrained municipalities are specifying these configurations to avoid local air quality permitting delays. The technology is compressing addressable market scope for traditional chiller OEMs while opening margin pools for thermal engineering specialists.
EPA's stationary source emissions framework under the Clean Air Act is compelling operators to evaluate selective catalytic reduction and lean-premix combustion retrofits ahead of permit renewal cycles. Industrial facilities in ozone non-attainment zones face accelerated compliance timelines that favor equipment replacement over control technology add-ons. Gas turbine deployments in Texas and California are experiencing procurement surge as operators preempt regulatory enforcement windows.
Hospital and university procurement committees are consolidating vendor relationships around single-source accountability for power and thermal output guarantees. Traditional split-responsibility contracts between electrical and mechanical contractors are losing share to integrated performance contracting models. This concentration is most visible in the Northeastern United States, where energy-as-a-service providers are capturing long-term operational contracts alongside initial equipment supply.
Cogeneration System Market Segmentation
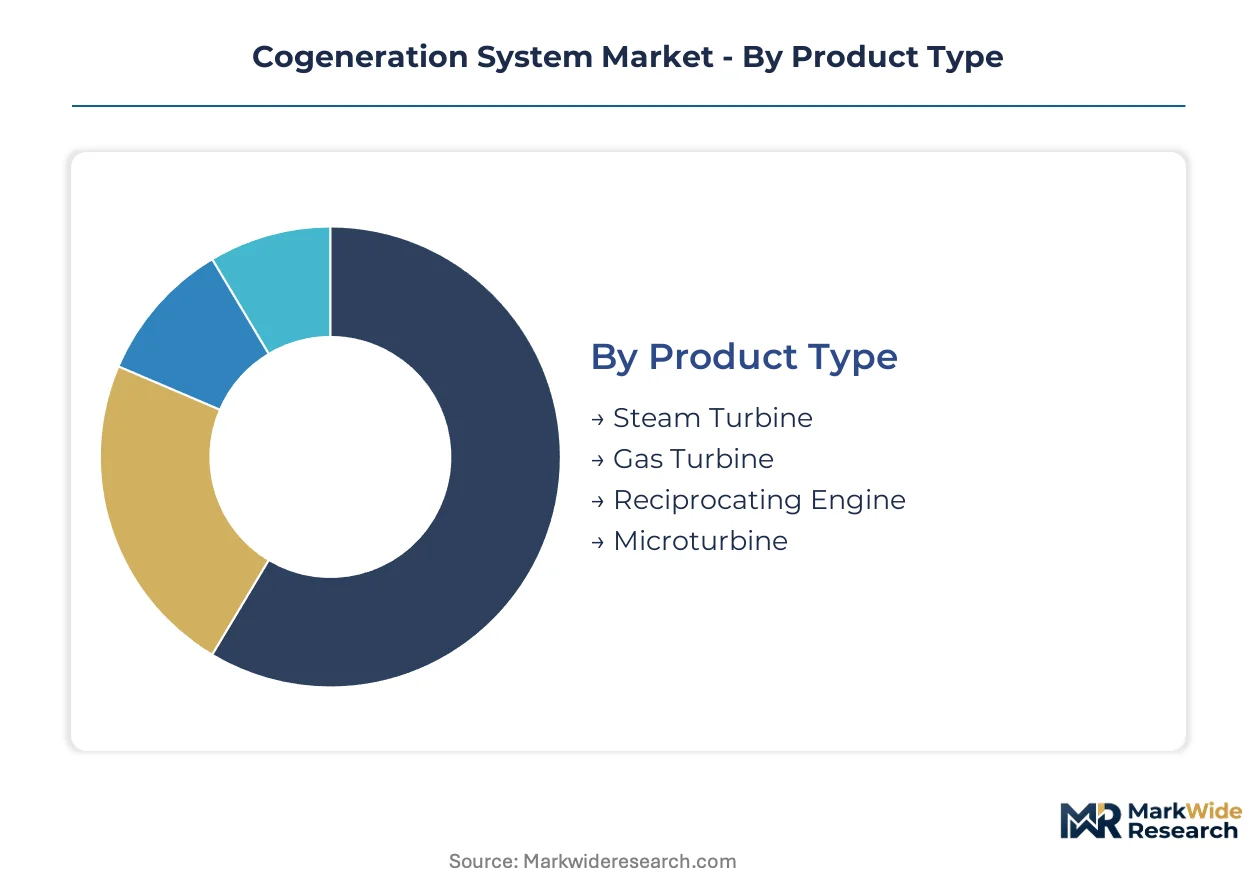
Cogeneration equipment selection hinges on scale-to-thermal requirements, fuel availability, and regulatory emissions thresholds. Procurement committees weigh twenty-year operational lifecycles against modular upgrade pathways when committing to specific technology configurations.
Product Type:
Gas turbine systems dominate export markets through large-scale utility and industrial applications, while reciprocating engines and microturbines concentrate in domestic commercial and biogas projects.
- Steam Turbine:Heavy rotating equipment converting high-pressure steam into mechanical power for process industries. Demand concentrates in Germany and China where aging coal-fired boiler infrastructure requires replacement with integrated heat recovery configurations.
- Gas Turbine:Combustion turbines achieving exhaust temperatures above 500°C that enable combined-cycle augmentation. Utility-scale installations across Texas and California are accelerating procurement ahead of EPA Clean Air Act enforcement windows.
- Reciprocating Engine:Piston-driven prime movers with fuel flexibility for biogas and natural gas applications. Agricultural facilities in rural Germany specify these packages for sub-20 MW distributed generation.
- Microturbine:Sub-1 MW configurations with absorption chiller integration for urban commercial buildings. Emissions-constrained municipalities in the Northeastern United States favor these for avoided permitting delays.
Gas turbine systems hold the largest share; momentum sits with microturbine configurations in urban emissions zones.
End User:
Industrial facilities command premium engineering resources through process steam requirements, while healthcare and commercial segments drive volume through standardized equipment packages.
- Industrial:Manufacturing plants requiring steady baseload power with high-pressure process steam. Refinery and chemical complexes along the US Gulf Coast anchor replacement demand as EPA stationary source rules tighten.
- Commercial:Office buildings, hotels, and retail centers seeking space conditioning with behind-the-meter generation. District cooling networks in Japanese urban centers specify absorption chiller integration.
- Residential:Multi-family developments and micro-district heating applications. Scandinavian municipal utilities deploy small-scale gas engine packages for neighborhood thermal grids.
- Healthcare:Hospitals requiring uninterrupted power with sterilization steam and space conditioning. University medical centers in the Northeastern United States consolidate vendor relationships around single-source performance guarantees.
Industrial applications anchor equipment revenue; healthcare facilities are expanding most quickly through energy-as-a-service procurement models.
Fuel Type:
Natural gas infrastructure availability determines geographic deployment feasibility, while biomass and coal access reflects regional resource endowments and carbon pricing exposure.
- Natural Gas:Pipeline-delivered fuel enabling lean-premix combustion with lower NOx profiles. US interstate pipeline networks support distributed generation economics in shale-proximate regions.
- Biomass:Agricultural residues and dedicated energy crops for rural industrial heat and power. Eastern European district heating utilities evaluate conversion under EU ETS carbon pricing pressure.
- Coal:Solid fuel combustion in legacy cogeneration infrastructure facing replacement cycles. Chinese industrial facilities retrofit aging boiler-turbine sets with integrated emissions controls.
- Oil:Distillate and residual fuel oil for backup and peaking applications in islanded grids. Caribbean and remote Alaskan installations maintain dual-fuel capability for supply security.
Natural gas dominates installed capacity; biomass-to-power projects are climbing the fastest under compliance-driven carbon accounting.
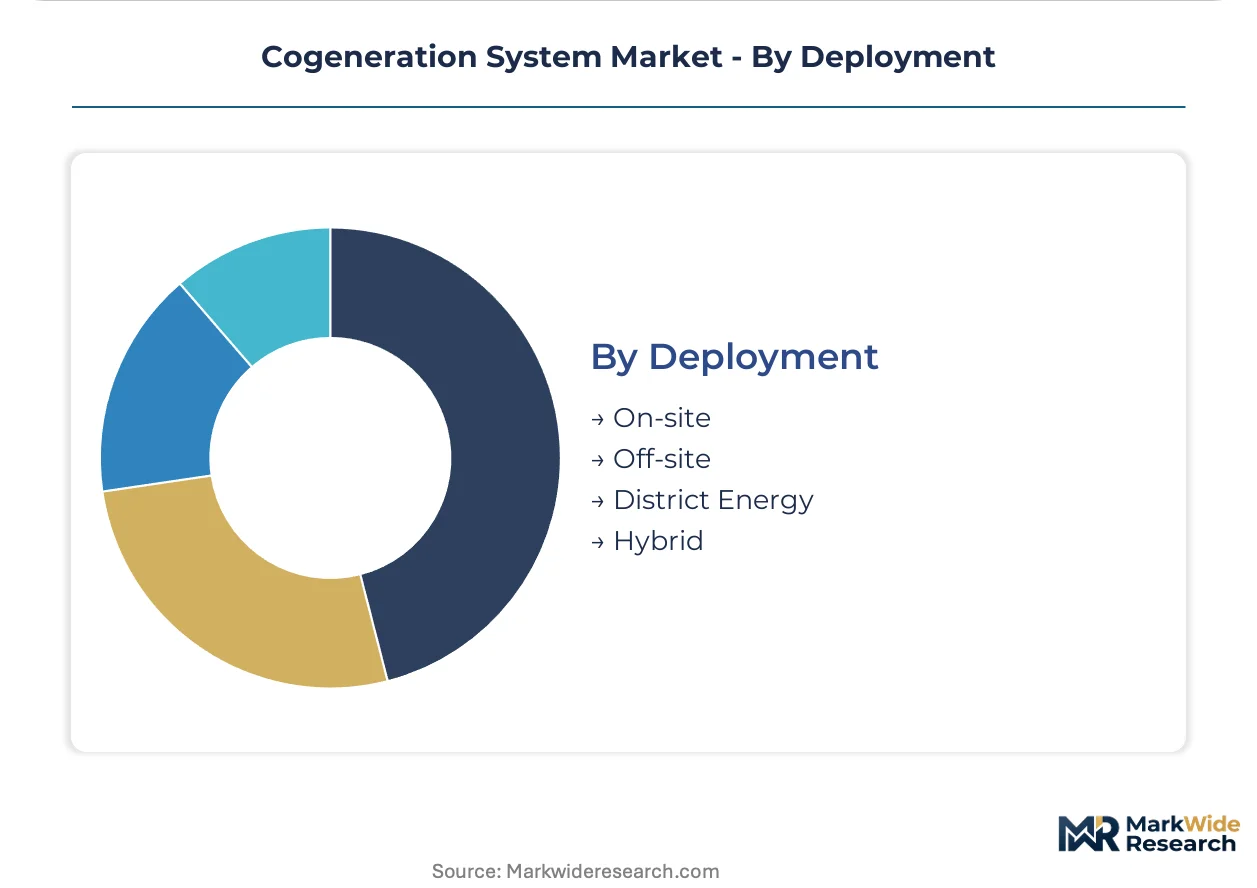
Deployment:
On-site generation captures industrial margin pools through avoided transmission charges, while district energy and hybrid models require municipal or utility-scale coordination.
- On-site:Behind-the-meter installation at industrial or commercial facilities with dedicated thermal loads. Data center operators in Northern Virginia and Phoenix accelerate procurement as FERC Order 2222 enables wholesale market participation.
- Off-site:Centralized generation with thermal energy transport to multiple customers. University campus contracts in the United States specify twenty-year heat and power purchase agreements.
- District Energy:Municipal-scale thermal grids serving mixed-use urban developments. Copenhagen and Stockholm networks demonstrate operational maturity with seasonal thermal storage integration.
- Hybrid:Combined heat, power, and cooling configurations with thermal storage and renewable integration. Singapore district cooling projects pair absorption chillers with solar thermal augmentation.
On-site deployment holds the largest share; hybrid configurations are gaining share fastest through renewable integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys cogeneration predominantly for district heating networks, while the United States concentrates installations at industrial facilities and data centers seeking behind-the-meter resilience. China anchors equipment manufacturing capacity and domestic coal-to-gas retrofit demand.
United States
Data center operators in Northern Virginia and Phoenix accelerate on-site power procurement as FERC Order 2222 enables wholesale market participation for distributed assets. EPA Clean Air Act enforcement windows in Texas and California compress project timelines toward modular gas turbine configurations. Refinery complexes along the Gulf Coast anchor replacement demand for integrated heat recovery systems.
Germany
Agricultural biogas facilities in rural regions specify reciprocating engine packages with fuel flexibility for sub-20 MW distributed generation. EU ETS carbon pricing drives compliance-based replacement cycles for coal-fired district heating plants in Eastern municipalities. Municipal utilities in Copenhagen-adjacent networks demonstrate operational maturity with seasonal thermal storage integration.
China
Industrial facilities retrofit aging coal-fired boiler-turbine sets with integrated emissions controls under national dual carbon goals. The Ministry of Ecology and Environment tightens stationary source standards for NOx and particulate output. Manufacturing clusters in Shandong and Jiangsu provinces concentrate domestic equipment demand for process steam applications.
Japan
District cooling networks in Tokyo and Osaka urban centers specify absorption chiller integration with gas turbine exhaust heat. METI efficiency standards accelerate replacement of aging industrial cogeneration assets with combined-cycle configurations. University medical centers consolidate vendor relationships around single-source performance guarantees for uninterrupted power.
India
CEA grid reliability mandates push pharmaceutical and textile clusters in Gujarat and Maharashtra toward captive generation with thermal recovery. State-level industrial policies incentivize natural gas infrastructure expansion for lean-premix combustion deployments. Special economic zones in Tamil Nadu specify hybrid configurations with renewable integration for export-oriented manufacturing.
Cogeneration System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the competitive landscape bifurcating between OEMs with captive turbine manufacturing and service providers competing on fuel flexibility. Siemens Energy leverages gas turbine manufacturing depth to anchor European district energy contracts, while Mitsubishi Heavy Industries dominates large-scale industrial installations across Asia-Pacific through captive supply of heavy rotating equipment. Strategic moves concentrate on modular equipment standardization to compress field assembly timelines and vertical integration into heat recovery steam generator production.
Within the integrated OEM tier, GE Vernova and Siemens Energy exemplify scale-driven positions anchored in combustion turbine manufacturing heritage. Clarke Energy occupies a specialist position focused on reciprocating engine packages for biogas applications, competing on fuel flexibility rather than unit scale. These three represent the dominant competitive archetypes: full-stack OEMs with manufacturing depth, and niche specialists with application-specific expertise.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| 2G Energy |
| Kawasaki Heavy Industries |
| ABB |
| Clarke Energy |
| Rolls-Royce |
| Andritz |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with integrated OEMs lock in turbine availability and price visibility for data center operators and industrial facilities committing to twenty-year asset lifecycles. These contracts transfer fuel price risk to buyers while securing manufacturing slots for heat recovery steam generators and emissions control packages.
Pricing Analysis
Project-based equipment procurement dominates utility-scale installations, with pricing stratifying across premium, standard, and economy tiers based on OEM manufacturing depth and after-sales service bundling. Price differentiation centers on combustion turbine efficiency ratings and EPA compliance certification levels. Cost compression in the standard tier intensifies because Chinese manufacturers expand export capacity for coal-retrofit markets. Hospital procurement committees demonstrate lowest price sensitivity due to uninterrupted power requirements, while commercial real estate developers in emissions-constrained municipalities face acute budget pressure.
Supply Chain Analysis
Strategic stockpiling of specialized alloys and precision castings characterizes OEM inventory management given extended lead times for gas turbine rotors and heat recovery components. Manufacturing concentrates in Germany, Japan, and the United States for heavy rotating equipment, with China anchoring cost-optimized boiler-turbine sets for domestic retrofit demand. Raw material dependencies draw from nickel-based superalloys, high-grade steel forgings, and selective catalytic reduction catalyst substrates. Single-source vulnerability persists for sub-20 MW reciprocating engine crankshafts produced by limited European machine shops. Distribution runs through EPC contractor networks with captive installation crews for field assembly and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222 and EPA Clean Air Act enforcement windows are accelerating procurement velocity beyond historical replacement cycles, compressing vendor selection timelines and favoring modular equipment configurations.
For Market Incumbents: Consolidate service capabilities around heat recovery steam generator maintenance and selective catalytic reduction retrofits to capture recurring revenue from installed gas turbine bases. Siemens Energy and Mitsubishi Heavy Industries should deepen backward integration into precision casting supply to mitigate single-source vulnerability for rotating components. Defensive positioning requires preemptive certification investment for EPA best available control technology tiers ahead of permit renewal windows. For New Entrants and Emerging Players: Differentiate on fuel flexibility for agricultural biogas and wastewater treatment applications where Clarke Energy has established limited geographic presence. The most penetrable white-space sits in sub-5 MW microturbine deployments for urban university district cooling networks in the Northeastern United States. A compelling go-to-market angle pairs absorption chiller integration with energy-as-a-service operational contracts to bypass upfront capital constraints. For Investors and Strategic Acquirers: Specialist EPC contractors with captive commissioning engineer teams represent attractive acquisition targets given talent scarcity extending project handover timelines. Long-term viability across the analysis window hinges on exposure to data center power procurement expansion and EU ETS-driven district heating replacement cycles. The signal to watch is FERC implementation guidance on distributed energy resource compensation mechanisms in wholesale markets.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Equipment Standardization | Factory-integrated packages compress field assembly timelines for data center operators facing EPA enforcement windows. |
| Backward Integration into Castings | In-house production of precision turbine components mitigates supply vulnerability from limited European machine shops. |
| Energy-as-a-Service Contracts | Long-term operational agreements capture hospital procurement committees seeking single-source performance guarantees. |
| Biogas Fuel Flexibility Programs | Agricultural and wastewater facilities in rural Germany and the United States specify reciprocating engine packages. |
| Selective Catalytic Reduction Retrofits | EPA Clean Air Act compliance creates equipment replacement demand in Texas and California ozone non-attainment zones. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads; and secondary validation through EIA data, IEA reports, FERC filings, and project development databases. Bottom-up equipment shipment tallies triangulated against top-down energy demand projections.
Across the projection horizon, the analytical framework modeled segmentation by fuel source, generation capacity tier, project scale, and regional grid type. CAGRs derived from historical installation patterns and policy-driven replacement cycle timing. Forecast inputs incorporated natural gas price trajectory assumptions and EPA stationary source enforcement schedule uncertainty.
Forecasts assume regulatory continuity in EPA Clean Air Act implementation and EU ETS carbon pricing mechanisms; material policy shifts would require re-modeling. Revision becomes warranted when FERC Order 2222 implementation guidance crosses thresholds that materially alter distributed energy resource compensation structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
East Africa Power Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Oman Power Market
Power Generation
Gas Fired Power Plant Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Captive Power Plant Market
Power Generation
Oilfield Power Generation Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Global Power to Gas Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
South East Asia Power Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Hydrogenerators Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Canada Power EPC Market
Power Generation
Gas Gensets Market