
 Combat Management System Market | 2026-2036
Combat Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Management System Market Analysis
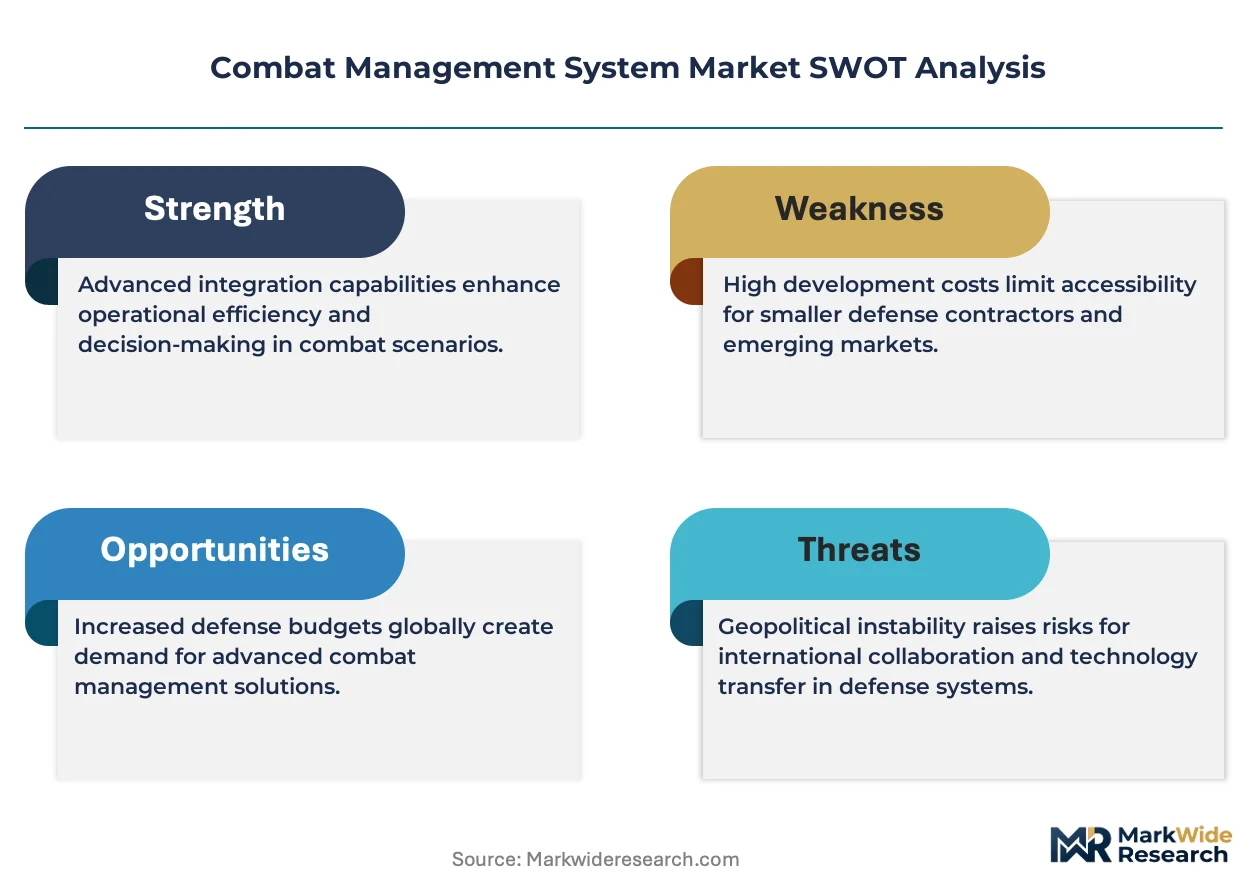
The EU Green Deal's defense sector decarbonization benchmarks is pivoting procurement criteria toward energy-efficient computing architectures in naval combat systems. BAE Systems leverages its sovereign UK supply chain to sustain integrated platform development across Royal Navy surface fleets. Thales Group anchors European collaborative programs through its Franco-Italian industrial footprint in maritime electronics. Elbit Systems competes in the upgrade segment with modular retrofit packages for legacy vessel classes.
A combat management system constitutes an integrated hardware-software suite that fuses sensor inputs, weapon systems, and communications into a unified tactical picture for naval commanders. The architecture typically processes multi-source radar, sonar, and electronic warfare data through real-time operating systems with sub-100-millisecond latency requirements for fire-control loops. Surface Combatants command the largest installed base due to fleet quantity, though Submarines generate premium margins from stealth-optimized acoustic processing and hardened radiation-tolerant electronics. Artificial Intelligence applications within the Technology dimension are expanding fastest as navies automate threat classification and predictive maintenance, while Cybersecurity investments intensify following demonstrated vulnerabilities in satellite-linked command networks.
The US Navy's NAVAIR certification requirements and the EU's MDR-aligned defense procurement standards constrain market access to vendors demonstrating traceable software development and electromagnetic compatibility compliance. NATO's STANAG interoperability protocols further mandate cross-national system integration, elevating engineering barriers for non-aligned suppliers. Stakeholders must weigh sovereign capability investments against coalition interoperability imperatives as software-defined warfare architectures evolve.
Market Dynamics
Software-defined warfare architectures are compressing procurement cycles for naval command-and-control platforms, forcing contractors to decouple hardware refresh from software capability updates. NATO interoperability mandates now require modular open-system designs that accommodate rapid threat environment adaptation.
Growth Catalysts
- US DoD Software-Defined Warfare Directives:The Pentagon's mandate for hardware-agnostic mission software accelerates open-architecture CMS procurements across carrier strike groups and littoral combat fleets.
- Indo-Pacific Maritime Disputes:Territorial tensions drive distributed fleet coordination investments from Singapore to Australia, requiring networked combat management across dispersed surface action groups.
- AI-Enabled Threat Classification:Machine learning inference at the tactical edge automates sensor correlation, reducing commander cognitive load during saturation attacks.
Market Restraints
- Radiation-Hardened Electronics Supply:Submarine-grade processors depend on a concentrated US and European foundry base with limited surge capacity for stealth-optimized acoustic arrays.
- NAVAIR Certification Timelines:US Navy airworthiness and electromagnetic compatibility validation extends development cycles to 18-24 months for new software releases.
- Legacy Vessel Integration Costs:Mechanical-gear analog systems on 1980s-era frigates require extensive cable plant replacement before digital CMS retrofit.
Strategic Opportunities
- Underpenetrated Southeast Asian Fleets:Vietnam, Indonesia, and the Philippines lack integrated combat management on patrol craft, creating upgrade pathways for modular retrofit packages.
- EU Green Deal Defense Decarbonization:Energy-efficient computing benchmarks pivot procurement toward low-power naval data centers with liquid cooling architectures.
- 5G Maritime Mesh Networks:Converging tactical data links with commercial cellular infrastructure enables shore-based fleet command during distributed operations.
Industry Challenges
- Sub-100-Millisecond Latency Engineering:Fire-control loop timing requirements demand specialized real-time operating system expertise scarce in commercial software labor pools.
- Cross-Domain Cybersecurity Certification:SATCOM-linked command networks require simultaneous compliance with NSA, NATO, and national cryptographic standards with conflicting update cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Management System Market |
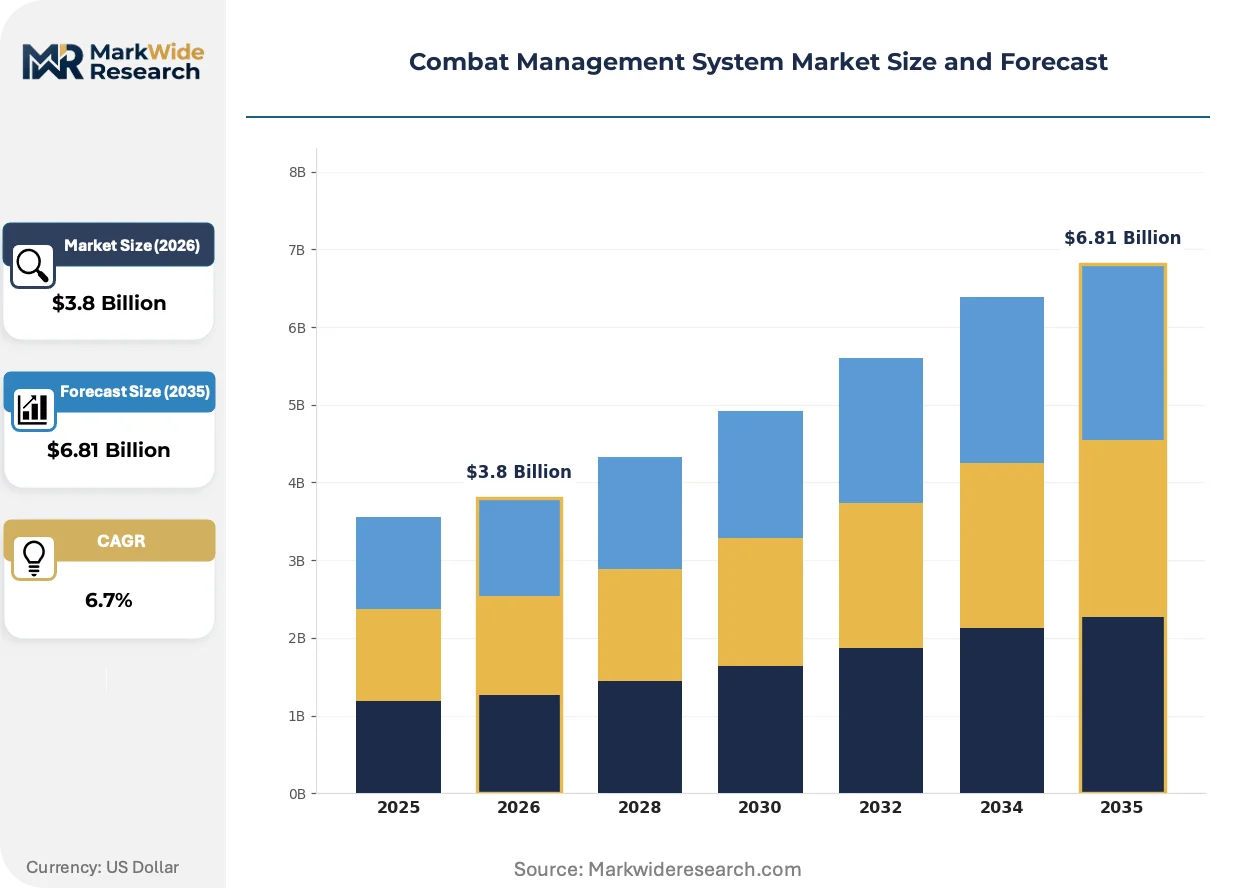
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Combatants, Submarines, Amphibious Warfare, Naval Aviation Technology: Artificial Intelligence, Cloud Computing, IoT, Cybersecurity End User: Military, Defense Contractors, Coast Guard, Naval Academies Installation: Onboard Installation, Land-Based Centers, Remote Operations, Integration Services |
| Companies Covered | Lockheed Martin Corporation, Thales Group, BAE Systems plc, Kongsberg Gruppen, Northrop Grumman Corporation, Elbit Systems Ltd, Raytheon Technologies Corporation, Saab AB, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Management System Market Emerging Trajectories
Artificial intelligence integration is restructuring how naval forces process sensor fusion, compressing decision timelines while introducing new verification burdens for autonomous threat response. Regulatory pressure on electromagnetic signatures and energy consumption is simultaneously reshaping hardware specifications.
Containerized software deployment is consolidating combat management functionality previously distributed across dedicated hardware modules. Royal Navy Type 26 frigates and US Navy DDG(X) programs adopt Kubernetes-orchestrated mission applications that migrate between processing nodes during battle damage. This architecture reduces spares inventory but concentrates vendor dependency on cloud-native security patches.
EU MDR-aligned defense procurement standards now mandate traceable software development with documented vulnerability management across the supply chain. European naval programs from the Franco-Italian European Patrol Corvette to the German F126 frigate require SBOM disclosure and third-party code audit. Prime contractors are responding by acquiring cybersecurity specialists and restricting subcontractor tiers to audited suppliers.
Buyer consolidation around sovereign capability requirements is fragmenting previously standardized procurement patterns. Australia, Japan, and South Korea now prioritize domestic integration of foreign sensor suites over turnkey foreign CMS platforms. This shift forces original equipment manufacturers to license core software stacks while ceding platform integration to national champions, compressing margin capture at the system level.
Combat Management System Market Segmentation
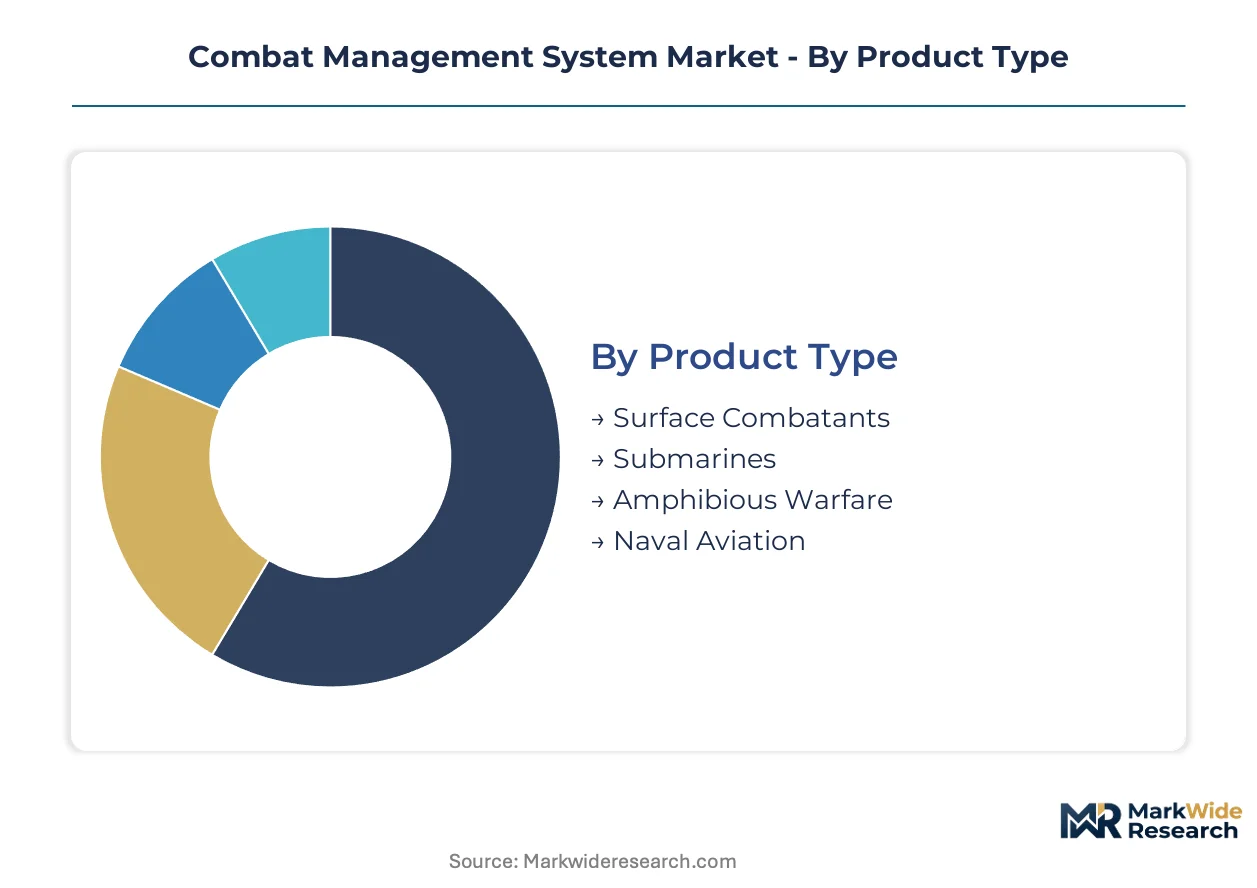
Combat management system procurement varies sharply across naval platform types, processing architectures, and operational environments. Each segmentation axis carries distinct certification requirements, latency specifications, and integration complexity that reshape vendor positioning.
Product Type:
Platform specifications dictate processing hardware, acoustic signatures, and electromagnetic hardening requirements across naval vessel categories.
- Surface Combatants:Distributed sensor fusion architectures on destroyers and frigates demand real-time correlation of radar, electro-optical, and electronic warfare feeds. The US Navy's DDG(X) program and Royal Navy Type 26 procurement concentrate demand here, though budget cycles stretch delivery timelines.
- Submarines:Stealth-optimized acoustic processing with radiation-tolerant electronics operates under extreme pressure and electromagnetic silence constraints. Premium margins attract specialized suppliers, but foundry capacity for hardened processors remains concentrated.
- Amphibious Warfare:Expeditionary platforms require modular systems supporting joint force coordination between ship and shore elements.
- Naval Aviation:Carrier-based aircraft and maritime patrol platforms integrate airborne mission computers with shipboard command networks.
Surface Combatants leads on scale; Submarines leads on momentum.
Technology:
Processing architectures range from embedded edge inference to shore-based cloud orchestration, with divergent latency tolerances and security postures.
- Artificial Intelligence:Machine learning inference at the tactical edge automates threat classification and predictive maintenance, compressing commander decision cycles during saturation attacks. NATO navies prioritize this for distributed fleet coordination in contested environments.
- Cybersecurity:Cross-domain cryptographic certification for SATCOM-linked command networks demands simultaneous compliance with NSA, NATO, and national standards with conflicting update cadences.
- Cloud Computing:Kubernetes-orchestrated mission applications enable software migration between processing nodes during battle damage.
- IoT:Sensor mesh networks expand distributed data collection across hull-mounted and towed arrays.
Artificial Intelligence commands investment priority; Cybersecurity faces the steepest compliance escalation.
End User:
Procurement authority and integration responsibility vary across sovereign navies, system integrators, and maritime security agencies with divergent budget cycles.
- Military:National naval services drive platform-level specifications through sovereign capability requirements, increasingly favoring domestic integration over turnkey foreign systems.
- Defense Contractors:Prime integrators license core software stacks while subcontracting platform-specific adaptation to national champions.
- Coast Guard:Law enforcement and search-rescue missions prioritize interoperability with civilian maritime traffic systems over combat functionality.
- Naval Academies:Training installations require lower-specification systems for crew certification without full combat hardware.
Military commands procurement volume; Defense Contractors faces margin compression from sovereign integration mandates.
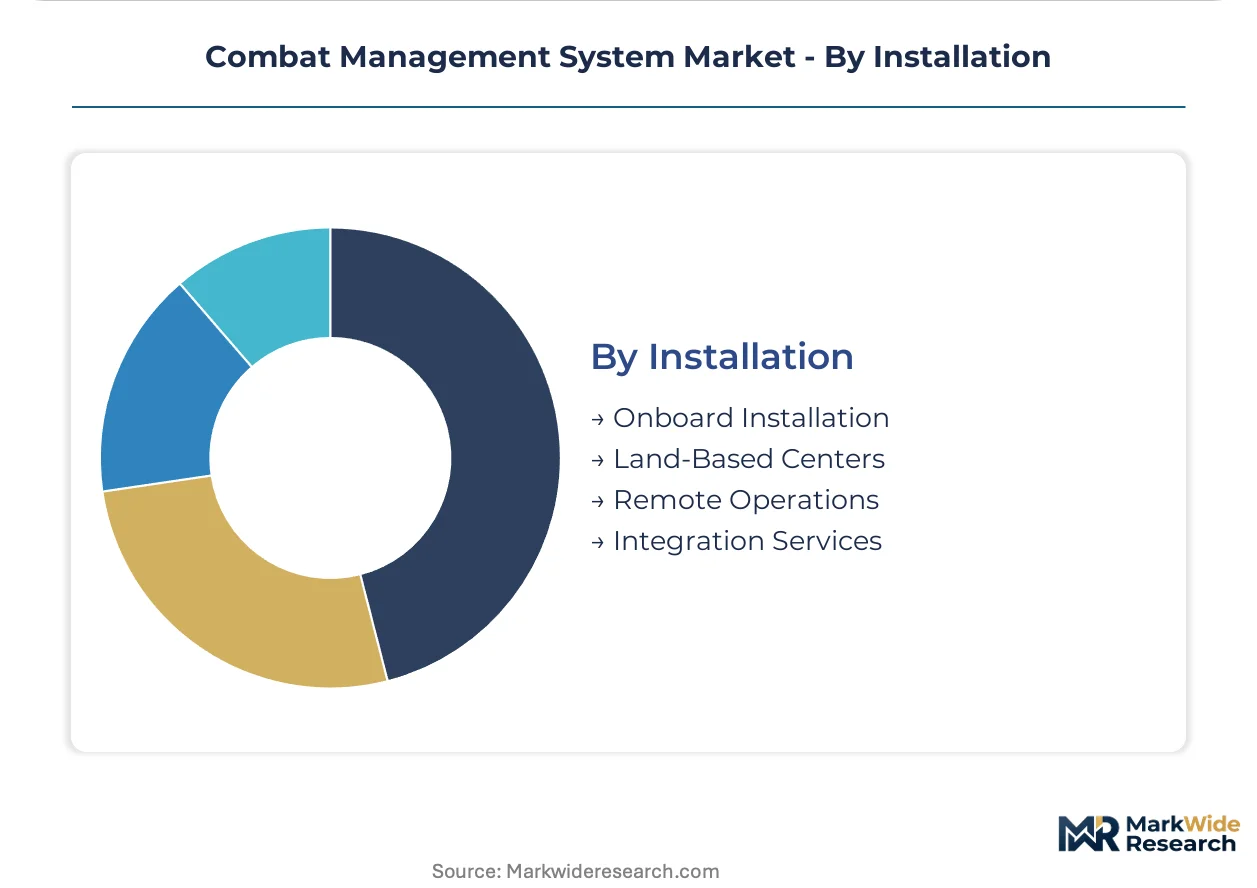
Installation:
Physical deployment mode determines cabling infrastructure, environmental hardening, and operational availability requirements.
- Onboard Installation:Hull-integrated combat management suites on new-construction vessels specify liquid-cooled naval data centers meeting EU Green Deal energy efficiency benchmarks.
- Integration Services:Legacy vessel retrofit demands extensive cable plant replacement on 1980s-era frigates with mechanical-gear analog systems, extending project timelines and cost uncertainty.
- Land-Based Centers:Shore fleet command facilities leverage commercial power and climate control for reduced hardware hardening costs.
- Remote Operations:SATCOM-dependent distributed command introduces latency and cyber vulnerability trade-offs.
Onboard Installation dominates new procurement; Integration Services expands fastest from aging fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics engineering talent concentrates in coastal metropolitan clusters across NATO member states and select Indo-Pacific allies, with submarine acoustics specialists concentrated in Scotland, Rhode Island, and South Australia.
United States
The US Navy's DDG(X) program and NAVAIR certification requirements drive demand for open-architecture combat management platforms. Pentagon software-defined warfare directives mandate hardware-agnostic mission software across carrier strike groups. Engineering clusters in Rhode Island and Virginia anchor submarine combat system development for stealth-optimized acoustic processing.
United Kingdom
Royal Navy Type 26 frigate procurement sustains integrated platform development for surface combatants. UK sovereign capability requirements favor domestic supply chain retention in naval electronics. Glasgow and Portsmouth shipyards concentrate combat management integration work for distributed fleet coordination systems.
France
The Franco-Italian European Patrol Corvette program anchors collaborative maritime electronics development under EU MDR-aligned defense procurement standards. Thales Group leverages its industrial footprint for cross-national system integration. Toulon and Brest naval bases cluster combat system validation expertise for NATO STANAG interoperability protocols.
Australia
AUKUS submarine acquisition and Hunter-class frigate programs prioritize domestic integration of foreign sensor suites over turnkey foreign platforms. Royal Australian Navy distributed fleet coordination investments respond to Indo-Pacific maritime disputes. South Australia concentrates combat system engineering talent for nuclear-powered submarine transition.
Japan
Japan Maritime Self-Defense Force destroyer modernization drives procurement of AI-enabled threat classification systems for saturation attack defense. METI industrial policy supports national champion integration of combat management components. Yokosuka and Kure naval districts cluster systems engineering for distributed surface action group coordination.
Combat Management System Market Vendor Landscape
Capital-heavy defense primes compete with specialized subsystem designers for combat management procurement, creating a tiered structure where platform integrators license core software stacks while national champions handle vessel-specific adaptation. The vendor base separates into three archetypes: full-spectrum naval electronics houses, modular retrofit specialists, and sovereign capability integrators. Prime contractors defend position through strategic partnerships with national shipyards and technology licensing arrangements that accommodate domestic integration mandates.
Among transatlantic defense conglomerates, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the platform-integrator archetype with extensive NAVAIR certification experience, while Thales Group occupies a position bridging European collaborative programs and Franco-Italian industrial coordination. BAE Systems plc anchors the sovereign capability tier through its UK supply chain integration for Royal Navy surface fleets. These three represent divergent responses to software-defined warfare procurement compression: hardware-agnostic mission software licensing, cross-national consortium participation, and domestic supply chain retention.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Thales Group |
| BAE Systems plc |
| Kongsberg Gruppen |
| Northrop Grumman Corporation |
| Elbit Systems Ltd |
| Raytheon Technologies Corporation |
| Saab AB |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Radiation-hardened processor foundry capacity constraints cascade through naval electronics supply chains into three-tier pricing structures across premium, standard, and economy certification levels. NAVAIR-certified subsystem suppliers command substantial premiums over commercial-grade alternatives as US and European foundries maintain restricted surge capacity for stealth-optimized acoustic arrays.
Pricing Analysis
Software licensing unbundled from hardware procurement now dominates prime contractor offerings, with AI-enabled threat classification modules priced separately from base combat management platforms. Price differentiation hinges on electromagnetic compatibility certification tier and sovereign supply chain content requirements. Cost compression in retrofit integration services intensifies as legacy vessel cable plant replacement absorbs margin. Coast guard and maritime security agencies exhibit highest price sensitivity; nuclear submarine programs demonstrate lowest sensitivity due to mission-critical latency specifications.
Supply Chain Analysis
Specialized real-time operating system engineering talent scarcity in Rhode Island, Scotland, and South Australia constrains production scaling for sub-100-millisecond fire-control loop components. Supply draws from concentrated US and European radiation-hardened semiconductor foundries, submarine-grade acoustic sensor manufacturers, and NATO-aligned cryptographic module suppliers. Single-source vulnerability persists in stealth-optimized processor fabrication. Distribution runs through sovereign naval procurement authorities with national security clearance requirements rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combat management system procurement functions as a geographic-arbitrage play where EU Green Deal energy efficiency benchmarks impose compliance costs absent from Indo-Pacific procurement, creating margin dispersion between regulatory jurisdictions.
For Market Incumbents: Acquire cybersecurity audit specialists to satisfy EU MDR-aligned software bill of materials disclosure mandates. License core software stacks to Australian and Japanese national champions rather than ceding platform integration entirely, preserving recurring revenue streams against sovereign capability mandates. Counter margin compression from domestic integration requirements through captive supply of radiation-hardened processor design IP. For New Entrants and Emerging Players: National shipyard partnerships in Vietnam, Indonesia, and the Philippines offer lowest barrier-to-entry pathways for modular retrofit packages on under-integrated patrol craft. Target Southeast Asian coast guard modernization programs with cybersecurity-light configurations before pursuing NATO STANAG certification. Lead with shore-based fleet command center integration rather than vessel-hull combat management to bypass NAVAIR timeline constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with sovereign capability integrators possessing cleared engineering workforces in AUKUS member states. Five-to-ten year viability hinges on nuclear-powered submarine transition program execution and distributed fleet coordination procurement acceleration. Monitor Royal Australian Navy domestic integration contract awards as inflection indicator for licensed-software model adoption across Indo-Pacific allies.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Cybersecurity Audit Specialist | EU MDR-aligned SBOM disclosure mandates require third-party code verification capabilities. |
| Software Stack Licensing to National Champions | Australian and Japanese domestic integration policies compress system-level margin capture. |
| Modular Retrofit Package Development | Southeast Asian patrol craft fleets lack integrated command-and-control platforms. |
| Radiation-Hardened Processor IP Captive Supply | US and European foundry concentration creates single-source vulnerability for submarine programs. |
| Shore-Based Fleet Command Center Integration | 5G maritime mesh networks enable distributed operations without vessel-hull certification delays. |
Methodological Framework
Direct dialogue with naval program executives, combat system engineering directors, defense procurement officers, and submarine acoustics specialists grounded qualitative assessment. Secondary validation drew from US Department of Defense budget justification materials, NATO STANAG protocol documentation, EU defense procurement directive filings, and naval shipyard production schedules. Bottom-up platform-level demand estimates triangulated against top-down national defense expenditure projections across the analysis window.
Segmentation outputs across platform type, processing architecture, and operational environment informed volume and value projections throughout the forecast period. CAGRs derived from procurement pipeline analysis, fleet modernization cycle timing, and software-defined warfare directive implementation velocity. Industry-specific inputs included NAVAIR certification queue depth, radiation-hardened foundry capacity utilization, and sovereign capability policy divergence between AUKUS and European defense autonomy initiatives.
Revisions become necessary when NATO interoperability mandate scope changes, submarine-grade processor foundry capacity expands, or Indo-Pacific maritime dispute intensity shifts materially. Forecasts reflect documented assumptions regarding procurement cycle compression and open-architecture adoption rates. Material deviation in defense budget authorization trajectories or electromagnetic compatibility certification timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Marine Penetrators Market