
 Marine Penetrators Market | 2026-2036
Marine Penetrators Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Penetrators Market Analytics
Norway's subsea manufacturing corridor is reshaping supply dynamics for high-pressure marine penetrators. TE Connectivity leverages its deep-water connector heritage to anchor European demand for titanium-hulled systems. Amphenol Corporation competes through specialized robotics interfaces that sustain repeat procurement from research fleets. Hydro Group dominates UK and Nordic defense contracts with pressure-rated assemblies that control NATO-standard qualification pathways.
Marine penetrators are pressure-balanced electrical or optical feedthrough devices, typically rated for depths exceeding 6,000 meters, that seal against seawater ingress while transmitting power or data across hull boundaries. Their primary purpose is to maintain integrity of manned vessels, remotely operated vehicles, and seabed sensor nodes under hydrostatic loads that would collapse conventional sealing architectures. Stainless steel penetrators lead military procurement cycles where corrosion resistance must meet decades-long service intervals, while titanium variants capture fastest growth in autonomous underwater vehicle programs where weight reduction directly extends operational endurance. Modular designs are concentrating margin pools in the commercial segment, as oilfield service companies demand field-reconfigurable interfaces that reduce vessel downtime between survey missions.
DNV standards govern pressure testing protocols for North Sea equipment, while the EU Marine Strategy Framework Directive imposes environmental impact assessments that shape material selection and disposal pathways for seabed installations. The US Navy's MIL-STD-810 and MIL-STD-202 qualification requirements filter market access for defense suppliers, forcing dual-use manufacturers to maintain parallel certification tracks. Stakeholders must monitor how tightening seabed mining regulations in the Pacific and Atlantic treaty zones redirect R&D spending toward biofouling-resistant coatings and extended-life sealing elastomers.
Market Dynamics
Subsea field electrification is compressing procurement cycles as offshore operators replace hydraulic umbilicals with all-electric architectures, forcing penetrator suppliers to requalify products for higher voltage densities and integrated fiber-optic telemetry.
Growth Catalysts
- EU Marine Strategy Framework Directive:Mandatory environmental impact assessments for seabed installations are accelerating replacement of legacy elastomer seals with biofouling-resistant fluoropolymer compounds in North Sea deployments.
- Autonomous underwater vehicle programs:Defense research agencies in Norway, the UK, and France are procuring titanium-hulled penetrators to extend operational endurance through weight reduction in deep-water survey missions.
- Subsea processing:Oilfield service companies operating Norway's Johan Sverdrup and Equinor's Troll West fields are demanding field-reconfigurable modular interfaces that compress vessel downtime between intervention campaigns.
Market Restraints
- Titanium sponge volatility:Feedstock price swings for aerospace-grade titanium constrain margin stability for hull manufacturers serving AUV programs.
- DNV certification concentration:Pressure testing protocol dependence on single-source Norwegian accreditation creates bottleneck risk for new market entrants.
- Hydraulic-to-electric substitution:All-electric subsea actuation architectures threaten demand for traditional power-only penetrator configurations in greenfield developments.
Strategic Opportunities
- Seabed mining treaty zones:Pacific and Atlantic regulatory frameworks under ISA jurisdiction are creating first-mover demand for extended-life sealing elastomers in polymetallic nodule extraction equipment.
- Dual-use defense-commercial crossover:MIL-STD-810 qualified suppliers are repurifying pressure-rated assemblies for oceanographic research fleets seeking NATO-standard reliability without military procurement overhead.
- Optical-electrical convergence:Hybrid fiber-copper penetrator designs are capturing specification wins in cabled observatory networks where power and data transmission must share single hull penetrations.
Industry Challenges
- Multi-standard qualification burden:Suppliers maintaining parallel DNV, MIL-STD-202, and IEC 60529 certification tracks face compressed R&D allocation for next-generation product development.
- Legacy system integration friction:Field-reconfigurable modular designs encounter interoperability failures when mated to 1990s-era subsea distribution units with non-standard connector geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Penetrators Market |
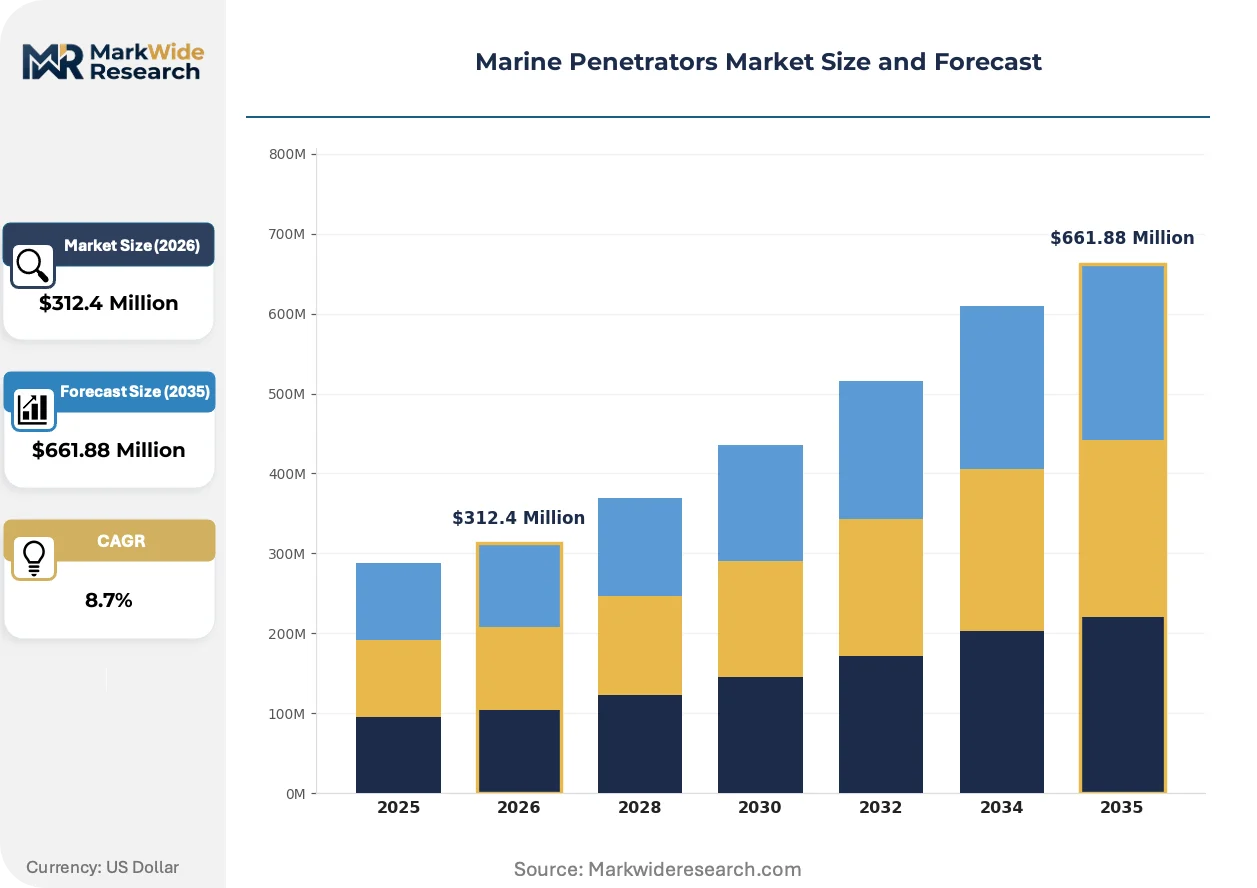
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Multi-Use, Modular, Customizable Material: Stainless Steel, Titanium, Composite, Plastic Application: Underwater Sensors, Robotics, Marine Research, Surveillance End User: Military, Research Institutions, Commercial Companies, Environmental Agencies |
| Companies Covered | TE Connectivity, Amphenol Corporation, Eaton Corporation, Teledyne Marine, Hydro Group, Fischer Connectors, Molex, SEACON, Glenair Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Penetrators Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape penetrator architectures, with hybrid optical-electrical systems and biofouling-resistant coatings displacing legacy single-function designs across defense and commercial fleets.
Fluoropolymer composite sealing technology is hybridizing traditional elastomer architectures with ceramic-reinforced matrices that withstand hydrothermal vent chemistry. Deep-sea research institutions operating ROV fleets in the Mid-Atlantic Ridge are specifying these compounds for repeat-deployment reliability. The technology is hybridizing procurement specifications across NATO-aligned navies and commercial survey operators, compressing qualification timelines for conventional nitrile rubber suppliers.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of anti-corrosion surface treatments for stainless steel hull penetrators. German and French defense procurement agencies now mandate chrome-free coating systems that maintain salt-spray resistance exceeding 5,000 hours. Military specification writers are responding by embedding environmental compliance clauses into multi-year framework agreements, shifting supplier selection criteria toward materials traceability documentation.
Integrated sensor-telemetry penetrators are capturing specification share as offshore operators unbundle data acquisition from separate instrumentation pods. Subsea field architects in Norway's North Sea cluster are specifying penetrators with embedded pressure-temperature-vibration sensing to reduce hull penetration count. This specification pattern is most visible in Equinor's capital projects, where single-penetration multifunction designs are compressing installation contractor man-hour estimates by fifteen to twenty percent on subsea template installations.
Marine Penetrators Market Segmentation
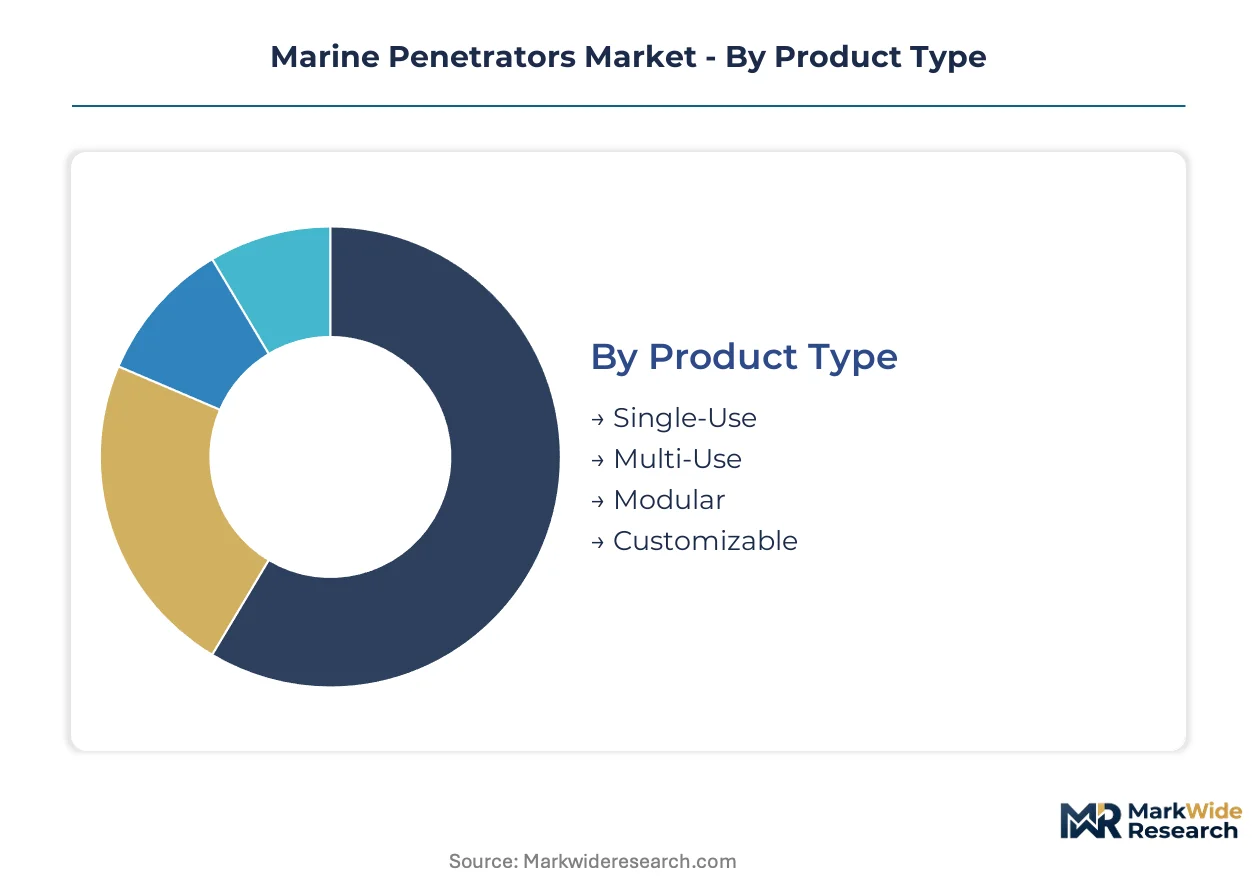
Marine penetrator procurement patterns diverge sharply across product architectures and end-use missions. Material selection and reconfiguration requirements drive distinct after-sales service intensities that reshape supplier margin structures.
Product Type:
After-sales service intensity concentrates heavily in field-reconfigurable architectures, where maintenance contracts and technical support obligations extend across multi-year deployment cycles.
- Modular:Field-reconfigurable interfaces with swappable connector modules enable rapid reconfiguration between survey missions. Oilfield service companies operating Norway's subsea fields specify these designs to compress vessel downtime between intervention campaigns.
- Customizable:Mission-specific penetrators engineered to unique hull geometries and pressure ratings demand intensive application engineering support. Defense research agencies in France and the UK procure these for specialized AUV programs where standard catalog products fail.
- Single-Use:Disposable penetrators for one-time deployment scenarios minimize service obligations.
- Multi-Use:Repeat-deployment designs for ROV fleets balance durability against refurbishment costs.
By volume, Single-Use leads in commercial survey fleets. By growth pace, Modular is gaining share fastest as subsea electrification accelerates.
Material:
Cost tier stratification separates aerospace-grade titanium hulls from standard stainless steel, with composite intermediates capturing specification wins where weight reduction meets budget constraints.
- Titanium:Aerospace-grade sponge construction delivers strength-to-weight ratios critical for extended AUV endurance. Norwegian and UK defense research agencies specify titanium-hulled penetrators for deep-water survey missions where every kilogram of payload capacity matters.
- Stainless Steel:Austenitic and duplex grades dominate military procurement cycles where corrosion resistance must sustain decades-long service intervals without hull replacement.
- Composite:Ceramic-reinforced polymer matrices bridge performance gaps in mid-depth research applications.
- Plastic:Polymer-housed penetrators serve shallow-water sensor networks with limited pressure exposure.
Titanium commands premium positioning in defense budgets. Stainless steel retains the largest installed base across NATO-aligned fleets.
Application:
Customer type concentration varies by mission criticality, with robotics and surveillance applications demanding highest reliability tiers and corresponding technical support commitments.
- Robotics:ROV and AUV interface penetrators must sustain repeated mating cycles under dynamic load conditions. Research fleets operating Mid-Atlantic Ridge hydrothermal vents specify fluoropolymer-sealed variants for repeat-deployment reliability in corrosive chemistry.
- Marine Research:Cabled observatory networks drive hybrid fiber-copper specifications where power and data transmission share single hull penetrations.
- Underwater Sensors:Pressure-temperature-vibration sensing penetrators reduce hull penetration count in subsea template installations.
- Surveillance:Covert deployment platforms require signature-minimized sealing architectures.
Robotics generates highest unit volumes. Marine Research shows steepest expansion trajectory as oceanographic infrastructure investment accelerates.
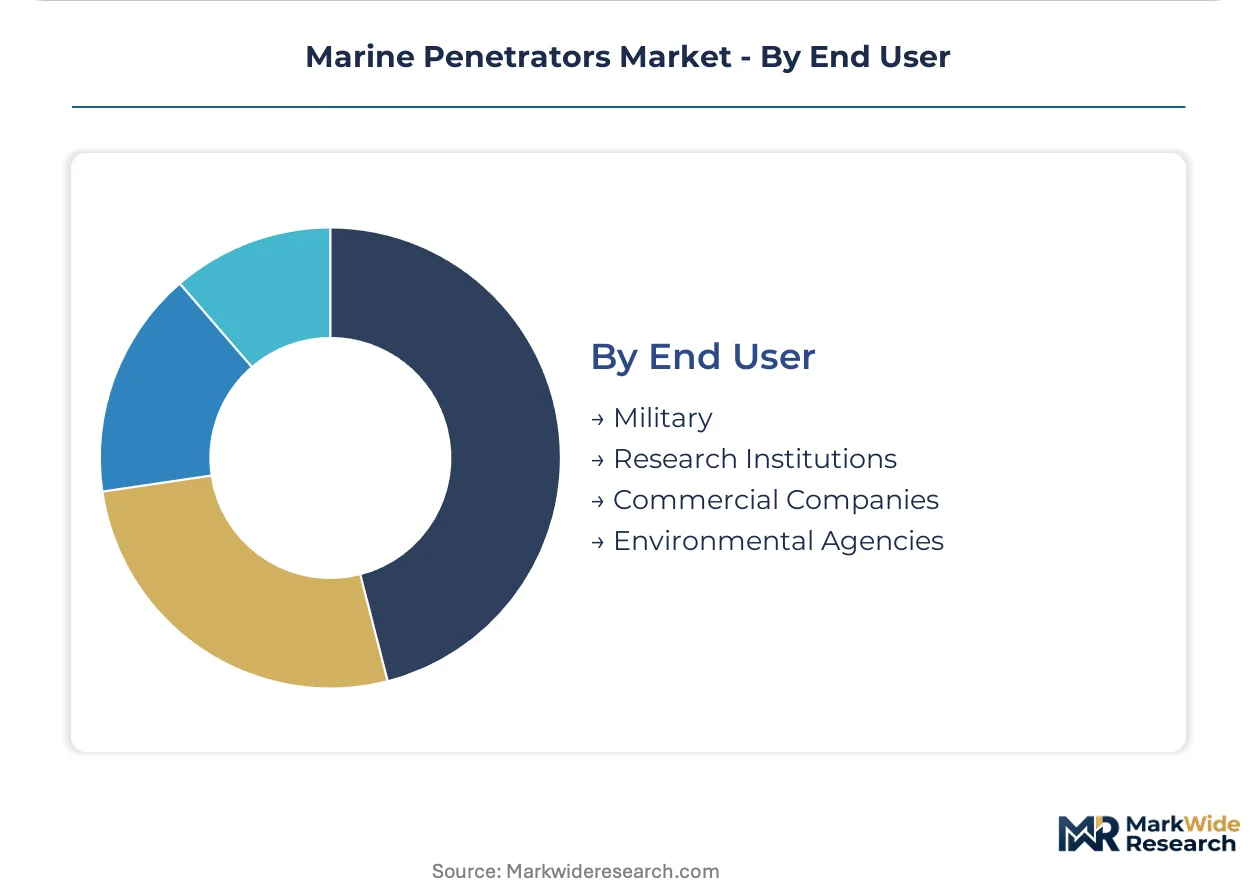
End User:
Supply concentration clusters around defense qualification pathways, where MIL-STD-810 and DNV certification tracks filter accessible supplier pools.
- Military:NATO-standard qualification requirements enforce parallel certification maintenance that elevates supplier switching costs. Hydro Group and TE Connectivity anchor European defense procurement through pressure-rated assemblies controlling accreditation pathways.
- Commercial Companies:Oilfield service operators prioritize field-reconfigurable designs that minimize vessel downtime between subsea intervention campaigns.
- Research Institutions:Deep-sea research programs specify fluoropolymer composite sealing for repeat-deployment reliability in extreme chemistry environments.
- Environmental Agencies:EU Marine Strategy Framework Directive compliance mandates biofouling-resistant materials and traceable disposal pathways.
Military procurement anchors premium-tier demand. Commercial Companies are expanding most quickly as subsea field electrification replaces hydraulic architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DNV standards anchor Norwegian regulatory frameworks for subsea pressure equipment, while the EU Marine Strategy Framework Directive shapes environmental compliance across North Sea deployments. Procurement clusters concentrate in specific national corridors where defense research and offshore oilfield development intersect.
Norway
Equinor's Johan Sverdrup and Troll West field developments drive penetrator procurement for subsea electrification programs. The Norwegian Maritime Authority enforces DNV-ST-F101 standards for pressure-containing equipment in offshore installations. Stavanger's subsea manufacturing corridor hosts concentrated supplier engineering facilities serving North Sea infrastructure.
United Kingdom
Defense research agencies in the UK procure titanium-hulled penetrators for autonomous underwater vehicle endurance extension. The Maritime and Coastguard Agency implements EU-derived environmental impact assessment protocols for seabed equipment. Aberdeen's oilfield services cluster demands field-reconfigurable modular interfaces to compress vessel downtime.
France
Naval Group and oceanographic research institutions specify fluoropolymer-sealed penetrators for repeat-deployment reliability. ANSM and CNIL oversight extends to environmental compliance documentation for defense procurement. Brest's maritime technology hub concentrates AUV program development and pressure-rated assembly qualification.
Germany
REACH Annex XVII restrictions on perfluorinated compounds force reformulation of anti-corrosion surface treatments for stainless steel penetrators. The Federal Maritime and Hydrographic Agency enforces environmental compliance for seabed installations in German waters. Hamburg's marine engineering cluster hosts qualification laboratories for NATO-standard pressure testing.
United States
The US Navy's MIL-STD-810 and MIL-STD-202 requirements filter market access for defense suppliers. NOAA's oceanographic research fleet specifications drive hybrid fiber-copper penetrator demand for cabled observatory networks. Houston's subsea engineering corridor anchors commercial procurement for Gulf of Mexico field developments.
Marine Penetrators Market Competitive Landscape
Capability concentration sits with defense-qualified specialists; scale advantage sits with diversified connector manufacturers. The vendor base separates into three tiers: NATO-accredited defense suppliers maintaining parallel certification tracks, commercial oilfield service providers optimizing for vessel downtime reduction, and research-oriented specialists serving institutional fleets. Consolidation pressure operates through dual-use crossover opportunities and subsea electrification qualification demands.
Within the defense-qualified tier, TE Connectivity and Hydro Group exemplify divergent geographic anchoring strategies. TE Connectivity occupies a position leveraging deep-water connector heritage across European demand clusters. Hydro Group represents UK and Nordic defense contract concentration through pressure-rated assembly qualification pathways. Amphenol Corporation sits within the diversified manufacturer archetype, competing through specialized interface capabilities that sustain institutional procurement relationships.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Eaton Corporation |
| Teledyne Marine |
| Hydro Group |
| Fischer Connectors |
| Molex |
| SEACON |
| Glenair Inc. |
| Others |
Value Network & Pricing Analysis
Aerospace-grade titanium sponge production concentrates in Chinese and Russian smelters, anchoring margin pools in hull fabrication tiers where defense contractors pass through feedstock volatility via indexed long-term supply agreements.
Pricing Analysis
Geographic price spreads of 15-25% separate Norwegian North Sea procurement from Asia-Pacific research fleet orders, reflecting DNV certification overhead and expedited delivery premiums. Three-tier pricing structure across MIL-STD qualified, commercial oilfield, and institutional research tiers differentiates on testing documentation depth and after-sales bundling. Cost compression in commercial stainless steel segments is intensifying because oilfield service companies consolidate supplier panels. Research institutions exhibit highest price sensitivity; defense agencies show lowest due to mission-critical reliability mandates.
Supply Chain Analysis
Extended payment terms of 90-120 days from major oilfield service companies strain working capital for specialized penetrator manufacturers, forcing supply-chain finance facility adoption among tier-2 suppliers. Hull fabrication draws from Norway, the United Kingdom, and the United States; sealing elastomer compounding rests on German and Japanese specialty chemical producers. Single-source vulnerability concentrates in DNV pressure-testing accreditation, where Norwegian laboratory capacity constrains new product qualification throughput. Distribution runs through subsea engineering integrators in Stavanger, Aberdeen, and Houston who bundle penetrators within umbilical and template installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine penetrators sit in early-cycle expansion as subsea field electrification displaces hydraulic architectures, with autonomous underwater vehicle procurement acceleration providing additional penetration runway.
For Market Incumbents: Insulate qualification moats by accelerating parallel DNV and MIL-STD certification maintenance to elevate switching costs for defense procurement officers. Deepen backward integration into titanium sponge sourcing through long-term offtake with aerospace-grade suppliers, hedging against Russian supply disruption. Prioritize field-reconfigurable modular platform R&D to capture oilfield service consolidation toward single-source penetrator vendors. For New Entrants and Emerging Players: Establish a beachhead in institutional research fleet procurement where NATO-standard reliability requirements are loosened and fluoropolymer composite sealing expertise differentiates against legacy nitrile rubber suppliers. Target Pacific seabed mining equipment manufacturers seeking extended-life elastomer qualifications ahead of ISA regulatory finalization. Lead with integrated sensor-telemetry penetrator designs that reduce hull penetration count for oceanographic observatory networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed oilfield service component suppliers holding DNV accreditation but lacking defense qualification pathways. Five-to-ten year viability hinges on dual-use crossover execution where commercial subsea electrification demand funds military certification maintenance. Watch titanium sponge price volatility as inflection indicator—sustained elevation accelerates composite hull substitution and reshapes acquisition target valuation metrics.| Strategic Initiative | Industry Significance |
|---|---|
| DNV-ST-F101 Certification Investment | Unlocks Equinor and Johan Sverdrup field procurement eligibility for Norwegian subsea contractors. |
| Fluoropolymer Composite Sealing Development | Captures Mid-Atlantic Ridge ROV fleet replacement cycles as REACH Annex XVII tightens. |
| Backward Integration into Titanium Sponge | Secures aerospace-grade feedstock allocation for UK and Norwegian defense AUV programs. |
| Hybrid Fiber-Copper Penetrator Launch | Addresses NOAA cabled observatory specifications with single-hull power-data convergence. |
| Seabed Mining Equipment Partnership | Positions for ISA-licensed polymetallic nodule extraction equipment qualification in Pacific zones. |
Research Methodology
Initial hypotheses were tested against primary input from subsea engineering directors, defense procurement officers, oilfield service supply chain managers, and oceanographic research fleet maintenance heads and refined through secondary validation across DNV technical standards, SEC 10-K filings from listed connector manufacturers, EU Marine Strategy Framework Directive implementation reports, and Norwegian Petroleum Directorate field development databases. Bottom-up penetrator shipment estimates by hull material and application were triangulated against top-down subsea capital expenditure projections across the analysis window.
Demand-supply balance modeling anchored volume forecasts, with segmentation across product architecture, material grade, application mission, and end-user procurement channel informing price trajectory assumptions. CAGRs were derived from installed base replacement cycles, electrification-driven new field specifications, and AUV program expansion timelines. Titanium sponge price elasticity, DNV certification queue lengths, and seabed mining regulatory progression served as scenario-weighting inputs throughout the modeling period.
Sensitivities concentrate around titanium feedstock disruption, DNV laboratory capacity constraints, and ISA seabed mining treaty ratification delays. Forecasts reflect assumptions regarding subsea electrification adoption velocity and defense research budget continuity. Macroeconomic contraction affecting offshore oilfield development, regulatory deviation in EU environmental compliance stringency, or breakthrough composite hull material commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Marine Radar Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Submarine Combat System Market