
 Digital Shipbuilding Market | 2026-2036
Digital Shipbuilding Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Shipbuilding Market Insights
Naval defense procurement is pivoting toward integrated digital twin environments, displacing legacy CAD-centric workflows in Western European and Asia-Pacific yards. Siemens leverages its industrial software stack to dominate marine-specific simulation and lifecycle management. Dassault Systèmes sustains competitive positioning through deep R&D intensity in 3D experience platforms tailored to complex hull design. Hexagon AB anchors geographic presence in Nordic defense shipbuilding through precision measurement and autonomous construction solutions.
Digital shipbuilding encompasses the application of computer-aided design, simulation, and data analytics to vessel conception, production, and lifecycle management, typically integrating hull structural modeling with propulsion system optimization and supply chain orchestration. Its primary purpose is compressing build cycles while improving fuel efficiency and regulatory compliance before steel cutting begins. Simulation Software leads product-type revenue as yards virtualize sea trials and stress testing, while AI Solutions within the technology dimension represents the fastest-expanding segment as classification societies begin mandating predictive maintenance capabilities. Design Optimization captures disproportionate margin pools among application categories because early-stage engineering decisions lock in seventy percent of lifetime vessel costs.
The International Maritime Organization enforces carbon intensity and energy efficiency standards that compel yards to validate hull designs through computational fluid dynamics before regulatory submission. Classification societies including Lloyd's Register and DNV apply digital-ready notations that gate market access for shipyards lacking certified simulation pipelines. Stakeholders must monitor whether EU Green Deal extensions or emerging national cybersecurity frameworks for maritime systems reshape software procurement criteria and vendor qualification thresholds.
Market Dynamics
The Digital Shipbuilding Market pivots on regulatory compression of design validation timelines, as the International Maritime Organization's carbon intensity indicators and EU Green Deal emissions mandates force yards to front-load simulation work before steel procurement.
Growth Catalysts
- EU Green Deal Compliance Mandates:The EU Green Deal's emissions monitoring requirements compel European yards to deploy AI-powered hull optimization tools, creating immediate procurement pull for simulation software vendors.
- Naval Fleet Modernization:South Korean shipyards accelerate digital twin platform adoption to meet defense procurement specifications for next-generation surface combatants and submarine programs.
- Computational Fluid Dynamics Virtualization:Classification societies now accept CFD-based sea trial validation, compressing physical testing schedules and expanding software licensing volumes at design houses.
Market Restraints
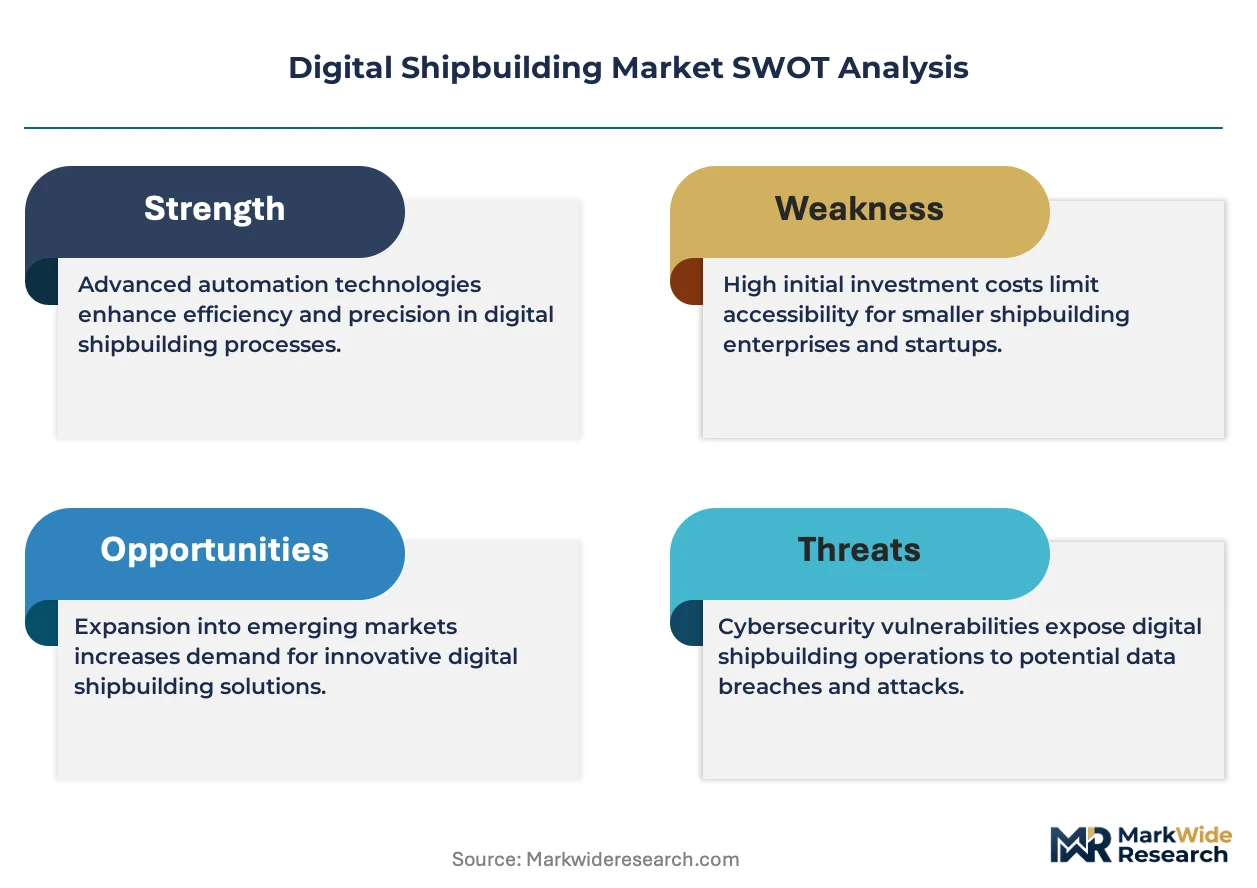
- Semiconductor Supply Concentration:GPU and high-performance computing chip availability remains constrained by Taiwan-based foundry capacity, limiting real-time simulation deployment at mid-tier yards.
- Legacy System Integration Friction:Existing CAD-CAM installations from the 2010s require costly middleware development to interface with modern digital twin architectures.
- Specialized Talent Scarcity:Marine simulation engineers with combined naval architecture and software development skills command premium compensation, inflating implementation costs.
Strategic Opportunities
- Indian Shipyard Digitization:India's Production-Linked Incentive scheme for maritime manufacturing creates untapped demand for design optimization platforms at yards in Goa and Visakhapatnam.
- Predictive Maintenance Mandates:Lloyd's Register and DNV digital-ready notations are expanding to require AI-based machinery monitoring, opening new software categories for classification society certification.
- Cloud-Native Simulation Convergence:The pairing of browser-based collaborative design environments with elastic compute resources enables smaller design consultancies to compete for complex hull projects.
Industry Challenges
- Interoperability Standardization Delays:Absence of unified data exchange protocols between hull structural, propulsion, and outfitting simulation modules forces costly custom integration at each yard.
- Cybersecurity Certification Complexity:Emerging national frameworks for maritime operational technology security impose overlapping compliance burdens on software vendors serving multiple flag states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Shipbuilding Market |
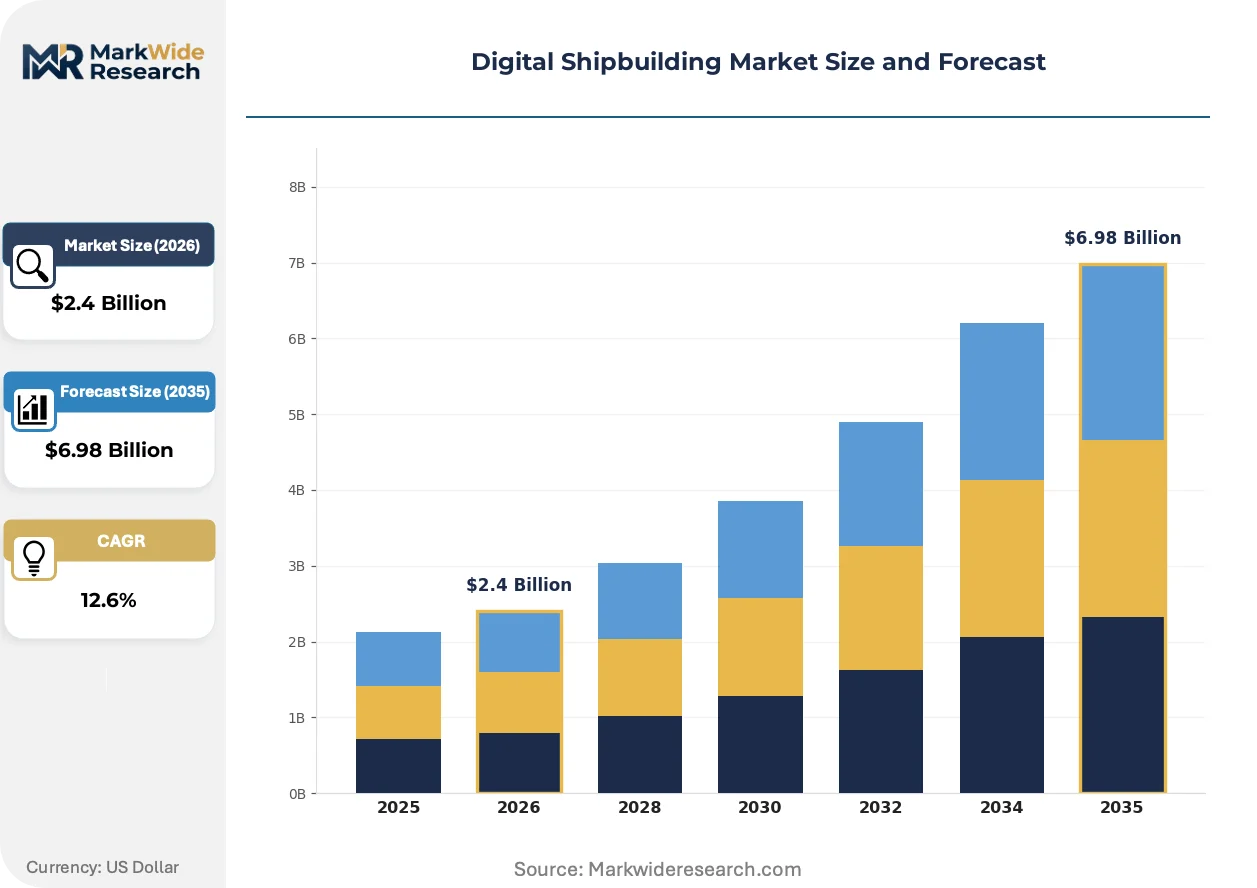
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
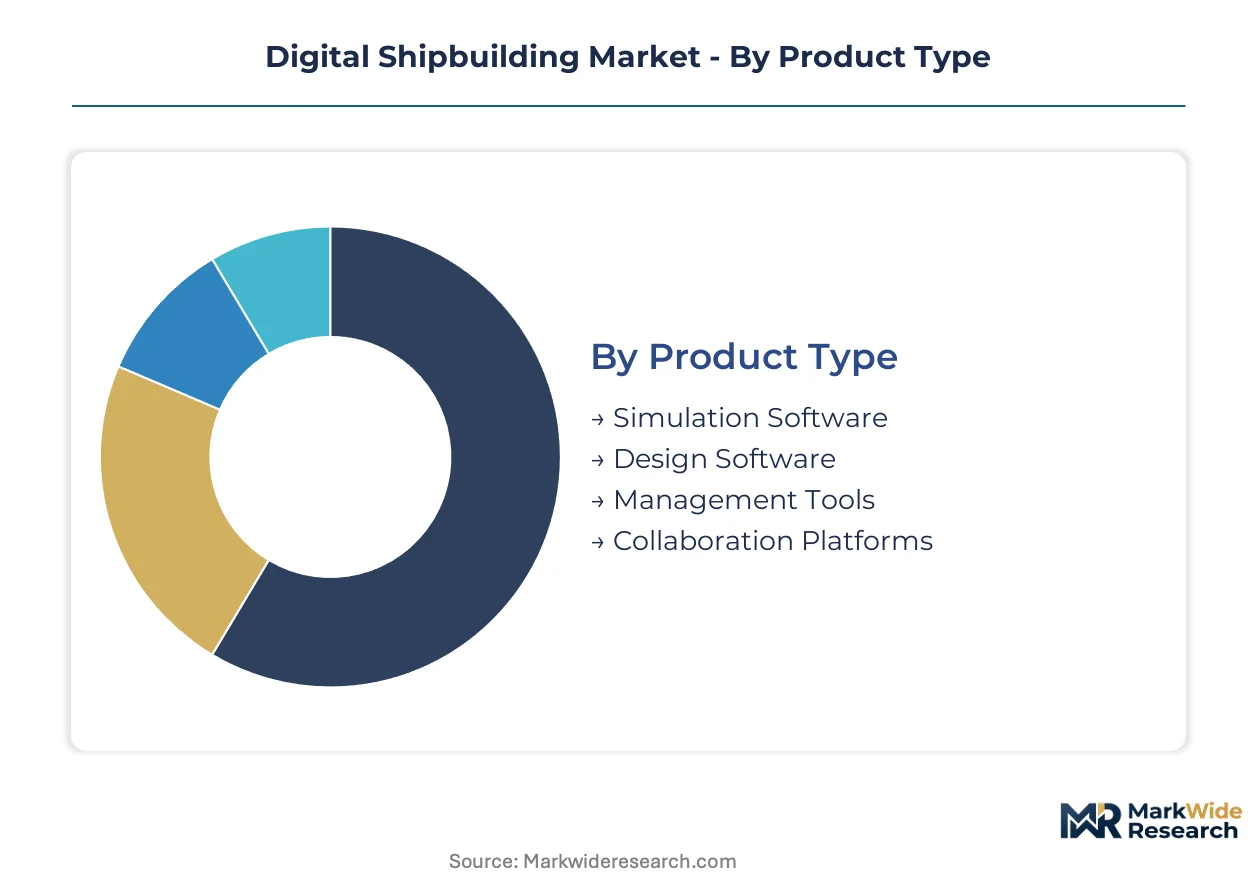
| Segmentation | Product Type: Simulation Software, Design Software, Management Tools, Collaboration Platforms End User: Shipyards, Naval Architects, Fleet Operators, Engineering Firms Technology: AI Solutions, IoT Devices, Cloud Computing, Virtual Reality Application: Design Optimization, Project Management, Quality Assurance, Maintenance Planning |
| Companies Covered | Siemens, Dassault Systèmes, Hexagon AB, AVEVA Group, BAE Systems, Wärtsilä, Altair Engineering, Accenture, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Shipbuilding Market Trends and Innovations
Digital twin architectures are consolidating previously siloed engineering disciplines, compressing the handoff friction between conceptual design, production engineering, and lifecycle service.
Real-time physics simulation is consolidating discrete event modeling, finite element analysis, and computational fluid dynamics into unified vessel digital twins. Naval architects at South Korean and Japanese yards now iterate hull forms in hours rather than weeks. This consolidation is collapsing the traditional sequential gate between preliminary design and detailed production engineering.
The EU AI Act's risk classification framework now captures autonomous navigation and predictive maintenance algorithms deployed on commercial vessels. Marine software vendors must document training data provenance and model drift monitoring for high-risk AI systems. Classification societies in Hamburg and Oslo are developing audit protocols to verify compliance before issuing digital-ready notations.
Shipowners now bundle design software procurement with lifecycle service contracts, unbundling perpetual licenses in favor of subscription access tied to vessel operational data streams. This reconfiguration concentrates purchasing authority at fleet technical departments rather than newbuild project teams. The shift is most pronounced among container lines and LNG operators with centralized procurement functions in Singapore and Copenhagen.
Digital Shipbuilding Market Segmentation
Segmentation in digital shipbuilding reveals how procurement authority is fragmenting across engineering disciplines and operational roles. Vendors must configure licensing models around distinct user workflows rather than one-size-fits-all platform sales.
Product Type:
Technical sophistication determines pricing tiers and implementation complexity across software categories.
- Simulation Software:Platforms integrating computational fluid dynamics, finite element analysis, and discrete event modeling for virtual sea trials and stress validation. South Korean naval yards in Busan and Geoje drive procurement volume for integrated hull-propulsion simulation suites under defense modernization programs.
- Design Software:Computer-aided design and manufacturing tools for hull structural modeling, outfitting layout, and production engineering. Engineering consultancies in Hamburg and Copenhagen concentrate demand for parametric hull form optimization to meet EU Green Deal emissions verification requirements.
- Management Tools:Enterprise resource planning and project control systems for yard scheduling, material tracking, and cost control.
- Collaboration Platforms:Browser-based environments enabling real-time design review and stakeholder coordination across distributed teams.
Simulation Software leads on scale; AI Solutions within the technology dimension leads on momentum.
End User:
Procurement authority varies sharply by organizational type and project phase involvement.
- Shipyards:Full-stack digital twin deployments spanning design through production engineering. Hyundai Heavy Industries and DSME in South Korea anchor capital expenditure for integrated platform installations serving both commercial and naval contracts.
- Naval Architects:Specialized simulation licensing for hull form development and regulatory compliance documentation. Independent design houses in Oslo and Glasgow concentrate demand for classification society-certified validation tools.
- Fleet Operators:Lifecycle management and predictive maintenance platform subscriptions tied to vessel operational data streams.
- Engineering Firms:Project-based software access for subcontracted detail design and production engineering support.
Shipyards command the largest contract values; Fleet Operators are expanding most quickly through subscription-based lifecycle models.
Technology:
Architecture choices determine integration depth and regulatory compliance pathways.
- AI Solutions:Machine learning systems for predictive maintenance, design optimization, and autonomous navigation algorithm development. Classification societies including Lloyd's Register and DNV are mandating AI-based machinery monitoring for digital-ready notations, accelerating procurement across European and Asian flag fleets.
- IoT Devices:Sensor networks for real-time hull stress, machinery condition, and environmental performance monitoring.
- Cloud Computing:Elastic compute resources enabling smaller design consultancies to access high-fidelity simulation without capital infrastructure investment.
- Virtual Reality:Immersive environments for design review, outfitting verification, and crew training simulation.
Cloud Computing enables broadest access; AI Solutions face the steepest regulatory compliance requirements.
Application:
Value capture concentrates in phases with greatest lifetime cost lock-in.
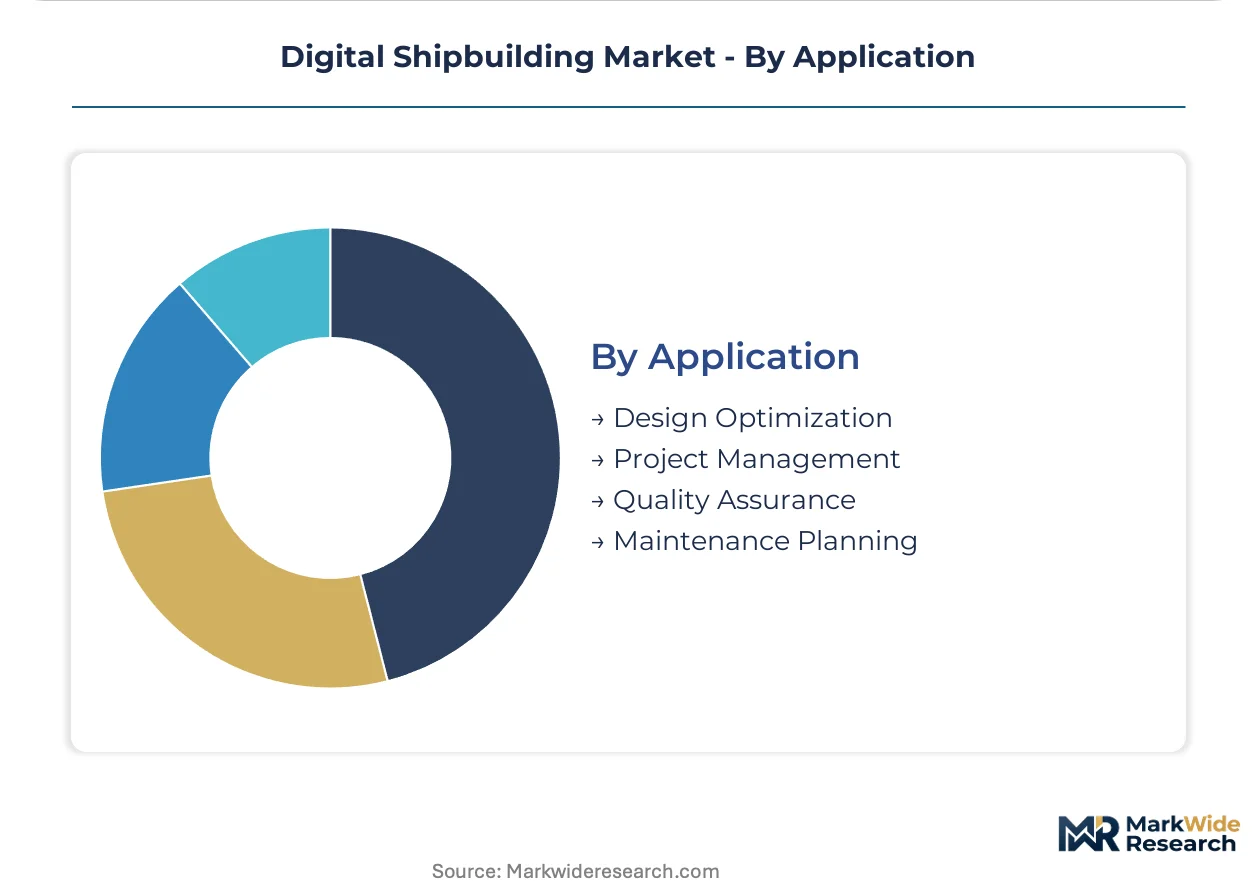
- Design Optimization:Early-stage engineering tools determining hull efficiency, structural integrity, and production cost before steel procurement. Early-stage decisions lock in seventy percent of lifetime vessel costs, concentrating margin capture at this phase across yards in Shanghai and Ulsan.
- Project Management:Scheduling, resource allocation, and milestone tracking systems for build program control.
- Quality Assurance:Inspection planning, non-conformance tracking, and certification documentation workflows.
- Maintenance Planning:Predictive algorithms and lifecycle service scheduling for operational fleet support.
Design Optimization captures the highest margins; Maintenance Planning is gaining share fastest through fleet operator subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where shipyards invest in digital infrastructure, as compliance cost gaps between jurisdictions drive platform procurement decisions toward jurisdictions with government-backed smart manufacturing incentives.
South Korea
Naval fleet modernization and defense procurement specifications are accelerating digital twin platform adoption at yards in Busan and Geoje. The country's Ministry of Trade, Industry and Energy channels funding through smart ship initiatives that mandate simulation software integration for newbuild contracts. DSME and Hyundai Heavy Industries anchor capital expenditure for integrated platform installations serving both commercial and naval programs.
China
Dual carbon goals and emissions verification mandates are compelling state-owned yards to validate hull designs through computational fluid dynamics before regulatory submission. MIIT standards for smart manufacturing require digital thread implementation across production engineering workflows. Shanghai and Dalian manufacturing clusters concentrate procurement of AI-powered design optimization tools under government-backed industrial upgrading programs.
Germany
EU Green Deal emissions monitoring requirements and REACH compliance timelines are forcing Hamburg and Bremen engineering consultancies to deploy parametric hull form optimization. The country's national maritime regulator enforces verification protocols that gate market access for yards lacking certified simulation pipelines. Northern German shipyards and design houses concentrate demand for classification society-certified validation tools.
Japan
METI smart ship initiatives and carbon intensity reduction targets are driving adoption of predictive maintenance platforms across Nagasaki and Kure manufacturing bases. JIS standards for digital-ready vessel notations require AI-based machinery monitoring integration before classification society certification. Japanese yards are consolidating previously siloed engineering disciplines through unified digital twin architectures.
India
The Production-Linked Incentive scheme for maritime manufacturing is creating procurement pull for design optimization platforms at yards in Goa and Visakhapatnam. Central government mandates for domestic content requirements are accelerating software localization partnerships. Western and eastern coastal manufacturing zones are attracting simulation software vendors targeting mid-tier yard digitization programs.
Digital Shipbuilding Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial software conglomerates commanding premium pricing in integrated platform categories while niche simulation houses capture project-based consulting revenue. The vendor base concentrates around three strategic archetypes: diversified industrial technology groups with marine-specific modules, pure-play simulation specialists with classification society certifications, and systems integrators bundling third-party tools with implementation services. Dominant competitive moves include vertical integration of sensor hardware with software stacks and geographic expansion through classification society partnership networks.
Among diversified industrial technology groups, Siemens and Dassault Systèmes occupy positions exemplifying the full-stack platform archetype, while Hexagon AB represents the precision measurement and autonomous construction specialization vector. These anchors demonstrate how scale-driven R&D intensity and marine-specific certification depth create differentiation in procurement decisions at major yards.
| Leading Market Players |
|---|
| Siemens |
| Dassault Systèmes |
| Hexagon AB |
| AVEVA Group |
| BAE Systems |
| Wärtsilä |
| Altair Engineering |
| Accenture |
| SAP |
| Others |
Pricing and Supply Chain Analysis
Backward integration into GPU and high-performance computing silicon anchors both supply security and pricing power for simulation software vendors serving Korean and Japanese naval yards. Captive control over elastic compute infrastructure allows tier-one platforms to resist margin compression while mid-tier competitors absorb cost volatility from Taiwan-based foundry constraints.
Pricing Analysis
Direct-to-yard enterprise licensing commands the dominant channel margin layer, displacing distributor-heavy models in defense procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by classification society certification depth and hull complexity rating. Pricing pressure stems from cloud-native entrants offering elastic simulation access without perpetual license commitments. Mid-tier commercial yards in India and Vietnam exhibit highest price sensitivity, while Korean naval programs demonstrate lowest sensitivity due to defense budget insulation.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke patterns for software delivery and implementation support. Supply concentrates in Taiwan for GPU silicon, South Korea for memory components, and Germany for precision measurement hardware. Raw material dependencies span advanced semiconductors, specialized sensors for hull monitoring, and high-fidelity display systems for VR design review. Single-source vulnerability around Taiwan-based foundry capacity threatens real-time simulation deployment timelines. Distribution runs through direct vendor-yard relationships for major programs, supplemented by systems integrator channels for mid-tier implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Shipbuilding Market functions as a regulatory compounder, with EU Green Deal extensions and IMO carbon intensity mandates creating irreversible procurement pull for certified simulation platforms.
For Market Incumbents: Cement classification society certification depth as the primary defensive moat, prioritizing Lloyd's Register and DNV digital-ready notation alignment ahead of emerging national cybersecurity frameworks. Expand in-house GPU cluster capacity to offset Taiwan foundry concentration risk and preserve margin structure against cloud-native price competition. For New Entrants and Emerging Players: Launch via browser-based collaborative environments targeting Indian Production-Linked Incentive scheme beneficiaries in Goa and Visakhapatnam, where legacy CAD-CAM displacement creates immediate white space. Focus initial penetration on predictive maintenance modules rather than full-stack digital twin competition, leveraging classification society mandate expansion as the go-to-market wedge. For Investors and Strategic Acquirers: Roll-up economics work for pure-play marine simulation specialists because vendor fragmentation across hull structural, propulsion, and outfitting modules forces costly custom integration at each yard. Long-term viability hinges on certification network density rather than raw R&D scale. Monitor Lloyd's Register and DNV notation expansion velocity as the primary inflection signal for AI-based machinery monitoring procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Certification Investment | DNV and Lloyd's Register digital-ready notations gate market access for yard procurement decisions. |
| GPU Cluster Capacity Expansion | In-house silicon control offsets Taiwan foundry constraints threatening real-time simulation deployment. |
| Cloud-Native Platform Launch | Browser-based environments enable smaller design consultancies to compete for complex hull projects. |
| Predictive Maintenance Module Development | IMO machinery monitoring mandates expand addressable software categories beyond design-phase tools. |
| Indian Yard Partnership Network | PLI scheme beneficiaries in Goa and Visakhapatnam create immediate procurement pull for digitization platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with naval architects at DSME and Hyundai Heavy Industries, software procurement leads at Hamburg engineering consultancies, classification society technical auditors at Lloyd's Register and DNV, and fleet technical directors at Singapore-based container lines. Secondary validation drew from IMO regulatory filings, EU Green Deal implementation directives, MIIT smart manufacturing standards, and SEC disclosures from industrial software conglomerates. Bottom-up yard-level procurement tracking and top-down vendor revenue analysis were triangulated against classification society certification database expansion.
Segment-weighting approaches applied differential growth assumptions across simulation software, AI solutions, and design optimization categories, with deployment model and certification complexity serving as cross-cutting dimensions. CAGRs were derived from regression analysis of historical procurement volumes against regulatory milestone timing, incorporating naval fleet modernization program schedules and EU emissions verification deadline clustering as industry-specific inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor supply disruption or accelerated EU AI Act enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Combat Management System Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Naval Vessels Market