
 Warship and Naval Vessels Market | 2026-2036
Warship and Naval Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Warship and Naval Vessels Market Intelligence
The US Navy's 30-year shipbuilding plan is recalibrating long-term demand signals across the contractor base. Huntington Ingalls Industries anchors nuclear aircraft carrier and submarine production from its Newport News and Ingalls facilities. BAE Systems leverages its Glasgow shipyard and Type 26 frigate program to compete for allied export contracts. General Dynamics NASSCO sustains strategic sealift and auxiliary vessel construction on the US West Coast.
Warships and naval vessels encompass steel-hulled combatants and support ships exceeding one thousand tons displacement, engineered for sustained blue-water operations with integrated combat management systems, layered defensive suites, and modular mission payloads. Frigates represent the fastest-expanding vessel category as middle-power navies prioritize flexible, cost-effective surface combatants over destroyer-class capital ships. Diesel-electric propulsion dominates export orders where nuclear technology transfer faces treaty constraints, while hybrid architectures gain traction in coast guard and offshore patrol applications seeking reduced acoustic signatures and fuel consumption.
The US Navy's shipbuilding mandates interact with UK MoD procurement standards and Australia's AUKUS treaty obligations to reshape supplier qualification requirements across Anglo-American construction networks. The International Maritime Organization's safety conventions and national naval classification societies enforce survivability standards that govern hull design, damage control subdivision, and combat system redundancy. Stakeholders must monitor how AUKUS nuclear-propulsion technology sharing alters subcontractor certification demands and which yards outside the three partner nations secure derivative conventional designs.
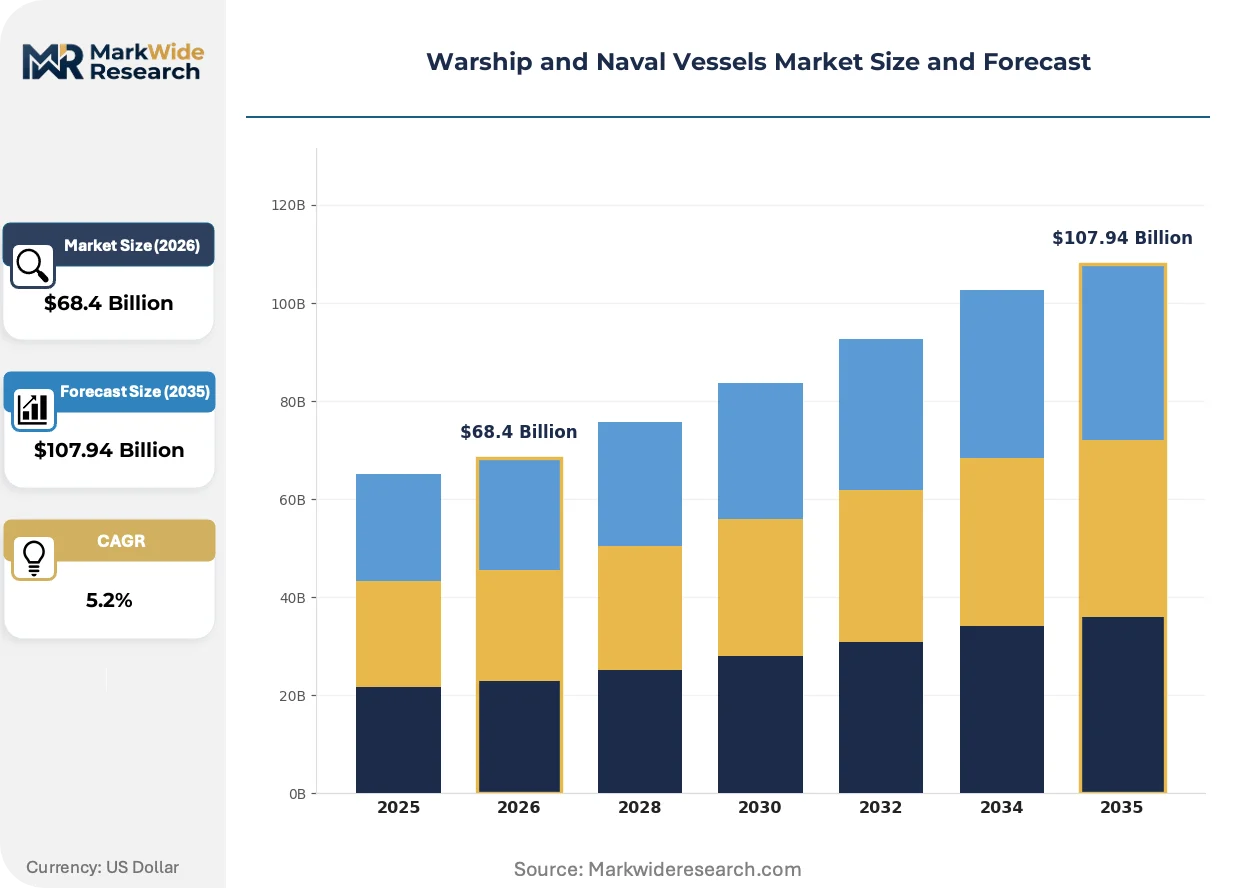
Market Dynamics
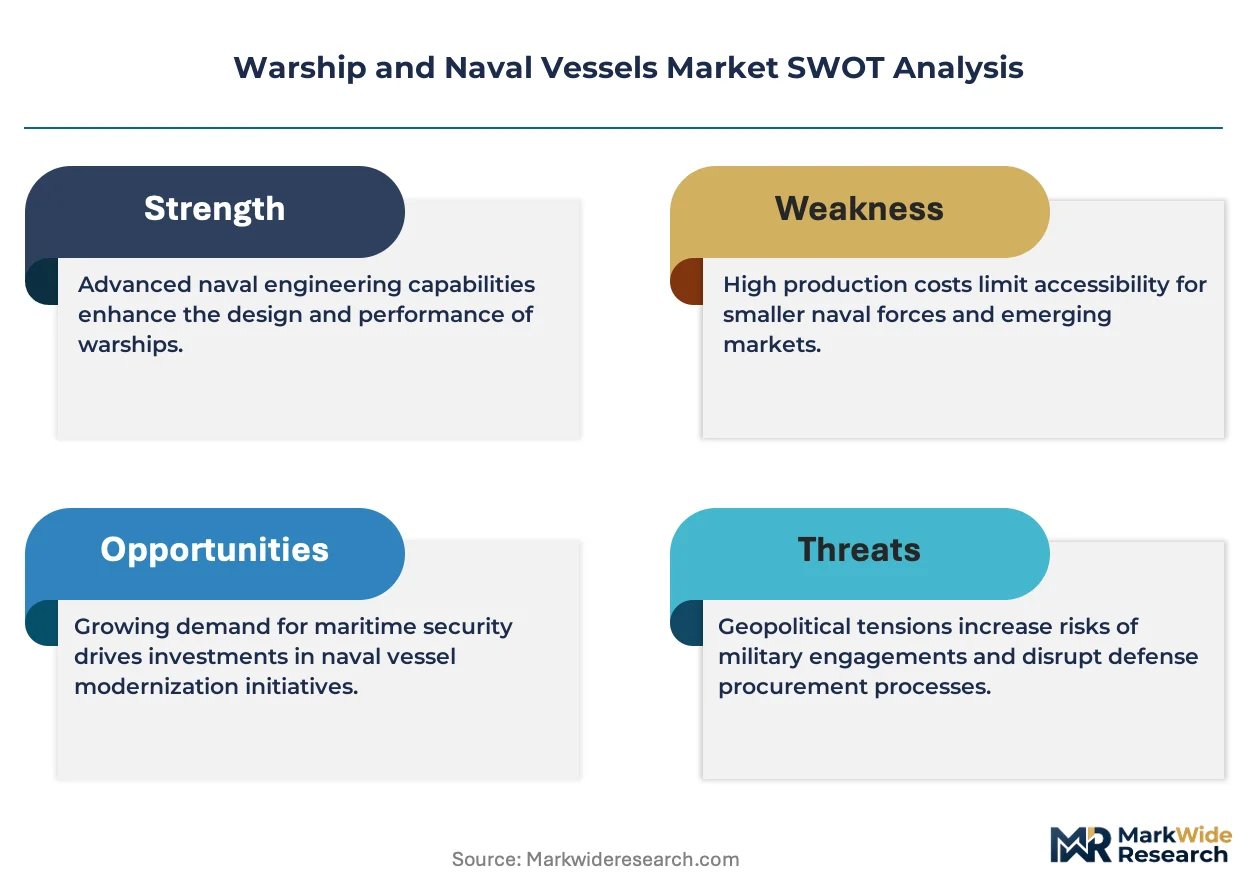
The AUKUS nuclear-propulsion technology sharing agreement is restructuring supplier qualification requirements across Anglo-American construction networks, forcing yards to recertify for reactor-grade fabrication standards while diverting engineering capacity from conventional hull programs.
Growth Catalysts
- US Navy 30-Year Shipbuilding Plan:Multi-decade procurement mandates from the Pentagon are locking in long-term demand visibility for nuclear aircraft carriers and Virginia-class submarines, allowing contractors to justify facility expansion and workforce training investments.
- AUKUS Treaty Obligations:Australia's commitment to acquire nuclear-powered submarines under the trilateral security pact is creating a second Pacific construction queue, with UK and US yards transferring reactor compartment fabrication techniques to Port Adelaide facilities.
- Integrated Electric Propulsion:Advanced motor-generator architectures are enabling smaller crews and reduced acoustic signatures in frigate-class vessels, appealing to middle-power navies seeking destroyer-equivalent capability without nuclear complexity.
Market Restraints
- Specialized Steel Supply Concentration:HY-80 and HY-100 high-yield submarine hull plates are produced by only three qualified mills globally, creating single-source vulnerability for US and UK nuclear programs.
- Nuclear Technology Transfer Barriers:The Nuclear Non-Proliferation Treaty and national export control regimes block reactor propulsion sales to non-AUKUS buyers, capping addressable demand for the highest-margin vessel category.
- Skilled Welder Scarcity:Radiographic-quality welding certification for pressure hull joints requires 4,000+ training hours, with Newport News and Electric Boat competing for a shrinking pool of qualified tradespeople.
Strategic Opportunities
- Conventional Derivative Designs:Non-AUKUS allies including Japan and South Korea are seeking Type 26 and Constellation-class frigate variants without nuclear systems, opening export channels for Glasgow and Marinette Marine yards.
- Coast Guard Hybrid Architectures:The US Coast Guard's offshore patrol cutter program is validating diesel-electric hybrid propulsion for 4,000-ton hulls, creating a template for allied constabulary fleets prioritizing fuel efficiency over sprint speed.
- PLI Scheme Alignment:India's production-linked incentive framework for defense manufacturing is attracting foreign shipbuilders to joint ventures at Goa and Visakhapatnam facilities, circumventing domestic construction capacity constraints.
Industry Challenges
- Combat System Integration Complexity:Lockheed Martin's Aegis Combat System and Thales' TACTICOS require multi-year software qualification cycles that extend delivery timelines and strain prime-subcontractor coordination.
- Classification Society Recertification:Lloyd's Register and ABS are implementing revised fatigue-life standards for welded aluminum superstructures, forcing design modifications on littoral combat ships already under construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warship and Naval Vessels Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Destroyers, Frigates, Submarines, Amphibious Assault Ships Naval Operations: Surface Warfare, Anti-Submarine Warfare, Amphibious Operations, Support Operations Propulsion Technology: Diesel-Electric, Gas Turbine, Nuclear, Hybrid End User: Naval Forces, Coast Guards, Maritime Security Agencies, Research Institutions |
| Companies Covered | BAE Systems, Fincantieri Marinette Marine, Huntington Ingalls Industries, Hanwha Ocean, Newport News Shipbuilding, General Dynamics NASSCO, Northrop Grumman, Ingalls Shipbuilding, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warship and Naval Vessels Market Strategic Shifts & Innovations
Digital twin technology is compressing sea-trial schedules and enabling predictive hull maintenance, while modular mission payload architectures are allowing single hull forms to switch between anti-submarine, surface warfare, and mine-countermeasures roles without dry-dock conversion.
Additive manufacturing is absorbing critical spare-part production for at-sea replenishment, with metal powder bed fusion now qualified for Inconel propeller shaft seals and titanium valve components. US Navy fleet maintenance squadrons are deploying containerized 3D printing cells aboard expeditionary sea base vessels, reducing dependency on continental supply chains for high-failure-rate subassemblies. This distributed fabrication model is compressing repair timelines from weeks to days for non-critical mechanical components.
The International Maritime Organization's revised Safety of Life at Sea conventions are mandating doubled hull-compartmentalization standards for vessels over 5,000 tons displacement, forcing redesign of auxiliary machinery spaces and ballast systems. European yards including Navantia and Fincantieri are accelerating compliance engineering to maintain classification society approvals for NATO interoperability certification. Frigate programs in Spain and Italy are absorbing the largest cost impact from redundant pumping and electrical distribution architectures.
Allied navies are consolidating maintenance contracts into decade-long availability agreements that bundle hull, mechanical, and combat system servicing under single-vendor responsibility. The UK Royal Navy's Type 45 destroyer support model is replacing discrete repair tenders with BAE Systems-managed through-life support, transferring operational risk to the industrial base. This performance-based structure is most advanced in Portsmouth and Devonport facilities, with Australia and Canada evaluating similar transitions for their surface combatant fleets.
Warship and Naval Vessels Market Segmentation
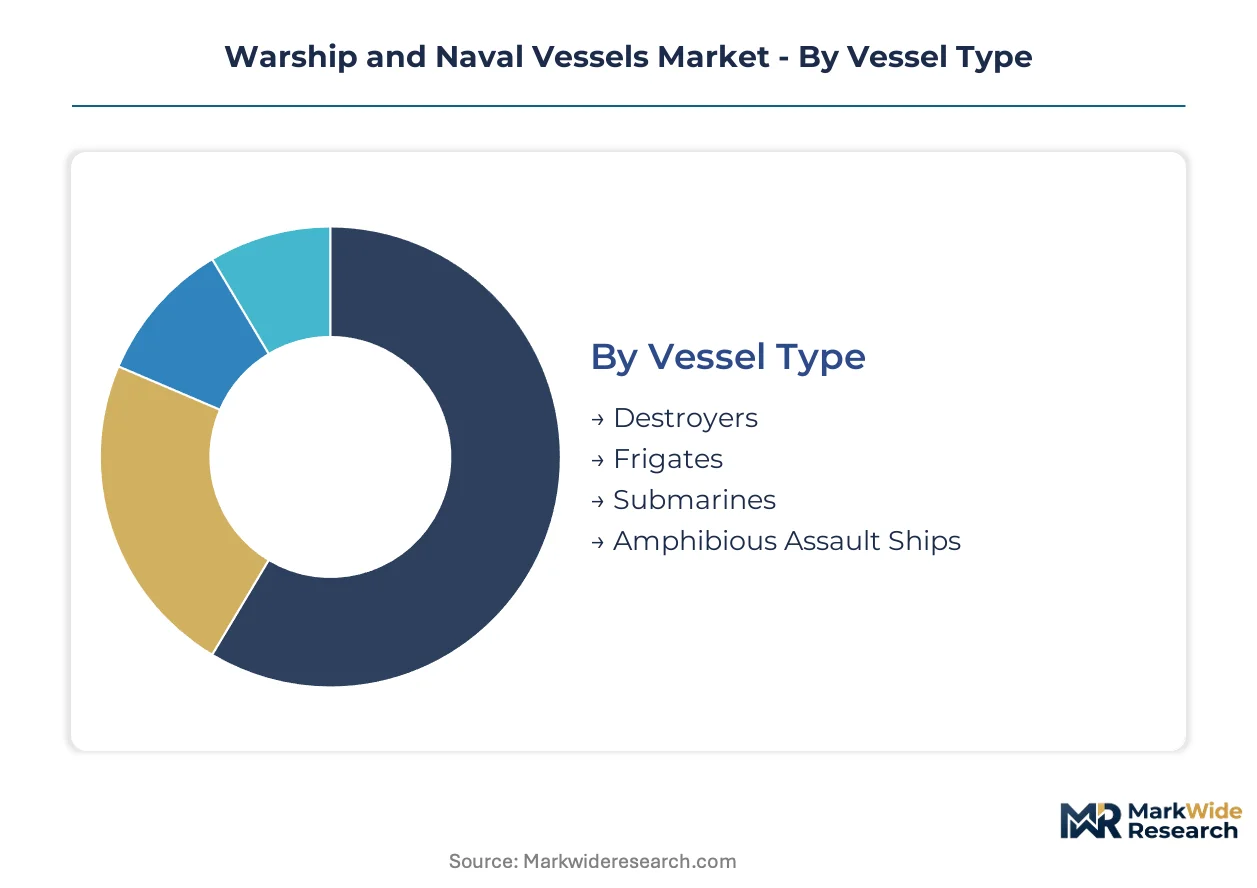
Segmentation reveals how procurement priorities diverge across mission profiles and technological sophistication. Contractor order books align with specific vessel categories and operational mandates, creating distinct competitive arenas within the broader market.
Vessel Type:
Production capacity concentrates in yards qualified for nuclear and large steel-hulled construction, with backlog visibility stretching across multi-decade procurement cycles.
- Destroyers:These 8,000-10,000 ton surface combatants integrate Aegis Combat Systems and vertical launch missile cells for area air defense. The US Navy's Arleigh Burke program and Japan's Maya-class construction at Yokosuka facilities absorb the majority of qualified yard capacity, constrained by combat system integration bottlenecks.
- Frigates:Smaller 4,000-6,000 ton hulls prioritize cost-effectiveness and exportability over destroyer-class capability. Australia's Hunter-class program at Osborne and the US Constellation-class at Marinette Marine are driving the fastest order expansion as middle-power navies seek flexible platforms.
- Submarines:Nuclear and diesel-electric variants require radiographic-quality welding and pressure hull fabrication at specialized facilities.
- Amphibious Assault Ships:Flat-deck aviation vessels and dock landing ships support expeditionary force projection with well deck and flight deck configurations.
Destroyers absorb the bulk of installed capacity; frigates are expanding most quickly.
Naval Operations:
Cost tier differentiation separates capital-intensive combat systems from lower-margin support functions, with prime contractors prioritizing integrated warfare packages over standalone auxiliary contracts.
- Surface Warfare:Anti-ship missile defense and naval gunfire support missions drive demand for large-caliber vertical launch systems and radar cross-section reduction. The US Navy's distributed maritime operations doctrine and China's fleet expansion in the South China Sea are concentrating procurement in Indo-Pacific theaters.
- Anti-Submarine Warfare:Sonar suite integration, variable-depth towed arrays, and torpedo countermeasures define this mission set. Norway's Kongsberg and Sweden's Saab are capturing niche demand for littoral-focused systems as Baltic and North Sea navies modernize.
- Amphibious Operations:Ship-to-shore connector compatibility and aviation fuel capacity prioritize well deck geometry and flight deck strength.
- Support Operations:Replenishment-at-sea and medical mission modules require modular payload architectures with reduced defensive suites.
Surface warfare absorbs the bulk of installed capacity; anti-submarine warfare is climbing the fastest.
Propulsion Technology:
Volume distribution reflects treaty constraints on nuclear transfer and the geographic concentration of reactor-grade fabrication expertise.
- Nuclear:Pressurized water reactors deliver unlimited range and submerged endurance for aircraft carriers and ballistic missile submarines. US and UK yards at Newport News and Barrow-in-Furness maintain exclusive qualification, with Australia's AUKUS submarine program now entering this restricted supplier base.
- Diesel-Electric:Conventional air-independent propulsion and lead-acid or lithium-ion battery banks dominate export markets barred from nuclear technology. German TKMS and French Naval Group compete for Mediterranean and Southeast Asian orders where submerged endurance requirements remain modest.
- Gas Turbine:LM2500 and MT30 marine turbines power surface combatants requiring sprint speeds above 30 knots.
- Hybrid:Diesel-electric architectures with battery buffering reduce acoustic signatures and fuel consumption for patrol missions.
Diesel-electric systems absorb the bulk of installed capacity; nuclear propulsion is gaining share fastest among high-value contracts.
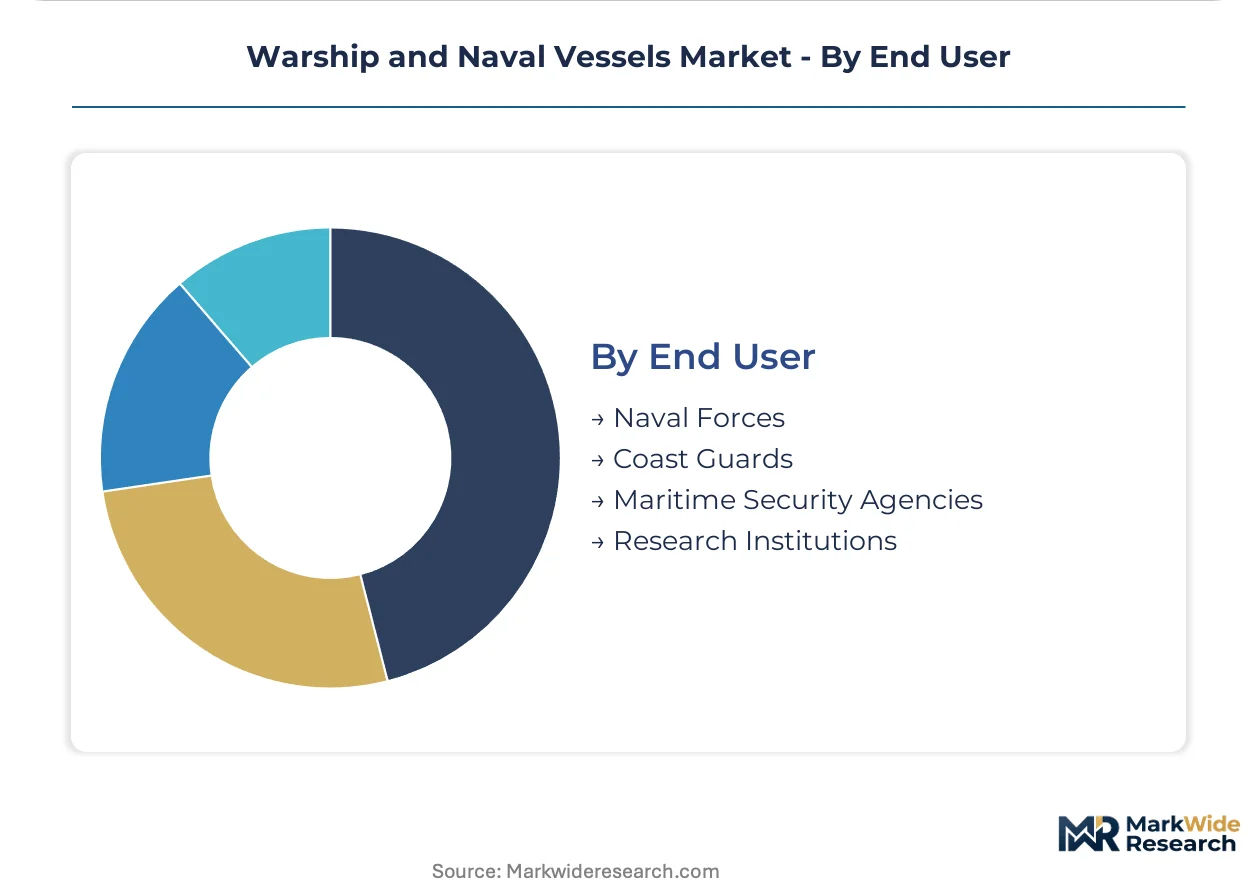
End User:
Customer type determines specification stringency, with naval forces demanding full combat system integration while constabulary fleets accept reduced defensive suites.
- Naval Forces:Blue-water navies require integrated combat management systems, layered air defense, and blue-water logistics compatibility. The US Navy's 30-year shipbuilding plan and India's indigenous aircraft carrier program represent the largest committed demand pipelines.
- Coast Guards:Offshore patrol and law enforcement missions prioritize endurance over armament, with the US Coast Guard's Heritage-class cutter program validating hybrid propulsion for 4,000-ton constabulary hulls.
- Maritime Security Agencies:Border patrol and counter-smuggling operations drive demand for lightly armed fast patrol craft.
- Research Institutions:Oceanographic survey and polar icebreaking missions require specialized hull forms with reduced ice-class certification.
Naval forces absorb the bulk of installed capacity; coast guards are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Newport News anchors nuclear carrier and submarine construction on the US Atlantic coast, while Barrow-in-Furness and Glasgow yards concentrate UK naval fabrication. Asian shipbuilding clusters in Ulsan and Goa are expanding conventional combatant capacity as regional fleets modernize.
United States
Virginia-class submarine procurement and Columbia-class ballistic missile replacement programs drive demand at Electric Boat and Newport News facilities. The US Navy's 30-year shipbuilding plan mandates sustained carrier construction through 2058. Ingalls Shipbuilding in Pascagoula and Bath Iron Works in Maine handle large surface combatant fabrication.
United Kingdom
The Dreadnought submarine program and Type 26 frigate exports to Australia and Canada sustain workload at BAE Systems' Barrow and Glasgow yards. UK MoD procurement standards require reactor-grade fabrication certification that limits supplier pools. Rosyth dockyard in Scotland handles aircraft carrier assembly and through-life support.
Australia
AUKUS treaty obligations commit Australia to nuclear-powered submarine acquisition with UK and US technology transfer to Port Adelaide facilities. The Hunter-class frigate program at Osborne South creates conventional construction capacity alongside nuclear infrastructure preparation. Australian Submarine Agency coordinates qualification requirements with Anglo-American partners.
South Korea
Hanwha Ocean in Ulsan and DSME in Okpo are expanding export frigate and submarine offerings for Southeast Asian and Middle Eastern navies. KDX-III destroyer production and Jangbogo-III submarine programs absorb domestic yard capacity. Seoul's Defense Acquisition Program Administration prioritizes indigenous combat system integration.
India
Indigenous aircraft carrier construction at Cochin Shipyard and Scorpene submarine license-building at Mazagon Dock sustain state-owned fabrication. India's PLI scheme for defense manufacturing attracts foreign joint ventures at Goa and Visakhapatnam facilities. Cochin and Mumbai clusters concentrate nuclear and conventional submarine expertise.
Warship and Naval Vessels Market Key Industry Players
Premium-margin players sit above commodity-margin players across nuclear certification barriers and combat system integration depth. The contractor base concentrates in yards qualified for reactor-grade fabrication and radiographic welding standards, with tiering determined by access to classified propulsion technology. Three archetypes dominate: sovereign nuclear-capable primes, conventional combatant specialists, and combat system integrators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as AUKUS obligations force cross-border engineering transfers.
Within the sovereign nuclear-capable tier, Huntington Ingalls Industries and General Dynamics NASSCO represent US-based fabrication anchors, while BAE Systems occupies a parallel position in UK construction networks. These entities exemplify the integrated prime model combining hull fabrication with through-life support contracting. Fincantieri Marinette Marine and Hanwha Ocean sit within the conventional combatant specialist archetype, pursuing export markets barred from nuclear technology transfer. The competitive terrain rewards yards that can bridge nuclear and conventional qualification regimes while securing decade-long availability agreements.
| Leading Market Players |
|---|
| BAE Systems |
| Fincantieri Marinette Marine |
| Huntington Ingalls Industries |
| Hanwha Ocean |
| Newport News Shipbuilding |
| General Dynamics NASSCO |
| Northrop Grumman |
| Ingalls Shipbuilding |
| Lockheed Martin |
| Others |
Cost & Logistics Intelligence
Naval procurement offices in the US, UK, and Australia anchor demand concentration, locking in cost-plus contracting with performance incentives tied to delivery milestones and combat system integration outcomes. This buyer structure privileges vessel categories with reactor-grade certification over conventional hulls.
Pricing Analysis
Availability-based pricing dominates, with through-life support contracts bundling hull construction, combat system integration, and decade-long maintenance under single-vendor responsibility. Price differentiation rests on radiographic welding certification tier and AUKUS nuclear-propulsion access. Cost compression in conventional frigate segments is intensifying because middle-power navies prioritize exportable hull forms over bespoke designs. Coast guard procurement shows highest price sensitivity; nuclear submarine programs show least.
Supply Chain Analysis
Refurbishment flows for pressure hull components and reactor compartment subassemblies create reverse-logistics demand at Newport News, Barrow-in-Furness, and Port Adelaide facilities. Supply concentrates in the United States, United Kingdom, and Australia for nuclear-qualified fabrication. HY-80 and HY-100 high-yield steel plate and radiographic-quality welding consumables constitute critical input dependencies. Single-source vulnerability at three qualified mills for submarine hull plate creates structural supply risk. Distribution runs through sovereign naval procurement channels with classified technology controls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiographic welder scarcity props pricing power for qualified yards, constraining output expansion regardless of order book depth.
For Market Incumbents: Acquire welding training capacity and reactor-grade fabrication certifications to lock in AUKUS program access. Huntington Ingalls Industries and BAE Systems should expand apprentice pipelines at Newport News and Glasgow while defending against emerging Korean and Japanese yards seeking conventional frigate exports. Certification investment represents the critical defensive lever. For New Entrants and Emerging Players: The mid-tier price gap between AUKUS nuclear programs and economy coast guard cutters creates entry space for hybrid-propulsion specialists. Hanwha Ocean and Fincantieri Marinette Marine can penetrate Southeast Asian and Middle Eastern navies seeking diesel-electric frigate variants without nuclear complexity. Joint venture structures with Indian PLI scheme beneficiaries offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors yards with dual conventional-nuclear qualification bridging AUKUS and export markets. Long-term viability hinges on securing decade-long availability agreements that transfer operational risk from navies to industrial bases. Monitor AUKUS technology transfer implementation timelines at Port Adelaide as the inflection signal for supplier certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor-Grade Certification Investment | BAE Systems and Electric Boat secure exclusive supplier status for AUKUS nuclear submarine construction queues. |
| Through-Life Support Contracting | UK Royal Navy Type 45 destroyer model transfers operational risk to BAE Systems-managed Portsmouth facilities. |
| Conventional Derivative Design Export | Type 26 and Constellation-class frigate variants open channels for Glasgow and Marinette Marine in non-AUKUS markets. |
| Welding Workforce Pipeline Expansion | Newport News and Barrow-in-Furness apprenticeships address 4,000-hour radiographic certification bottlenecks. |
| Hybrid Propulsion Architecture Validation | US Coast Guard Heritage-class cutter program creates template for allied constabulary fleet fuel efficiency demands. |
Research Approach
Independent corroboration across naval shipyard executives, defense procurement officers, and combat system integration engineers underwrites the qualitative findings. Primary interviews with welding certification instructors, classification society surveyors, and submarine program managers combined with secondary validation from Lloyd's Register specifications, ABS hull standards, and national naval classification society filings. Bottom-up order book analysis and top-down defense budget triangulation anchored volume estimates.
Comparable-period anchoring to historical shipbuilding cycles and procurement wave patterns structured the forecast window across the projection horizon. Segmentation modeling captured vessel type, propulsion technology, naval operations mission profile, and end-user tier dimensions. CAGRs derived from contracted backlog visibility and planned procurement milestones. AUKUS treaty implementation schedules and 30-year shipbuilding plan revisions constituted key forecast inputs.
Inputs from shipyard capacity disclosures and defense ministry budget documentation were available through the study window; gaps in classified combat system integration timelines introduce uncertainty bands around delivery schedules. Forecasts reflect assumptions regarding welder training pipeline expansion and steel mill qualification maintenance. Practitioners should monitor AUKUS technology transfer progress and HY-80 steel mill capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Vessels Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Military Frigate Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Digital Shipbuilding Market