
 Combat Drone Market | 2026-2036
Combat Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Drone Market Insights
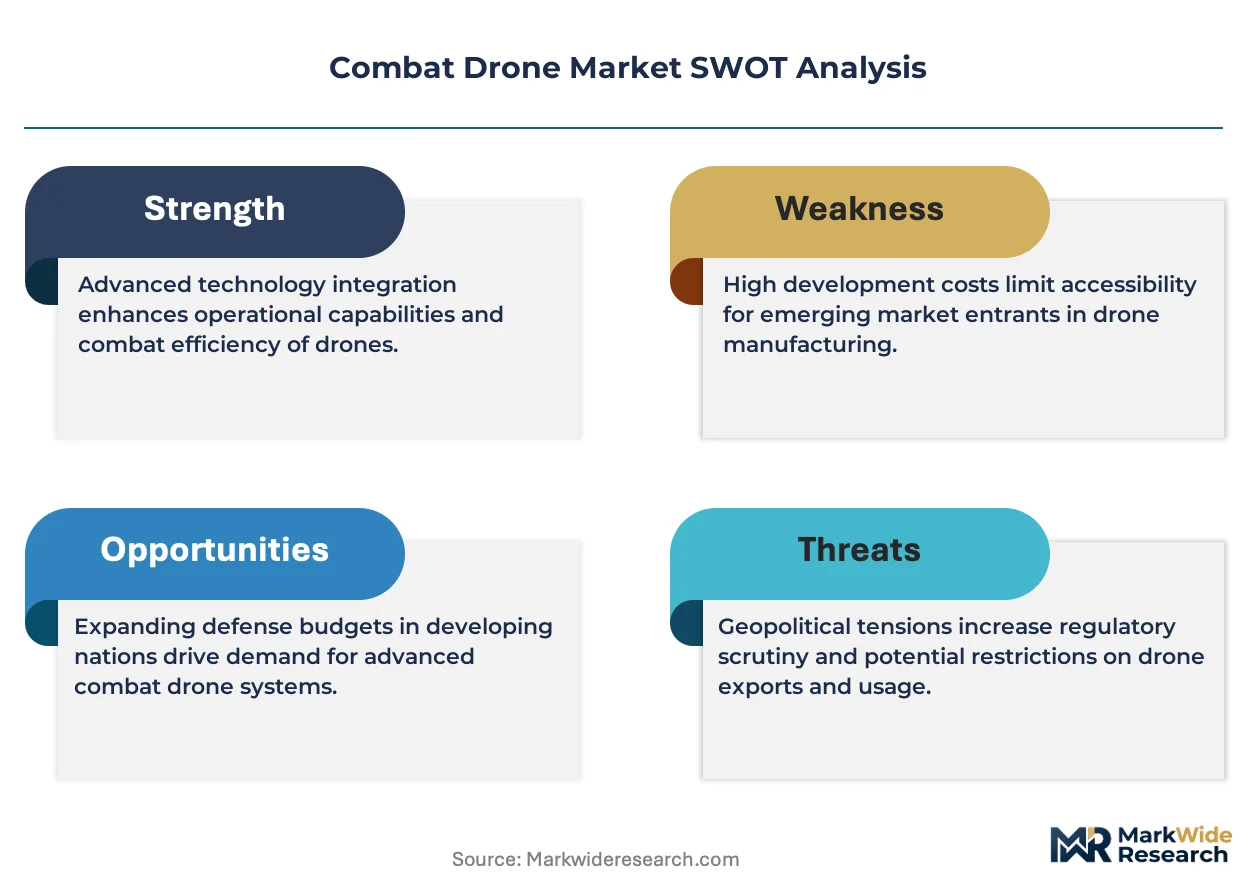
Carbon fiber composites is consolidating as the primary airframe material, replacing aluminum alloys in medium-altitude long-endurance platforms. General Atomics Aeronautical Systems leverages its integrated composite manufacturing to control costs on the MQ-9 Reaper line. Northrop Grumman Corporation anchors its high-altitude portfolio with all-composite Global Hawk derivatives. Elbit Systems competes through specialized Hermes-family architectures optimized for export markets with lighter payload requirements.
Combat drones are unmanned aerial systems designed for kinetic and non-kinetic military operations, typically spanning wingspaces from three meters on tactical platforms to over thirty meters on strategic systems, with endurance ranging eight to forty hours and operating ceilings between 25,000 and 60,000 feet. Fixed-wing drones dominate procurement budgets for persistent surveillance and precision strike missions. Rotary-wing configurations occupy niche roles in urban close-air support where vertical takeoff constraints apply. Artificial Intelligence integration represents the fastest-expanding technology segment, with autonomous target recognition algorithms reshaping operator-to-vehicle ratios across reconnaissance and target acquisition missions.
The US Federal Aviation Administration coordinates military airspace integration for beyond-visual-line-of-sight training flights, while the European Union Aviation Safety Agency enforces civil-military dual-use certification under its drone regulatory framework. The US International Traffic in Arms Regulations restrict technology transfer to allied nations, creating segmented supply chains that limit component sourcing for non-NATO manufacturers. Stakeholders must monitor evolving autonomous weapons governance at the United Nations Convention on Certain Conventional Weapons, where lethal autonomy prohibitions could redirect R&D investment toward manned-unmanned teaming architectures.
Market Dynamics
Autonomous targeting algorithms are compressing operator-to-vehicle ratios across NATO reconnaissance formations, forcing procurement offices to restructure training pipelines and maintenance contracts around reduced crew footprints.
Growth Catalysts
- ITAR Technology Transfer:The US International Traffic in Arms Regulations create captive supply chains that shield domestic manufacturers from foreign component competition while mandating allied nations source through approved channels.
- Carbon Fiber Manufacturing:Integrated composite fabrication is reducing airframe weight by thirty percent on medium-altitude platforms, extending mission endurance without engine upgrades.
- NATO Strike Platform Procurement:Member state defense ministries are consolidating orders for persistent surveillance systems under collective capability targets, pooling development costs across national budgets.
Market Restraints
- FAA-EASA Divergence:The US Federal Aviation Administration and European Union Aviation Safety Agency impose incompatible airworthiness certification pathways, forcing manufacturers to maintain dual compliance documentation.
- Semiconductor Supply Concentration:Radiation-hardened flight processors rely on a single foundry geography, creating single-point vulnerability for guidance system production.
- Lethal Autonomy Governance:United Nations Convention on Certain Conventional Weapons deliberations threaten to prohibit fully autonomous strike decisions, capping algorithmic capability investment.
Strategic Opportunities
- Manned-Unmanned Teaming:Piloted aircraft coordination protocols are opening architecture contracts for datalink integration specialists serving fighter wing command structures.
- Urban Close-Air Support:Rotary-wing configurations for vertical takeoff constraints in dense environments remain underpenetrated relative to fixed-wing procurement volumes.
- Export Market Payload Optimization:Lighter sensor packages for allied nations with restricted payload budgets are creating derivative platform lines with simplified maintenance requirements.
Industry Challenges
- Autonomous Systems Engineering Talent:Machine vision and sensor fusion expertise concentrates in civilian technology sectors, forcing defense contractors to compete for algorithm developers outside traditional aerospace labor pools.
- Beyond-Visual-Line-of-Sight Certification:Military airspace integration for training flights requires case-by-case FAA coordination, extending program development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Drone Market |
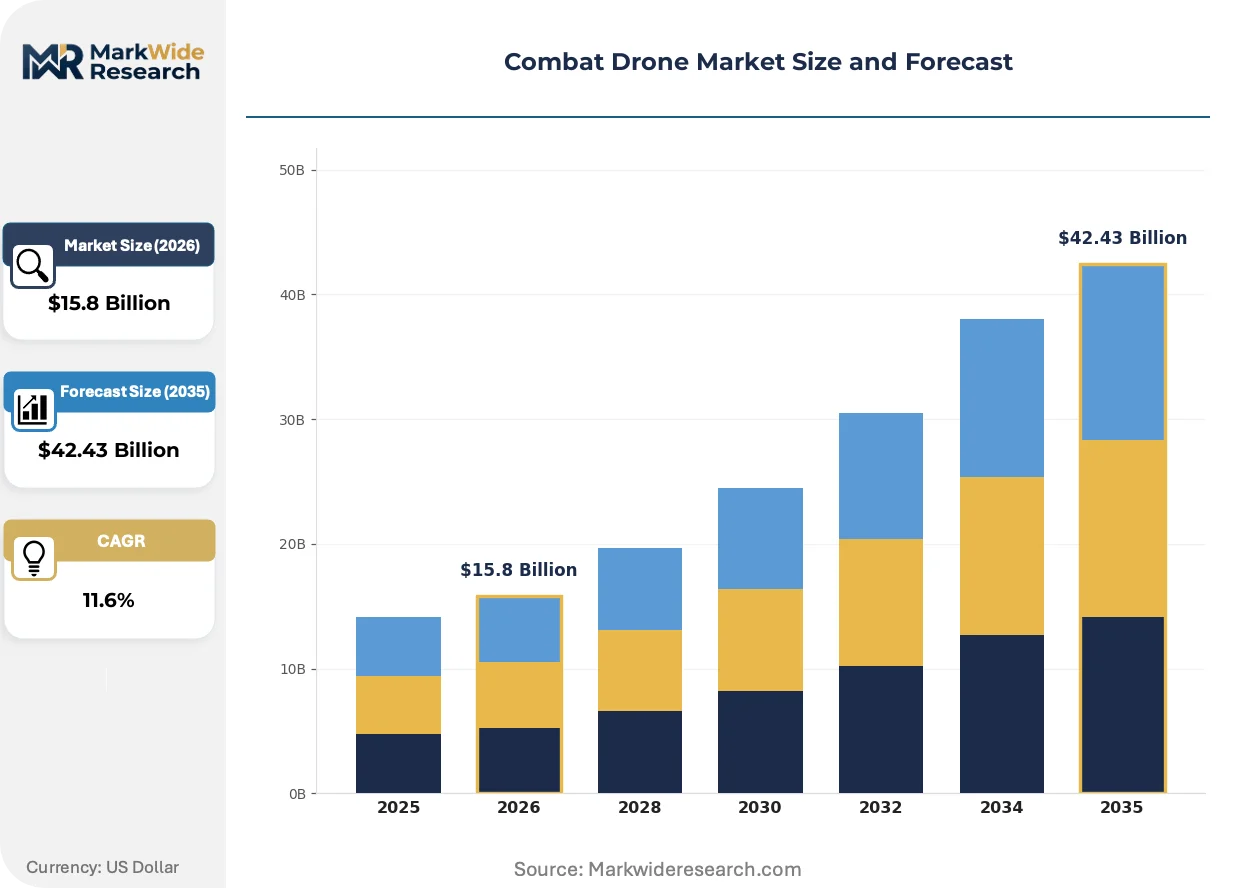
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $42.43 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Rotary-Wing Drones, Hybrid Drones, Nano Drones Technology: Autonomous Navigation, Remote Control, Artificial Intelligence, Signal Intelligence, Surveillance Systems Application: Reconnaissance, Target Acquisition, Combat Support, Border Patrol, Electronic Warfare End User: Military Forces, Defense Contractors, Government Agencies, Security Forces |
| Companies Covered | General Atomics Aeronautical Systems, Northrop Grumman Corporation, Raytheon Technologies Corporation, Israel Aerospace Industries Ltd., Elbit Systems, Baykar Technologies, Lockheed Martin, Teledyne FLIR LLC., Leonardo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Drone Market Trends and Innovations
Artificial intelligence integration is fragmenting traditional platform categories as software-defined capabilities allow single airframes to alternate between surveillance, electronic warfare, and kinetic roles through payload swaps rather than dedicated fleet procurement.
Neuromorphic computing architectures for onboard target recognition is overtaking conventional GPU-based processing in next-generation flight computers. The US Department of Defense is accelerating fielding timelines for these systems through rapid acquisition pathways. This compression is collapsing the traditional gap between laboratory demonstration and operational deployment for autonomous decision aids.
The European Union Aviation Safety Agency drone regulatory framework is mandating civil-military dual-use certification for platforms operating in shared airspace. Manufacturers must now design airworthiness documentation that satisfies both combat survivability standards and civilian collision-avoidance protocols. This dual compliance is most burdensome for tactical platforms intended for rapid deployment across multiple theater types.
Defense procurement offices are unbundling sensor packages from airframe contracts, creating separate competitive solicitations for mission equipment. System integrators now compete on platform-agnostic payload compatibility rather than vertical airframe-sensor offerings. This shift is most visible in United States Special Operations Command requirements documents, which specify open architecture standards mandating third-party subsystem integration.
Combat Drone Market Segmentation
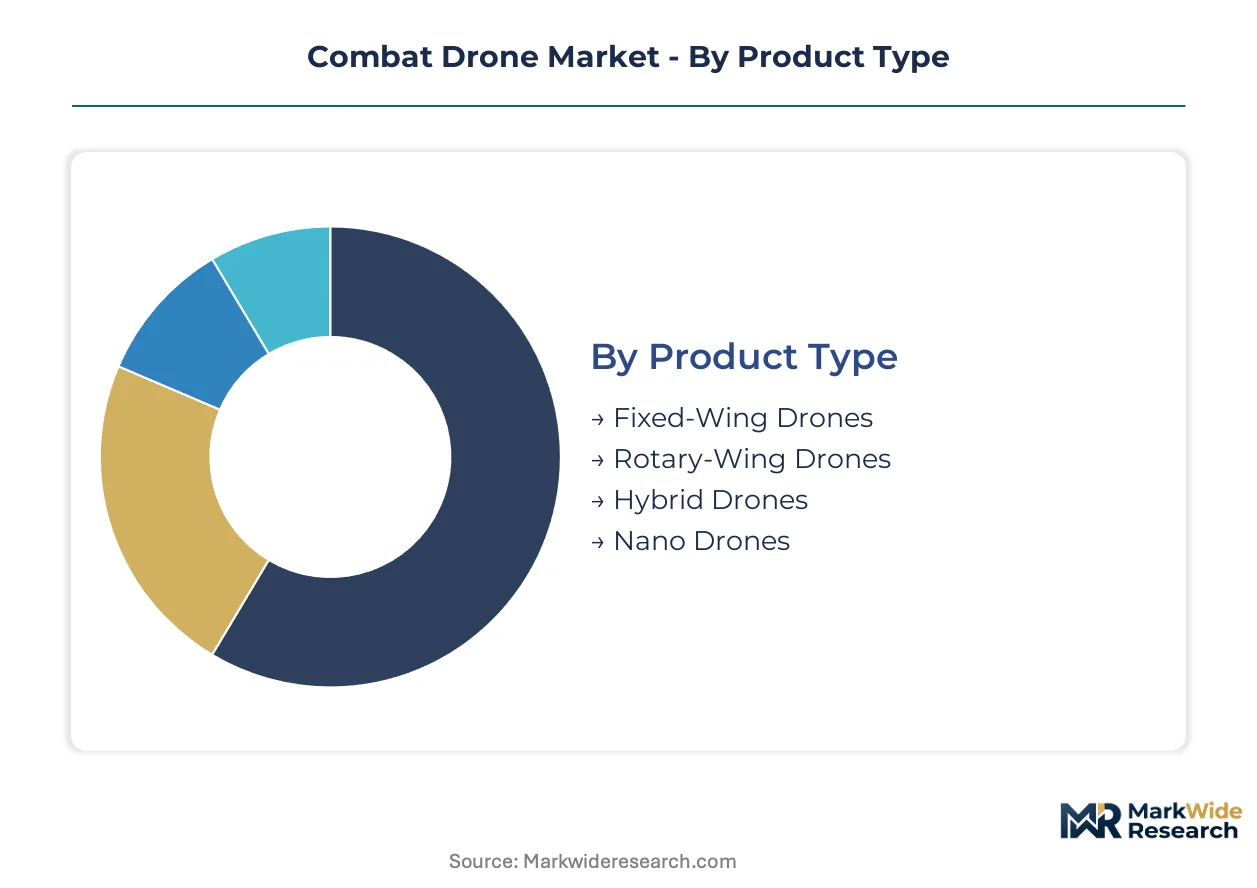
Combat drone procurement divides across mission profile, autonomy level, and operator type. Procurement officers structure acquisition around endurance requirements, payload flexibility, and rules of engagement constraints. Each segmentation axis carries distinct certification pathways and supply chain implications.
Product Type:
Fixed-wing platforms command procurement volume for persistent surveillance missions. Rotary-wing and hybrid configurations capture premium pricing in specialized access scenarios.
- Fixed-Wing Drones:High-aspect-ratio airframes deliver 20-40 hour endurance at medium altitude. The United States Department of Defense concentrates orders here for counter-insurgency operations requiring station time over target.
- Rotary-Wing Drones:Coaxial and quadrotor architectures enable vertical takeoff from confined spaces. Urban close-air support missions in dense environments drive specialized procurement from security forces lacking runway infrastructure.
- Hybrid Drones:Tilt-rotor and tail-sitter configurations merge runway independence with transit efficiency.
- Nano Drones:Sub-200-gram platforms for infantry-level reconnaissance carry severe payload and range constraints.
Today's leader: Fixed-Wing Drones. Tomorrow's challenger: Hybrid Drones.
Technology:
Autonomy sophistication determines operator-to-vehicle ratios and export licensing tiers. Remote-controlled systems face fewer International Traffic in Arms Regulations restrictions than algorithmic target recognition platforms.
- Artificial Intelligence:Onboard target recognition and sensor fusion algorithms compress crew requirements by 60% on reconnaissance missions. The United Nations Convention on Certain Conventional Weapons deliberations constrain investment in lethal autonomy, redirecting R&D toward manned-unmanned teaming protocols.
- Autonomous Navigation:GPS-denied waypoint following and terrain-relative navigation enable operations in contested electromagnetic environments. NATO member states prioritize this capability for near-peer conflict scenarios.
- Remote Control:Line-of-sight radio links retain dominance in tactical platforms where spectrum assurance is unreliable.
- Signal Intelligence:Communications intercept and electronic support measures require specialized antenna arrays and processing hardware.
- Surveillance Systems:Electro-optical and synthetic aperture radar payloads represent mature procurement categories with established supplier bases.
Artificial Intelligence is climbing the fastest. Remote Control retains installed base dominance.
Application:
Reconnaissance and target acquisition absorb majority procurement spend. Combat support and electronic warfare represent higher-margin specialization opportunities.
- Reconnaissance:Wide-area persistent surveillance drives fleet sizing for NATO member states. Ground moving target indication and full-motion video requirements shape sensor package specifications.
- Target Acquisition:Laser designation and coordinate generation for manned strike platforms demands precise geolocation accuracy. Special Operations Command requirements documents prioritize this mission set for contested environment operations.
- Combat Support:Armed overwatch and convoy protection missions require kinetic payload integration.
- Border Patrol:Sovereignty enforcement applications favor cost-optimized platforms with simplified maintenance.
- Electronic Warfare:Radar jamming and communications denial missions require high-power RF generation with thermal management constraints.
Reconnaissance holds procurement volume leadership. Electronic Warfare shows steepest expansion trajectory.
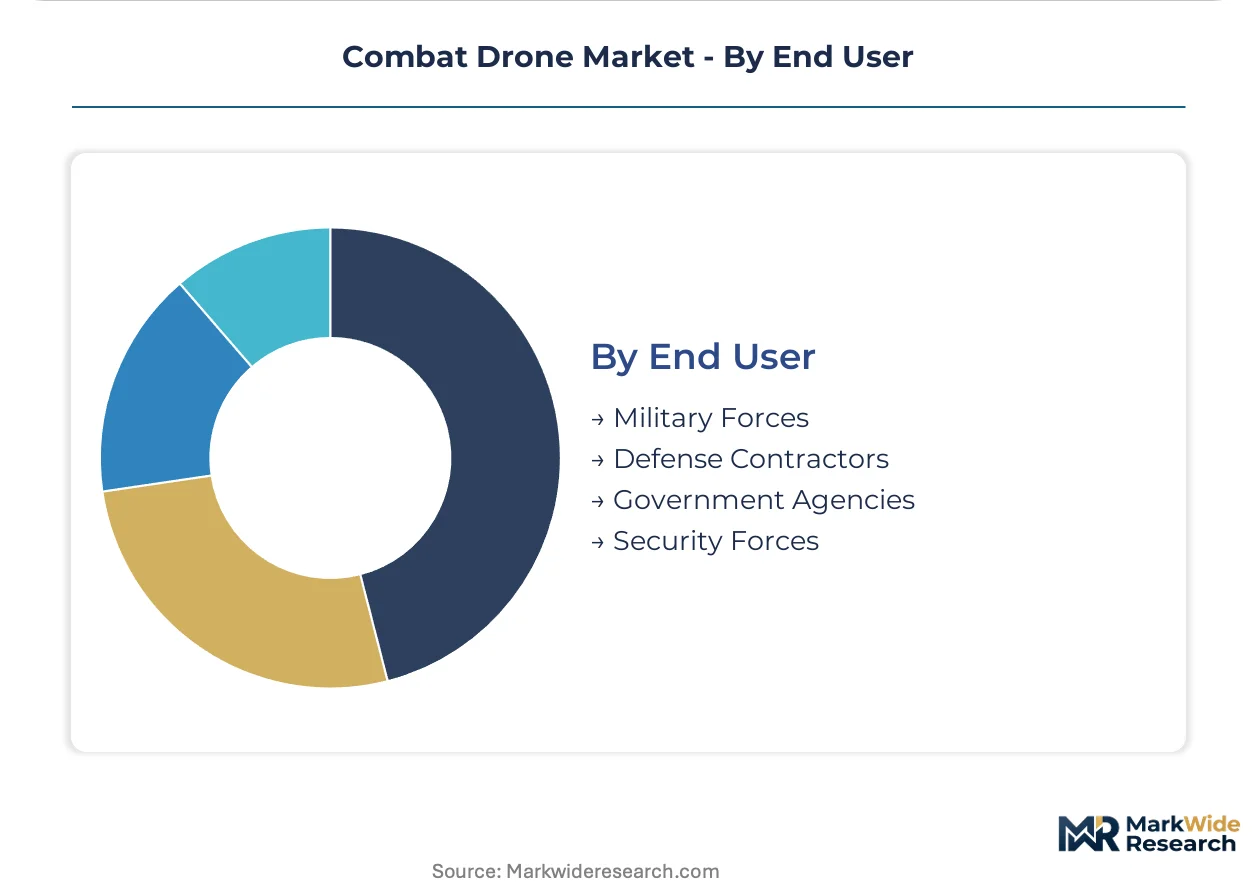
End User:
Military forces structure acquisition around joint operational requirements. Defense contractors and government agencies pursue specialized capabilities outside standard program of record pathways.
- Military Forces:Service branches define platform specifications through joint capabilities integration and development system processes. The United States Army, Navy, Air Force, and Marine Corps maintain distinct procurement timelines with varying payload and basing requirements.
- Defense Contractors:Prime integrators and subsystem vendors acquire platforms for foreign military sales preparation and technology demonstration. International Traffic in Arms Regulations compliance shapes their supplier relationships.
- Government Agencies:Border security and maritime enforcement organizations operate under civil aviation regulatory frameworks requiring dual-use certification.
- Security Forces:Paramilitary and law enforcement units face stricter rules of engagement constraints than national military organizations.
Military Forces dominate program of record volume. Defense Contractors drive technology transition velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States defense industrial base anchors combat drone procurement volume through Pentagon program of record spending and rapid acquisition pathways for autonomous systems.
United States
Department of Defense operational requirements for persistent surveillance and precision strike sustain the largest armed unmanned fleet worldwide. The Federal Aviation Administration coordinates military airspace integration for beyond-visual-line-of-sight training flights through case-by-case waivers. General Atomics Aeronautical Systems maintains integrated composite manufacturing in California to control costs on medium-altitude platforms.
Israel
Export-oriented manufacturers target allied nations with restricted payload budgets through specialized platform architectures optimized for lighter mission equipment. The country's defense export licensing framework accommodates foreign military sales preparation under International Traffic in Arms Regulations alignment. Israel Aerospace Industries and Elbit Systems anchor production clusters around Tel Aviv with Hermes-family derivatives serving NATO and non-NATO customers.
Turkey
Indigenous platform development accelerated following technology transfer restrictions from traditional suppliers, creating vertically integrated domestic supply chains for tactical strike systems. The country's defense procurement agency prioritizes autonomous strike platforms for regional security operations under national industrial policy directives. Baykar Technologies exemplifies this trajectory from Ankara-based manufacturing facilities serving Middle Eastern and Central Asian export markets.
United Kingdom
Royal Air Force procurement concentrates on persistent surveillance integration with NATO collective capability targets, pooling development costs across allied national budgets. The UK Civil Aviation Authority enforces dual-use certification standards for platforms operating in shared airspace with civilian traffic. BAE Systems and Leonardo UK coordinate subsystem integration from Lancashire and Yeovil production sites for Protector RG1 platform deliveries.
Germany
Bundeswehr acquisition timelines for armed unmanned systems remain constrained by parliamentary oversight requirements and lethal autonomy governance debates. The country's national aviation regulator applies European Union Aviation Safety Agency drone regulatory framework for civil-military dual-use certification. Rheinmetall and Airbus Defence and Space maintain development activities in Bavaria and Hamburg for platform-agnostic payload compatibility under open architecture standards.
Combat Drone Market Competitive Landscape
Integrated composite manufacturing dominates the current landscape as manufacturers reduce airframe weight by thirty percent on medium-altitude platforms without engine upgrades. The vendor base concentrates around defense primes with captive supply chains shielded from foreign component competition through International Traffic in Arms Regulations compliance requirements. Three strategic archetypes define competitive positioning: vertically integrated airframe-sensor providers, platform-agnostic system integrators, and specialized export-market optimizers. M&A activity and strategic partnerships represent the dominant competitive moves as contractors seek algorithmic capability access outside traditional aerospace labor pools.
Within the vertically integrated tier, General Atomics Aeronautical Systems exemplifies cost control through in-house composite fabrication for Reaper platform lines. Northrop Grumman Corporation occupies a position among high-altitude specialists with all-composite Global Hawk derivatives. Elbit Systems represents the export-market optimization archetype through Hermes-family architectures serving allied nations with lighter payload requirements. These three anchors illustrate how competitive positioning fragments across mission endurance requirements and customer regulatory constraints rather than consolidating around uniform platform specifications.
| Leading Market Players |
|---|
| General Atomics Aeronautical Systems |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| Israel Aerospace Industries Ltd. |
| Elbit Systems |
| Baykar Technologies |
| Lockheed Martin |
| Teledyne FLIR LLC. |
| Leonardo |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ITAR-compliant platforms and civil-military dual-use systems splits pricing power across divergent supply chain configurations. Manufacturers serving United States Department of Defense programs command premiums through captive composite fabrication and restricted component sourcing, while export-optimized architectures compete on simplified maintenance economics and lighter payload integration.
Pricing Analysis
Carbon fiber composite input costs pass through directly to platform pricing, with integrated manufacturers capturing margin advantage over outsourced airframe suppliers. Three-tier pricing structure across ITAR-restricted, NATO-approved, and civil-export platforms reflects certification complexity and end-use constraints. Pricing pressure stems from semiconductor supply concentration forcing premium sourcing for radiation-hardened flight processors. Defense contractors show lowest price sensitivity due to program-of-record funding, while security forces in emerging markets prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
ITAR qualification gates restrict component sourcing to approved domestic and allied-nation suppliers, fragmenting supplier bases across certification tiers. Manufacturing concentrates in the United States, Israel, and Turkey, each with distinct regulatory alignment and export licensing frameworks. Supply chains draw from specialized carbon fiber prepregs, radiation-hardened semiconductors, and precision-guided munitions subsystems. Single-source vulnerability concentrates in flight processor foundries. Distribution runs through prime contractor direct sales for military programs and government-to-government foreign military sales channels for allied nations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FAA-EASA divergence and evolving United Nations autonomous weapons governance create sustained demand for compliance-specialized engineering services and dual-certification platform architectures.
For Market Incumbents: Acquire machine vision and sensor fusion talent pools outside traditional aerospace labor markets to offset autonomous systems engineering scarcity. Lock in long-term carbon fiber supply agreements before capacity constraints intensify. Counter emerging Turkish and Israeli export competitors by embedding open architecture standards that complicate their closed-system alternatives. For New Entrants and Emerging Players: Enter via urban close-air support rotary-wing configurations where fixed-wing procurement saturation leaves white space. Target security forces in Southeast Asia and Middle Eastern nations lacking runway infrastructure for vertical takeoff platforms. Pursue civil-military dual-use certification from inception to access government agency budgets outside defense ministry silos. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithmic autonomy specialists possessing exportable non-lethal recognition software. Long-term viability hinges on positioning ahead of manned-unmanned teaming architecture standardization. Monitor United Nations Convention on Certain Conventional Weapons deliberations as the critical inflection signal for autonomous strike investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Compliance Infrastructure Investment | Captive supply chain certification shields domestic manufacturers from foreign component competition under United States export controls. |
| Carbon Fiber Manufacturing Scale-Up | Integrated composite fabrication reduces airframe weight by thirty percent on medium-altitude platforms without engine upgrades. |
| Autonomous Navigation Algorithm Development | GPS-denied waypoint following enables operations in contested electromagnetic environments prioritized by NATO member states. |
| Manned-Unmanned Teaming Protocol Integration | Datalink architecture contracts open for specialists serving fighter wing command structures across allied air forces. |
| Dual-Use Certification Pathway Expansion | EASA civil-military framework compliance accesses government agency budgets for border security and maritime enforcement applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with program managers at United States Department of Defense acquisition offices, NATO defense procurement agency officials, composite manufacturing engineers, and flight autonomy algorithm developers with secondary validation. Secondary sources included Federal Aviation Administration airspace integration waivers, European Union Aviation Safety Agency drone regulatory framework documentation, International Traffic in Arms Regulations compliance filings, and Pentagon budget justification materials. Bottom-up platform shipment estimates and top-down defense expenditure allocation models were triangulated for convergence.
Segment-weighting approaches distributed value across fixed-wing, rotary-wing, and hybrid configurations proportional to endurance-adjusted procurement volumes. Technology segmentation incorporated artificial intelligence, autonomous navigation, remote control, signal intelligence, and surveillance systems tiers. End-user weighting reflected military forces, defense contractors, government agencies, and security forces budget allocations. CAGRs were derived from regression-adjusted procurement timelines and capability refresh cycles. Forecast inputs included NATO collective capability target commitments and national industrial policy directives from Turkey and Israel.
Inputs from Department of Defense program of record documentation and EASA certification registries were available through the study window; gaps in classified rapid acquisition pathway spending introduce uncertainty bands around autonomous systems investment estimates. Forecasts reflect assumptions regarding sustained United Nations deliberation timelines and stable ITAR framework continuity. A model refresh is warranted upon material change in lethal autonomy governance outcomes or FAA-EASA regulatory convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
GCC Drones Market
UAV
Drone-Based Consulting Services Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Middle-East and Africa Drones Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Drone-As-A-Service Market
UAV
Industrial Drones Market
UAV
Global Inspection Drones Market
UAV
Anti-Drone Technology Market
UAV
Global Electric Drone Market
UAV
North America Tactical UAV Market
UAV
UAV Market
UAV
Consumer Drone Market
UAV
Global Multirotor UAV Market
UAV
Rc Helicopter Market
UAV
Drone Tracking Antenna Market