
 Naval Missiles and Missile Launch Systems Market | 2026-2036
Naval Missiles and Missile Launch Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Missiles and Missile Launch Systems Market Foresight
Naval aerospace engineering talent scarcity is redrawing competitive boundaries across the sector. MBDA leverages pan-European consortium structures to sustain specialized workforce pipelines across France, Italy, and the United Kingdom. RTX Corporation anchors North American supply chains through captive manufacturing of solid-rocket motors and guidance electronics. Rafael Advanced Defense Systems differentiates via vertical integration into electro-optical seekers and active radar homing systems.
Naval missiles and missile launch systems comprise guided weapons and associated firing mechanisms designed for maritime deployment, typically featuring turbojet or ramjet propulsion, composite airframes, and inertial-GPS midcourse guidance with terminal active seekers. These systems enable surface combatants and submarines to engage aerial, surface, and land targets beyond visual range with precision standoff capability. Cruise missiles and anti-ship variants command the dominant product-type margin pools due to recurring replenishment cycles and complexity premiums. Launch platforms centered on destroyers and frigates represent the fastest-expanding category as navies prioritize distributed lethality over concentrated carrier strike groups. Smart munitions and launch control systems within the technology dimension attract disproportionate R&D allocation as operators demand network-enabled cooperative engagement.
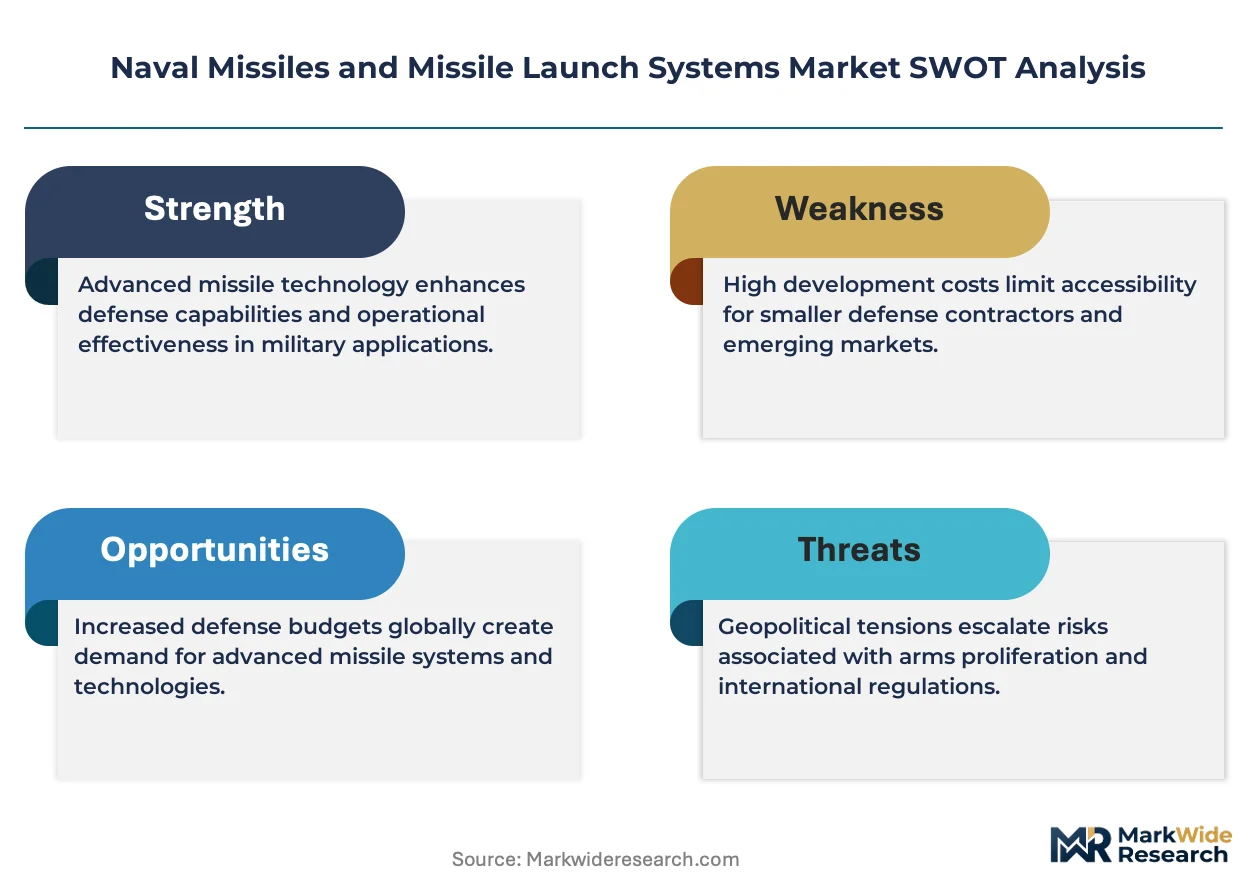
Export control regimes administered by the US Department of State through ITAR and the UK Strategic Export Control Group constrain technology transfer and shape alliance-specific procurement patterns. The EU Green Deal's emerging defense industrial requirements and Japan's Three Principles on Transfer of Defense Equipment further fragment market access rules. Stakeholders must monitor convergence between commercial space launch supply chains and naval propulsion component sourcing as dual-use competition intensifies for limited solid-fuel motor capacity.
Market Dynamics
Hypersonic propulsion testing is compressing development cycles across naval missile programs, forcing suppliers to reconfigure solid-fuel motor capacity and guidance electronics architectures ahead of platform integration deadlines.
Growth Catalysts
- ITAR modernization initiatives:The US Department of State is streamlining licensing timelines for allied fleet commonality, accelerating technology transfer to Australia and Japan under AUKUS and bilateral frameworks.
- Indo-Pacific distributed lethality doctrine:Surface combatant procurement is tilting toward smaller, missile-dense platforms rather than concentrated carrier groups, expanding launcher cell counts per hull.
- Network-enabled cooperative engagement:Integrated fire control architectures are linking sensors and shooters across dispersed formations, requiring interoperable launch control electronics and data links.
Market Restraints
- Solid-rocket motor capacity constraints:Commercial space launch demand is competing for limited ammonium perchlorate and composite case production, extending lead times for naval propulsion systems.
- UK Strategic Export Control Group licensing:British subsystem suppliers face multi-month approval cycles for seeker technology transfers, fragmenting pan-European supply coordination.
- Electro-optical seeker thermal limitations:Current focal plane array cooling systems restrict sustained hypersonic flight profiles, capping terminal engagement windows.
Strategic Opportunities
- Japan's Three Principles on Transfer of Defense Equipment relaxation:Tokyo is easing export restrictions on jointly developed systems, opening third-party sales channels for US-Japan collaborative programs.
- Unmanned surface vessel integration:Autonomous platforms under 500 tons are emerging as mobile missile magazines, demanding compact vertical launch systems and reduced-crew maintenance architectures.
- EU Green Deal defense industrial requirements:Emerging sustainability mandates are creating preference for reduced-toxicity propellant formulations and recyclable composite airframe materials.
Industry Challenges
- Aerospace engineering talent scarcity:Specialized workforce pipelines in ramjet combustion and inertial navigation are contracting across France, Italy, and the United Kingdom, forcing consortium structures to cross-train across national boundaries.
- Legacy platform integration complexity:Newer network-enabled launch control systems must interface with 1980s-era combat management architectures aboard upgraded destroyers, requiring costly middleware development and certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Missiles and Missile Launch Systems Market |
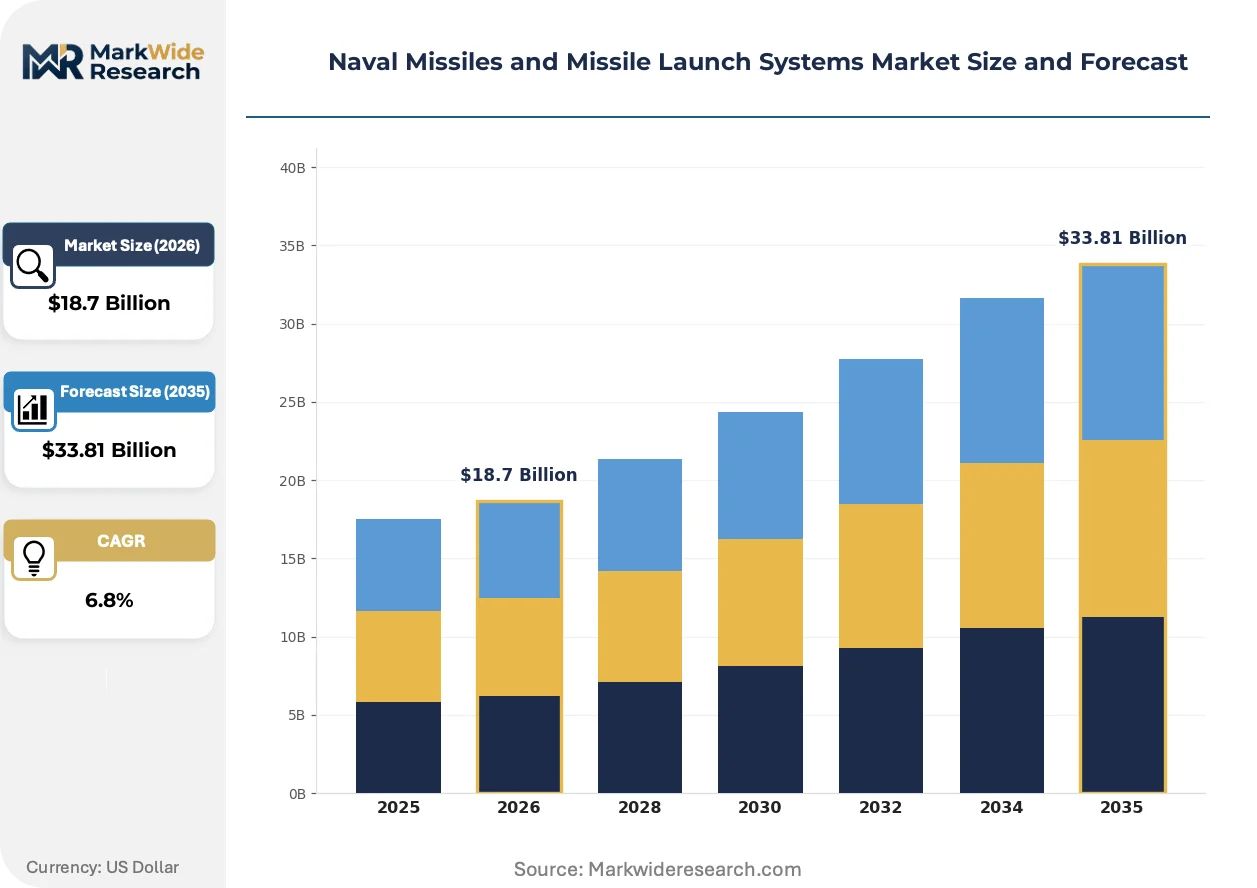
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface-to-Surface, Surface-to-Air, Anti-Ship, Cruise Missiles Launch Platform: Submarines, Destroyers, Aircraft Carriers, Frigates Technology: Guided Missiles, Unmanned Systems, Smart Munitions, Launch Control Systems End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions |
| Companies Covered | MBDA, Kongsberg Gruppen ASA, Lockheed Martin Corporation, Rafael Advanced Defense Systems Ltd., Saab AB, RTX Corporation, Elbit Systems Ltd., Israel Aerospace Industries Ltd., BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Missiles and Missile Launch Systems Market Shifts & Advancements
Ramjet propulsion architectures are overtaking turbojet dominance in next-generation anti-ship programs, while regulatory frameworks and procurement models are simultaneously restructuring how capabilities reach operational fleets.
Scramjet and dual-mode ramjet technologies are achieving sustained combustion above Mach 5 for extended sea-skimming profiles. Surface combatant operators in the United States and Japan are prioritizing these systems for area-denial missions against maneuvering targets. Conventional turbojet-powered cruise missiles are supplanting older subsonic designs in replenishment contracts, compressing the operational relevance of legacy propulsion categories.
The EU Green Deal's emerging defense industrial requirements are mandating lifecycle carbon accounting for munitions production and propellant formulation transparency. European prime contractors are reformulating solid-fuel recipes and airframe resin systems to satisfy anticipated sustainability scoring in competitive tenders. Naval missile programs with substantial European subsystem content face the most acute compliance pressure, driving joint Franco-Italian research into reduced-toxicity oxidizers.
Fleet operators are consolidating procurement authority into centralized defense materiel agencies rather than service-specific acquisition commands. The United Kingdom's Defence Equipment and Support organization and Japan's Acquisition, Technology and Logistics Agency are aggregating multi-year requirements for common launch systems and missile families. This concentration is compressing supplier negotiation leverage and favoring platform-agnostic weapon designs with broader interoperability credentials.
Naval Missiles and Missile Launch Systems Market Segmentation
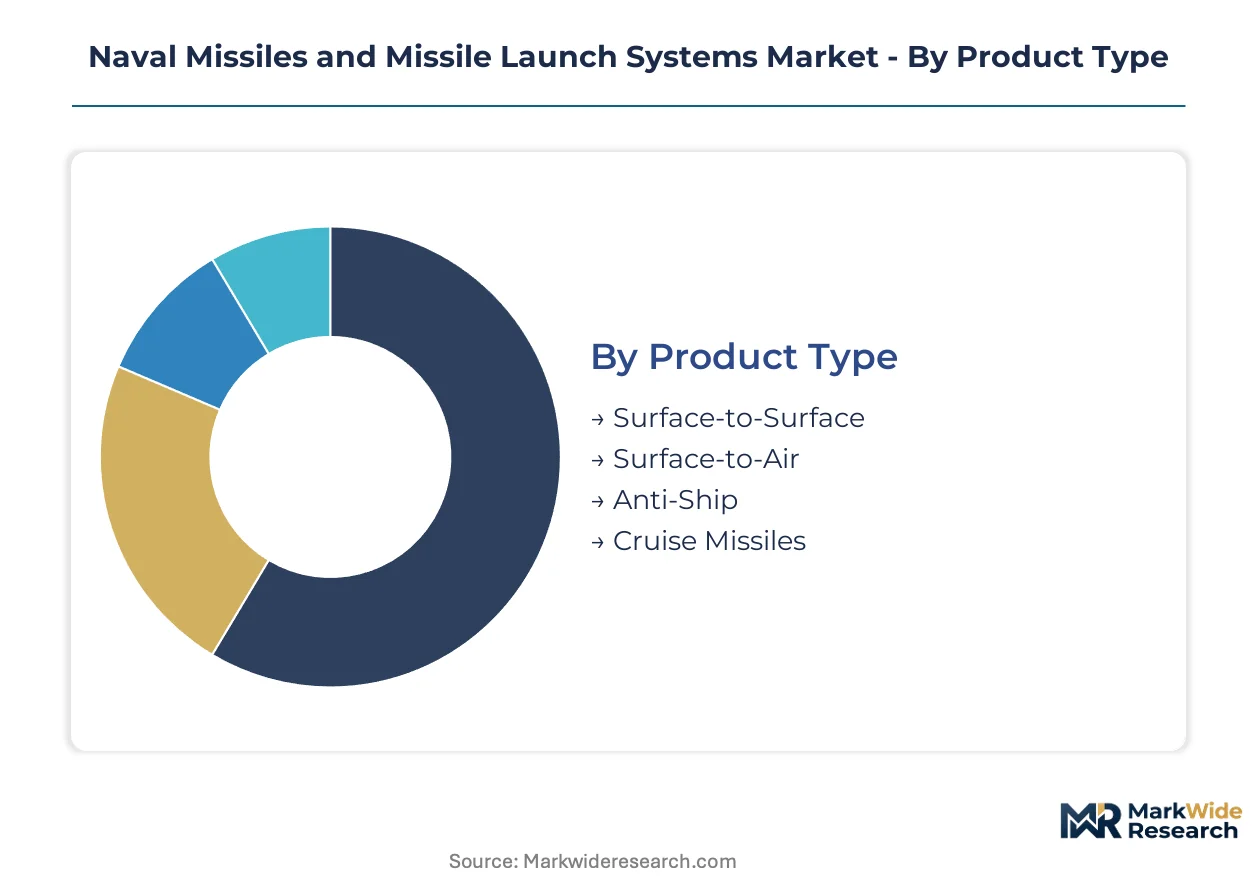
Segmentation in naval missiles and missile launch systems reveals how procurement authority, platform modernization cycles, and technology maturity create divergent growth trajectories across product categories. Understanding these divisions exposes where defense budgets concentrate and where emerging capabilities are displacing legacy systems.
Product Type:
Export licensing intensity varies sharply across this category, with cruise missiles and anti-ship variants facing stricter ITAR controls than surface-to-air systems.
- Surface-to-Surface:These ballistic and guided weapons deliver precision strikes against land-based targets from maritime platforms. Demand concentrates in the United States and Japan as both nations prioritize distributed maritime strike for island-chain defense scenarios, though solid-rocket motor shortages are extending procurement timelines.
- Surface-to-Air:Naval area-defense interceptors feature active radar homing and vertical-launch cold-start capability. Procurement runs heaviest through destroyer upgrade programs, where legacy combat management system integration complexity is inflating middleware development costs for contractors.
- Anti-Ship:Sea-skimming and terminal-maneuvering variants with ramjet propulsion.
- Cruise Missiles:Subsonic and supersonic turbojet-powered standoff weapons.
Cruise missiles command the established base. The steepest expansion runs through anti-ship variants as ramjet architectures displace older propulsion categories.
Launch Platform:
Platform selection directly determines launcher cell density, crew requirements, and network integration complexity for missile control architectures.
- Destroyers:These 8,000-10,000 ton combatants carry 90-122 vertical launch cells and integrated fire control for multi-domain engagement. Procurement is accelerating fastest in Japan and the United Kingdom as both navies shift from carrier-centric to distributed lethality force structures, expanding missile magazines across more hulls.
- Frigates:Medium-displacement surface combatants with 16-48 cell vertical launch capacity. Demand is climbing in the United Kingdom and Italy under pan-European consortium arrangements, where cost-per-hull constraints favor smaller, missile-dense platforms over concentrated capital ship investment.
- Submarines:Stealth launch platforms with torpedo tube or vertical launch capability.
- Aircraft Carriers:Strike group centers with defensive missile loadouts.
Destroyers anchor the revenue base. Frigates are gaining share fastest as procurement tilts toward smaller, distributed platforms.
Technology:
R&D allocation intensity separates this category, with smart munitions and launch control systems capturing disproportionate investment versus mature guided missile architectures.
- Smart Munitions:Network-enabled weapons with cooperative engagement and in-flight retargeting capability. Development concentrates in the United States and United Kingdom under AUKUS technology sharing frameworks, where ITAR modernization is accelerating seeker and data link transfers to allied production lines.
- Launch Control Systems:Integrated fire control electronics linking sensors, decision aids, and vertical launch cells. Procurement is expanding across Indo-Pacific fleets as operators demand interoperability between US, British, and Japanese combat management architectures.
- Guided Missiles:Established inertial-GPS midcourse guidance with terminal active seekers.
- Unmanned Systems:Autonomous platforms with embedded missile magazines.
Guided missiles represent the established volume base. Launch control systems are climbing fastest as network-enabled cooperative engagement mandates proliferate.
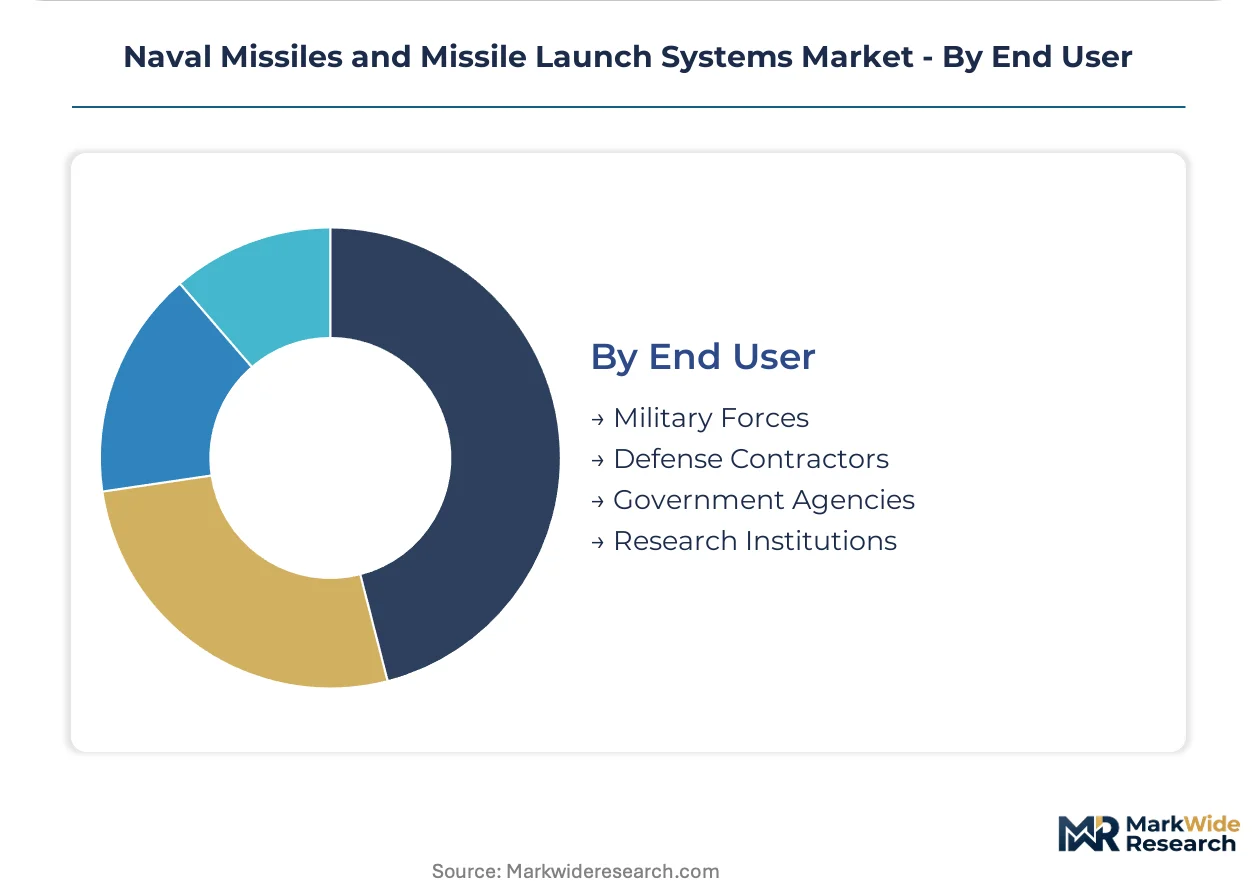
End User:
Procurement authority concentration is restructuring this category, with centralized defense materiel agencies displacing service-specific acquisition commands.
- Military Forces:Operational fleet operators including surface fleets and submarine commands. Requirements aggregation is tightening in Japan through the Acquisition, Technology and Logistics Agency and in the United Kingdom through Defence Equipment and Support, compressing supplier leverage for multi-year missile family contracts.
- Defense Contractors:Prime and subsystem manufacturers with captive production of solid-rocket motors and guidance electronics. Supply chain positioning is intensifying in the United States as RTX Corporation and others anchor North American propulsion capacity against commercial space launch competition.
- Government Agencies:Defense ministries and export control administrations.
- Research Institutions:National laboratories and university-affiliated test centers.
Military forces anchor the demand base. Defense contractors are expanding most quickly as production consolidation and supply chain captive strategies accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of State administers ITAR licensing frameworks that shape procurement patterns across allied fleets. Naval modernization programs concentrate demand in specific national markets where distributed maritime strike capabilities drive platform investment.
United States
AUKUS technology sharing frameworks and ITAR modernization initiatives accelerate missile system transfers to Australia and Japan. The Department of State streamlines licensing timelines for allied fleet commonality. RTX Corporation anchors North American supply chains through captive manufacturing clusters in Arizona and Massachusetts.
United Kingdom
Defence Equipment and Support aggregates multi-year requirements for common launch systems and missile families. The UK Strategic Export Control Group administers multi-month approval cycles for seeker technology transfers. MBDA leverages pan-European consortium structures across Bristol and Stevenage facilities to sustain specialized workforce pipelines.
Japan
The Acquisition, Technology and Logistics Agency centralizes procurement authority for surface combatant modernization. Tokyo's relaxation of the Three Principles on Transfer of Defense Equipment opens third-party sales channels for US-Japan collaborative programs. Mitsubishi Heavy Industries clusters production around Nagasaki and Kobe shipyards for vertical launch system integration.
France
Franco-Italian research partnerships advance reduced-toxicity oxidizer formulations under anticipated EU Green Deal compliance pressure. The Directorate General of Armament coordinates naval missile procurement through MBDA's Saint-Cloud headquarters. Toulouse and Le Plessis-Robinson host electro-optical seeker development centers for ramjet propulsion architectures.
Italy
Pan-European consortium arrangements with France drive frigate procurement under cost-per-hull constraints favoring missile-dense platforms. Leonardo S.p.A. concentrates launch control electronics manufacturing in Rome and La Spezia. The Ministry of Defense integrates network-enabled cooperative engagement mandates across upgraded destroyer programs.
Naval Missiles and Missile Launch Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around propulsion system captivity and seeker technology differentiation. Prime contractors compete through backward integration into solid-rocket motors and guidance electronics rather than subsystem outsourcing. Strategic archetypes include pan-European consortium entities, North American integrated suppliers, and Israeli vertically specialized defense groups. Competitive moves center on capacity expansion in ammonium perchlorate production and strategic partnerships for network-enabled fire control architectures.
Within the integrated tier, MBDA exemplifies pan-European consortium coordination across national boundaries. RTX Corporation anchors North American supply positioning against commercial space launch competition. Rafael Advanced Defense Systems Ltd. occupies a specialist position in electro-optical and active radar homing system architectures.
| Leading Market Players |
|---|
| MBDA |
| Kongsberg Gruppen ASA |
| Lockheed Martin Corporation |
| Rafael Advanced Defense Systems Ltd. |
| Saab AB |
| RTX Corporation |
| Elbit Systems Ltd. |
| Israel Aerospace Industries Ltd. |
| BAE Systems plc |
| Others |
Supply & Pricing Matrix
ITAR licensing frameworks administered by the US Department of State simultaneously gate supplier qualification and stratify price tiers across allied procurement channels. Nations with streamlined bilateral agreements access seeker technology and solid-rocket motors at preferential rates, while restricted markets face cost premiums and extended delivery timelines. This regulatory moat reinforces pricing power for qualified primes while compressing margins for second-tier subsystem vendors competing on technical differentiation alone.
Pricing Analysis
Trans-Atlantic price spreads of 15-25 percent separate US-Japan collaborative programs from pan-European consortium offerings for equivalent ramjet propulsion architectures. Three-tier pricing structure across ITAR-compliant, NATO-restricted, and third-party export tiers reflects certification burden and end-use monitoring costs. Cost compression in seeker electronics is intensifying because commercial focal plane array production is scaling faster than defense-specific demand. National navies with centralized defense materiel agencies exhibit lowest price sensitivity, while emerging fleet operators in Southeast Asia negotiate hardest on per-unit procurement.
Supply Chain Analysis
Strategic stockpiling of ammonium perchlorate and composite case materials dominates inventory strategy as commercial space launch demand competes for limited solid-fuel motor capacity. Supply concentrates in the United States, France, and Japan for guidance electronics; solid-rocket propulsion draws from Arizona, Massachusetts, and Saint-Cloud production clusters. Raw material dependencies center on high-purity ammonium perchlorate, carbon-fiber prepregs, and rare-earth magnet alloys for inertial navigation systems. Single-source vulnerability in electro-optical seeker cooling systems poses acute disruption risk. Distribution runs through prime contractor captive manufacturing networks rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Naval missile programs sit in early-cycle expansion as distributed lethality doctrine accelerates launcher cell counts per hull across Indo-Pacific fleets. Ramjet propulsion maturation and network-enabled cooperative engagement mandates are creating fresh demand arcs for integrated fire control architectures.
For Market Incumbents: Fortify captive production of solid-rocket motors and guidance electronics against commercial space launch competition for limited propellant capacity. Deepen backward integration into ammonium perchlorate synthesis and composite case winding to defend margin position as second-tier suppliers consolidate. Prioritize certification investment for ITAR-modernized licensing pathways to maintain access preference in Australian and Japanese procurement channels.
For New Entrants and Emerging Players: Anchor in unmanned surface vessel integration as the most penetrable white-space segment, where compact vertical launch systems and reduced-crew maintenance architectures lack established supplier relationships. Target smart munitions and launch control electronics subsystems where R&D allocation intensity runs highest and prime contractor outsourcing pressure is mounting. Pursue joint development frameworks with Japanese or Australian system integrators to bypass ITAR direct-licensing barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hypersonic propulsion testing and integrated launch control architectures as development cycles compress. Long-term viability favors primes with demonstrated ramjet combustion expertise and electro-optical seeker vertical integration. The acquisition target archetype is mid-tier subsystem specialists with qualified solid-rocket motor capacity or focal plane array cooling technology. Watch for relaxation of Japan's Three Principles on Transfer of Defense Equipment as the signal indicating third-party sales channel opening and revenue multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solid-Rocket Motor Production | RTX Corporation's Arizona manufacturing cluster secures propulsion capacity against commercial space launch competition. |
| Network-Enabled Cooperative Engagement Certification | MBDA's pan-European consortium structures qualify for AUKUS technology sharing frameworks and allied fleet commonality. |
| Reduced-Toxicity Propellant Formulation Development | Franco-Italian research partnerships anticipate EU Green Deal compliance scoring in competitive tenders. |
| Unmanned Surface Vessel Launch System Miniaturization | Compact vertical launch architectures address emerging demand from autonomous platforms under 500 tons displacement. |
| Electro-Optical Seeker Thermal Management Advancement | Focal plane array cooling system improvements extend terminal engagement windows for sustained hypersonic flight profiles. |
Research Methodology
A spread of perspectives from naval program executives, defense procurement officers, solid-rocket motor plant managers, guidance electronics R&D directors, and export control administrators converged on the working assumptions. Primary fieldwork combined structured interviews with subsystem suppliers and fleet operators across the United States, United Kingdom, Japan, and France. Secondary validation drew from Department of State ITAR licensing disclosures, UK Strategic Export Control Group approval records, Japan Acquisition Technology and Logistics Agency procurement bulletins, and EU Green Deal defense industrial requirement drafts. Bottom-up demand aggregation across launch platform modernization cycles was triangulated against top-down defense budget allocation analysis.
Segmentation dimensions modeled include product type, launch platform class, technology maturity tier, and end-user procurement authority structure across the projection horizon. CAGRs were derived from weighted scenario analysis of fleet modernization timelines and replenishment cycle phasing. Hypersonic propulsion testing schedules, network-enabled fire control architecture deployment mandates, and solid-rocket motor capacity constraints served as industry-specific forecast inputs. Volume and value outputs reflect convergence of platform-level procurement forecasts with subsystem bill-of-materials decomposition.
Decision-makers should treat outputs as directional under assumptions of sustained Indo-Pacific distributed lethality doctrine adoption and ITAR modernization timeline execution; material deviation would warrant model refresh. Forecasts incorporate assumptions regarding allied technology transfer framework stability and commercial space launch demand trajectories. Revision becomes warranted when solid-rocket motor capacity constraints or electro-optical seeker thermal limitations cross operational deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Combat Management System Market
Naval Warfare
Military Frigate Market