
 Submarine Combat System Market | 2026-2036
Submarine Combat System Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Combat System Market Analysis
Asia-Pacific submarine fleet expansion is fragmenting procurement patterns across multiple national programs. Northrop Grumman Corporation leverages its sonar processing heritage to anchor US Navy integrated combat system contracts. Thales Group sustains European market presence through France's Barracuda-class program and export naval packages. Lockheed Martin Corporation dominates US combat system integration with the AN/BYG-1 combat control architecture.
A submarine combat system integrates sonar arrays, weapon launchers, communications suites, and command-control modules into a unified undersea warfare platform, typically operating at depths exceeding 800 feet while processing multi-sensor tracks in real time. Sonar Systems and Control Systems segments capture the largest share of program value due to extended development cycles and classified signal-processing requirements. AI-Based Analytics within the Technology dimension is expanding fastest as navies automate threat classification and reduce operator cognitive load during prolonged submerged patrols.
The US Navy's Naval Sea Systems Command sets combat system technical specifications through the AN/BYG-1 program office, while NATO's Maritime Strategy for the North Atlantic area standardizes interoperability protocols across allied submarine forces. The UK's Defence Equipment and Support organization and France's Direction Générale de l'Armement enforce national security certification requirements that constrain vendor eligibility. Procurement officers must weigh sovereign capability mandates against the cost advantages of transnational subsystem integration.
Market Dynamics
Networked undersea warfare doctrine is compressing procurement cycles as navies abandon siloed sensor suites in favor of open-architecture combat systems that integrate third-party modules through standardized middleware interfaces.
Growth Catalysts
- US Navy Fleet Modernization:Columbia-class ballistic missile submarine procurement is driving demand for integrated combat control suites with extended service-life requirements.
- NATO Interoperability Mandates:Allied submarine forces must achieve seamless data exchange under Maritime Strategy for the North Atlantic protocols, forcing combat system standardization.
- AI-Based Threat Classification:Machine-learning algorithms embedded in sonar processing chains are reducing operator workload during prolonged submerged patrols.
Market Restraints
- Classified Signal-Processing Expertise:Sovereign security certification requirements in France, the United Kingdom, and the United States restrict vendor eligibility to domestic or cleared contractors.
- Titanium Alloy Supply Concentration:Pressure hull and sonar dome fabrication depends on specialized metallurgical suppliers concentrated in Russia and China, creating input vulnerability.
- Extended Development Cycles:Combat system integration programs span 8-14 years from concept to fleet deployment, locking capital and obsolescing mid-cycle technology insertions.
Strategic Opportunities
- Australian AUKUS Submarine Program:Nuclear-powered submarine acquisition creates demand for combat system transfer and indigenous integration capability building.
- Undersea Infrastructure Protection:Seabed cable and energy pipeline security missions are expanding submarine operational portfolios beyond traditional anti-submarine warfare.
- Unmanned Underwater Vehicle Integration:Convergence of crewed submarine command nodes with autonomous sensor platforms enables distributed kill chains without platform concentration.
Industry Challenges
- Cleared Workforce Scarcity:Combat system engineering requires personnel holding top-secret security clearances, constraining program staffing across US, UK, and French suppliers.
- Legacy System Architecture Integration:Existing Los Angeles-class and Astute-class submarines operate proprietary combat control systems that resist modular upgrade paths.
- Multi-National Certification Timelines:Joint development programs must satisfy concurrent review by Naval Sea Systems Command, Defence Equipment and Support, and Direction Générale de l'Armement, extending qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Combat System Market |
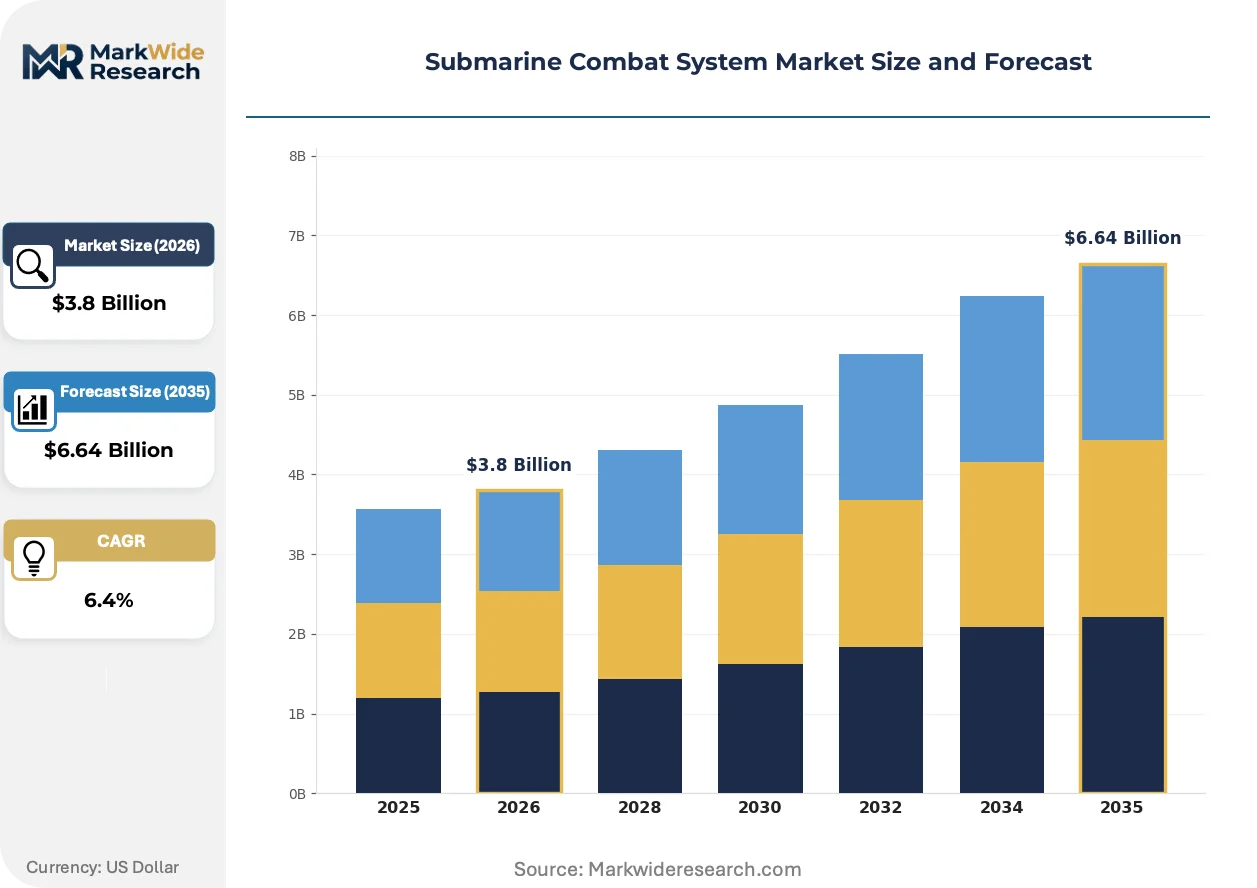
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Sonar Systems, Weaponry, Communication Equipment, Control Systems Application: Offensive Operations, Defensive Strategies, Intelligence Gathering, Surveillance Missions End User: Navies, Defense Contractors, Government Agencies, Research Institutions Technology: Electro-Optical Systems, Automated Targeting, AI-Based Analytics, Acoustic Sensors |
| Companies Covered | Northrop Grumman Corporation, Thales Group, Raytheon Technologies Corporation, Mitsubishi Heavy Industries Ltd., L3Harris Technologies Inc., Lockheed Martin Corporation, BAE Systems Plc., Huntington Ingalls Industries Inc., General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Combat System Market Emerging Trajectories
Active sonar processing and command-control software architectures are undergoing accelerated refresh cycles as commercial computing advances outpace traditional 15-year military acquisition timelines.
Photonic mast sensor suites are collapsing the distinction between periscope-dependent optical surveillance and integrated multi-spectrum detection. The US Navy's Virginia-class block upgrades are fielding these systems at 2-year intervals rather than platform mid-life. This compression is collapsing supplier business models built around decades-long production runs.
EU defense procurement directives are mandating cross-border industrial participation in major naval programs. France's Direction Générale de l'Armement now requires Barracuda-class combat system subcontractors to maintain dual-use facilities across at least two member states. European suppliers are consolidating engineering presence in Belgium and the Netherlands to satisfy these rules.
Naval procurement officers are bundling combat system sustainment into 25-year availability contracts rather than discrete capital purchases. Australia's AUKUS submarine negotiations embed through-life support obligations that transfer operational risk to prime contractors. This restructuring is most advanced in Pacific Rim programs where crewed submarine numbers are insufficient to justify organic maintenance infrastructure.
Submarine Combat System Market Segmentation
Submarine combat system procurement fragments across mission profiles, platform generations, and sovereign security requirements. Each segment carries distinct certification barriers and technology refresh cycles that reshape vendor competitive positioning.
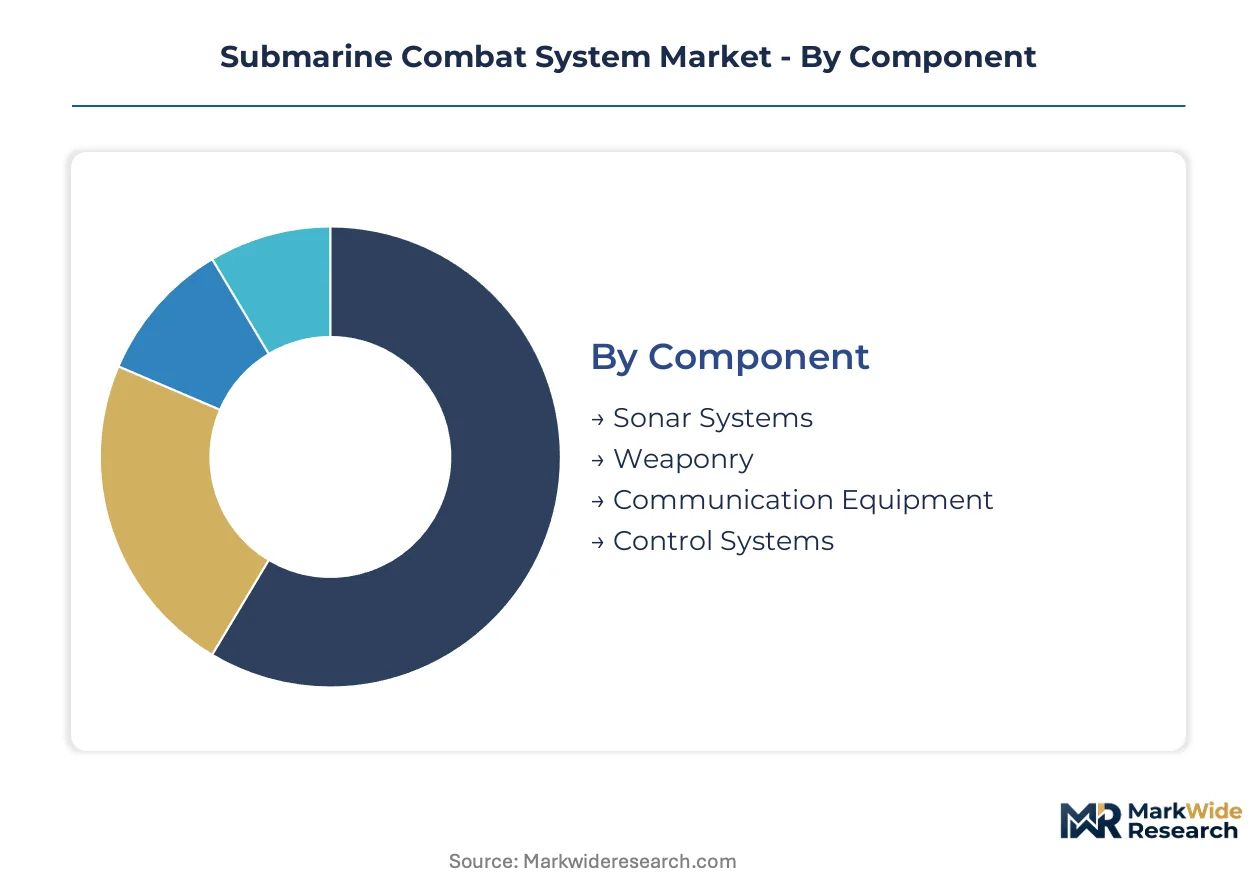
Component:
Naval architects configure combat suites around threat spectra ranging from deep-water anti-submarine warfare to littoral intelligence collection.
- Sonar Systems:Hull-mounted and towed arrays process acoustic signatures through classified algorithms optimized for specific oceanographic conditions. US Navy Virginia-class and Columbia-class programs concentrate demand for broadband digital sonar processing, driven by undersea warfare doctrine shifts toward networked distributed operations.
- Control Systems:Command-and-control architectures integrate sensor fusion, weapon assignment, and communications management into unified combat management platforms. Extended development cycles spanning 8-14 years lock capital and complicate mid-cycle technology insertions, constraining procurement flexibility.
- Weaponry:Torpedo launch systems and vertical payload modules interface with combat control software through standardized middleware.
- Communication Equipment:Very low frequency and satellite uplink systems enable submerged connectivity with national command authorities.
Established volume favors Sonar Systems; emerging adoption favors Control Systems.
Application:
Mission type dictates sensor prioritization, crew complement, and platform endurance requirements.
- Offensive Operations:Anti-submarine and anti-surface warfare missions demand active sonar prosecution capabilities and rapid weapon engagement timelines. NATO Maritime Strategy for the North Atlantic standardization protocols are compressing procurement cycles as allied forces abandon siloed sensor suites.
- Intelligence Gathering:Signals intelligence and acoustic signature collection require passive sensor optimization and extended loiter endurance. Asia-Pacific submarine fleet expansion across multiple national programs is fragmenting procurement patterns for specialized intelligence-configured platforms.
- Defensive Strategies:Area denial and escort protection missions emphasize threat detection radius and coordinated engagement.
- Surveillance Missions:Seabed infrastructure protection and chokepoint monitoring expand operational portfolios beyond traditional warfare roles.
Procurement concentration clusters in Offensive Operations; steepest expansion trajectory appears in Surveillance Missions.
End User:
Contracting authority shapes technical specifications, security clearance requirements, and sustainment liability allocation.
- Navies:Fleet operators define operational requirements and maintain through-life support infrastructure. US Naval Sea Systems Command, UK Defence Equipment and Support, and France's Direction Générale de l'Armement enforce national security certification requirements that constrain vendor eligibility to domestic or cleared contractors.
- Defense Contractors:Prime integrators assume availability risk under 25-year sustainment contracts transferring operational liability from navies. Australian AUKUS submarine negotiations embed through-life support obligations that accelerate this restructuring.
- Government Agencies:National intelligence services commission specialized platforms for covert collection missions.
- Research Institutions:Academic and government laboratories prototype next-generation acoustic processing and autonomous system integration.
Contractual risk transfer favors Defense Contractors; capability sovereignty mandates favor Navies.
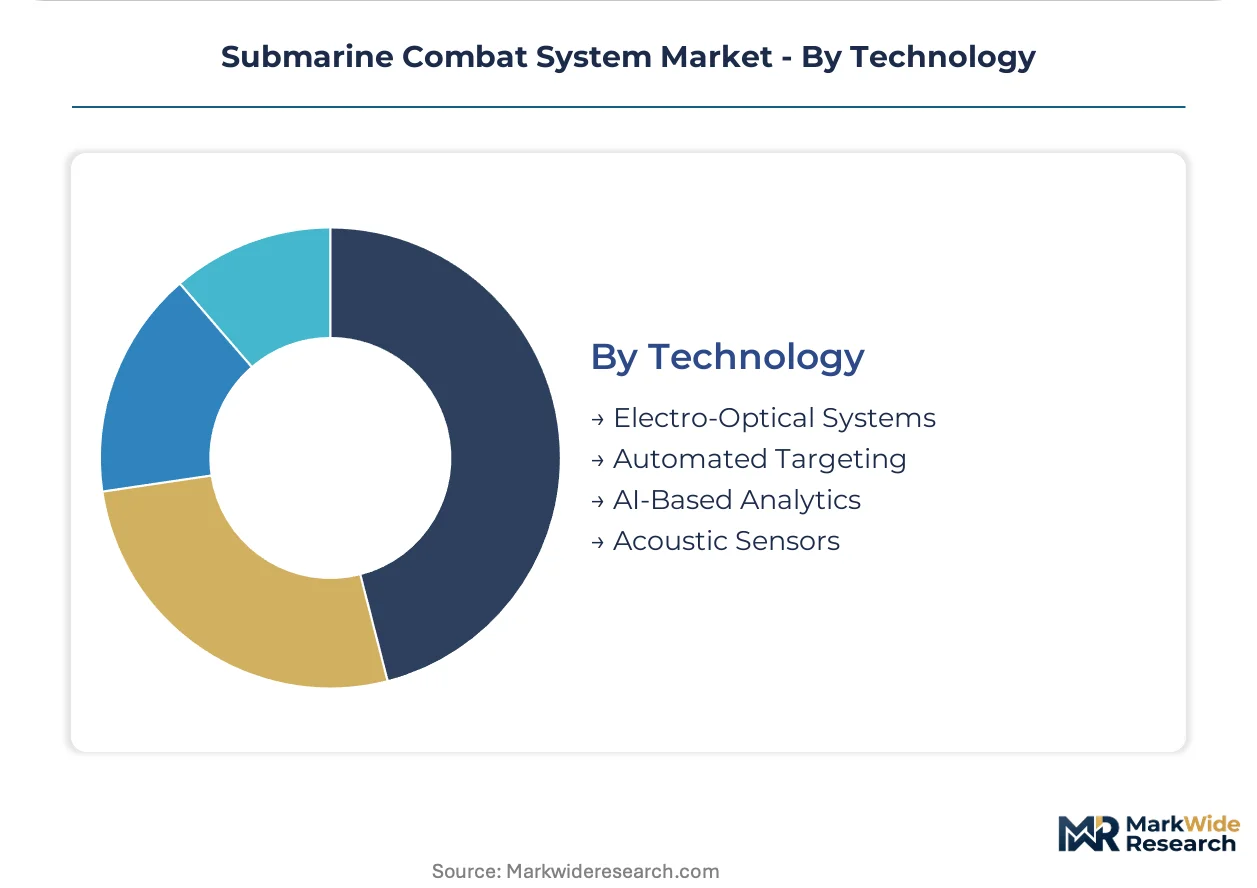
Technology:
Processing architecture determines threat classification speed and operator cognitive load during prolonged submerged patrols.
- AI-Based Analytics:Machine-learning algorithms embedded in sonar processing chains automate threat classification and reduce operator workload. US Navy Virginia-class block upgrades field photonic mast and processing enhancements at 2-year intervals, collapsing supplier business models built around decades-long production runs.
- Acoustic Sensors:Piezoelectric and fiber-optic hydrophone arrays form the foundational detection layer for all undersea warfare platforms. Titanium alloy supply concentration in Russia and China creates input vulnerability for pressure hull and sonar dome fabrication.
- Electro-Optical Systems:Photonic mast sensor suites replace periscope-dependent optical surveillance with integrated multi-spectrum detection.
- Automated Targeting:Fire control automation compresses sensor-to-shooter timelines for torpedo and missile engagement.
Integration complexity constrains Acoustic Sensors; capability investment flows fastest into AI-Based Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval Sea Systems Command specifications anchor procurement volumes in the United States, while sovereign security certification requirements in France and the United Kingdom constrain vendor eligibility to domestic or cleared contractors across NATO submarine programs.
United States
Virginia-class and Columbia-class submarine programs concentrate demand for integrated combat control suites with extended service-life requirements. Naval Sea Systems Command sets combat system technical specifications through the AN/BYG-1 program office. Connecticut-based submarine builders and Virginia-class construction facilities in Rhode Island anchor fleet modernization supply chains.
France
Barracuda-class nuclear attack submarine procurement drives combat system integration requirements with sovereign capability mandates. Direction Générale de l'Armement enforces national security certification requirements that restrict vendor eligibility to domestic or cleared European contractors. Naval Group facilities in Cherbourg and Toulon cluster pressure hull fabrication with combat system integration.
United Kingdom
Astute-class successor programs and Dreadnought-class ballistic missile submarine procurement sustain combat system demand. Defence Equipment and Support organization mandates security clearance requirements constraining subsystem vendor selection. Barrow-in-Furness shipyard complexes in Cumbria concentrate nuclear submarine construction with integrated combat suite installation.
Australia
AUKUS nuclear-powered submarine acquisition creates demand for combat system transfer and indigenous integration capability building. Australian Department of Defence embeds through-life support obligations transferring operational risk to prime contractors. Osborne naval shipyard in South Australia anchors planned nuclear submarine construction infrastructure.
Japan
Taigei-class diesel-electric submarine expansion sustains combat system procurement with emphasis on lithium-ion battery integration and enhanced sonar processing. Ministry of Defense acquisition programs prioritize domestic industrial participation with licensed foreign technology transfer. Mitsubishi Heavy Industries and Kawasaki Heavy Industries facilities in Kobe and Yokohama cluster submarine construction with combat system integration.
Submarine Combat System Market Vendor Landscape
Defense prime integrators and sovereign national champions split the market into consolidated supply relationships with limited vendor rotation. Tier-1 system integrators assume availability risk under multi-decade sustainment contracts while specialized subsystem suppliers maintain positions in sonar processing and combat control software. Strategic archetypes include full-spectrum combat system integrators, sovereign national champions with domestic mandate protection, and specialized sensor processing houses. Competitive dynamics center on 25-year through-life support contract capture and security clearance infrastructure maintenance.
Within the full-spectrum integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent archetypal positions anchored by AN/BYG-1 combat control architecture and sonar processing heritage respectively. Thales Group occupies a position exemplifying European sovereign champion strategy through France's Barracuda-class program and export naval packages. BAE Systems Plc. anchors UK-centric supply relationships constrained by Defence Equipment and Support security certification requirements.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thales Group |
| Raytheon Technologies Corporation |
| Mitsubishi Heavy Industries Ltd. |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| BAE Systems Plc. |
| Huntington Ingalls Industries Inc. |
| General Dynamics Corporation |
| Others |
Supply Flow & Price Mechanics
Titanium alloy supply concentration in Russia and China feeds directly into margin capture at pressure hull fabrication and sonar dome manufacturing tiers, where sovereign security mandates prevent supplier switching and lock pricing power with cleared metallurgical vendors.
Pricing Analysis
Geographic price spreads between US, UK, and French combat system procurement run wide due to divergent security clearance infrastructure costs and sovereign capability mandates. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade, with AN/BYG-1 integrated architectures commanding premium positioning against modular retrofit packages. Cost compression in mid-tier sonar processing subsystems is intensifying because commercial computing advances outpace military acquisition timelines. Defense contractors with 25-year availability contracts show least price sensitivity; research institutions and export customers without domestic integration mandates exhibit highest.
Supply Chain Analysis
Tariff exposure between NATO member states and Russian titanium suppliers dominates supply chain risk matrices for pressure hull fabrication. Manufacturing gravity centers on the United States, France, and the United Kingdom for classified combat system integration, with Japan and Australia building secondary clusters through licensed technology transfer. Raw material dependencies rest on titanium sponge, high-grade steel alloys, and specialized piezoelectric ceramics for sonar arrays. Single-source vulnerability persists in photonic mast sensor suites where cleared vendor pools remain shallow. Distribution runs through naval procurement authorities rather than open commercial channels, with Naval Sea Systems Command, Defence Equipment and Support, and Direction Générale de l'Armement anchoring demand aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Top-secret security clearance infrastructure represents the binding constraint across all vendor tiers, with cleared workforce scarcity creating durable competitive moats for incumbents who have invested in personnel security infrastructure.
For Market Incumbents: Pre-empt modular architecture displacement by accelerating open-standard middleware development before Australian AUKUS and Japanese Taigei-class programs finalize combat system specifications. Lockheed Martin Corporation and Northrop Grumman Corporation should deepen backward integration into sonar signal-processing chipsets to offset cleared contractor wage inflation. Certification investment in dual-use European facilities satisfies Direction Générale de l'Armement cross-border mandates while defending against Thales Group sovereign champion positioning. For New Entrants and Emerging Players: Build out unmanned underwater vehicle combat system integration capabilities as the most penetrable white space, where crewed submarine primes have underinvested in distributed kill chain architectures. Target seabed infrastructure protection mission profiles for Australian and Japanese navies, where operational portfolios expand beyond traditional anti-submarine warfare. Pursue joint development agreements with Mitsubishi Heavy Industries or Naval Group to access cleared facility networks without organic security infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed defense electronics suppliers holding submarine sonar processing contracts but lacking prime integrator scale. Long-term viability hinges on through-life support contract capture extending 15-20 years beyond initial platform delivery, with availability-based revenue streams reducing program cyclicality. Watch for Australian AUKUS submarine construction timeline acceleration as the inflection signal for combat system transfer demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Based Sonar Processing Investment | Machine-learning threat classification reduces operator cognitive load during Virginia-class submerged patrols. |
| Photonic Mast Technology Refresh | Two-year upgrade cycles collapse supplier business models built around decades-long production runs. |
| 25-Year Availability Contract Capture | Risk transfer to prime contractors accelerates in Pacific Rim programs with insufficient organic maintenance infrastructure. |
| Cleared Workforce Pipeline Development | Security clearance infrastructure constrains program staffing across US, UK, and French suppliers. |
| Unmanned Underwater Vehicle Integration | Autonomous sensor platform convergence enables distributed kill chains without platform concentration risk. |
Methodological Framework
A standing panel of submarine program managers, combat system integration engineers, naval procurement officers, and security clearance administrators provided ongoing calibration across primary interviews with industry stakeholders. Secondary validation drew from Naval Sea Systems Command technical specifications, Direction Générale de l'Armement procurement bulletins, Defence Equipment and Support contract announcements, and Australian Department of Defence capability acquisition reports. Bottom-up segment sizing triangulated against top-down fleet modernization budget aggregation.
Scenario-bracketing anchored the analytical framework across the projection horizon, with sensitivity testing on Columbia-class procurement acceleration and AUKUS submarine construction timeline shifts. Segmentation dimensions modeled included component tier, mission application profile, end-user contracting authority, and processing technology architecture. CAGRs derived from fleet replacement cycle analysis and technology refresh interval compression. Industry-specific forecast inputs incorporated undersea warfare doctrine evolution toward networked distributed operations and NATO Maritime Strategy standardization mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign national champions or cross-border joint venture formations would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Marine Penetrators Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Military Frigate Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Naval Radar Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Anti-Ship Missile Defense System Market