
 Aircraft Carrier Market | 2026-2036
Aircraft Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Carrier Market Analysis
The US Navy's net-zero emissions mandate for surface combatants is consolidating procurement criteria around nuclear propulsion and energy-efficient systems. Huntington Ingalls Industries leverages its Newport News facility to dominate US nuclear carrier construction. BAE Systems anchors UK carrier capability through its role in the Queen Elizabeth-class program. Naval Group competes in the export market with its CATOBAR design expertise.
An aircraft carrier is a large-deck warship engineered to deploy, recover, and sustain fixed-wing aircraft operations at sea, typically displacing over 40,000 tonnes with flight decks exceeding 240 meters in length and integrated arresting gear systems. Its primary purpose is to project air power beyond territorial limits without reliance on land-based airfields. Nuclear carriers command the largest capital allocations among product types due to reactor complexity and fifty-year service life expectations. Amphibious assault ships represent the fastest-growing category as navies prioritize flexible expeditionary platforms over traditional strike carriers. Integrated combat systems concentrate margin pools as defense primes bundle sensors, weapons direction, and network architecture into sole-source packages.
The US Navy's shipbuilding programs operate under Congressional cost caps and National Defense Authorization Act oversight, while the UK's Military Aviation Authority governs flight certification standards for carrier-based operations. France's Direction Générale de l'Armement imposes nuclear safety protocols that restrict technology transfer on propulsion systems. Stakeholders must monitor procurement cycle timing across Washington, London, and Paris as budget authorization delays compress construction schedules and strain supplier bases.
Market Dynamics
The US Navy's electromagnetic aircraft launch system (EMALS) transition is compressing carrier construction timelines and forcing shipyards to retool from steam catapult legacy infrastructure. This propulsion-agnostic launch architecture is redistributing technical risk across the supplier base.
Growth Catalysts
- Indo-Pacific Naval Modernization:India's indigenous carrier program at Cochin Shipyard is accelerating hull production schedules. The Indian Navy's pursuit of a three-carrier force structure is absorbing drydock capacity and training naval architects.
- Nuclear Propulsion Mandates:The US Navy's net-zero emissions directive for surface combatants is consolidating procurement criteria around reactor-based propulsion systems. Congressional authorization for Ford-class follow-on hulls is sustaining Newport News facility utilization.
- CATOBAR Export Competitiveness:France's Direction Générale de l'Armement is certifying electromagnetic arresting gear for foreign sales. Naval Group's design expertise is penetrating Middle Eastern and Southeast Asian feasibility studies.
Market Restraints
- Reactor Fuel Cycle Concentration:Highly enriched uranium supply for naval reactors concentrates at two enrichment facilities. Geographic concentration of fuel fabrication creates single-point vulnerability for nuclear carrier programs.
- Arresting Gear Input Volatility:Specialized high-tensile steel for arresting engine components faces aerospace alloy competition. Nickel and chromium price swings compress margin predictability for flight deck subsystem suppliers.
- Technical Obsolescence Risk:Steam catapult maintenance expertise is attriting as EMALS displaces legacy systems. Shipyard workforces with compound steam turbine experience are retiring without knowledge transfer protocols.
Strategic Opportunities
- Amphibious Assault Platform Expansion:Navies are prioritizing flexible expeditionary hulls over traditional strike carriers. The Royal Australian Navy's LHD procurement pattern is replicable across Southeast Asian maritime forces.
- Integrated Combat System Bundling:Defense primes are consolidating sensors, weapons direction, and network architecture into sole-source packages. Margin pools are concentrating in combat system integration rather than hull fabrication.
- UK Flight Certification Expertise:The Military Aviation Authority's carrier-based operation standards are exportable to Commonwealth navies. British flight deck certification protocols are licensing to Indo-Pacific operator training programs.
Industry Challenges
- Naval Architect Pipeline Collapse:University programs in warship structural design are contracting. Shipyard apprenticeship systems are failing to replace retiring hull stress analysts with compound curvature expertise.
- EMALS-Arresting Gear Integration Complexity:Electromagnetic launch and recovery systems require simultaneous software-hardware validation. Test facility bottlenecks at Lakehurst are compressing sea trial schedules.
- Long-Cycle Capital Intensity:Nuclear carrier construction requires decade-long capital commitment without revenue recognition. Shipyard balance sheets strain under work-in-progress accumulation across multi-hull programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Carrier Market |
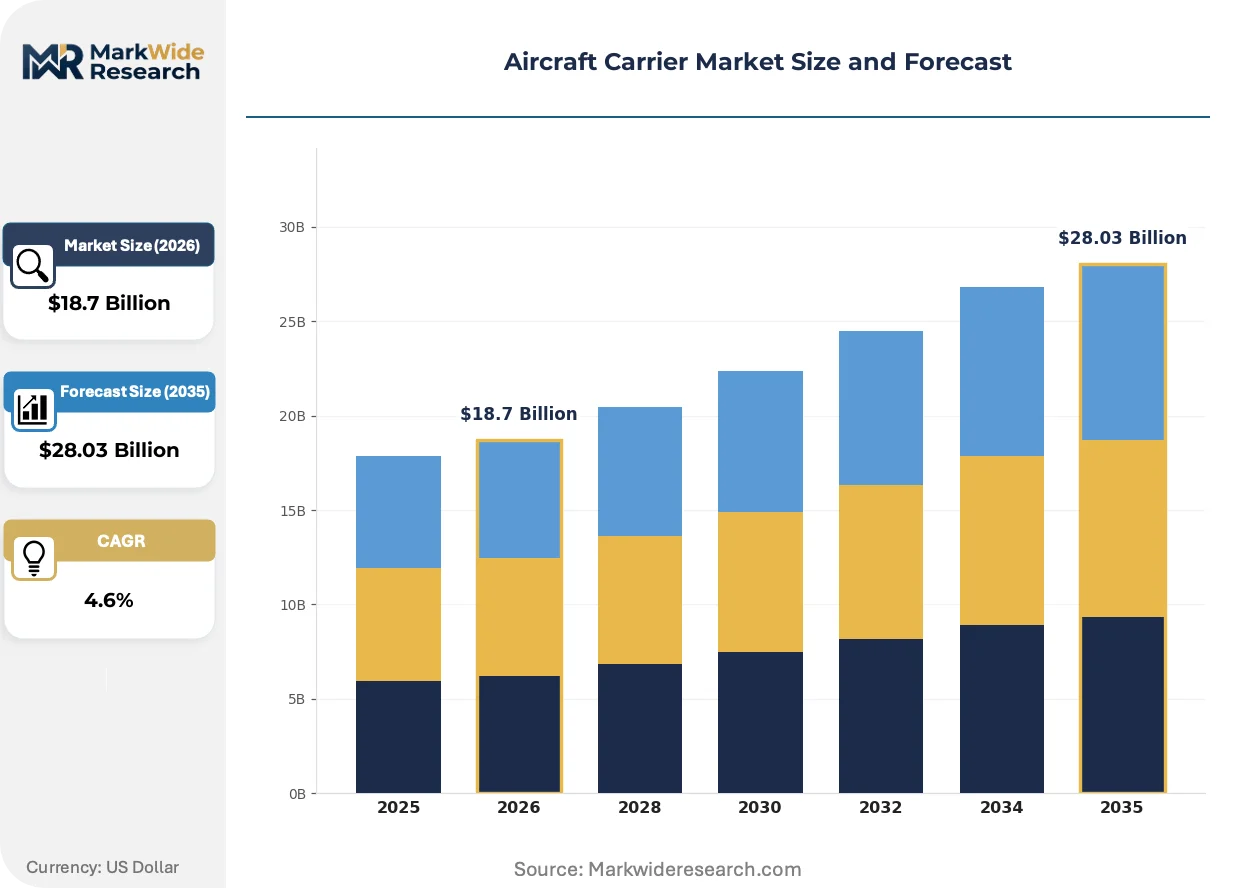
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Carriers, Nuclear Carriers, Amphibious Assault Ships, Multi-Purpose Carriers End User: Navy, Coast Guard, Defense Contractors, Private Sector Technology: Catapult Launch Systems, Vertical Launch Systems, Advanced Radar Systems, Integrated Combat Systems Deployment: Onshore, Offshore, Forward Operating Bases, International Waters |
| Companies Covered | Jiangnan Shipyard, BAE Systems, Huntington Ingalls Industries, Sevmash, Babcock International, Newport News Shipbuilding, Naval Group, Damen Shipyards Group, China State Shipbuilding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Carrier Market Emerging Trajectories
Carrier design philosophy is pivoting from maximum sortie generation toward distributed maritime operations. Electromagnetic systems are displacing steam infrastructure while unmanned aerial vehicle integration is reshaping flight deck geometry requirements.
Electromagnetic Aircraft Launch System (EMALS) technology is unifying launch energy control with digital diagnostics. The US Navy's Ford-class program is operationalizing this architecture after extensive land-based testing at Joint Base McGuire-Dix-Lakehurst. EMALS is unifying previously separate steam generation, accumulator, and catapult valve subsystems into a solid-state electromagnetic motor configuration, compressing mechanical complexity and enabling precision launch energy adjustment for unmanned platforms.
The US National Defense Authorization Act is imposing Congressional cost caps on carrier construction programs. These oversight mechanisms are forcing shipyards to front-load design maturity before steel cutting. Nuclear carrier procurement is most affected, with Huntington Ingalls Industries restructuring contract incentive structures to absorb risk within fixed-price learning curve assumptions.
Naval aviation authorities are unbundling flight certification from hull delivery schedules. The UK's Military Aviation Authority is decoupling F-35B operational testing from Queen Elizabeth-class acceptance trials, compressing initial operational capability timelines. This pattern is most visible in Indo-Pacific navies acquiring STOVL-capable platforms, where air wing certification is proceeding in parallel with sea trials rather than sequentially.
Aircraft Carrier Market Segmentation
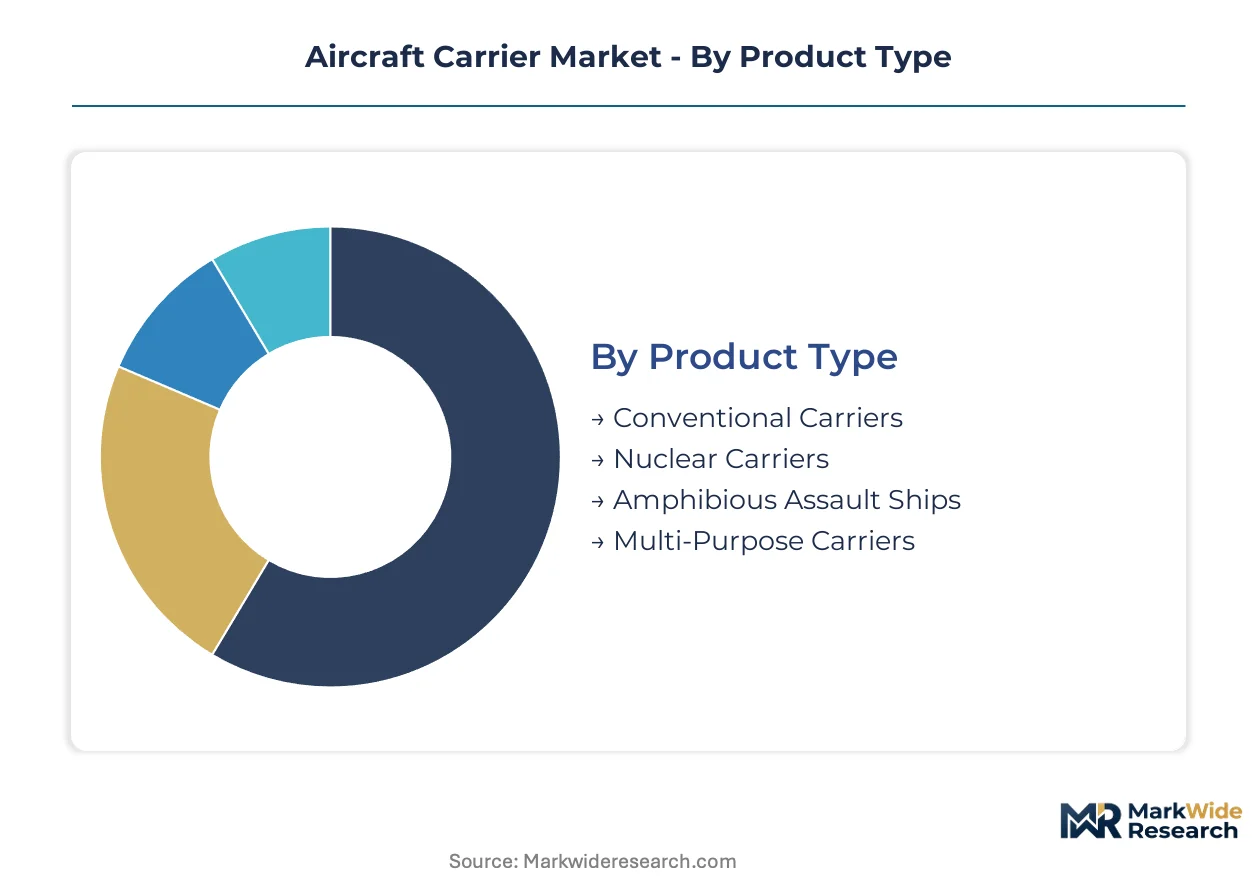
Aircraft carrier procurement decisions hinge on propulsion architecture, operational endurance requirements, and air wing composition. Each segmentation dimension reveals distinct buyer priorities across naval modernization cycles and force structure planning.
Product Type:
Capital allocation intensity drives procurement committee evaluation, with lifecycle cost modeling dominating source selection for hull categories.
- Nuclear Carriers:These hulls integrate pressurized water reactors delivering unlimited range at sustained flank speeds. The US Navy's Ford-class program at Newport News absorbs the largest procurement budgets, constrained by reactor fuel cycle security and fifty-year service life amortization schedules.
- Amphibious Assault Ships:Expeditionary platforms displace 40,000-plus tonnes with well decks and aviation facilities combined. The Royal Australian Navy's Canberra-class acquisition pattern is replicating across Southeast Asian maritime forces seeking flexible power projection without strike carrier capital burden.
- Conventional Carriers:Gas turbine or diesel propulsion limits operational endurance but reduces upfront capital commitment and crew qualification requirements.
- Multi-Purpose Carriers:Hybrid designs merge fixed-wing aviation with amphibious lift capacity, optimizing hull utilization across mission profiles.
Volume sits with nuclear carriers; growth tilts toward amphibious assault ships.
End User:
Operational authority and funding mechanisms determine specification requirements, with sovereign navies imposing distinct certification standards on hull acceptance.
- Navy:Blue-water fleets command specification priority, integrating electromagnetic launch systems and nuclear propulsion. India's indigenous carrier production at Cochin Shipyard exemplifies sovereign construction capability acquisition.
- Defense Contractors:Prime integrators absorb design risk through fixed-price contracts, bundling combat systems and network architecture into sole-source packages with concentrated margin pools.
- Coast Guard:Constabulary missions drive smaller flight deck requirements with helicopter-centric aviation facilities.
- Private Sector:Limited procurement concentrates on training platforms and heritage vessel preservation.
Procurement volume clusters with sovereign navies; contractor-led integration is expanding fastest.
Technology:
Flight deck architecture and sensor integration determine mission effectiveness, with electromagnetic systems displacing legacy steam infrastructure.
- Integrated Combat Systems:Bundled sensors, weapons direction, and network architecture consolidate supplier margins. BAE Systems and Naval Group compete to embed combat management systems into hull fabrication contracts.
- Catapult Launch Systems:EMALS technology unifies launch energy control with digital diagnostics, compressing mechanical complexity. Lakehurst test facility bottlenecks constrain sea trial scheduling for new hull programs.
- Advanced Radar Systems:Dual-band phased arrays provide air traffic control and ballistic missile defense cueing.
- Vertical Launch Systems:Short take-off configurations reduce flight deck engineering complexity for smaller navies.
Installed base concentrates in catapult systems; integrated combat systems are climbing the fastest.
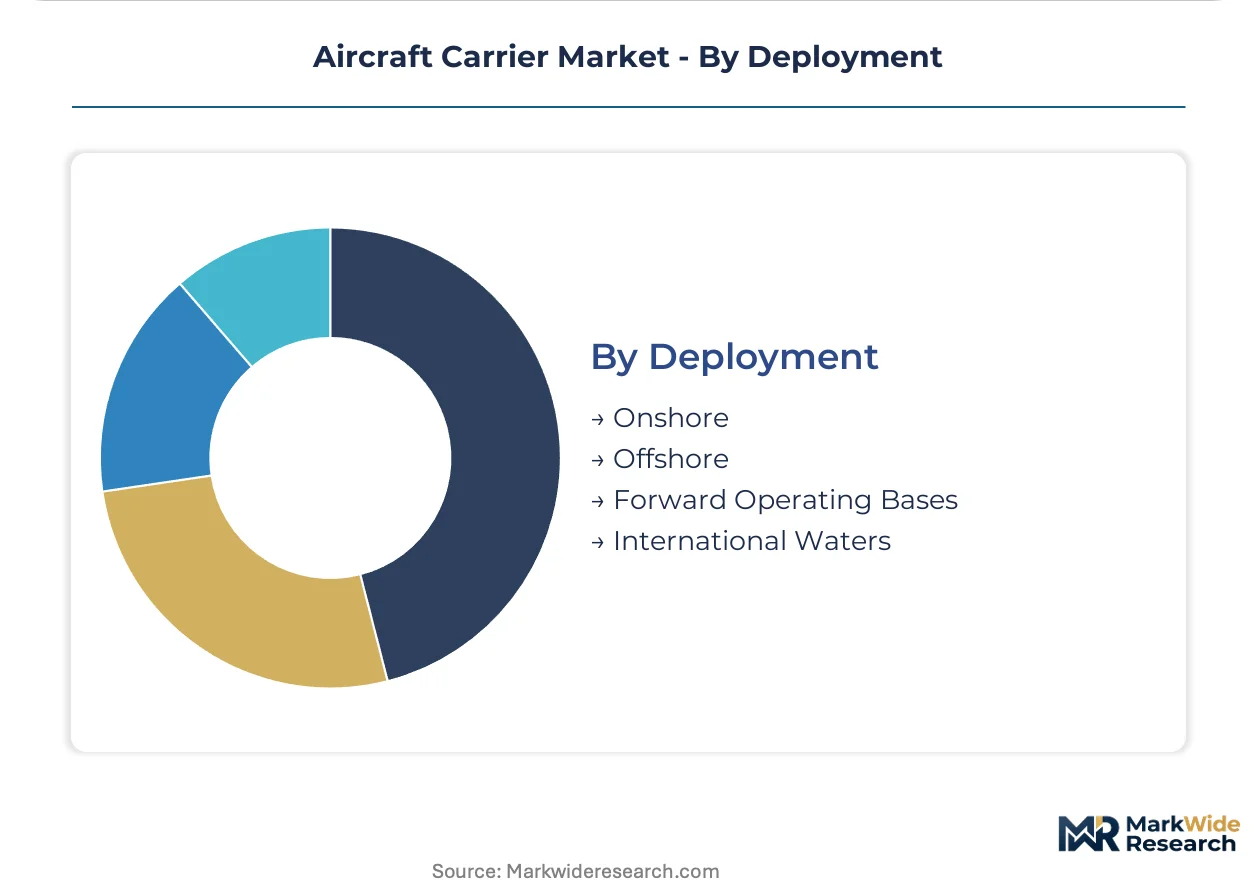
Deployment:
Operational posture dictates hull specifications, with forward presence requirements driving endurance and self-sufficiency investments.
- International Waters:Sustained blue-water presence demands nuclear propulsion and comprehensive logistics independence. The US Navy's carrier strike group rotations exemplify continuous deployment architecture.
- Forward Operating Bases:Shore facility proximity enables conventional propulsion acceptance with reduced endurance requirements.
- Onshore:Maintenance and modernization periods concentrate at specialized facilities like Newport News and Rosyth.
- Offshore:Littoral operations within territorial sea limits optimize for helicopter and STOVL aviation.
Operational tempo centers on international waters deployment; forward basing infrastructure is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier construction concentrates in sovereign shipyards with nuclear certification, while demand disperses across Indo-Pacific navies seeking fleet expansion. Production capacity clusters at facilities with decade-long capital commitments and specialized workforce pipelines.
United States
Congressional cost caps under the National Defense Authorization Act compress construction timelines for Ford-class hulls. The FAA governs carrier-based aviation certification standards through delegated military authority. Newport News Shipbuilding anchors nuclear carrier production on the Atlantic coast, absorbing the largest single-nation procurement budgets.
China
Indigenous carrier programs at Jiangnan Shipyard accelerate hull production for fleet expansion beyond the first island chain. MIIT coordinates military-civilian fusion standards for dual-use shipbuilding technologies. Dalian and Shanghai maritime clusters concentrate drydock capacity for both conventional and nuclear hull variants.
India
The Indian Navy's three-carrier force structure absorbs Cochin Shipyard capacity through indigenous construction timelines. The Ministry of Defence imposes offset requirements on foreign subsystem suppliers. Kochi's naval infrastructure cluster trains naval architects in compound curvature hull design for flight deck integration.
United Kingdom
Rosyth dockyard completion of Queen Elizabeth-class hulls preserves CATOBAR design expertise for export advisory roles. The Military Aviation Authority decouples flight certification from hull delivery schedules. Scottish shipbuilding clusters transition toward maintenance and modernization periods after construction peak.
France
Naval Group certifies electromagnetic arresting gear for foreign sales through Direction Générale de l'Armement oversight. Nuclear safety protocols restrict propulsion technology transfer to sovereign programs only. Toulon and Saint-Nazaire maritime facilities concentrate carrier maintenance and new construction respectively.
Aircraft Carrier Market Vendor Landscape
The competitive structure tilts toward state-affiliated shipyards with sovereign security clearances and nuclear certification. Huntington Ingalls Industries and China State Shipbuilding Corporation anchor opposite poles of this bifurcation. Three archetypes dominate: nuclear-certified sovereign builders, conventional carrier specialists, and combat system integrators. Consolidation through sole-source combat system bundling and geographic expansion through foreign military sales advisory roles represent the primary competitive vectors.
Among US-based fabricators, Huntington Ingalls Industries and Newport News Shipbuilding occupy positions within the nuclear-certified sovereign tier, representing decades of pressurized water reactor integration expertise. BAE Systems anchors UK capability through Queen Elizabeth-class program involvement. Naval Group exemplifies the export-oriented CATOBAR specialist archetype, sitting within the combat system integration tier through electromagnetic launch and recovery certification.
| Leading Market Players |
|---|
| Jiangnan Shipyard |
| BAE Systems |
| Huntington Ingalls Industries |
| Sevmash |
| Babcock International |
| Newport News Shipbuilding |
| Naval Group |
| Damen Shipyards Group |
| China State Shipbuilding Corporation |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange nickel price volatility cascades through flight deck subsystem supply chains, compressing margin predictability for arresting engine component suppliers while amplifying cost premiums on nuclear-grade steel alloys. Procurement committees absorb these fluctuations through multi-hull contract bundling that front-loads design maturity before steel cutting.
Pricing Analysis
Sortie-generation throughput anchors value-based pricing for integrated combat system packages, with BAE Systems and Naval Group competing to embed combat management systems into hull fabrication contracts. Pricing stratifies across nuclear-certified sovereign builders, conventional carrier specialists, and combat system integrators based on reactor fuel cycle security clearances and electromagnetic launch certification levels. Cost compression in conventional propulsion tiers intensifies as amphibious assault platforms absorb expeditionary demand without strike carrier capital burden. Coast Guard and private sector buyers exhibit highest price sensitivity due to helicopter-centric aviation facility requirements, while sovereign navies prioritize lifecycle cost amortization over upfront capital commitment.
Supply Chain Analysis
Single-source vulnerability sits with highly enriched uranium enrichment facilities concentrated in the United States and Russia, creating geographic chokepoints for nuclear carrier propulsion systems. Specialized high-tensile steel for arresting gear components draws from aerospace alloy competition in the United Kingdom, France, and Japan. Nickel and chromium price swings, reactor fuel cycle concentration, and shipyard workforce attrition compound supply chain fragility. Distribution runs through sovereign shipyards with decade-long capital commitments and nuclear certification, with Huntington Ingalls Industries and China State Shipbuilding Corporation anchoring opposite production poles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft carrier market sits in a technology-transition phase as electromagnetic aircraft launch systems displace steam catapult legacy infrastructure, redistributing technical risk across supplier bases and compressing construction timelines.
For Market Incumbents: Deepen electromagnetic launch and recovery certification investments to capture sole-source combat system bundling margins, while accelerating knowledge transfer protocols to offset naval architect pipeline collapse. Threat of steam catapult maintenance expertise attrition demands compound steam turbine workforce retention programs at Newport News and Rosyth facilities. For New Entrants and Emerging Players: Enter via amphibious assault platform specialization targeting Southeast Asian maritime forces replicating the Royal Australian Navy's LHD procurement pattern, exploiting flexible expeditionary hull demand without strike carrier capital barriers. White-space concentrates in integrated combat system integration for STOVL-capable platforms where flight certification proceeds parallel to sea trials. For Investors and Strategic Acquirers: Distressed-cycle entries favor combat system integrators with electromagnetic arresting gear certification in France and the United Kingdom, where Naval Group and BAE Systems hold export-advisory positioning. Long-term viability hinges on five-to-ten year nuclear propulsion mandate durability under sovereign net-zero emissions directives. Watch EMALS-Arresting Gear integration complexity resolution at Lakehurst test facilities as inflection indicator for sea trial schedule compression.| Strategic Initiative | Industry Significance |
|---|---|
| EMALS Technology Certification | Naval Group's Direction Générale de l'Armement oversight enables foreign sales penetration in Middle Eastern feasibility studies. |
| Indigenous Carrier Construction | India's Cochin Shipyard acceleration absorbs drydock capacity and trains naval architects in compound curvature hull design. |
| Integrated Combat System Bundling | Defense primes consolidate sensors and network architecture into sole-source packages with concentrated margin pools. |
| Amphibious Assault Platform Expansion | Flexible expeditionary hulls prioritize power projection without traditional strike carrier capital burden across Southeast Asian forces. |
| Nuclear Propulsion Mandate Compliance | US Navy net-zero emissions directives consolidate procurement criteria around reactor-based systems at Huntington Ingalls Industries. |
Methodological Framework
Multi-period observation of Congressional authorization timelines, drydock capacity utilization, and electromagnetic system test schedules anchored the trend analysis, supplemented by interviews with naval architects at sovereign shipyards, carrier air wing commanders, defense procurement officers, and combat system integration engineers. Secondary validation drew from National Defense Authorization Act filings, UK Military Aviation Authority certification protocols, French Direction Générale de l'Armement safety directives, and shipyard SEC disclosures. Bottom-up hull production tracking and top-down fleet modernization budget analysis provided triangulation across data sources.
Segment-weighting approaches modeled nuclear versus conventional propulsion architecture, CATOBAR versus STOVL flight deck configurations, and sovereign versus export market delivery patterns across the analysis window. CAGRs derived from procurement cycle timing compression, construction schedule strain indicators, and supplier base capacity constraints. Industry-specific forecast inputs incorporated electromagnetic system land-based test completion rates and naval reactor fuel cycle security assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Congressional cost cap enforcement delays and Lakehurst test facility bottlenecks. Assumptions reflect documented procurement authorization schedules, workforce pipeline replacement rates, and nickel-chromium alloy price corridor stability. Deviation in Indo-Pacific naval modernization acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Marine Radar Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Bow and Stern Thrusters Market