
 Amphibious Landing Craft Market | 2026-2036
Amphibious Landing Craft Market Size, Share, and Industry Trends Forecast 2026-2036
Amphibious Landing Craft Market Analysis
REACH compliance is decoupling European builder certification from legacy hull fabrication methods, forcing new capital allocation toward resin-infused composite shops. Fincantieri Marine Group leverages its Italian yard network to sustain dual-use production lines for naval and coast guard variants. General Dynamics NASSCO anchors U.S. Navy LCAC service-life extension work through its San Diego facility. Garden Reach Shipbuilders & Engineers Ltd. competes on cost structure for littoral craft tenders across the Indian Ocean rim.
An amphibious landing craft is a self-propelled vessel engineered for ship-to-shore cargo and personnel transfer, typically featuring shallow-draft hull geometry, ramp-configured bow sections, and payload capacities spanning 60 to 180 metric tons for mechanized equipment delivery. Steel-aluminum hybrid construction dominates military specifications where blast resistance and magnetic signature reduction govern material selection, while commercial derivatives employ welded aluminum for corrosion resistance in tropical littorals. Assault craft configurations lead procurement volume among product types due to expeditionary force restructuring across multiple navies, whereas automated systems technology captures expanding R&D allocation as unmanned surface vessel interoperability becomes a design mandate. Personnel carriers represent a mature segment with replacement-driven demand rather than fleet expansion.
The U.S. Navy's Naval Sea Systems Command, the European Defence Agency, and Australia's Department of Defence shape market access through divergent qualification regimes spanning shock testing, survivability standards, and local content thresholds. Builders must navigate concurrent certification to NATO STANAG protocols and country-specific naval architecture rules to maintain tender eligibility. Stakeholders should monitor which procurement authorities merge manned and unmanned craft requirements into single acquisition streams, as this integration trajectory will determine future platform specifications and vendor selection criteria.
Market Dynamics
Naval modernization programs across NATO allies and Indo-Pacific partners are forcing builders to requalify production lines for composite hull fabrication, decoupling certification from legacy steel-aluminum methods and concentrating capital in resin-infused manufacturing capabilities.
Growth Catalysts
- Assault craft procurement:Expeditionary force restructuring across multiple navies drives volume demand for mechanized equipment delivery platforms with shallow-draft geometry.
- REACH compliance:European hull fabrication standards are accelerating composite material adoption by disqualifying legacy coating systems from builder certification pathways.
- LCAC replacement timelines:U.S. Navy service-life extension programs sustain demand for air-cushion landing craft maintenance and mid-life upgrade work.
Market Restraints
- Aluminum price volatility:Welded aluminum hull construction for tropical littoral operations faces input cost pressure from energy-intensive smelting capacity constraints.
- Builder qualification concentration:Shock testing and survivability certification requirements limit viable suppliers to yards with existing naval architecture credentials.
- Personnel carrier maturity:Replacement-driven demand in this segment offers limited fleet expansion opportunity compared to assault craft growth.
Strategic Opportunities
- Unmanned surface vessel interoperability:Automated systems R&D allocation is unifying manned and unmanned craft requirements into single acquisition streams.
- Australian capability enhancement:Canberra's amphibious fleet renewal plans create regional tender opportunities for ship-to-shore cargo transfer platforms.
- Indian Ocean rim tenders:Littoral craft procurement across littoral states offers cost-competitive entry points for builders with established coast guard relationships.
Industry Challenges
- Concurrent certification complexity:Builders must maintain simultaneous compliance with NATO STANAG protocols and country-specific naval architecture rules to retain tender eligibility.
- Resin-infused composite skill gaps:Capital allocation toward new fabrication shops requires retraining welders and laminators in vacuum-assisted transfer molding techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphibious Landing Craft Market |
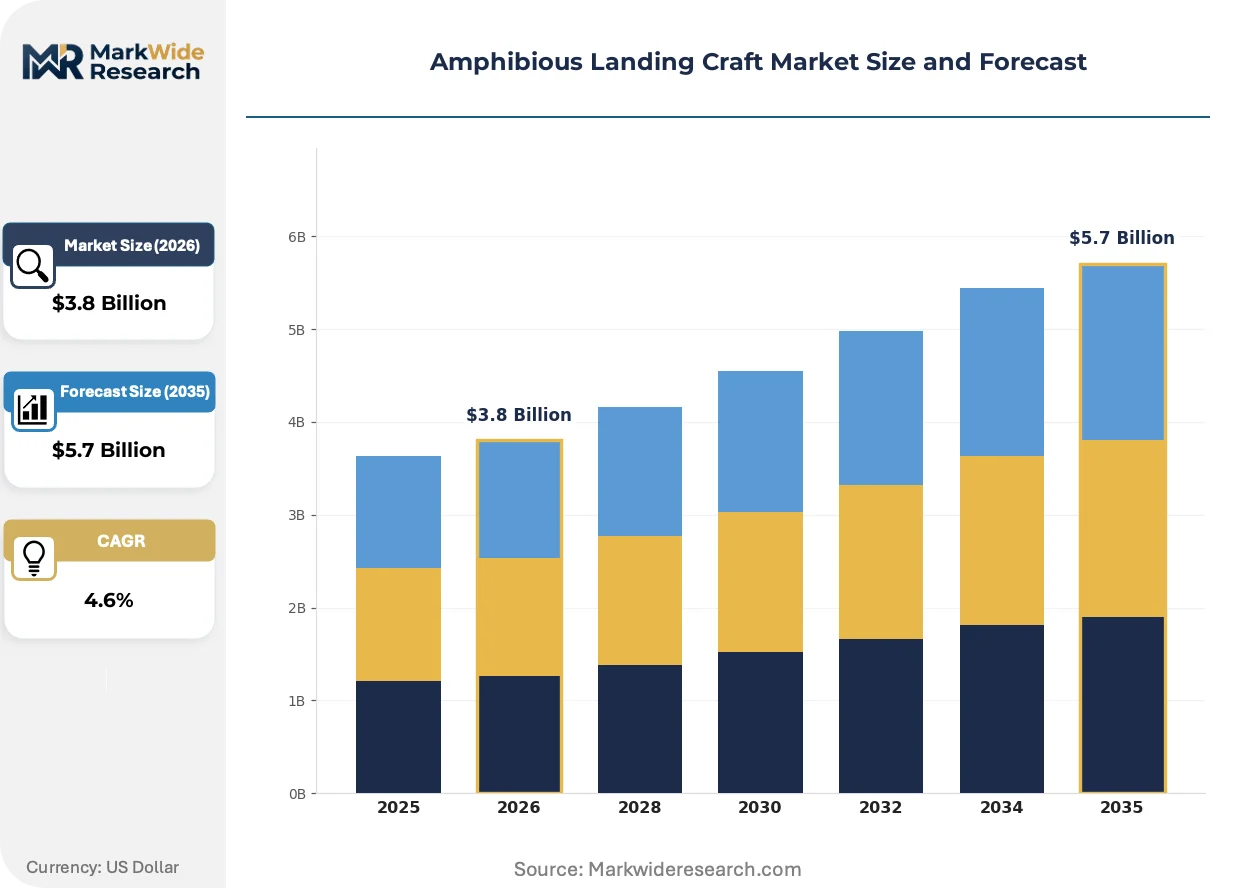
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Landing Vehicles, Assault Craft, Support Crafts, Personnel Carriers Application: Military Operations, Disaster Relief, Coastal Surveillance, Cargo Transport Technology: Hydrostatic Drive, Amphibious Propulsion, Modular Design, Automated Systems End User: Defense Forces, Humanitarian Organizations, Government Agencies, Research Institutions |
| Companies Covered | Fincantieri Marine Group, Garden Reach Shipbuilders & Engineers Ltd., Griffon Hoverwork Ltd., Damen Shipyards Group, Goa Shipyard Ltd., L3Harris Technologies, Inc., General Dynamics NASSCO, Abu Dhabi Ship Building PJSC, BAE Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphibious Landing Craft Market Emerging Trajectories
Material science advances and procurement integration mandates are compressing traditional boundaries between manned assault platforms and autonomous logistics systems, reshaping builder design priorities.
Resin-infused composite hull construction is unifying blast resistance and magnetic signature reduction in a single material system. NATO specification writers are adopting these methods for next-generation craft. This convergence is compressing the supplier base toward yards with captive composite manufacturing capability.
EU REACH regulations on volatile organic compounds are disqualifying traditional marine coatings from European naval tenders. Builders serving NATO STANAG markets must reformulate surface preparation and finishing protocols. Personnel carrier segments in European procurement face the steepest compliance timeline pressures.
Acquisition authorities are bundling manned assault craft and unmanned logistics platform requirements into unified tender documents. Australian and U.S. Navy procurement offices lead this consolidation. This pattern compresses vendor selection criteria toward builders with demonstrated autonomous systems integration experience.
Amphibious Landing Craft Market Segmentation
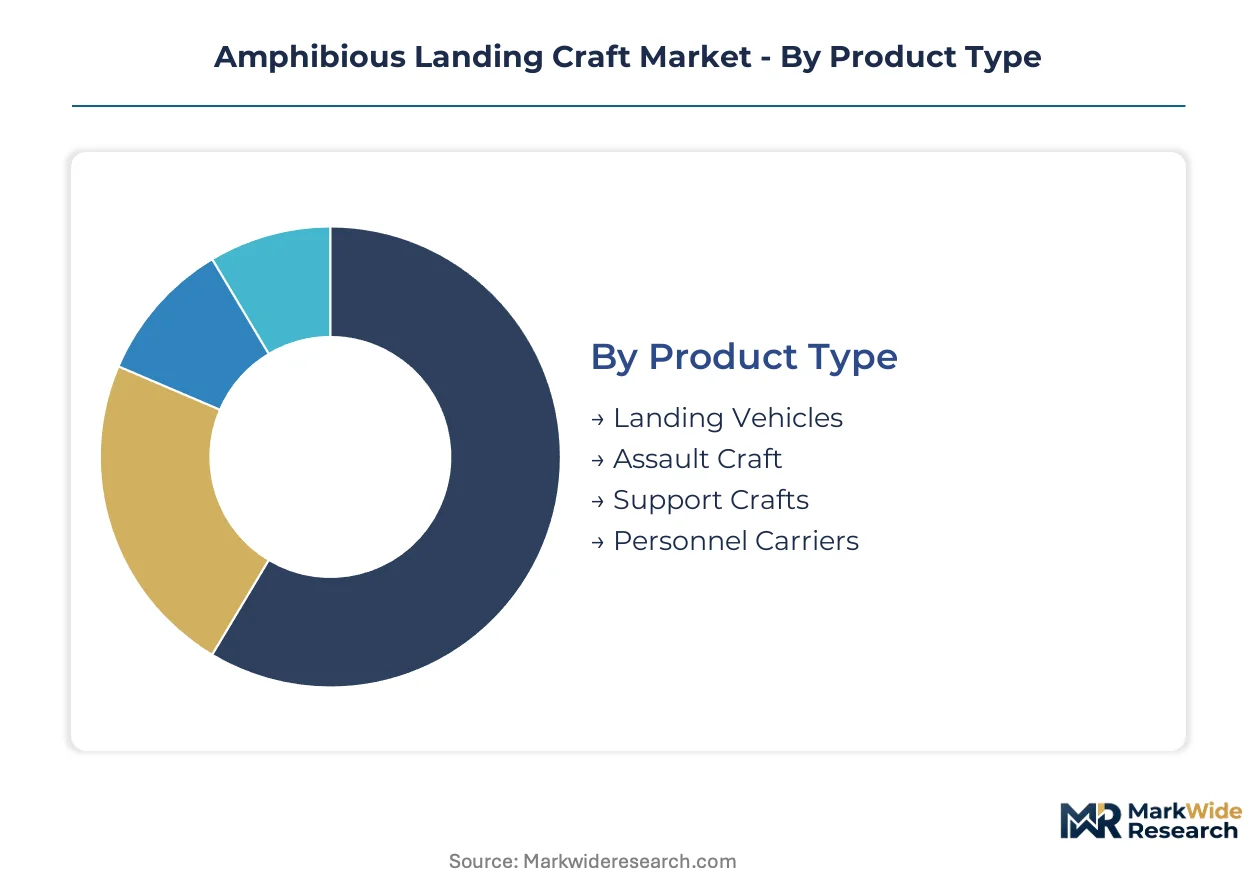
Procurement authorities bundle requirements across multiple dimensions, forcing builders to qualify platforms for overlapping mission profiles rather than single-use specifications. Segmentation clarity determines tender eligibility and design resource allocation.
Product Type:
Payload capacity and draft geometry drive platform selection for specific ship-to-shore transfer missions.
- Assault Craft:Mechanized equipment delivery platforms feature shallow-draft hull geometry and ramp-configured bow sections for beach landing operations. Expeditionary force restructuring across NATO allies and Indo-Pacific partners concentrates procurement volume in this segment.
- Personnel Carriers:Troop transport configurations employ steel-aluminum hybrid construction for blast resistance and magnetic signature reduction. Replacement-driven demand in this mature segment offers limited fleet expansion opportunity compared to assault craft procurement cycles.
- Landing Vehicles:Tracked or wheeled amphibious platforms bridge the gap between ship-based craft and shore operations.
- Support Crafts:Auxiliary vessels provide logistics, maintenance, and command functions for amphibious task forces.
Assault craft leads on scale; automated systems integration is gaining share fastest among new procurement specifications.
Application:
Mission profile determines survivability standards, certification pathways, and maintenance contract structures.
- Military Operations:Combat-configured platforms require shock testing certification and NATO STANAG protocol compliance for mechanized assault missions. Naval modernization programs across multiple navies sustain demand for platforms with integrated command-and-control architectures.
- Disaster Relief:Humanitarian logistics configurations prioritize rapid deployment and simplified maintenance protocols for emergency response scenarios. Australia's Department of Defence and coast guard agencies drive regional tender volume for dual-use platforms.
- Coastal Surveillance:Patrol-optimized variants emphasize endurance and sensor integration over heavy-lift capacity.
- Cargo Transport:Commercial-military hybrid specifications serve logistics chains in tropical littoral environments.
Military operations leads on scale; disaster relief expands most quickly as dual-use procurement consolidates funding streams.
Technology:
Fabrication method and propulsion architecture determine builder qualification requirements and capital allocation priorities.
- Automated Systems:Unmanned surface vessel interoperability mandates reshape design specifications for next-generation platforms. U.S. Navy and Australian procurement offices lead consolidation of manned and unmanned craft requirements into unified tender documents.
- Modular Design:Reconfigurable payload bays and mission modules extend platform service life across multiple operational roles. REACH compliance pressures accelerate composite material adoption for European naval tenders.
- Hydrostatic Drive:Water-jet propulsion systems enable precise maneuvering in shallow-draft littoral zones.
- Amphibious Propulsion:Dual-mode land-water propulsion architectures serve tracked landing vehicle applications.
Modular design leads on scale; automated systems climbs the fastest as acquisition authorities merge procurement streams.
End User:
Budget cycle timing and qualification regimes segment demand across institutional buyer categories.
- Defense Forces:Naval Sea Systems Command and equivalent authorities impose survivability standards, shock testing protocols, and local content thresholds. Defense procurement dominates volume through multi-year fleet modernization programs.
- Government Agencies:Coast guard and maritime security organizations purchase patrol-optimized variants with reduced armor specifications. Tender opportunities concentrate in the Indian Ocean rim where littoral states expand maritime enforcement capabilities.
- Humanitarian Organizations:Non-governmental logistics operators acquire simplified maintenance platforms for rapid deployment scenarios.
- Research Institutions:Scientific survey configurations prioritize sensor payload capacity and extended endurance.
Defense forces leads on scale; government agencies shows steepest expansion trajectory as coast guard procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled naval architects and marine engineers concentrate in coastal defense hubs across four maritime nations, anchoring regional procurement capacity for amphibious platform development.
United States
Naval Sea Systems Command modernization timelines and LCAC replacement programs sustain demand for air-cushion landing craft engineering. EPA vessel discharge standards and Coast Guard safety protocols govern builder certification pathways. San Diego hosts concentrated service-life extension work through established yard networks.
Australia
Canberra's amphibious capability enhancement plans drive regional fleet renewal for ship-to-shore cargo transfer platforms. Department of Defence tender specifications mandate local content thresholds and survivability testing aligned with NATO STANAG frameworks. Queensland and Western Australia host emerging fabrication clusters for littoral craft assembly.
Italy
Fincantieri's integrated yard network sustains dual-use production capacity for naval and coast guard landing craft variants. EU REACH compliance on volatile organic compounds accelerates composite material adoption across Mediterranean builders. Trieste and Monfalcone anchor resin-infused hull fabrication capabilities for European defense tenders.
India
Garden Reach Shipbuilders and Goa Shipyard compete on cost structure for Indian Ocean rim littoral craft procurement. Ministry of Defence indigenization policies and BIS naval material standards shape local qualification requirements. Kolkata and Goa host concentrated government shipyard capacity for patrol-optimized amphibious variants.
United Arab Emirates
Abu Dhabi Ship Building anchors Gulf Cooperation Council demand for patrol-configured landing craft with reduced armor specifications. UAE maritime security strategies and coast guard modernization programs expand tender volume for shallow-draft logistics platforms. Abu Dhabi industrial zones concentrate composite fabrication investment for regional export positioning.
Amphibious Landing Craft Market Vendor Landscape
The competitive structure tilts toward defense-integrated shipyards with captive naval architecture credentials. Builder qualification concentration limits viable suppliers to yards maintaining concurrent NATO STANAG and country-specific certification. Three archetypes dominate: government-affiliated naval shipbuilders, private defense contractors with composite manufacturing capability, and regional specialists serving coast guard procurement. Strategic moves center on resin-infused composite shop expansion and unmanned systems integration partnerships.
Among established naval shipbuilders, Fincantieri Marine Group, General Dynamics NASSCO, and Garden Reach Shipbuilders & Engineers Ltd. represent distinct geographic anchors for regional tender eligibility. Fincantieri exemplifies the dual-use production archetype spanning naval and coast guard variants. General Dynamics NASSCO occupies a position within U.S. Navy service-life extension workflows. Garden Reach Shipbuilders anchors cost-competitive positioning for Indian Ocean rim procurement. These three entities illustrate how certification concentration and geographic proximity to naval command structures determine competitive access.
| Leading Market Players |
|---|
| Fincantieri Marine Group |
| Garden Reach Shipbuilders & Engineers Ltd. |
| Griffon Hoverwork Ltd. |
| Damen Shipyards Group |
| Goa Shipyard Ltd. |
| L3Harris Technologies, Inc. |
| General Dynamics NASSCO |
| Abu Dhabi Ship Building PJSC |
| BAE Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Aluminum LME price volatility cascades through amphibious landing craft supply chains into three distinct pricing tiers: steel-aluminum hybrid military specifications command premium valuations, welded aluminum commercial variants occupy mid-market positioning, and resin-infused composite platforms reset cost benchmarks as REACH compliance disqualifies legacy coating systems from European tender eligibility.
Pricing Analysis
Unbundled hull fabrication competes against bundled lifecycle service contracts across procurement streams. Three-tier pricing structure across premium, standard, and economy levels separates NATO STANAG-certified assault craft from coast guard patrol variants and commercial logistics derivatives. Price differentiation hinges on shock testing certification tier and after-sales maintenance bundling. Cost compression in standard-tier welded aluminum hulls is intensifying because energy-intensive smelting capacity constraints tighten input material availability. Coast guard agencies and littoral state maritime security organizations exhibit highest price sensitivity; defense forces with multi-year fleet modernization budgets demonstrate lowest.
Supply Chain Analysis
Freight costs for oversized hull sections and specialized marine propulsion systems concentrate procurement leverage in yards with captive fabrication clusters. Supply concentrates in Italy, the United States, and India for naval-qualified assembly; Australia and the United Arab Emirates anchor emerging composite fabrication investment. Raw material dependencies span high-grade marine aluminum alloys, resin systems for vacuum-assisted transfer molding, and shock-absorbent composite laminates. Single-source vulnerability in EU-certified resin formulation creates qualification bottlenecks for builders serving NATO STANAG markets. Distribution runs through defense procurement authority tender processes with multi-year contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amphibious landing craft procurement functions as a geographic-arbitrage play where Italian and Australian regulatory alignment with NATO STANAG protocols creates tender access advantages against Indian cost-competitive positioning for Indian Ocean rim coast guard contracts.
For Market Incumbents: Extend composite manufacturing capabilities into Australian and UAE fabrication clusters before REACH compliance deadlines consolidate European supplier bases. Anchor U.S. Navy service-life extension workflows through LCAC upgrade capacity in San Diego. Resin-infused skill gaps and unmanned systems integration mandates represent the primary threat vectors; certification investment in concurrent NATO STANAG and country-specific naval architecture rules remains the critical defensive lever. For New Entrants and Emerging Players: Enter via Indian Ocean rim coast guard tenders where Garden Reach Shipbuilders and Goa Shipyard have established cost-competitive benchmarks but capacity constraints create white-space. Target Australian Department of Defence dual-use disaster relief specifications as the most penetrable segment given Canberra's fleet renewal timelines. Partner with established composite fabrication shops for resin-infused hull qualification rather than greenfield capital allocation. For Investors and Strategic Acquirers: Asymmetric upside sits with private defense contractors possessing captive unmanned surface vessel interoperability capabilities as acquisition authorities merge manned and unmanned craft requirements. Long-term viability over the projection horizon favors builders with demonstrated autonomous systems integration experience over pure-play hull fabricators. Monitor which procurement authorities issue unified tender documents bundling assault craft and logistics platform specifications as the inflection signal for platform consolidation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Resin-Infused Composite Shop Expansion | REACH compliance deadlines in European markets compress supplier bases toward yards with captive vacuum-assisted transfer molding capability. |
| Unmanned Systems Integration Partnership | U.S. Navy and Australian procurement offices now mandate autonomous interoperability in unified tender specifications. |
| Dual-Use Production Line Configuration | Fincantieri's Italian yard network demonstrates how naval and coast guard variants sustain capacity utilization across defense budget cycles. |
| Service-Life Extension Contract Capture | General Dynamics NASSCO's San Diego anchoring of LCAC upgrade work illustrates recurring revenue potential in platform sustainment. |
| Regional Fabrication Cluster Establishment | Queensland and Western Australia emerging clusters position builders for Australian Department of Defence local content thresholds. |
Methodological Framework
Bottom-up defense procurement modeling reconciled against top-down shipyard capacity tracking forms the analytical core of this study. Primary interviews with naval architects, shipyard program managers, defense procurement officers, and coast guard fleet planners combined with secondary validation from NATO STANAG documentation, EU REACH regulatory filings, U.S. Naval Sea Systems Command budget justifications, and Australian Department of Defence tender archives. Customs and trade data on marine aluminum alloy shipments, resin system imports, and completed vessel deliveries provided supply-side triangulation against demand signals from fleet modernization announcements.
Historical trendline analysis of assault craft, personnel carrier, and support craft procurement volumes established baseline growth patterns across the projection horizon. Segmentation modeling captured product type, application mission profile, fabrication technology, and end-user institution categories alongside geographic regulatory cluster differentiation. CAGRs derived from weighted average of defense budget trajectory assumptions and shipyard orderbook visibility. Forecast inputs included LCAC replacement timeline phasing, REACH compliance deadline impacts on builder certification, and unmanned surface vessel interoperability mandate adoption rates.
The model holds under steady defense budget commitment and regulatory timeline adherence; deviation in aluminum price volatility extremes or NATO STANAG protocol revision would shift builder qualification economics and procurement volume distributions. Forecasts reflect documented assumptions regarding composite material adoption curves and unmanned systems integration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market