
 Africa Undersea Warfare Systems Market | 2026-2036
Africa Undersea Warfare Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Undersea Warfare Systems Market Insights
Coast guard modernization programs is redrawing procurement patterns across African maritime agencies. Thales Group leverages its acoustic sensor portfolio to anchor contracts with North African navies. Lockheed Martin Corporation competes through signal processing integration for surveillance architectures. Naval Group sustains its presence via submarine platform expertise tailored to regional fleet requirements.
Africa undersea warfare systems encompass integrated platforms and technologies designed for submarine detection, tracking, and neutralization in littoral and deep-water environments, typically operating at depths exceeding 200 meters with acoustic detection ranges spanning dozens of kilometers. These systems serve primarily to secure territorial waters, protect commercial shipping corridors, and deny hostile submarine access to strategic maritime zones. Sonar systems dominate current procurement budgets given their foundational role in anti-submarine warfare architectures, while autonomous underwater vehicles represent the fastest-expanding technology segment as navies seek reduced-crew reconnaissance and mine countermeasure capabilities. Maritime security applications command substantial investment flows due to piracy threats along the Gulf of Guinea and Horn of Africa, whereas intelligence gathering functions attract specialized funding from defense forces prioritizing submarine fleet monitoring.
South Africa's Armaments Corporation and Egypt's military procurement authority shape regional demand through localized offset requirements and technology transfer stipulations. The African Union's maritime security framework and individual national defense white papers collectively establish operational standards that foreign suppliers must satisfy for market access. Stakeholders should monitor how coastal nations balance sovereign capability building against dependency on imported platforms as undersea warfare requirements intensify across the continent.
Market Dynamics
South Africa's exclusive economic zone protection mandates are compressing procurement cycles for acoustic detection platforms, while Egypt's submarine fleet expansion creates synchronized demand spikes for integrated undersea warfare architectures across North African littoral zones.
Growth Catalysts
- EEZ Protection Mandates:South Africa's defense modernization framework requires continuous seabed monitoring across its 1.5 million square kilometer maritime zone. This legislative pressure accelerates sonar array deployments.
- Gulf of Guinea Piracy Response:Nigeria's naval procurement authority channels defense budgets toward autonomous underwater vehicles for corridor surveillance. Maritime security applications absorb disproportionate capital allocation.
- Technology Transfer Stipulations:Egypt's military procurement authority mandates localized production offsets for foreign suppliers. Domestic assembly requirements reshape vendor selection criteria toward partners offering co-development frameworks.
Market Restraints
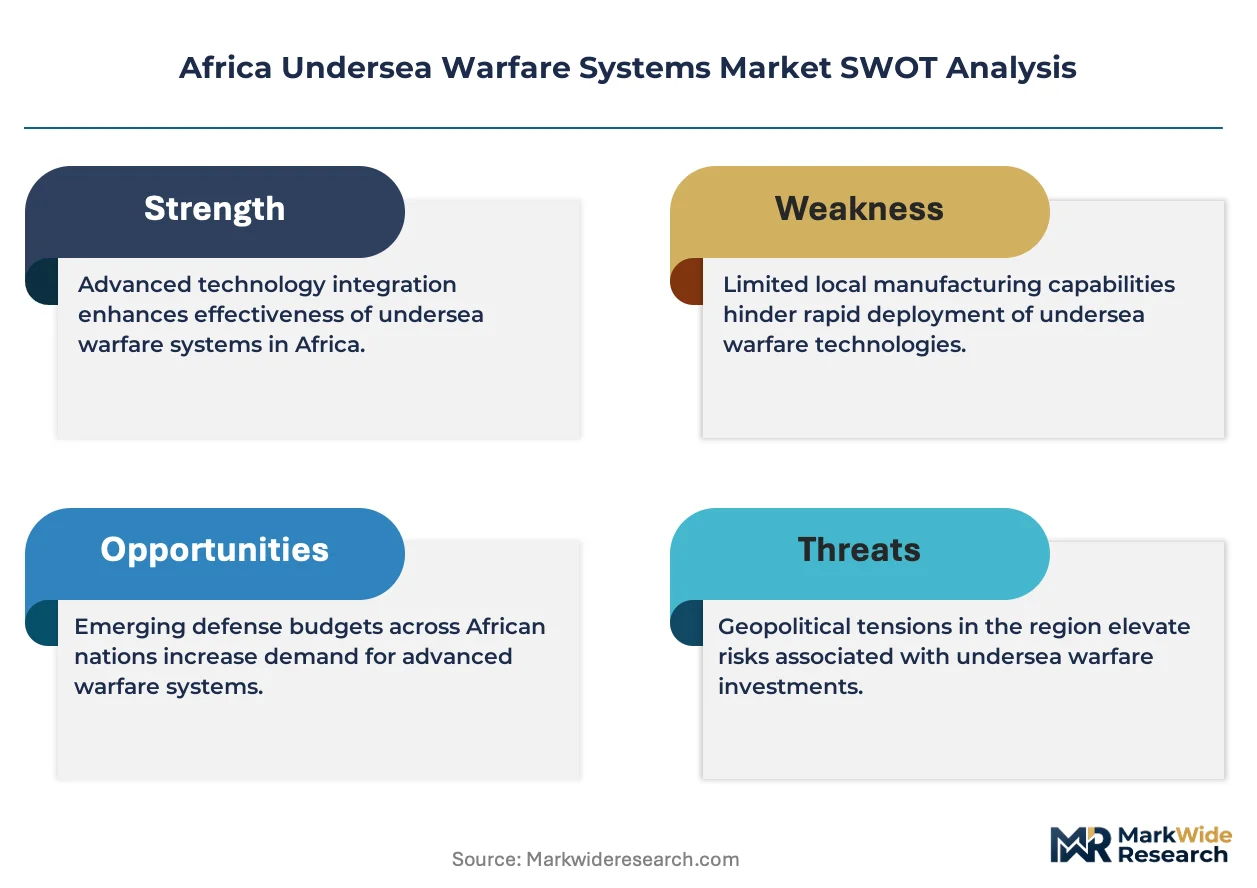
- Acoustic Sensor Supply Concentration:Specialized piezoelectric transducer manufacturing concentrates among European and North American defense contractors. African navies face extended lead times for critical subsystem replacement.
- Foreign Exchange Volatility:Naira and Rand depreciation against dollar-denominated platform contracts creates procurement execution risk. Nigerian defense budgets experience particular stress from currency mismatch.
- Technical Limitation:Littoral water acoustic complexity degrades active sonar performance in shallow African coastal zones. Operators require dual-mode passive-active architectures that compound system integration complexity.
Strategic Opportunities
- Moroccan Naval Modernization:Royal Moroccan Navy submarine capability gaps present white space for integrated combat system providers. Atlantic coastline surveillance requirements outpace current platform availability.
- Autonomous-Underwater-Vehicle Convergence:Artificial intelligence-enabled target classification merges with extended-range battery propulsion. This technology pairing enables reduced-crew mine countermeasure operations previously requiring manned platforms.
- East African Maritime Security Initiative:Kenya and Tanzania coastal patrol agencies seek interoperable undersea detection networks. Regional framework coordination creates multi-country contract aggregation potential.
Industry Challenges
- Acoustic Engineer Scarcity:Signal processing specialization for undersea warfare applications lacks training pipeline capacity across African defense industrial bases. South Africa's technical universities produce insufficient graduates for platform maintenance demands.
- Legacy System Integration:Existing hull-mounted sonar installations from Soviet-era procurement require interface bridging with modern digital combat management systems. Retrofit engineering consumes disproportionate program resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Undersea Warfare Systems Market |
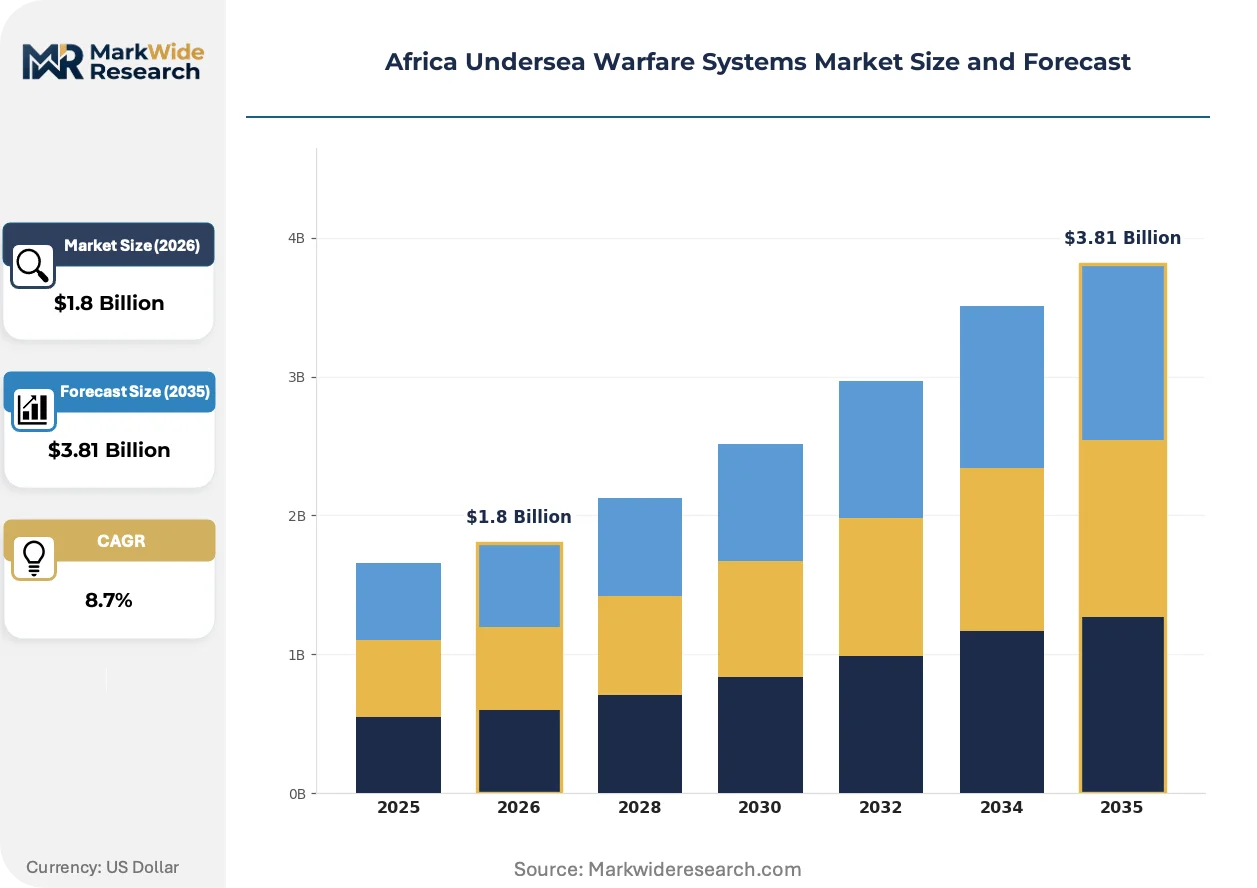
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submarines, Sonar Systems, Torpedoes, Surveillance Systems Application: Naval Operations, Intelligence Gathering, Maritime Security, Anti-Submarine Warfare Technology: Electro-Optical Systems, Acoustic Sensors, Autonomous Underwater Vehicles, Signal Processing End User: Defense Forces, Coast Guard, Private Security Firms, Research Institutions |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, General Dynamics, Thales Group, BAE Systems, Raytheon Technologies, Naval Group, Saab AB, L3Harris Technologies, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Undersea Warfare Systems Market Trends and Innovations
Digital signal processing architectures are displacing analog beamforming in African naval procurement specifications. This transition compresses platform upgrade timelines while elevating software-defined system requirements for foreign suppliers.
Synthetic aperture sonar is displacing conventional side-scan systems for seabed mapping and mine detection missions. South African Navy mine countermeasure units prioritize adoption given improved resolution at extended ranges. This displacement forces incumbent suppliers to requalify platforms under revised technical standards or exit the segment.
The African Union's maritime security framework establishes common operational standards for undersea surveillance data sharing. Member state navies must align platform interoperability specifications to qualify for collective security funding. Egyptian and Algerian procurement authorities now embed AU certification requirements into tender documentation, filtering vendor participation.
Long-term leasing arrangements for acoustic sensor platforms are displacing traditional capital purchase models among cash-constrained African maritime agencies. Gulf of Guinea coast guard units increasingly favor availability-based contracts with embedded maintenance provisions. Nigerian procurement patterns demonstrate this behavioral shift most visibly, with five-year operational service agreements supplanting outright platform acquisition in recent awards.
Africa Undersea Warfare Systems Market Segmentation
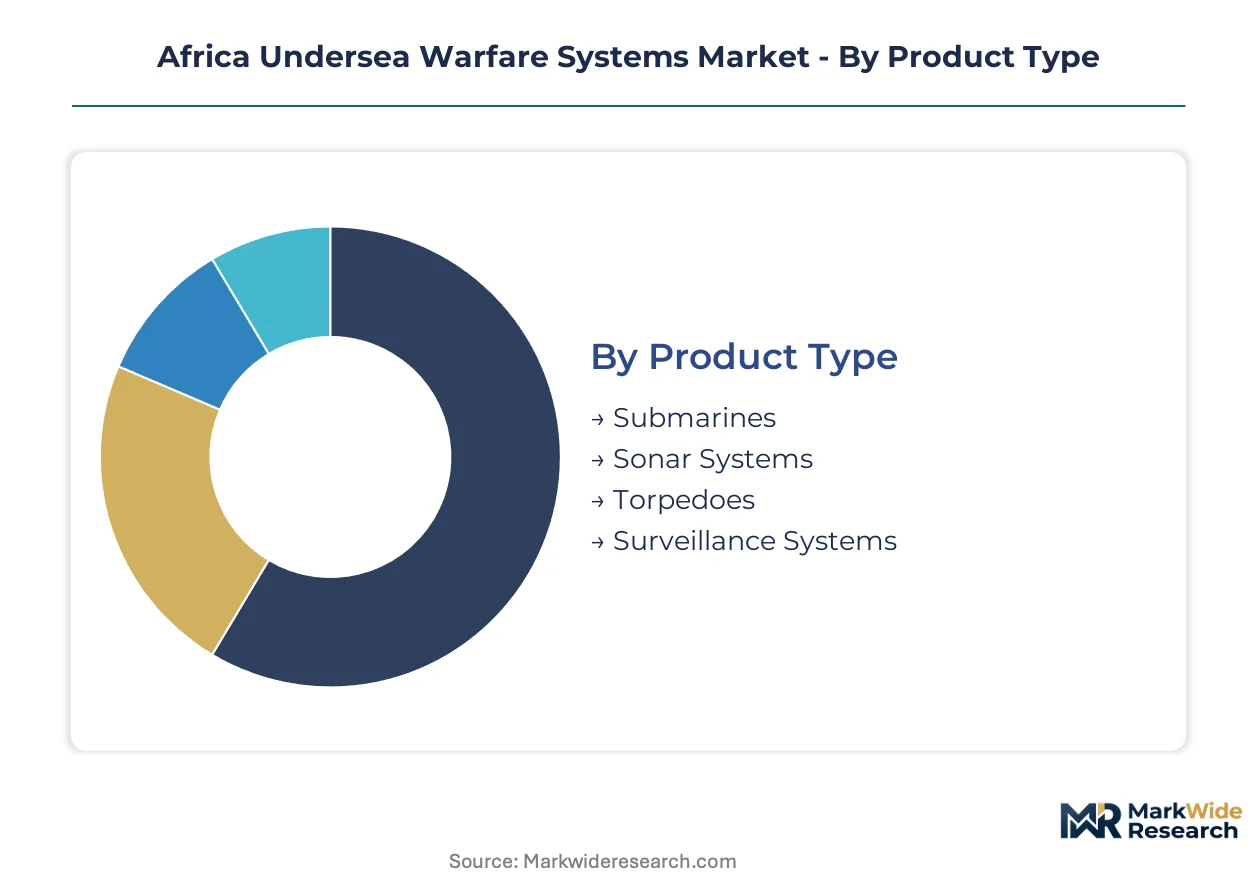
Segmentation of the Africa Undersea Warfare Systems Market reveals how procurement budgets fragment across platform types and operational requirements. Understanding these divisions clarifies where substitution pressures and technology transitions concentrate competitive risk.
Product Type:
Sonar systems face the strongest substitution pressure as synthetic aperture and digital beamforming architectures displace legacy analog installations across African naval procurement cycles.
- Sonar Systems:Active and passive acoustic detection platforms incorporating hull-mounted, towed, and dipping array variants. South African Navy exclusive economic zone mandates concentrate demand for continuous seabed monitoring capabilities that integrate with combat management architectures.
- Submarines:Diesel-electric attack submarines and coastal defense platforms with integrated undersea warfare suites. Egypt's fleet expansion program drives synchronized procurement of combat systems and acoustic countermeasures for littoral and blue-water operations.
- Torpedoes:Wire-guided and autonomous homing underwater weapons for submarine and surface vessel launch platforms. Nigerian naval procurement authority prioritizes lightweight variants for coastal defense against asymmetric threats.
- Surveillance Systems:Integrated seabed monitoring networks combining fixed sensors and mobile platforms. Moroccan Atlantic coastline requirements outpace current platform availability, creating white space for system providers.
Sonar systems anchor the volume base while autonomous underwater vehicles gain share at the steepest rate across African maritime procurement budgets.
Application:
Cost tier differentiation separates capital-intensive naval operations from deployable maritime security solutions that African coast guard agencies favor under constrained fiscal conditions.
- Naval Operations:Fleet-level anti-submarine warfare and area denial missions requiring integrated platform suites. South Africa's defense modernization framework channels substantial capital toward continuous patrol capabilities across its 1.5 million square kilometer maritime zone.
- Maritime Security:Corridor surveillance and piracy response operations along the Gulf of Guinea and Horn of Africa. Nigeria's procurement patterns demonstrate visible behavioral shift toward five-year operational service agreements supplanting outright platform acquisition.
- Intelligence Gathering:Covert submarine tracking and acoustic signature collection missions. Specialized funding flows from defense forces prioritizing hostile fleet monitoring in contested littoral zones.
- Anti-Submarine Warfare:Coordinated detection, tracking, and neutralization of hostile submarine threats. Algerian and Egyptian procurement authorities embed African Union certification requirements into tender documentation for interoperability compliance.
Maritime security applications absorb disproportionate capital allocation among cash-constrained agencies, whereas naval operations command the largest absolute contract values.
Technology:
Supply concentration in piezoelectric transducer manufacturing elevates procurement risk for acoustic sensor-dependent segments while electro-optical alternatives attract diversification interest.
- Acoustic Sensors:Piezoelectric transducer arrays and signal conditioning electronics for underwater detection. Extended lead times from European and North American contractors constrain African navy platform availability and subsystem replacement cycles.
- Autonomous Underwater Vehicles:Extended-range battery propulsion platforms with artificial intelligence-enabled target classification. Kenya and Tanzania coastal patrol agencies seek interoperable networks enabling reduced-crew mine countermeasure operations.
- Signal Processing:Digital beamforming and acoustic analysis software for sensor data interpretation. South African technical universities produce insufficient graduates for platform maintenance demands, creating capability scarcity.
- Electro-Optical Systems:Laser-based detection and optical imaging for littoral zone surveillance. Shallow water acoustic complexity degrades active sonar performance, elevating alternative sensor interest for coastal operations.
Acoustic sensors dominate current procurement specifications while autonomous underwater vehicles expand most quickly as navies seek reduced-crew reconnaissance capabilities.
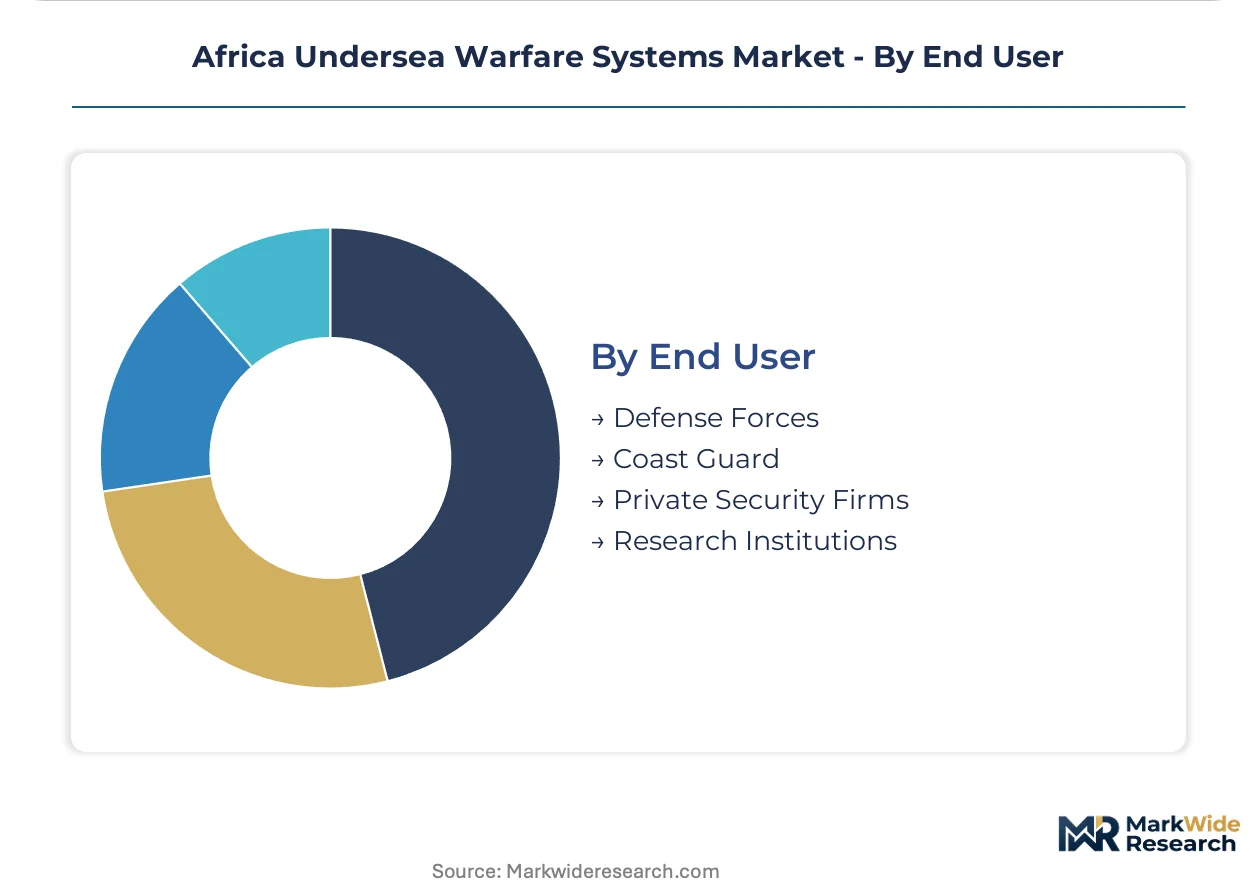
End User:
Customer type fragmentation splits demand between sovereign defense forces with technology transfer requirements and coast guard units pursuing operational leasing arrangements.
- Defense Forces:National navies with submarine fleets and blue-water operational mandates. Egypt's military procurement authority mandates localized production offsets that reshape vendor selection toward co-development frameworks.
- Coast Guard:Maritime law enforcement agencies with corridor surveillance and interdiction responsibilities. Gulf of Guinea units increasingly favor availability-based contracts with embedded maintenance provisions over capital purchase models.
- Private Security Firms:Commercial maritime protection providers serving shipping corridor contracts. Regulatory frameworks across African littoral states constrain armed platform deployment, limiting addressable market scope.
- Research Institutions:Academic and government laboratories conducting seabed mapping and acoustic propagation studies. South Africa's Armaments Corporation shapes regional demand through localized offset requirements for scientific equipment procurement.
Defense forces anchor contract value concentration while coast guard agencies drive volume expansion through distributed platform deployment across African maritime zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Authority's maritime corridor management and South Africa's Cape of Good Hope shipping lanes anchor Africa's strategic position in undersea warfare system deployment across both Atlantic and Indian Ocean littorals.
South Africa
Armaments Corporation procurement mandates drive continuous seabed monitoring requirements across the 1.5 million square kilometer exclusive economic zone. The country's defense modernization framework channels capital toward Simon's Town naval base upgrades for submarine fleet support. Cape Town's defense industrial cluster concentrates acoustic sensor integration capabilities for regional platform maintenance.
Egypt
Military procurement authority submarine fleet expansion creates synchronized demand for integrated combat systems and acoustic countermeasures. Technology transfer stipulations mandate localized production offsets that reshape vendor selection toward co-development frameworks. Alexandria's naval shipyard complex anchors North African submarine platform assembly and combat system integration activities.
Nigeria
Naval procurement authority channels defense budgets toward autonomous underwater vehicles for Gulf of Guinea corridor surveillance against piracy threats. Maritime security applications absorb disproportionate capital allocation under constrained fiscal conditions. Lagos maritime industrial zone hosts platform maintenance facilities for regional coast guard unit deployments.
Morocco
Royal Moroccan Navy submarine capability gaps present white space for integrated combat system providers addressing Atlantic coastline surveillance shortfalls. National defense procurement frameworks prioritize maritime domain awareness investments. Casablanca's port infrastructure supports undersea detection network deployment logistics for extended littoral coverage.
Algeria
Defense procurement authorities embed African Union maritime security certification requirements into tender documentation for interoperability compliance. Anti-submarine warfare coordination with regional navies drives platform specification alignment. Oran naval base complex concentrates submarine detection system operational testing and crew training programs.
Africa Undersea Warfare Systems Market Competitive Landscape
Listed defense conglomerates compete with private specialists across acoustic sensor and platform integration segments. Market structure consolidates around tier-one system integrators with submarine platform expertise and tier-two component specialists addressing retrofit opportunities. Three archetypes dominate: full-spectrum naval architects, acoustic sensor pure-plays, and autonomous platform developers. Competitive moves concentrate on technology licensing arrangements and localized production partnerships satisfying African offset requirements.
Within the full-spectrum integrator tier, Lockheed Martin Corporation and Thales Group exemplify archetypes competing through signal processing integration and acoustic sensor portfolios respectively. Naval Group occupies a position representing submarine platform specialization tailored to regional fleet requirements. These three anchors illustrate how vendor selection criteria shift toward partners offering co-development frameworks under Egyptian and South African technology transfer mandates.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| General Dynamics |
| Thales Group |
| BAE Systems |
| Raytheon Technologies |
| Naval Group |
| Saab AB |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term operational service agreements with embedded maintenance provisions lock in supply access for African coast guard units while compressing price visibility for platform vendors navigating currency volatility across Naira and Rand contracts. These availability-based contracts concentrate procurement leverage with defense ministries that can aggregate multi-year commitments, forcing suppliers to absorb foreign exchange risk in exchange offtake security.
Pricing Analysis
Three-tier pricing structure across integrated combat system, standalone sensor, and leased platform levels anchors contract negotiations between African navies and foreign suppliers. Price differentiation hinges on technology transfer depth and localized assembly mandates from Egypt's military procurement authority. Cost compression in standalone sensor tiers is intensifying because South African Armaments Corporation procurement mandates prioritize domestic offset fulfillment over brand premium. Coast guard agencies demonstrate highest price sensitivity due to constrained fiscal conditions, while defense forces with submarine fleet mandates exhibit lowest sensitivity given operational imperatives.
Supply Chain Analysis
Extended lead times for piezoelectric transducer arrays stretch inventory cycles across European and North American defense contractors serving African naval customers. Manufacturing concentration in France, Germany, and the United States draws from specialized ceramic substrate and rare-earth magnet inputs. Single-source vulnerability pervades hull-mounted sonar subsystem sourcing where qualified vendors number below five globally. Distribution runs through Alexandria, Simon's Town, and Casablanca naval shipyard complexes for final integration and crew training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in autonomous underwater vehicle deployment where Nigerian maritime security mandates and Kenyan coastal patrol requirements create specialized niches outside integrated combat system dominance. Coast guard leasing arrangements and technology transfer stipulations collectively reshape vendor selection criteria toward partners with localized production capacity.
For Market Incumbents: Fortify position through backward integration into piezoelectric transducer manufacturing to mitigate supply concentration risk from European specialist vendors. Expand capacity addition in South Africa's Cape Town defense industrial cluster to satisfy Armaments Corporation localization mandates. Signal processing software certification investment represents critical defensive lever against emerging AI-enabled target classification specialists. For New Entrants and Emerging Players: Differentiate on extended-range battery propulsion architectures tailored for Gulf of Guinea corridor surveillance missions. Moroccan Atlantic coastline submarine capability gaps present most penetrable white space for integrated combat system challengers. East African Maritime Security Initiative coordination creates multi-country contract aggregation potential for interoperable undersea detection networks. Pursue availability-based contract structures with embedded maintenance provisions as primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors acoustic sensor pure-plays with AI-enabled target classification capabilities over legacy analog beamformers. Long-term viability across the projection horizon rests on positioning against Egyptian and South African technology transfer mandates that reshape vendor economics. Acquisition target archetype encompasses autonomous underwater vehicle developers with extended-range battery intellectual property. Watch for African Union maritime security certification requirement expansion as inflection indicator for interoperability-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Partnership | Egypt's military procurement authority mandates localized production offsets reshaping vendor selection criteria toward co-development frameworks. |
| Autonomous Platform Development | AI-enabled target classification merges with extended-range battery propulsion enabling reduced-crew mine countermeasure operations. |
| Regional Certification Alignment | African Union maritime security framework establishes common operational standards filtering vendor participation through interoperability compliance. |
| Acoustic Engineer Training Pipeline | South African technical university partnerships address signal processing specialization scarcity constraining platform maintenance capacity. |
| Legacy System Retrofit Integration | Soviet-era hull-mounted sonar installations require interface bridging with modern digital combat management systems consuming program resources. |
Research Methodology
A standing panel of naval procurement officers, acoustic systems engineers, defense ministry budget directors, and coast guard operations chiefs provided ongoing calibration across primary interview cycles. Secondary validation drew from African Union maritime security framework documentation, national defense white papers, customs import records for acoustic sensor platforms, and SEC filings of listed defense conglomerates. Bottom-up platform deployment counts across South Africa, Egypt, Nigeria, Morocco, and Algeria triangulated against top-down defense budget allocation estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, application, technology, and end user, with additional granularity on technology transfer depth and leasing versus purchase contract structures. CAGRs were derived from fitted growth curves anchored to documented procurement timelines and fleet modernization announcements. Forecast inputs incorporated exclusive economic zone protection mandate legislative pressures and synthetic aperture sonar displacement patterns for seabed mapping missions.
Decision-makers should treat outputs as directional under stable currency conversion assumptions and continued African Union framework implementation; material deviation in foreign exchange volatility or maritime security funding allocation would warrant model refresh. Specific risk factors include Naira and Rand depreciation against dollar-denominated contracts, acoustic sensor supply concentration disruptions, and littoral water acoustic complexity degrading active sonar performance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Military Frigate Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Marine Radar Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Europe Naval Vessels Market