
 Bow and Stern Thrusters Market | 2026-2036
Bow and Stern Thrusters Market Size, Share, and Industry Trends Forecast 2026-2036
Bow and Stern Thrusters Market Analysis
IMO Tier III compliance-grade propulsion is bifurcating the bow and stern thrusters landscape into emissions-certified and legacy equipment tiers. Wärtsilä Corporation leverages its exhaust after-treatment integration to dominate commercial harbor-assist contracts. Schottel GmbH anchors the European inland waterway segment with modular electric pod designs. ZF Friedrichshafen AG competes through hydrostatic drive expertise transferred from its industrial gearbox portfolio.
Bow and stern thrusters are lateral thrust devices mounted in tunnels at a vessel's extremities, typically driven by electric motors, hydraulic pumps, or diesel engines through fixed-pitch or controllable-pitch propellers generating bollard pull ratings from 10 kN to over 500 kN for precision maneuvering in confined waters. Electric thrusters now lead the product mix as harbor authorities in Rotterdam, Singapore, and Long Beach impose shore-power readiness mandates that penalize idling auxiliary diesels. The above 100 HP power rating segment captures the strongest margin pool from offshore platform supply vessels requiring dynamic positioning redundancy. Remote and automatic control systems are displacing manual configurations as single-bridge integrated bridge systems become standard on vessels over 500 gross tons.
Federal Maritime Commission guidelines in the United States, EU MRV monitoring requirements, and IMO's Carbon Intensity Indicator collectively reshape thruster procurement toward energy-efficient designs with verifiable fuel-consumption footprints. Classification societies including DNV and Lloyd's Register now embed thruster efficiency metrics within vessel Energy Efficiency Design Index scores, directly linking hardware selection to charter market access. Stakeholders must weigh electric architecture conversion costs against port tariff incentives and carbon credit eligibility in their fleet renewal decisions.
Market Dynamics
The bow and stern thrusters market is undergoing a fundamental restructuring as harbor authorities in Rotterdam, Singapore, and Long Beach impose shore-power readiness mandates that penalize idling auxiliary diesels, forcing fleet operators to accelerate electric architecture conversions ahead of regulatory deadlines.
Growth Catalysts
- IMO Tier III emissions rules:Tightening diesel engine restrictions in Mediterranean waters are compelling mega-yacht and superyacht builders to expand electric thruster installations across newbuild programs.
- Norway's fjord cruise sector:Operators now mandate zero-emission maneuvering in UNESCO-protected waterways, concentrating demand for battery-electric azimuth systems in Scandinavian yards.
- Dynamic positioning redundancy:Offshore platform supply vessels require redundant thruster configurations for station-keeping in harsh environments, driving specification of above 100 HP power rating segments.
Market Restraints
- Copper and rare-earth magnet costs:Electric motor manufacturing faces input volatility from concentrated Chinese processing capacity for neodymium and dysprosium.
- Classification society backlog:DNV and Lloyd's Register thruster efficiency verification protocols create extended certification timelines for novel electric pod designs.
- Hydraulic system legacy lock-in:Existing harbor-assist fleets carry sunk capital in hydrostatic drive infrastructure that resists full electrification retrofit economics.
Strategic Opportunities
- EU Green Deal port infrastructure funding:Shore-power installation subsidies in Hamburg, Antwerp, and Barcelona create captive demand for shore-compatible electric thruster specifications.
- Autonomous vessel integration:Convergence of integrated bridge systems with AI-powered collision avoidance is opening specification windows for thrusters with millisecond-response digital controls.
- After-sales service unbundling:Remote condition monitoring via satellite telemetry enables predictive maintenance contracts separate from hardware procurement, recurring revenue for thruster OEMs.
Industry Challenges
- Marine electrical engineering talent scarcity:High-voltage power management expertise for megawatt-class electric propulsion systems outstrips vocational training pipeline output in European shipbuilding regions.
- Retrofit integration complexity:Tunnel modifications for electric thruster installations in existing hulls require naval architecture recertification that extends dry-dock schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bow and Stern Thrusters Market |
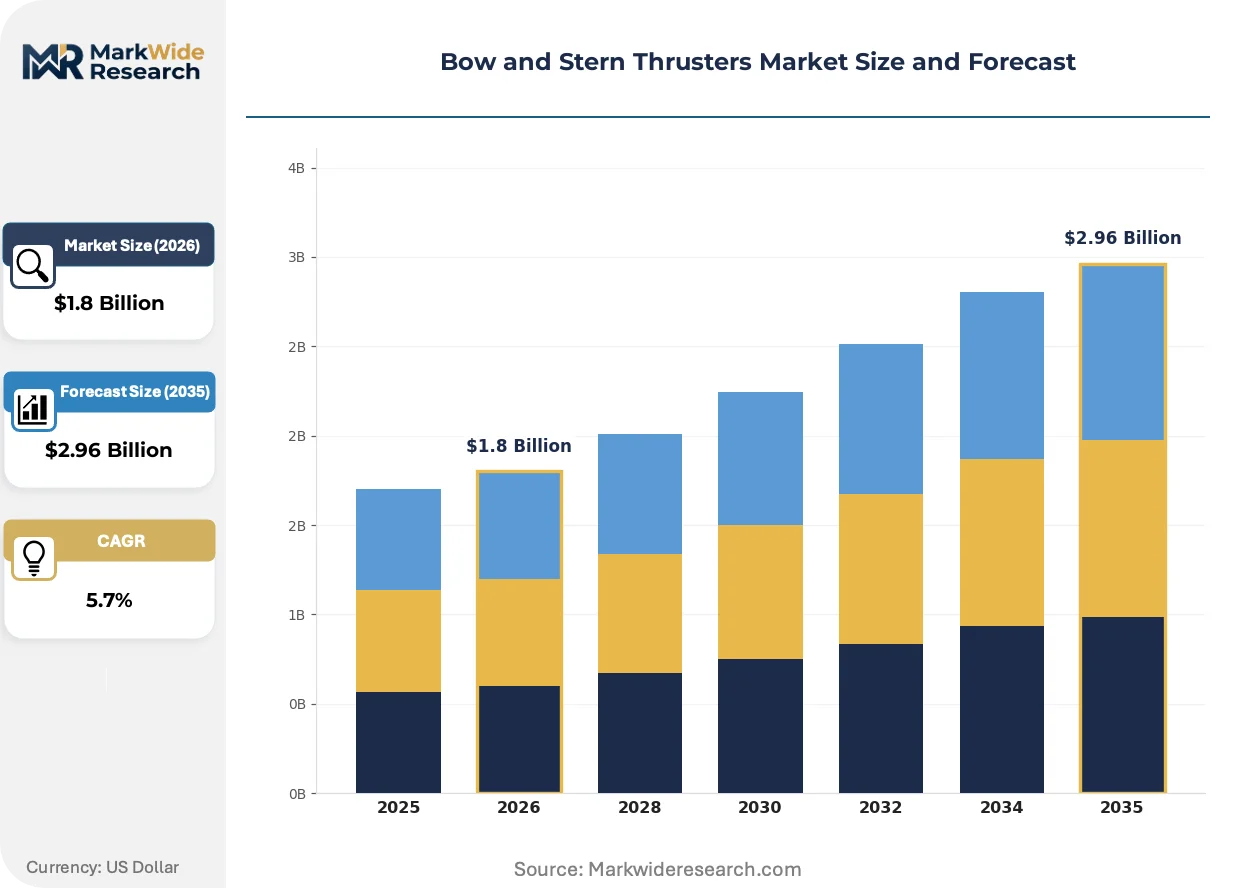
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Thruster Type: Electric Thrusters, Hydraulic Thrusters, Mechanical Thrusters, Hybrid Thrusters Application: Commercial Vessels, Recreational Boats, Offshore Platforms, Fishing Vessels Power Rating: Up to 20 HP, 21 to 50 HP, 51 to 100 HP, Above 100 HP Control System: Manual Control, Remote Control, Automatic Control, Semi-Automatic Control |
| Companies Covered | Wärtsilä Corporation, Dutch Thruster Group BV, VETUS, CMC Marine Srl, Sleipner Motor AS, ZF Friedrichshafen AG, Lewmar Limited, Side-Power, Schottel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bow and Stern Thrusters Market Emerging Trajectories
Electrification of maneuvering propulsion is fragmenting traditional supply relationships as vessel operators bypass conventional diesel-hydraulic channels and source integrated electric pod systems directly from specialized manufacturers.
Permanent magnet synchronous motor technology is fragmenting the competitive landscape for bow thruster drive systems. Offshore wind turbine installation vessels are specifying these motors for their superior torque density and partial-load efficiency. The technology is fragmenting market share between established gearbox suppliers and emerging direct-drive specialists who control magnet supply chains.
EU MRV monitoring requirements and IMO's Carbon Intensity Indicator are compressing thruster procurement cycles toward verifiable fuel-consumption footprints. Vessel operators must now document auxiliary power consumption during port maneuvers. The regulations are forcing charterers to specify Energy Efficiency Design Index-compliant hardware or face exclusion from premium cargo contracts.
Single-bridge integrated bridge systems are consolidating thruster control authority under unified command architectures. Vessel operators over 500 gross tons are displacing standalone joystick consoles with software-defined maneuvering stations. This consolidation is most visible in Norwegian and Dutch offshore supply fleets where DP-2 certification mandates redundant control pathways.
Bow and Stern Thrusters Market Segmentation
Thruster procurement patterns diverge sharply across vessel categories and operational profiles. Port authorities, offshore contractors, and yacht builders each impose distinct technical specifications that reshape supplier priorities and certification requirements.
Thruster Type:
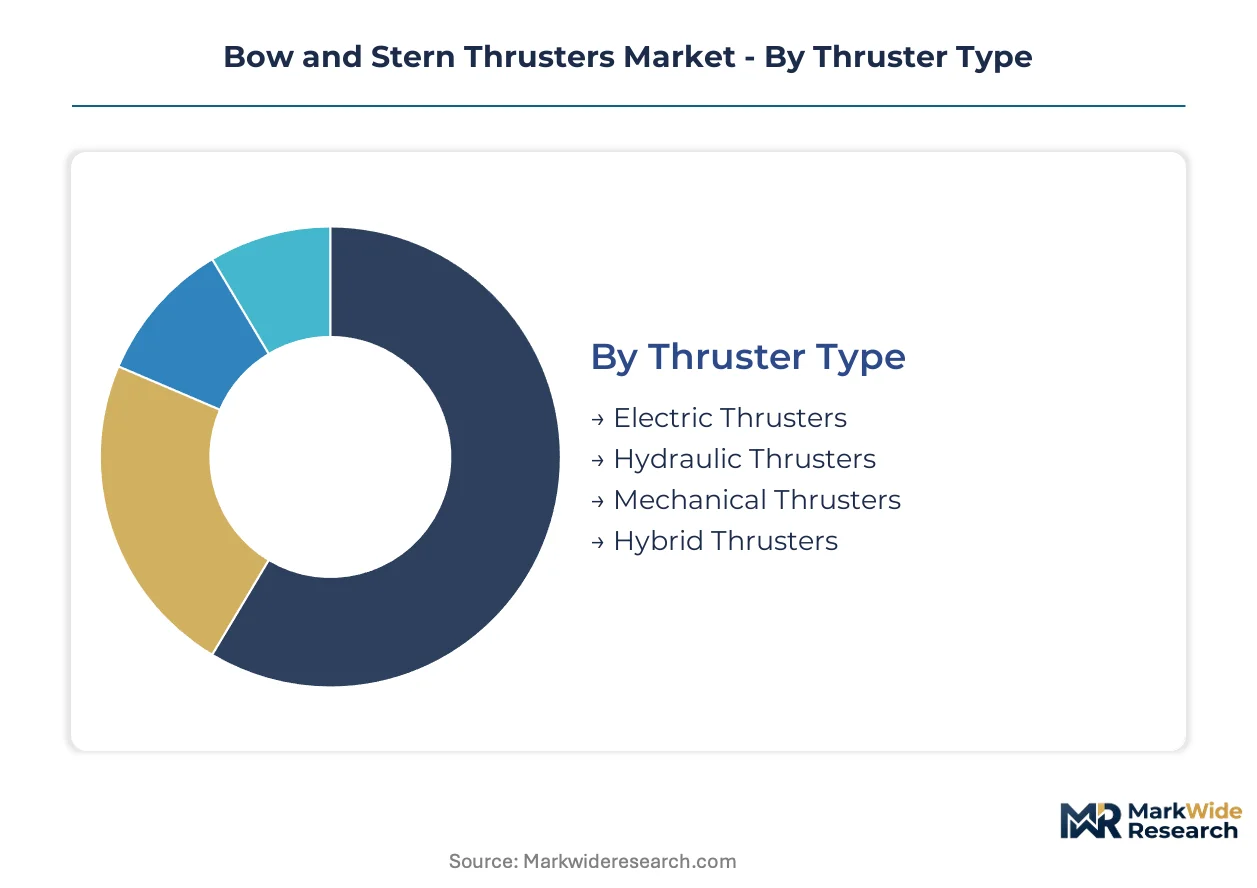
Electric thruster demand concentrates in Scandinavian yards and Mediterranean superyacht builders, while hydraulic systems retain dominance in retrofit-heavy harbor-assist fleets across Rotterdam and Long Beach.
- Electric Thrusters:Permanent magnet synchronous motors deliver superior torque density for offshore wind turbine installation vessels. Norwegian fjord cruise operators mandate zero-emission configurations for UNESCO-protected waterways, locking in battery-electric azimuth specifications.
- Hydraulic Thrusters:Hydrostatic drive systems leverage existing infrastructure in commercial towing fleets. Sunk capital in pump and piping networks across North American harbor-assist operators resists full electrification economics despite shore-power penalties.
- Mechanical Thrusters:Direct diesel-mechanical drives persist in cost-sensitive fishing vessel segments where auxiliary engine redundancy is limited.
- Hybrid Thrusters:Dual-mode architectures allow switching between electric shore-power and onboard generation, appealing to EU-flagged vessels navigating Green Deal port infrastructure requirements.
Electric thrusters hold the largest share; momentum sits with hybrid configurations bridging shore-power mandates and operational flexibility needs.
Application:
Offshore platform supply vessels command premium pricing through dynamic positioning redundancy requirements, while recreational boatbuilders prioritize compact tunnel dimensions over bollard pull ratings.
- Commercial Vessels:Container ships and bulk carriers specify thrusters for single-bridge integrated bridge systems compliance above 500 gross tons. IMO Carbon Intensity Indicator documentation requirements now embed auxiliary power consumption during port maneuvers into charter contract terms.
- Offshore Platforms:Station-keeping in harsh environments demands above 100 HP redundant configurations. North Sea operators require DNV thruster efficiency verification for DP-2 certification, extending procurement timelines.
- Recreational Boats:Mega-yacht builders in Italian and Spanish yards expand electric installations as IMO Tier III emissions rules tighten diesel restrictions in Mediterranean waters.
- Fishing Vessels:Smaller tunnel diameters and lower duty cycles favor mechanical or compact hydraulic drives in price-sensitive fleet renewal programs.
Commercial vessels dominate volume; offshore platforms command the steepest expansion trajectory as wind farm installation fleets multiply.
Power Rating:
High-horsepower segments concentrate manufacturing expertise in German and Norwegian suppliers, while sub-50 HP categories fragment across Asian component assemblers.
- Above 100 HP:Dynamic positioning redundancy for platform supply vessels and anchor-handling tugs drives specification of megawatt-class electric pods. Classification society efficiency protocols from Lloyd's Register directly link hardware selection to charter market access.
- 51 to 100 HP:Mid-range ratings serve coastal cargo vessels and medium-format offshore support ships requiring moderate bollard pull without full DP certification.
- 21 to 50 HP:Compact electric thrusters dominate harbor tug and pilot boat retrofits where tunnel modifications face naval architecture recertification delays.
- Up to 20 HP:Pleasure craft and small fishing vessels specify these ratings, with cost pressure favoring standardized motor platforms over custom engineering.
Above 100 HP captures the strongest margin pool; 21 to 50 HP is gaining share fastest through harbor fleet electrification mandates.
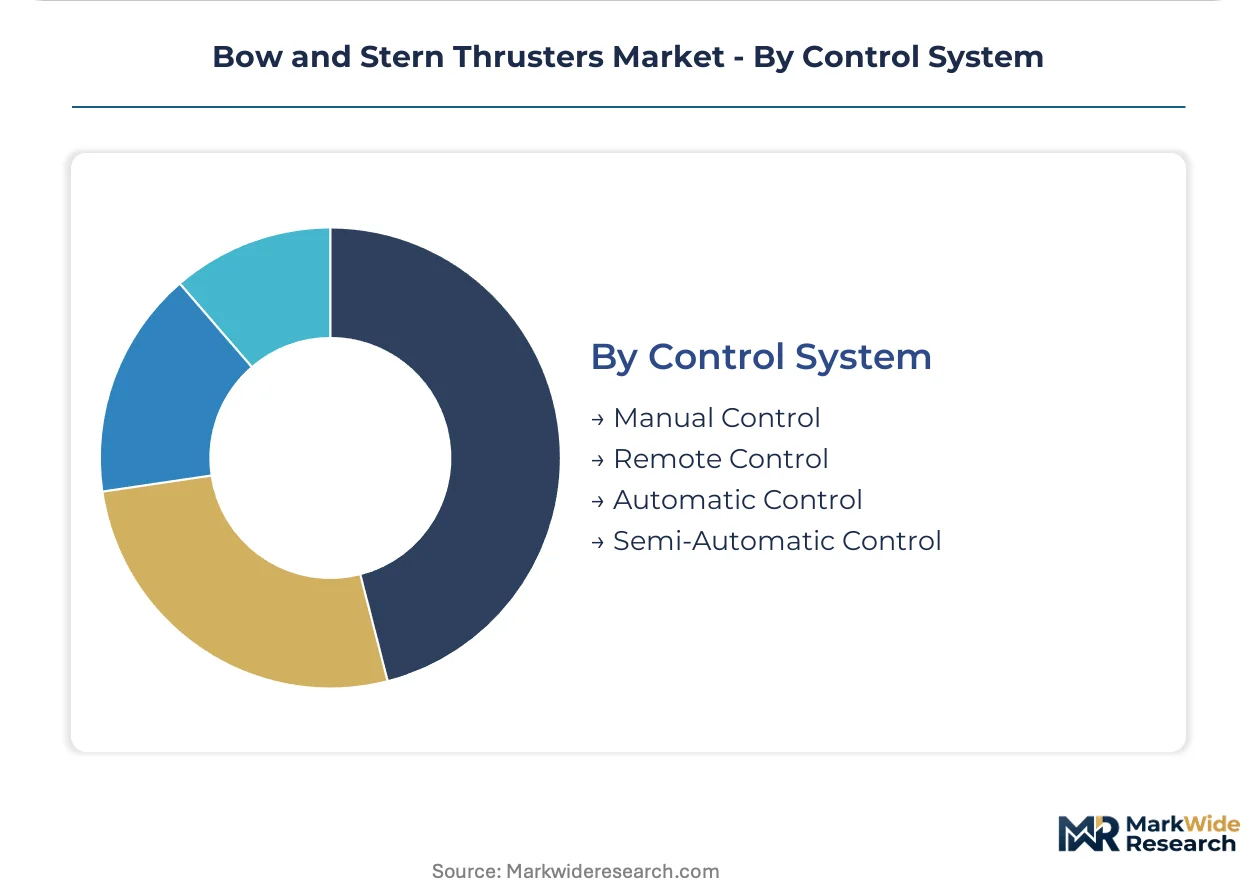
Control System:
Automation intensity correlates with vessel gross tonnage and flag state requirements, creating tiered specification patterns across European and Asian shipyards.
- Automatic Control:AI-powered collision avoidance convergence enables millisecond-response digital thruster integration. Norwegian and Dutch offshore supply fleets mandate redundant control pathways for DP-2 certification under unified command architectures.
- Remote Control:Satellite telemetry enables predictive maintenance contracts separate from hardware procurement, opening recurring revenue streams for thruster OEMs serving distributed fleets.
- Semi-Automatic Control:Hybrid joystick and software-defined stations bridge legacy manual systems and full automation in mid-life vessel upgrades.
- Manual Control:Standalone joystick consoles persist in vessels under 500 gross tons and non-DP fishing operations where capital constraints limit bridge system investment.
Automatic control leads adoption curves; remote control is climbing the fastest as condition monitoring unbundles from initial hardware sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German thruster manufacturers export battery-electric azimuth systems to Norwegian fjord cruise operators facing UNESCO waterway mandates. Mediterranean mega-yacht builders in Italy and Spain source electric tunnel thrusters from Scandinavian suppliers to meet IMO Tier III compliance deadlines.
Norway
Fjord cruise operators mandate zero-emission maneuvering in UNESCO-protected waterways, driving battery-electric azimuth specifications. The country's maritime regulator enforces strict environmental standards for coastal navigation. Bergen and Stavanger shipyards concentrate demand for Scandinavian-built electric pod systems.
Germany
Offshore wind turbine installation vessels specify permanent magnet synchronous motors for superior torque density. The Federal Maritime and Hydrographic Agency implements stringent efficiency verification protocols. Hamburg and Bremen industrial clusters anchor megawatt-class electric thruster manufacturing expertise.
Italy
Mega-yacht builders in Viareggio and Ancona expand electric thruster installations as IMO Tier III emissions rules tighten diesel restrictions. The country's environmental ministry coordinates with EU MRV monitoring requirements. Adriatic and Ligurian shipyards drive Mediterranean superyacht electrification trends.
United States
Harbor authorities in Long Beach and Los Angeles impose shore-power readiness mandates that penalize idling auxiliary diesels. The Federal Maritime Commission guidelines reshape thruster procurement toward energy-efficient designs. Pacific Northwest and Gulf Coast shipyards retrofit commercial fleets with electric architecture conversions.
Singapore
The Maritime and Port Authority mandates shore-power compatibility for harbor-assist vessels calling at the world's busiest transshipment hub. Container terminals impose tariff penalties on diesel-idling auxiliary systems. Jurong ship repair clusters concentrate electrification retrofit demand for regional tanker and bulk carrier fleets.
Bow and Stern Thrusters Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base shows moderate consolidation around exhaust after-treatment integrators, modular electric pod designers, and hydrostatic drive specialists. Three archetypes dominate: diversified industrial conglomerates with marine divisions, dedicated thruster engineering houses, and gearbox manufacturers leveraging industrial portfolios. Competitive moves concentrate on strategic partnerships for shore-power integration and geographic expansion into Scandinavian electrification clusters.
Within the diversified industrial tier, Wärtsilä Corporation and ZF Friedrichshafen AG occupy positions leveraging exhaust after-treatment and hydrostatic drive expertise respectively. Schottel GmbH exemplifies the dedicated engineering house archetype with modular electric pod designs. These three entities anchor the competitive structure across commercial harbor-assist, European inland waterway, and offshore platform supply segments.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| Dutch Thruster Group BV |
| VETUS |
| CMC Marine Srl |
| Sleipner Motor AS |
| ZF Friedrichshafen AG |
| Lewmar Limited |
| Side-Power |
| Schottel GmbH |
| Others |
Supply Flow & Price Mechanics
Permanent magnet synchronous motor substitution for conventional induction drives simultaneously concentrates supply geography in Chinese rare-earth processing corridors and compresses pricing economics for European gearbox manufacturers. This material transition rewards thruster OEMs with captive magnet sourcing while penalizing legacy hydrostatic drive suppliers facing stranded engineering investments.
Pricing Analysis
Current-generation electric pod systems command substantial premiums over prior-generation hydraulic tunnel thrusters, while next-generation solid-state motor controllers promise further cost compression. Three-tier pricing structure across IMO Tier III-certified premium, standard commercial-grade, and economy mechanical tiers reflects certification burden and after-sales bundling intensity. Pricing pressure stems from Rotterdam and Singapore port authorities accelerating shore-power penalty schedules. Fishing vessel operators exhibit highest price sensitivity; offshore wind installation contractors show lowest due to DP-2 redundancy mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate thruster final assembly, though strategic stockpiling of neodymium and dysprosium concentrates persists among German and Norwegian manufacturers exposed to Chinese export quota volatility. Supply geography centers on China for rare-earth magnet processing, Germany for megawatt-class power electronics, and Norway for battery-electric azimuth system integration. Copper winding supply draws from Chilean concentrate and Indonesian smelting capacity. Single-source vulnerability in Chinese rare-earth separation capacity threatens production continuity. Distribution runs through shipyard direct procurement with classification society certification gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts unbundled from hardware sales are expanding faster than thruster unit shipments, converting capital expenditure relationships into recurring service revenue streams.
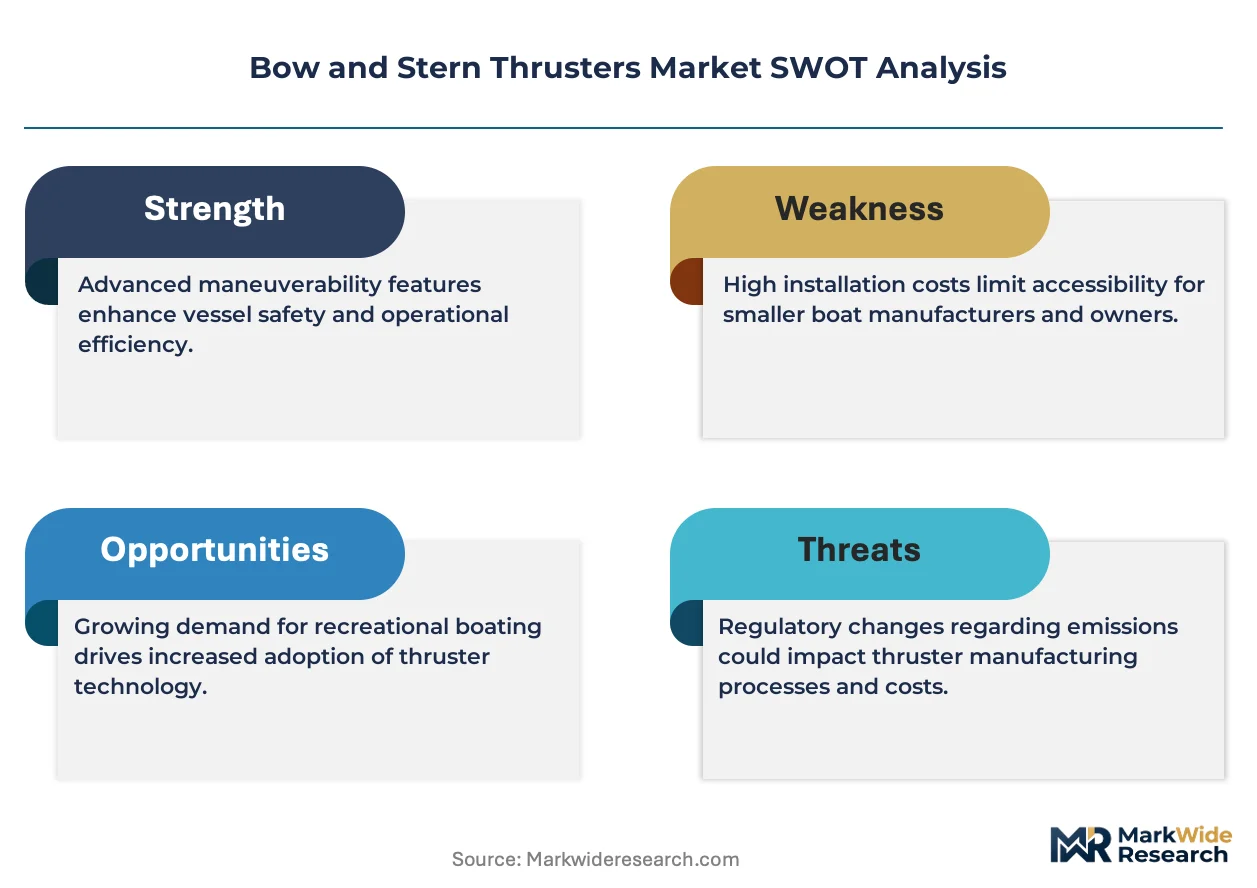
For Market Incumbents: Compound defensive positioning through backward integration into permanent magnet supply chains and certification investment in DNV efficiency protocols. Chinese direct-drive specialists threaten established gearbox suppliers with magnet supply chain control. Capacity addition in Scandinavian yards serving Norwegian fjord cruise operators locks in zero-emission specification windows. For New Entrants and Emerging Players: Differentiate on millisecond-response digital control architectures for autonomous vessel integration. Harbor-assist fleet electrification retrofits in Long Beach and Singapore represent the most penetrable white space. Coastal cargo vessels in the 51-100 HP segment offer secondary entry points with moderate certification barriers. Direct shipyard partnerships bypass incumbent distributor channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electric pod specialists holding Norwegian fjord cruise order backlogs. Long-term viability hinges on shore-power infrastructure deployment pace across EU Green Deal ports. Acquisition targets include condition-monitoring software platforms with satellite telemetry integration. Watch for IMO Carbon Intensity Indicator enforcement stringency as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Supply Chain Integration | Captive dysprosium sourcing insulates Wärtsilä and Schottel from Chinese export quota shocks. |
| Predictive Maintenance Platform Launch | Satellite telemetry contracts convert hardware sales into recurring revenue at VETUS and CMC Marine. |
| DP-2 Certification Fast-Track Program | Lloyd's Register partnership accelerates Norwegian offshore supply vessel order capture. |
| Shore-Power Compatibility Retrofit | Hybrid thruster architectures secure Singapore Maritime and Port Authority compliance mandates. |
| Autonomous Control Integration | AI-powered collision avoidance opens specification windows for millisecond-response digital thrusters. |
Methodological Framework
Operator-level perspectives from fleet managers at harbor-assist operators, procurement directors at offshore vessel contractors, and superyacht build captains anchored the qualitative base. Secondary validation drew from Lloyd's Register thruster efficiency protocols, DNV vessel certification databases, IMO Marine Environment Protection Committee submissions, and EU MRV monitoring disclosure filings. Bottom-up unit shipment estimates triangulated against top-down addressable vessel fleet analysis.
Sensitivity analysis tested forecast outputs against rare-earth price volatility scenarios and shore-power mandate acceleration timelines across the projection horizon. Segmentation dimensions modeled include thruster type, power rating tier, control system architecture, and vessel application category. CAGRs derived from historical installation rates projected against regulatory deadline clustering. Industry-specific inputs incorporated fjord cruise operator zero-emission commitments and offshore wind turbine installation vessel order backlogs.
The analysis sits within stated boundaries; outcomes outside sustained Chinese rare-earth export quota stability and EU Green Deal port infrastructure funding continuity would require recalibration. Forecasts reflect assumptions on classification society certification timeline normalization and shipyard electrification retrofit capacity expansion. Revision becomes warranted when IMO Carbon Intensity Indicator enforcement stringency crosses thresholds triggering accelerated fleet replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Combat Management System Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Marine Radar Market
Naval Warfare
Naval Radar Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Sea Skimmer Missile Market