
 Coastal Patrol Military Vessels Market | 2026-2036
Coastal Patrol Military Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Coastal Patrol Military Vessels Market Outlook
The capability gap between capital-intensive naval shipyards and smaller patrol craft specialists is collapsing as modular construction techniques democratize hull production. BAE Systems leverages its integrated combat systems expertise to dominate the offshore patrol vessel segment. Damen Shipyards Group anchors its position through standardized hull families that reduce lead times for coast guard operators. Fr. Fassmer GmbH & Co. KG specializes in aluminum-hulled fast attack craft optimized for shallow-water endurance.
Coastal patrol military vessels are steel or aluminum-hulled surface combatants typically displacing 50 to 3,000 tonnes, designed for sustained operations in littoral zones with integrated radar, electro-optical sensors, and remote weapon stations for maritime domain awareness. Their primary purpose centers on territorial water sovereignty enforcement, exclusive economic zone protection, and asymmetric threat interdiction near shorelines. Offshore patrol vessels command the largest value share due to their multi-mission flexibility and higher unit costs. Fast attack craft represent the fastest-expanding segment as navies prioritize rapid response against swarm threats in congested waterways. Hybrid propulsion systems are capturing margin attention as fuel efficiency mandates reshape lifecycle cost calculations for fleet operators.
The International Maritime Organization's MARPOL conventions constrain engine emissions for naval auxiliary vessels, while NATO STANAG standards govern interoperability requirements for allied coastal forces operating in joint theaters. National regulators including Lloyd's Register and Bureau Veritas enforce classification rules that dictate survivability standards, fire safety protocols, and structural integrity benchmarks for patrol hulls. Stakeholders must monitor how emerging autonomous navigation certifications from classification societies will reshape crewing requirements and platform design specifications.
Market Dynamics
Hybrid propulsion architectures are collapsing the traditional trade-off between endurance and sprint speed in littoral platforms, forcing shipyards to reconfigure supply chains around electric-diesel integration modules rather than conventional drivetrain assemblies.
Growth Catalysts
- Indonesian Naval Modernization:The Indonesian Navy's Minimum Essential Force program is accelerating orders for 80-meter offshore patrol vessels with helicopter decks. Shipyards in Surabaya are expanding drydock capacity to meet delivery timelines.
- MARPOL Annex VI Phase III:The International Maritime Organization's tightened nitrogen oxide limits for vessels operating in emission control areas are compelling coast guard fleets to spec hybrid-electric systems for harbor maneuvering.
- Swarm Threat Response Doctrine:Naval strategists in Southeast Asian commands are rewriting procurement specifications to prioritize 35-knot sprint speeds and stabilized remote weapon stations for asymmetric engagement scenarios.
Market Restraints
- Aluminum Hull Plate Volatility:Marine-grade 5083 aluminum sheet pricing fluctuates with LME spot markets, compressing margins for fast attack craft specialists who cannot pass through material cost swings in fixed-price government contracts.
- Combat System Integration Bottlenecks:A handful of European sensor houses control supply of qualified naval radar suites, creating single-source vulnerability for shipyards outside the NATO supplier network.
- Crew Endurance Regulations:The International Labour Organization's Maritime Labour Convention minimum crew rest standards are limiting the operational tempo that navies can extract from smaller patrol platforms without automation investment.
Strategic Opportunities
- Vietnamese Coast Guard Expansion:Hanoi is doubling its white-hull fleet through licensed production agreements with foreign designers, creating entry paths for modular hull technology licensors.
- Autonomous Navigation Certification:Classification societies in Norway and France are piloting approval frameworks for reduced-crewed patrol craft, opening design space for smaller accommodation blocks and extended range.
- US Coast Guard Offshore Patrol Cutter Program:The Deepwater recapitalization is generating demand for integrated bridge systems and over-the-horizon targeting suites that suppliers can adapt for allied fleets.
Industry Challenges
- Naval Architect Talent Scarcity:Shipyards in Southeast Asia cannot recruit sufficient hull designers familiar with high-speed planing craft hydrodynamics, forcing reliance on expatriate contractors.
- Combat System Cybersecurity Certification:NATO STANAG 4671 and equivalent national standards require extensive penetration testing for integrated mission systems, extending delivery schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coastal Patrol Military Vessels Market |
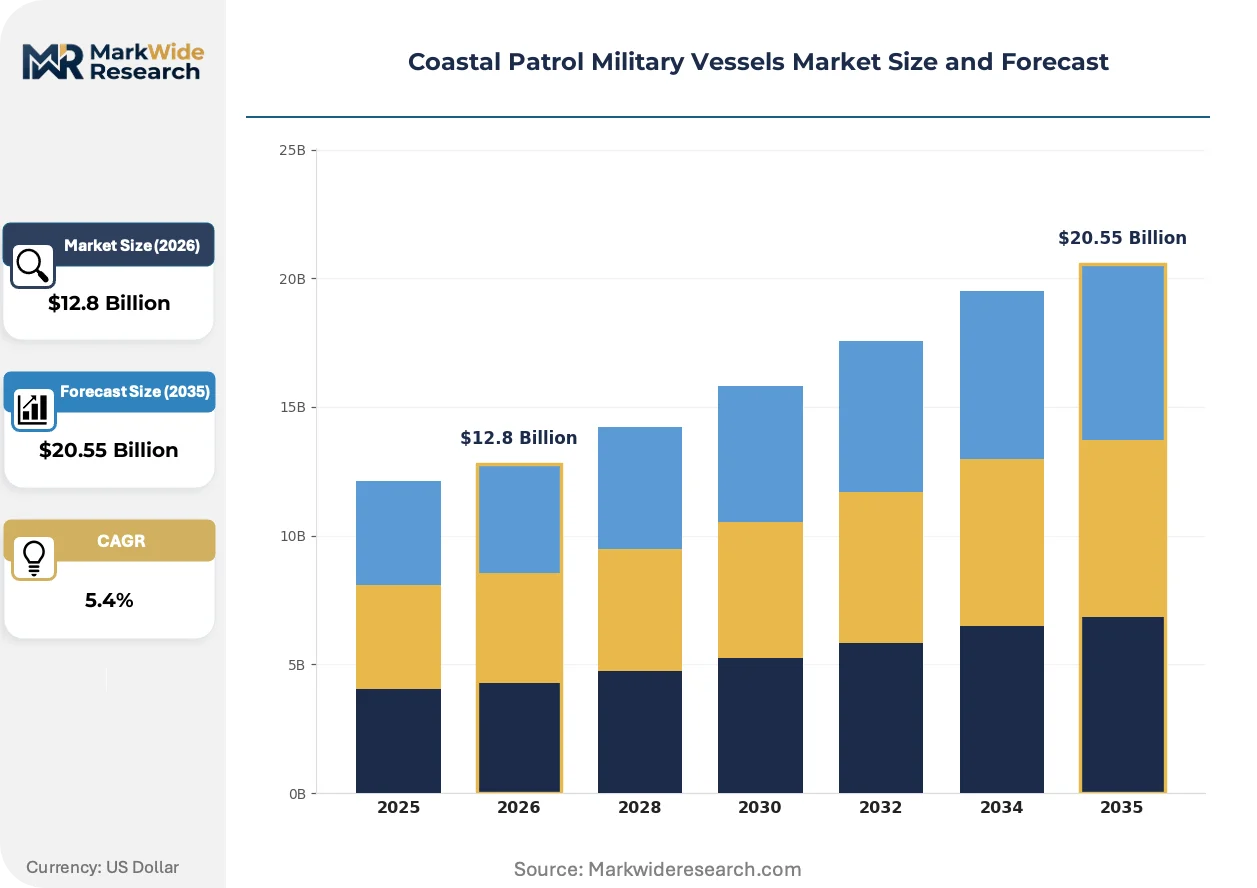
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Fast Attack Craft, Offshore Patrol Vessel, Coastal Defense Vessel, Surveillance Vessel Operating Environment: Shallow Waters, Open Ocean, Harbors, Estuaries Propulsion Type: Diesel, Gas Turbine, Hybrid, Electric Mission Profile: Surveillance, Search and Rescue, Anti-Piracy, Counter-Terrorism |
| Companies Covered | DSME Co., Ltd., Damen Shipyards Group, Fr. Fassmer GmbH & Co. KG, BAE Systems, Mitsubishi Heavy Industries, Grup Aresa, STX France, Huntington Ingalls Industries, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coastal Patrol Military Vessels Market Strategic Shifts
Electrification of propulsion and weapon systems is compressing machinery space requirements while expanding sensor payload capacity, enabling a generation of smaller hulls to carry capabilities previously reserved for frigate-class displacement.
Stabilized electro-optical/infrared sensor turrets are miniaturizing from 400-kilogram naval mounts to sub-100-kilogram packages suitable for 15-meter interceptor craft. Malaysian Maritime Enforcement Agency procurement officers are specifying these compact systems for their next fast patrol boat tranche. The size reduction is miniaturizing the minimum viable hull length for effective night surveillance, allowing shipyards to bid smaller, cheaper platforms for coast guard tenders.
The European Union's Green Deal maritime component is tightening carbon intensity metrics for vessels calling at EU ports, including naval auxiliaries on sovereign missions. Shipbuilders in the Netherlands and Germany are responding with methanol-ready engine rooms and battery-buffered hotel loads. Offshore patrol vessel programs in the Baltic and Mediterranean are now requiring shore power connectivity and exhaust after-treatment as standard.
Navies are unbundling through-life support from initial platform procurement, separating hull-and-machinery contracts from combat system sustainment. The Royal Australian Navy's patrol boat replacement program illustrates this bifurcation, with prime contractors delivering bare platforms while sensor integrators hold separate performance-based logistics agreements. This purchasing pattern is most pronounced in Anglo-Pacific fleets where budget transparency requirements separate capital and operating appropriations.
Coastal Patrol Military Vessels Market Segmentation
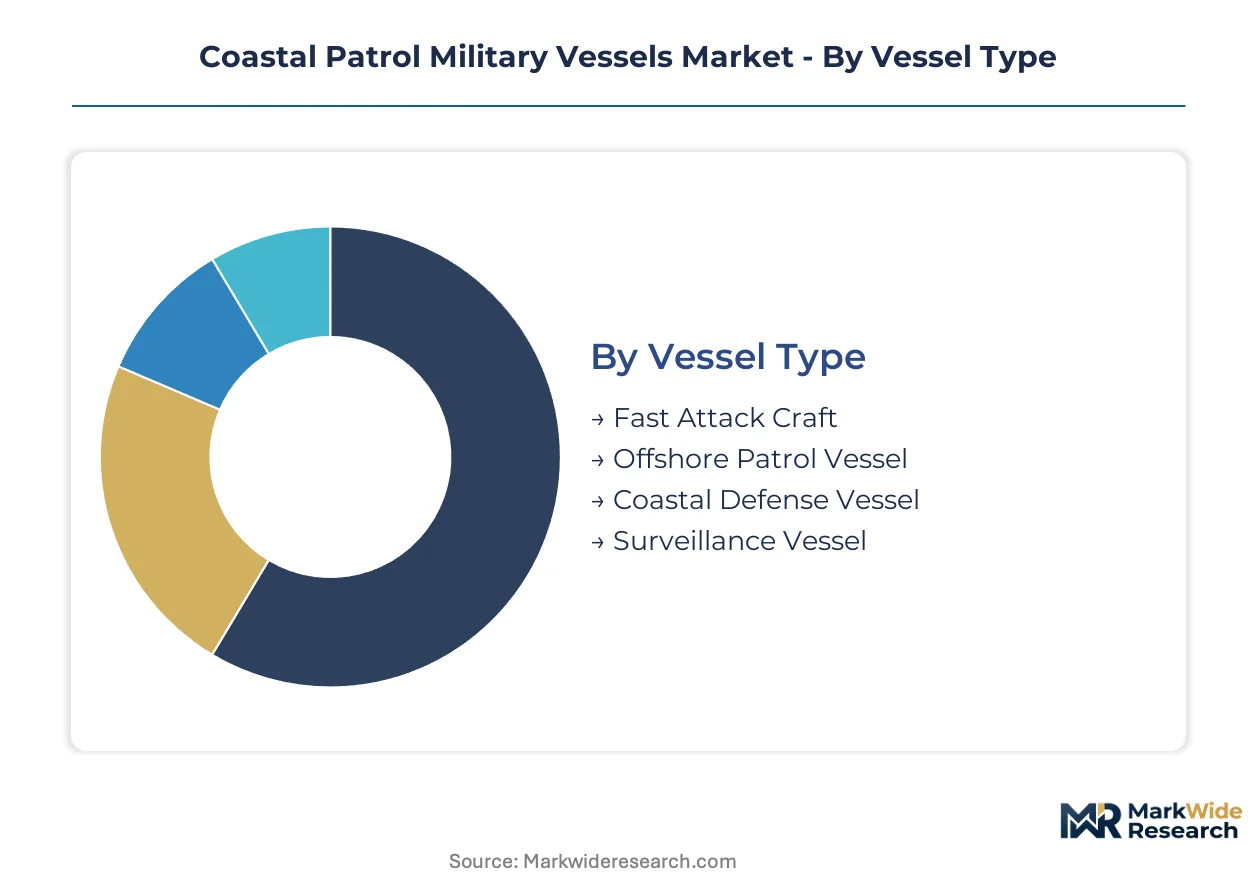
Coastal patrol military vessels serve radically different operational needs across littoral zones, harbor approaches, and offshore boundaries. Segmentation reveals how procurement budgets split between high-endurance platforms for exclusive economic zone patrol and sprint-capable craft for congested waterway interdiction.
Vessel Type:
Export orders concentrate in offshore patrol vessels for coast guard recapitalization, while domestic shipyards retain fast attack craft production for sovereign fleet renewal.
- Offshore Patrol Vessel:Steel-hulled platforms displace 1,000 to 3,000 tonnes with helicopter decks and over-the-horizon radar suites. Indonesian Navy procurement under the Minimum Essential Force program anchors regional demand for 80-meter variants with extended range.
- Fast Attack Craft:Aluminum-hulled interceptors achieve 35-knot sprint speeds for swarm threat response. Malaysian Maritime Enforcement Agency specifications prioritize stabilized remote weapon stations on compact 15-meter hulls for night surveillance in the Strait of Malacca.
- Coastal Defense Vessel:Fixed installations and mobile missile platforms protect harbor approaches and chokepoints.
- Surveillance Vessel:Minimally armed platforms maximize sensor payload and loiter time for maritime domain awareness.
Offshore patrol vessels command the established base. The steepest expansion runs through fast attack craft.
Operating Environment:
Platform design diverges sharply between shallow-draft requirements for archipelagic navies and seakeeping specifications for open ocean patrol.
- Shallow Waters:Draft constraints below 3 meters dominate procurement for Indonesia's 17,000 islands and Vietnam's Mekong Delta approaches. Hull forms prioritize planing surfaces over displacement efficiency.
- Open Ocean:Seakeeping in Sea State 5+ conditions requires deeper hulls and active stabilization. Philippine Coast Guard orders for South China Sea patrol specify this category exclusively.
- Harbors:Maneuverability and low wash characteristics predominate for port security applications.
- Estuaries:Corrosion-resistant coatings and debris-tolerant intakes address brackish water operations.
Shallow waters absorb the majority of hull orders. Open ocean specifications are gaining share fastest as exclusive economic zone enforcement extends beyond visual range.
Propulsion Type:
Cost tiers separate established diesel mechanical systems from emerging hybrid architectures that command premium pricing for fuel efficiency compliance.
- Hybrid:Combined diesel-electric and mechanical systems enable harbor maneuvering on battery power with sprint capability from direct diesel drive. MARPOL Annex VI Phase III nitrogen oxide limits in emission control areas are accelerating coast guard fleet specifications for this architecture.
- Diesel:Mechanical direct-drive systems remain standard for cost-constrained navies with simpler maintenance requirements and established supply chains.
- Gas Turbine:High-power density propulsion suits sprint-dominant mission profiles with limited endurance requirements.
- Electric:Pure battery and fuel-cell systems are emerging for harbor patrol and autonomous platform applications.
Diesel systems retain the installed base. Hybrid configurations are climbing the fastest as lifecycle cost calculations incorporate carbon intensity metrics.
Mission Profile:
Customer type splits between military navies prioritizing kinetic engagement and coast guard agencies focused on constabulary presence.
- Surveillance:Sensor-dense configurations with minimal armament maximize on-station time for maritime domain awareness. Vietnamese Coast Guard fleet expansion emphasizes this profile for gray-zone competition in disputed waters.
- Anti-Piracy:Boarding team facilities, small boat davits, and non-lethal deterrent systems address asymmetric threats in shipping lanes.
- Search and Rescue:Survivability features, medical facilities, and helicopter recovery systems dominate specifications.
- Counter-Terrorism:High-speed intercept capability and close-quarters weapon systems address vessel-borne improvised explosive device threats.
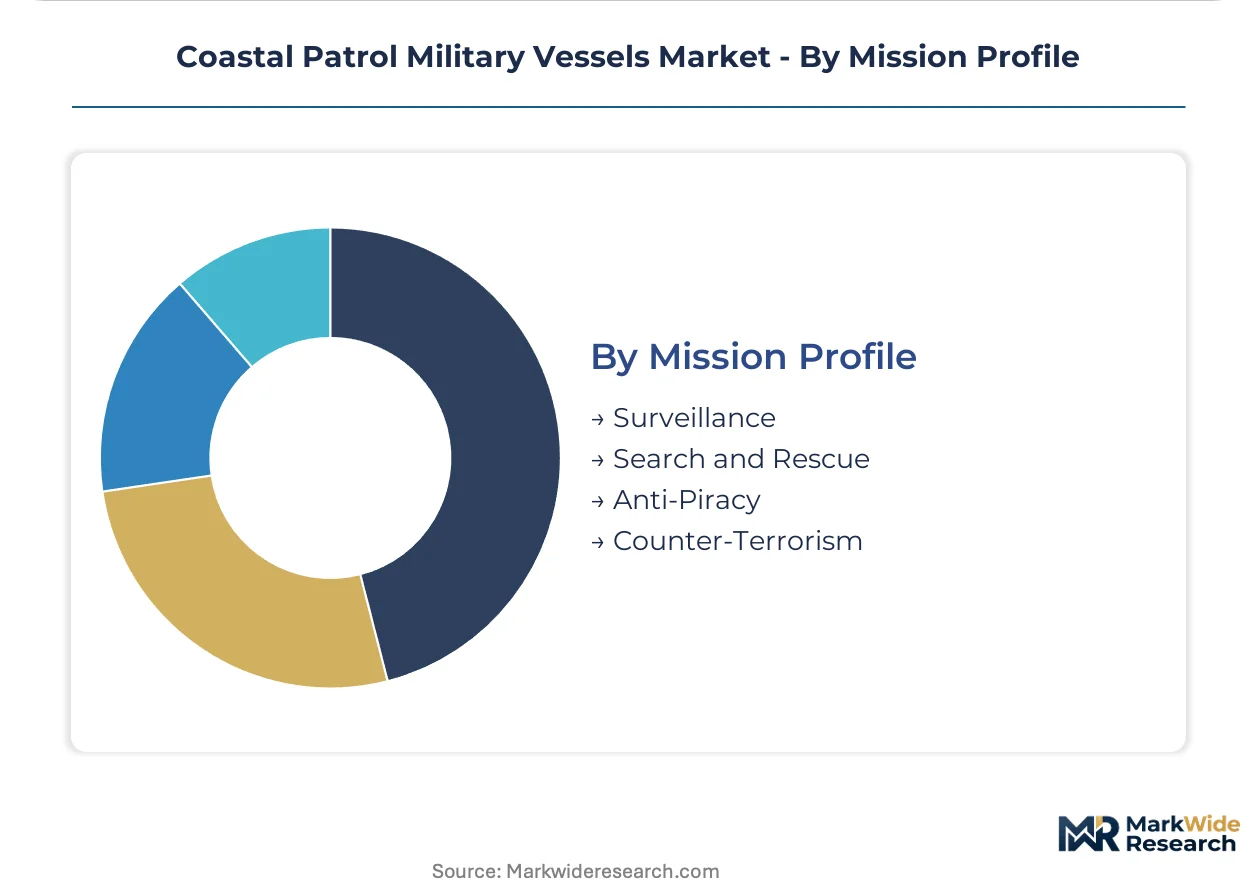
Surveillance missions anchor procurement volume. Anti-piracy specifications are expanding most quickly as shipping lane protection extends beyond traditional naval mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Archipelagic navies prioritize shallow-draft fast attack craft for inter-island mobility, while continental coast guards favor larger offshore patrol vessels for exclusive economic zone enforcement, creating divergent procurement patterns across littoral defense budgets.
Indonesia
The Indonesian Navy's Minimum Essential Force program drives orders for 80-meter offshore patrol vessels with helicopter decks. The country's national maritime regulator enforces classification standards through Lloyd's Register and Bureau Veritas rules for naval auxiliary construction. Shipyards in Surabaya are expanding drydock capacity to meet delivery timelines for coast guard fleet recapitalization.
Vietnam
Hanoi is doubling its white-hull fleet through licensed production agreements with foreign designers, creating entry paths for modular hull technology licensors. The Vietnam Register applies structural integrity benchmarks adapted from international classification society frameworks. Da Nang hosts emerging shipbuilding clusters where local fabricators are absorbing technology transfer protocols for aluminum-hulled interceptors.
Malaysia
The Malaysian Maritime Enforcement Agency specifies stabilized remote weapon stations on compact 15-meter hulls for night surveillance in the Strait of Malacca. National procurement regulations favor domestic content thresholds for naval platform assembly. Lumut maintains the principal naval shipyard complex where patrol craft construction integrates with regional maintenance networks.
Philippines
Philippine Coast Guard orders for South China Sea patrol specify open-ocean seakeeping in Sea State 5+ conditions exclusively. The Maritime Industry Authority coordinates with international classification societies on hull certification protocols. Subic Bay Freeport Zone retains shipyard infrastructure repurposed for coast guard vessel construction and foreign navy servicing contracts.
United States
The US Coast Guard Offshore Patrol Cutter program generates demand for integrated bridge systems and over-the-horizon targeting suites adaptable for allied fleets. The Coast Guard's acquisition directorate applies federal procurement regulations separating hull-and-machinery contracts from combat system sustainment. Ingalls Shipbuilding in Pascagoula and Eastern Shipbuilding in Panama City anchor domestic production capacity for deepwater recapitalization.
Coastal Patrol Military Vessels Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in coastal patrol vessel construction. European and Northeast Asian shipyards dominate offshore patrol vessel categories through combat systems integration expertise, while aluminum-hulled fast attack craft specialists compete on sprint speed and shallow-water maneuverability. Two strategic archetypes define competitive positioning: integrated prime contractors delivering platform-and-mission-system packages, and modular hull licensors enabling licensed production in emerging navies. Capacity expansion and technology licensing represent the dominant competitive moves as shipyards seek to capture Southeast Asian procurement cycles.
Among integrated defense contractors, BAE Systems exemplifies the platform-and-systems archetype through its offshore patrol vessel segment presence. Damen Shipyards Group occupies a position as a standardized hull family licensor with compressed delivery timelines for coast guard operators. Fr. Fassmer GmbH & Co. KG represents the aluminum-hulled specialist tier optimized for shallow-water endurance applications.
| Leading Market Players |
|---|
| DSME Co., Ltd. |
| Damen Shipyards Group |
| Fr. Fassmer GmbH & Co. KG |
| BAE Systems |
| Mitsubishi Heavy Industries |
| Grup Aresa |
| STX France |
| Huntington Ingalls Industries |
| General Dynamics Corporation |
| Others |
Value Chain & Pricing Dynamics
MARPOL Annex VI Phase III certification gates both supply qualification and price differentiation simultaneously, as shipyards without hybrid-electric integration capabilities cannot bid for coast guard contracts in emission control areas while those with certified architectures command lifecycle cost premiums. Government procurement officers weight fuel efficiency compliance heavily in total cost of ownership calculations, compressing margins for conventional diesel specialists and elevating pricing power for hybrid-ready builders.
Pricing Analysis
Long-term offtake contracts dominate naval procurement, with fixed-price platform deliveries spanning hull-and-machinery construction while combat system sustainment is unbundled into separate performance-based logistics agreements. Price differentiation rests on certification tier—NATO STANAG-qualified sensor integrators extract premiums over non-aligned suppliers—and on vertical integration depth, with in-house combat system houses capturing margin that modular hull licensors forfeit. Cost compression in fast attack craft segments is intensifying because aluminum hull plate volatility cannot be passed through in fixed-price government contracts, making Southeast Asian domestic yards the most price-sensitive buyers while European integrated primes show lowest sensitivity due to through-life service attach rates.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Southeast Asian shipbuilding clusters, with marine-grade 5083 aluminum sheet sourcing concentrated in China, South Korea, and Japan. Combat system integration draws from a handful of European sensor houses controlling qualified naval radar supply, creating single-source vulnerability for shipyards outside the NATO supplier network. Tariff exposure on steel and aluminum inputs presents structural risk as national content regulations tighten across Indonesian, Malaysian, and Vietnamese procurement frameworks. Distribution runs through government defense acquisition directorates with multi-year budget cycles, compressing working capital flexibility for smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based logistics agreements for combat system sustainment are expanding faster than hull construction revenue, creating service-attach opportunities that reshape competitive economics for platform providers.
For Market Incumbents: Compound platform-and-systems integration advantages by deepening backward integration into sensor payload production and expanding drydock capacity in Surabaya or Da Nang to capture Indonesian and Vietnamese naval modernization cycles. Threat of modular hull licensors enabling licensed production in emerging navies demands certification investment in autonomous navigation standards to maintain differentiation. For New Entrants and Emerging Players: Classification society fast-tracks for reduced-crewed patrol craft open entry paths for automation-focused specialists without legacy crew accommodation design heritage. White-space targets center on Vietnamese coast guard licensed production agreements and Malaysian Maritime Enforcement Agency compact fast patrol boat specifications. Go-to-market positioning as hybrid-electric integration module suppliers to established hull builders bypasses capital-intensive shipyard construction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aluminum-hulled fast attack craft specialists in Northern Europe facing margin compression from material cost volatility. Long-term viability over the next decade hinges on through-life service contract attach rates rather than platform delivery volume. Signal to watch is Indonesian Navy contract awards shifting from domestic shipyard preference to technology licensing frameworks that enable foreign equity participation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Integration | MARPOL Annex VI Phase III compliance enables bidding for emission control area coast guard contracts. |
| Modular Hull Technology Licensing | Technology transfer protocols accelerate Vietnamese and Indonesian fleet expansion without greenfield shipyard investment. |
| Autonomous Navigation Certification | Classification society approval frameworks from Norway and France open design space for reduced crew requirements. |
| Combat System Cybersecurity Investment | NATO STANAG 4671 penetration testing capabilities compress delivery schedules by 8-14 months for qualified integrators. |
| Performance-Based Logistics Unbundling | Separating hull delivery from sensor sustainment matches Anglo-Pacific budget transparency requirements for capital and operating appropriations. |
Study Parameters
A spread of perspectives from naval architects at Southeast Asian shipyards, procurement officers in Indonesian and Vietnamese defense ministries, combat system integrators in European sensor houses, and classification society surveyors converged on the working assumptions underlying this analysis. Primary interviews with coast guard fleet managers and drydock operations directors combined with secondary validation from Lloyd's Register and Bureau Veritas classification records, customs trade data on marine-grade aluminum shipments, and government defense budget appropriations documents. Bottom-up vessel order aggregation and top-down maritime security expenditure analysis provided triangulation on market sizing.
Segmentation dimensions modeled span vessel type, operating environment, propulsion architecture, and mission profile across the projection horizon. Analytical framework approach incorporates exclusive economic zone patrol range requirements, territorial dispute intensity indices, and MARPOL regulatory phase-in schedules. CAGRs were derived from procurement pipeline visibility and fleet recapitalization cycle timing. Industry-specific forecast inputs include Indonesian Minimum Essential Force program delivery timelines and US Coast Guard Deepwater recapitalization budget authority trajectories.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continuing territorial tension assumptions; material deviation in emission control area designations or defense budget prioritization would warrant model refresh. Forecasts reflect these base conditions with acknowledged sensitivity to aluminum price volatility and combat system integration bottleneck resolution. Practitioners should keep alternative scenarios live as autonomous navigation certification pathways and swarm threat response doctrine specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Marine Radar Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Military Marine Vessel Engines Market